
 Tube Ice Machine Market | 2026-2036
Tube Ice Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Ice Machine Market Insights
Buyer concentration among large-scale fishing cooperatives and integrated seafood processors is restructuring procurement patterns across the tube ice machine landscape. Scotsman Ice Systems leverages its North American service network to anchor commercial vessel contracts. Focusun Refrigeration competes on evaporative-cooled engineering for tropical dockside installations. Manitowoc sustains beverage-sector relationships through modular configurations that reduce downtime during harvest seasons.
A tube ice machine produces cylindrical ice with hollow cores by circulating water over a vertical or horizontal evaporator surface, then harvesting the frozen tubes through a hot-gas defrost or water-spray release cycle. The resulting ice offers high surface-area-to-mass ratio, rapid cooling transfer, and minimal bridging during bulk storage, which serves seafood preservation, concrete temperature control, and chemical processing applications. Automatic tube ice machines dominate installed base economics where labor costs exceed capital recovery thresholds, while portable configurations represent the fastest-growing segment for remote construction and event catering deployments. Water-cooled technology occupies the premium tier in coastal zones with abundant seawater access, whereas air-cooled systems lead inland markets constrained by water treatment regulations.
The US Department of Energy enforces minimum efficiency standards on commercial refrigeration equipment, compressing operational cost differentials between legacy and next-generation compressors. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerant quotas, redirecting R&D expenditure toward CO2 transcritical and ammonia systems. ISO 22000 food safety management protocols shape export-market access for machines deployed in direct-contact seafood handling. Stakeholders must monitor refrigerant transition timelines and regional energy subsidy programs to align capital deployment with tightening lifecycle cost requirements.
Market Dynamics
Energy-efficiency mandates from the US Department of Energy are compressing payback periods for water-cooled tube ice systems, while Southeast Asian seafood processors accelerate fleet mechanization to displace manual block harvesting operations.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon phase-down quotas redirect capital expenditure toward CO2 transcritical and ammonia refrigeration architectures, expanding addressable market for low-GWP machine configurations.
- Dockside infrastructure modernization:Vietnam's Mekong Delta fishing ports require continuous ice supply for post-harvest preservation, creating installed-base expansion for automated tube ice systems.
- Evaporative-cooled engineering:Tropical coastal installations favor water-cooled technology where seawater access reduces compressor load, improving operational economics in high-ambient environments.
Market Restraints
- Refrigerant transition costs:R&D expenditure redirection toward CO2 and ammonia systems strains mid-tier manufacturer balance sheets before scale economies materialize.
- Water treatment compliance:Inland markets face air-cooled system mandates where discharge regulations constrain evaporative-cooled deployments, limiting technology choice.
- Labor cost thresholds:Automatic tube ice machine economics require capital recovery periods that exceed acceptable horizons in markets where manual harvesting labor remains inexpensive.
Strategic Opportunities
- Remote construction vertical:Portable tube ice configurations address event catering and infrastructure projects lacking grid-connected cold chain, representing segment expansion outside traditional seafood processing.
- ISO 22000 certification pathways:Food safety management protocols for direct-contact seafood handling create export-market access barriers that certified machine architectures can monetize.
- Concrete temperature control:Chemical processing and ready-mix applications exploit high surface-area-to-mass ratio ice properties for batch cooling, diversifying end-use beyond preservation.
Industry Challenges
- Ammonia refrigeration expertise:CO2 transcritical and ammonia system deployment requires specialized technician training that outpaces vocational program output in emerging markets.
- Legacy hot-gas defrost integration:Water-spray release cycle retrofits face compatibility constraints with existing vertical evaporator installations, complicating upgrade paths.
- Regional energy subsidy alignment:Capital deployment timing must synchronize with fragmented municipal incentive programs that lack standardization across coastal provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Ice Machine Market |
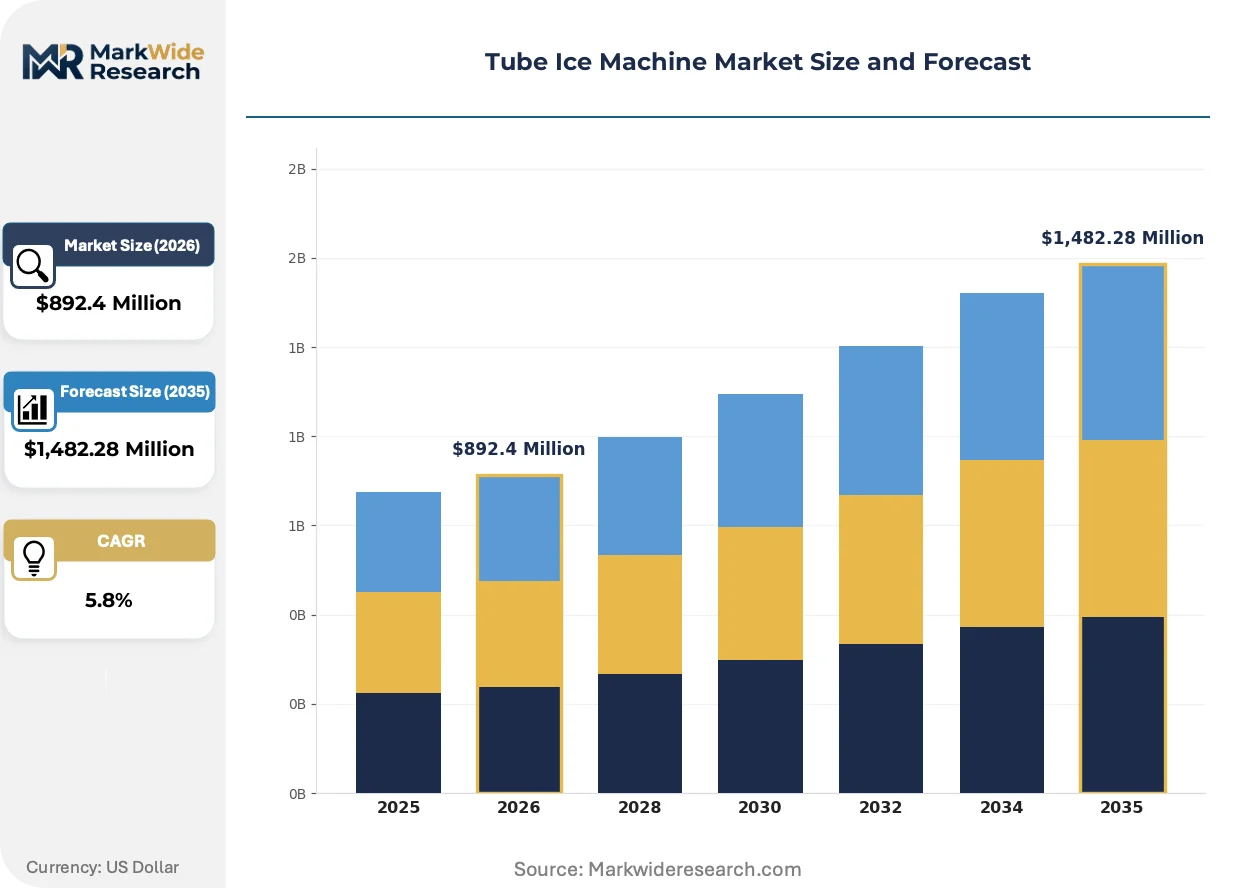
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Tube Ice Machine, Semi-Automatic Tube Ice Machine, Modular Tube Ice Machine, Portable Tube Ice Machine Technology: Air-Cooled, Water-Cooled, Evaporative-Cooled, Hybrid-Cooled Application: Seafood Preservation, Beverage Cooling, Concrete Cooling, Chemical Processing End User: Fishing Firms, Beverage Manufacturers, Construction Companies, Pharmaceutical Producers |
| Companies Covered | Scotsman Ice Systems, Bitzer, Holiday Ice, Larkin, Arctic-Temp, Focusun Refrigeration, Manitowoc, Copeland, Icesta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Ice Machine Market Trends and Innovations
Refrigerant chemistry transitions and modular system architectures are restructuring competitive advantage in tube ice production, with efficiency mandates accelerating technology turnover cycles.
CO2 transcritical refrigeration is absorbing market share in coastal European installations where the EU F-Gas Regulation has compressed hydrofluorocarbon availability. Large-scale fishing cooperatives in the North Sea basin are specifying these systems for new-build dockside capacity. The technology is absorbing premium pricing power from legacy R-404A configurations as lifecycle cost differentials narrow under carbon pricing mechanisms.
REACH compliance requirements for chemical processing equipment are extending to ice machines used in pharmaceutical and biotechnology applications. Manufacturers must document substance safety across the supply chain for machines deployed in GMP-regulated environments. German chemical processors are demanding expanded technical files that exceed baseline CE marking obligations, creating certification segmentation between industrial and food-grade product lines.
After-sales service unbundling is fragmenting traditional procurement relationships in the beverage sector. Restaurant chains and hotel operators are separating capital equipment acquisition from maintenance contracts, pressuring OEM margin structures. This pattern concentrates in North American markets where third-party service networks have achieved density sufficient to support multi-brand maintenance agreements.
Tube Ice Machine Market Segmentation
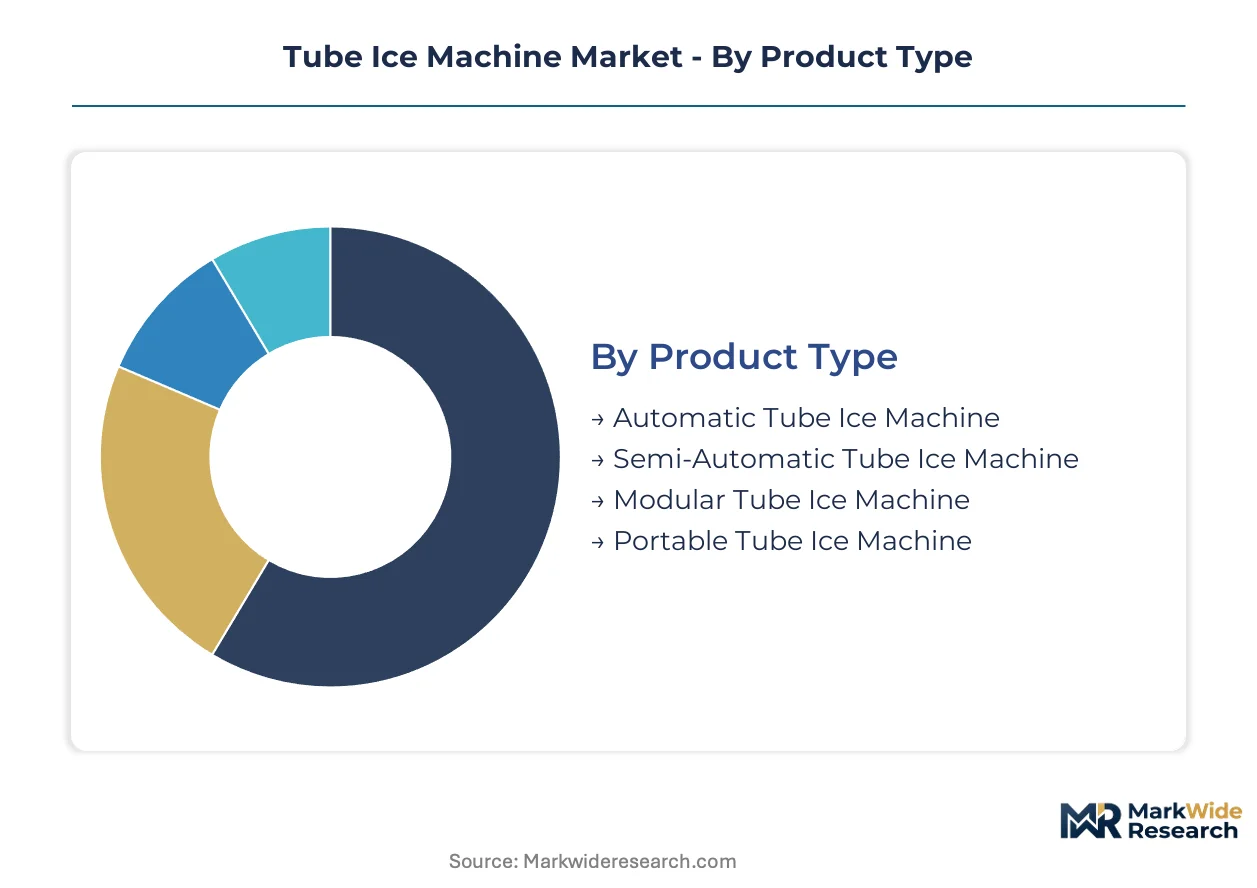
Tube ice machine procurement patterns diverge sharply across capital intensity thresholds, automation requirements, and cooling infrastructure availability. Segmentation reveals where technology investments concentrate versus where portable or modular configurations capture emerging demand.
Product Type:
Capital intensity escalates with automation integration and evaporator sophistication, separating industrial-scale installations from mobile deployments.
- Automatic Tube Ice Machine:Fully integrated systems with programmable harvest cycles and continuous production capability. Mekong Delta fishing cooperatives specify these for dockside operations where labor costs exceed capital recovery thresholds.
- Portable Tube Ice Machine:Compact units with self-contained refrigeration circuits and wheeled chassis for rapid relocation. Remote construction projects in Southeast Asian infrastructure corridors drive demand where grid connectivity remains intermittent.
- Semi-Automatic Tube Ice Machine:Intermediate systems requiring manual harvest initiation with automated ice extrusion.
- Modular Tube Ice Machine:Scalable configurations allowing capacity expansion through evaporator bank additions.
Automatic configurations absorb the bulk of installed capacity; portable units are expanding most quickly.
Technology:
Cooling medium selection hinges on ambient temperature profiles, water access economics, and regulatory discharge constraints.
- Water-Cooled:Seawater or freshwater heat rejection through shell-and-tube or plate exchangers. Vietnam's coastal processing fleets favor these where abundant seawater access reduces compressor discharge pressures.
- Air-Cooled:Finned-coil condensers rejecting heat to ambient air without water consumption. Inland Chinese provinces mandate these where water treatment regulations constrain evaporative discharge.
- Evaporative-Cooled:Hybrid systems combining water spray evaporation with air convection for tropical high-humidity environments.
- Hybrid-Cooled:Switchable architectures allowing operators to alternate between air and water rejection modes seasonally.
Water-cooled systems dominate coastal installations; air-cooled variants are gaining share fastest in inland regulatory environments.
Application:
End-use thermal requirements dictate ice geometry specifications and production continuity demands.
- Seafood Preservation:Rapid chilling of catch through direct ice contact maintains cold chain integrity from vessel to processing plant.
- Concrete Cooling:Batch temperature reduction in ready-mix operations exploits hollow-core ice geometry for accelerated heat transfer.
- Beverage Cooling:Food-service dispensing applications prioritize ice clarity and minimal mineral content for aesthetic presentation.
- Chemical Processing:Reaction temperature control in pharmaceutical synthesis requires documented ice purity under ISO 22000 protocols.
Seafood preservation commands the largest operational footprint; concrete cooling is climbing the fastest as infrastructure investment accelerates.
End User:
Procurement authority concentrates among vertically integrated processors with captive cold chain requirements versus fragmented contractor fleets.
- Fishing Firms:Fleet operators and shore-based cooperatives with continuous ice demand for catch preservation.
- Construction Companies:Project-based contractors requiring mobile cooling for concrete batching in remote locations.
- Beverage Manufacturers:Bottling plants and brewing operations with steady-state cooling loads and quality-sensitive specifications.
- Pharmaceutical Producers:GMP-regulated facilities demanding certified equipment with full supply chain documentation under REACH compliance.
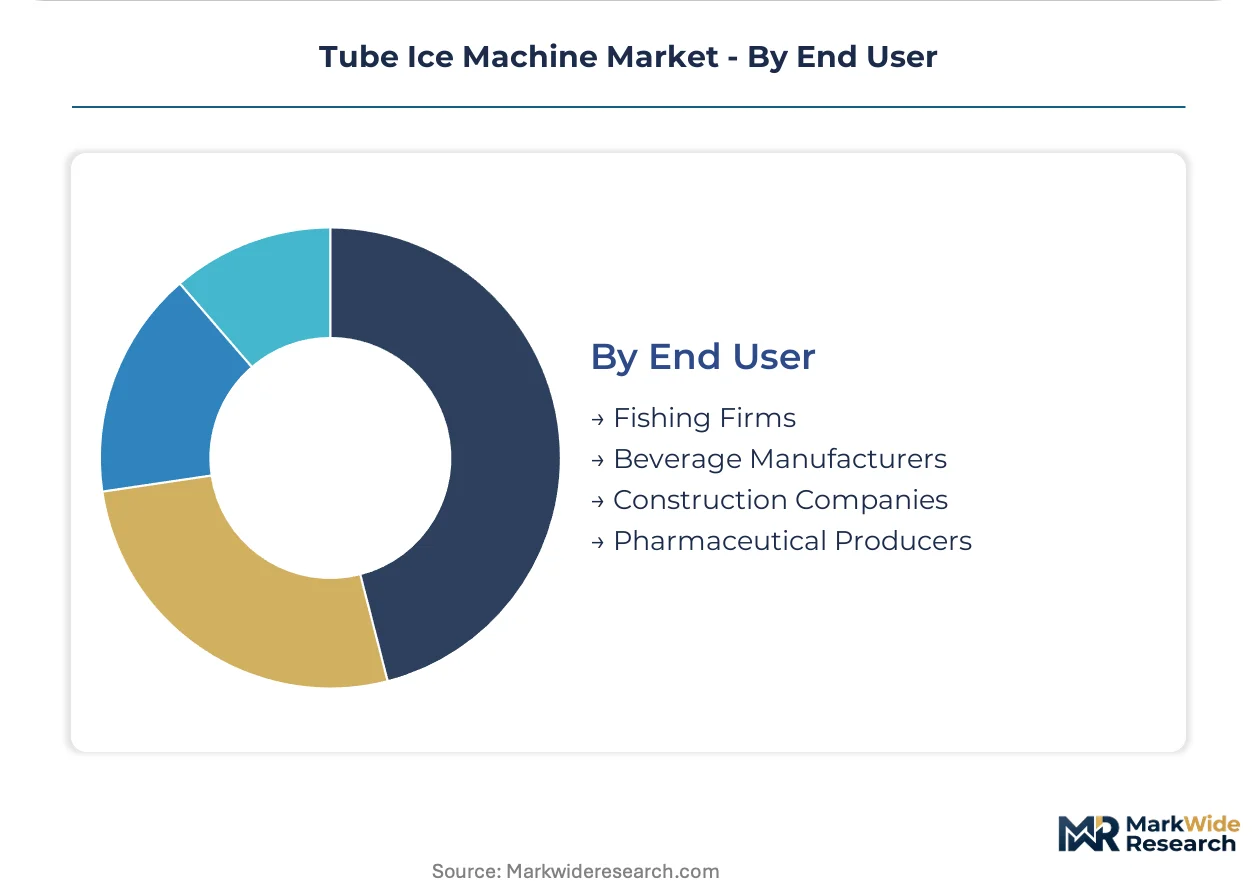
Fishing firms anchor procurement volume; construction companies are expanding their share fastest through portable system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal fishing ports with abundant seawater access anchor tube ice machine deployment, while inland regulatory environments reshape cooling technology selection across major economies.
United States
Commercial vessel operators and beverage manufacturers drive water-cooled system procurement along the Gulf and Atlantic coasts. The US Department of Energy enforces minimum efficiency standards on commercial refrigeration equipment, compressing payback periods for next-generation compressor installations. Seattle's seafood processing cluster sustains demand for dockside ice production capacity serving Pacific Northwest fishing fleets.
Vietnam
Mekong Delta fishing cooperatives accelerate mechanized ice production to displace manual block harvesting operations in shrimp and pangasius supply chains. National infrastructure investment programs prioritize dockside cold chain modernization in coastal provinces. Ho Chi Minh City anchors distribution networks connecting manufacturing facilities to Ca Mau and Kien Giang processing ports.
Germany
Chemical processors and pharmaceutical manufacturers specify certified equipment under REACH compliance requirements for GMP-regulated environments. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerant quotas, redirecting capital expenditure toward CO2 transcritical systems. Hamburg's port infrastructure supports marine refrigeration service networks serving North Sea fishing cooperatives.
China
Inland construction corridors drive portable tube ice machine adoption for remote concrete batching operations where grid connectivity remains intermittent. Provincial water treatment regulations mandate air-cooled system deployments in interior manufacturing zones. Shandong Peninsula fishing ports concentrate dockside ice production capacity serving Yellow Sea seafood processing fleets.
Japan
High-ambient coastal installations favor evaporative-cooled engineering for tropical-equivalent humidity conditions in southern prefectures. METI efficiency programs accelerate replacement cycles for legacy refrigeration equipment in food-service applications. Osaka-Kobe industrial corridor maintains specialized technician training infrastructure for ammonia system deployment.
Tube Ice Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular and portable configurations for remote deployment scenarios. The vendor base stratifies across three maturity levels: multinational refrigeration specialists with integrated service networks, regional fabricators competing on evaporator engineering customization, and specialized entrants targeting portable segment expansion. Strategic differentiation concentrates on refrigerant transition readiness and after-sales service unbundling. Competitive moves prioritize technology licensing partnerships for CO2 transcritical architectures and geographic expansion through third-party service network density.
Among North American refrigeration specialists, Scotsman Ice Systems and Manitowoc exemplify established-tier positioning through integrated commercial relationships. Focusun Refrigeration represents the regional-fabricator archetype with engineering specialization in tropical dockside installations. These three anchors illustrate how competitive positioning stratifies across service network reach, evaporator customization capability, and modular system scalability rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Scotsman Ice Systems |
| Bitzer |
| Holiday Ice |
| Larkin |
| Arctic-Temp |
| Focusun Refrigeration |
| Manitowoc |
| Copeland |
| Icesta |
| Others |
Pricing and Supply Chain Analysis
Captive service network integration anchors both supply positioning and pricing power for tube ice machine OEMs, with North American multinationals leveraging dense technician infrastructure to bundle multi-year maintenance contracts that inflate upfront equipment premiums while compressing total cost of ownership for fishing cooperatives and beverage processors.
Pricing Analysis
Warranty and service-bundling configurations stratify buyer segments, with unbundled after-sales arrangements gaining traction among North American restaurant chains seeking third-party maintenance flexibility. Pricing stratifies across premium, standard, and economy tiers keyed to refrigerant architecture sophistication, with CO2 transcritical systems commanding certification premiums under EU F-Gas Regulation constraints. Cost compression in mid-tier air-cooled configurations intensifies as Chinese regional fabricators scale evaporator production. Large-scale fishing cooperatives exhibit lowest price sensitivity due to lifecycle cost focus, while remote construction contractors prioritize capital minimization over efficiency metrics.
Supply Chain Analysis
Compressor supply rests on German and Japanese precision manufacturing clusters, with Bitzer and Copeland anchoring displacement and screw compressor availability for industrial-scale evaporator banks. Copper tubing and aluminum finstock draw from Chinese smelting capacity, while electronic control modules source from South Korean semiconductor packaging operations. Single-source vulnerability concentrates in CO2 transcritical valve assemblies, where European specialty component producers maintain limited qualified supplier lists. Distribution runs through authorized dealer networks with regional service subcontracts, constraining direct OEM relationships outside major metropolitan processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation erects a compliance moat that favors incumbent capital reserves, with hydrofluorocarbon phase-down timelines forcing mid-tier manufacturers toward expensive refrigerant architecture transitions that strain balance sheets before scale economies materialize.
For Market Incumbents: Cement defensible positioning through backward integration into compressor remanufacturing capabilities that shorten lead times for tropical dockside installations. Acquire ammonia refrigeration training infrastructure in Southeast Asian markets where technician scarcity constrains CO2 system deployment. The threat of modular portable entrants from Chinese fabricators demands preemptive channel control in Vietnam's Mekong Delta corridor. For New Entrants and Emerging Players: Remote construction contractors represent the most penetrable buyer archetype, with intermittent grid connectivity and project-based demand cycles underserved by legacy OEM service networks. Target portable system deployment through equipment rental partnerships rather than direct capital sales. White-space concentration appears in concrete cooling applications for Southeast Asian infrastructure corridors, where batch temperature control specifications diverge from seafood preservation norms. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational refrigeration specialists seeking tropical evaporator engineering capabilities. Long-term viability hinges on refrigerant transition readiness rather than manufacturing scale alone. The signal to watch is municipal energy subsidy synchronization across Vietnamese coastal provinces, which would accelerate installed-base replacement cycles and validate premium technology investments.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Technology Licensing | EU F-Gas Regulation compliance unlocks premium pricing in North Sea fishing cooperatives. |
| Backward Integration into Compressor Remanufacturing | Captive refurbishment capacity compresses service response times for dockside fleets. |
| Portable System Rental Partnerships | Project-based construction demand in Vietnam infrastructure corridors escapes capital constraints. |
| Ammonia Technician Training Infrastructure | Specialized vocational programs address CO2 deployment bottlenecks in emerging markets. |
| ISO 22000 Certification Pathway Investment | Food safety documentation creates export-market access barriers for uncertified competitors. |
Research Methodology
Independent corroboration across maintenance directors at fishing cooperatives, plant engineers at beverage bottling facilities, aftermarket service heads at regional refrigeration dealers, and procurement leads at concrete batching operations underwrites the qualitative findings. Secondary validation draws from customs trade data for compressor and evaporator imports, SEC filings of listed refrigeration equipment manufacturers, EU F-Gas Regulation quota tracking databases, and dockside infrastructure investment disclosures from Vietnamese provincial planning authorities. Bottom-up installed-base estimates triangulate against top-down market size calculations derived from capital expenditure patterns across seafood processing and chemical manufacturing verticals.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchor the forecast window across the projection horizon. Segmentation dimensions modeled include automation intensity, cooling technology architecture, refrigerant chemistry compliance tier, end-use thermal application, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating energy-efficiency mandate compliance costs and labor cost threshold crossover points. Industry-specific inputs encompass fishing fleet mechanization rates in Southeast Asia and concrete infrastructure investment pipelines in Chinese interior provinces.
Revisions become necessary when refrigerant transition timelines accelerate, energy subsidy programs fragment across municipal jurisdictions, or ammonia system deployment outpaces vocational training output. Forecasts reflect documented assumptions regarding compliance cost trajectories and technology substitution elasticities. A small set of named triggers warrants ongoing watch: EU F-Gas quota auction outcomes, Vietnamese dockside electrification schedules, and METI efficiency program revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Global Electrodialysis Equipment Market