
 Food Grade Nylon Market | 2026-2036
Food Grade Nylon Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Nylon Market Foresight
China is narrowing the gap between domestic polyamide supply and food-contact certification capacity as state-backed chemical parks add compounding lines. BASF leverages its Ludwigshafen integrated site to sustain European food-grade nylon output with backward control over caprolactam feedstock. DuPont anchors North American supply through specialized polymer grades engineered for low-migration film applications.
Food grade nylon denotes polyamide resins meeting FDA 21 CFR 177.1500 and EU 10/2011 migration limits for repeated food contact, typically synthesized via ring-opening polymerization of lactams or condensation of diamines with dicarboxylic acids to achieve molecular weights between 15,000 and 30,000 g/mol with extractable fractions below regulatory thresholds. Nylon 6 and Nylon 66 occupy the dominant volume positions due to established supply chains and cost-efficient polymerization, while Nylon 12 commands premium positioning in high-barrier film and tubing where lower moisture absorption and superior chemical resistance protect margin pools. Granule form leads industrial offtake as compounders prefer melt-extrusion-ready feedstock, though film form captures faster growth from vacuum packaging and modified-atmosphere applications.
FDA migration testing protocols and EU Regulation 10/2011 establish the compliance baseline for market access, with China's National Health Commission issuing supplementary food-contact material standards that foreign suppliers must navigate for import clearance. REACH and RoHS frameworks in Europe further constrain additive packages and processing aids permitted in food-grade formulations. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances that threaten incumbent barrier coatings and could accelerate nylon substitution in certain packaging architectures.
Market Dynamics
Migration from fluorinated barrier coatings toward polyamide alternatives is compressing certification timelines and rewiring supplier qualification protocols across food-contact packaging supply chains.
Growth Catalysts
- EU 10/2011 Migration Limits:Harmonized testing protocols reduce regulatory fragmentation for compounders seeking multi-jurisdiction approval, accelerating cross-border material flows.
- Modified-Atmosphere Packaging:Retail meat and cheese processors specify nylon 6/66 coextrusions for oxygen scavenging, pulling film-grade resin volumes upward.
- Caprolactam Supply Diversification:China and Germany now host parallel feedstock corridors, diluting historical concentration risk around single-source monomer inputs.
Market Restraints
- Caprolactam Price Volatility:Benzene-derived monomer costs swing with crude differentials, compressing compounder margins unpredictably.
- Additive Package Constraints:REACH and RoHS restrict plasticizers and heat stabilizers permitted in food-contact grades, forcing reformulation cycles.
- High-Barrier Film Substitution:Ethylene vinyl alcohol copolymers and metallized polyesters compete in oxygen transmission rate-sensitive applications.
Strategic Opportunities
- India FSSAI Compliance Gap:Domestic compounders lack certified food-grade nylon capacity, creating import substitution potential for qualified foreign suppliers.
- Active Packaging Convergence:Oxygen-absorbing nylon layers hybridized with natural antioxidant inserts target premium ready-meal segments.
- Recyclable Monomaterial Design:Supermarket private-label mandates in Germany and France favor single-polymer packaging architectures that boost nylon 6 recyclate demand.
Industry Challenges
- Migration Testing Bottlenecks:FDA 21 CFR 177.1500 protocol completion stretches 18-24 months, freezing product launch schedules.
- Extrusion Technician Scarcity:Food-grade film production demands operators skilled in melt rheology control and contamination prevention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Nylon Market |
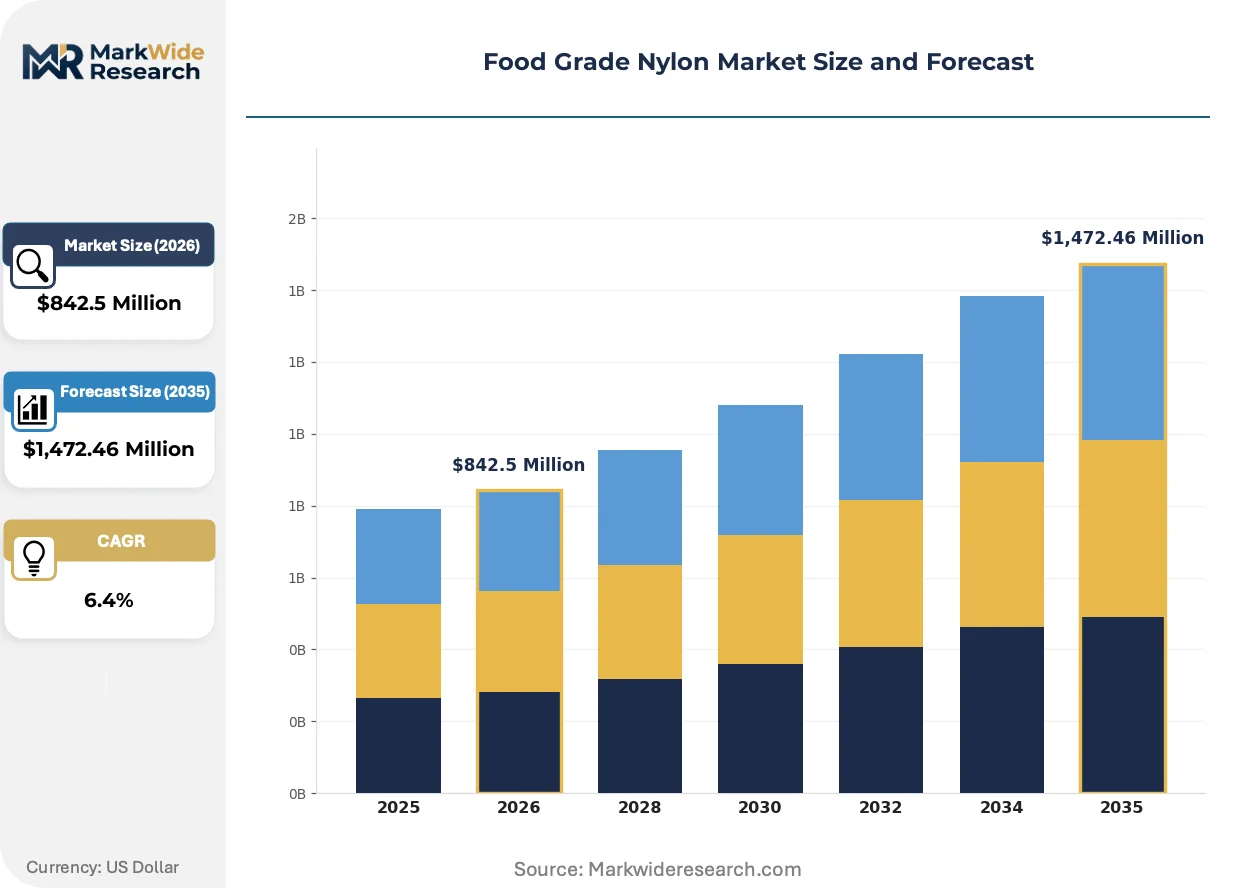
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,472.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon 6, Nylon 66, Nylon 11, Nylon 12, Nylon 610 Form: Film, Sheet, Rod, Tube, Granules Application: Packaging, Industrial Films, Consumer Goods, Food Processing Equipment End User: Food & Beverage Manufacturers, Packaging Companies, Equipment Fabricators, Specialty Suppliers |
| Companies Covered | DuPont, BASF, Invista, Ascend Performance Materials, Solvay, Toray Industries, EMS-Chemie, Evonik Industries, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Nylon Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to displace incumbent barrier technologies with engineered polyamide architectures.
Barrier nylon is hybridizing with bio-based caprolactam feedstocks to meet brand-owner carbon reduction targets without sacrificing oxygen transmission performance. European dairy packaging converters pilot these grades in thermoformed cheese trays. The technology is hybridizing supply chains, forcing compounders to dual-source petrochemical and renewable monomer streams.
REACH restrictions on per- and polyfluoroalkyl substances eliminate incumbent grease-resistant coatings from paperboard food packaging. ECHA enforcement timelines compress substitution decisions into 24-month windows. Nordic ready-meal producers now specify nylon 12 tubing for fatty acid contact, redirecting premium resin allocations northward.
Certification-driven procurement now dominates capital equipment purchasing for food-contact film lines. Brand-owner technical audits replace generic resin specifications with compounder-specific migration test data. This pattern concentrates supplier relationships in Germany and the United States where documentation depth exceeds Asian competitors.
Food Grade Nylon Market Segmentation
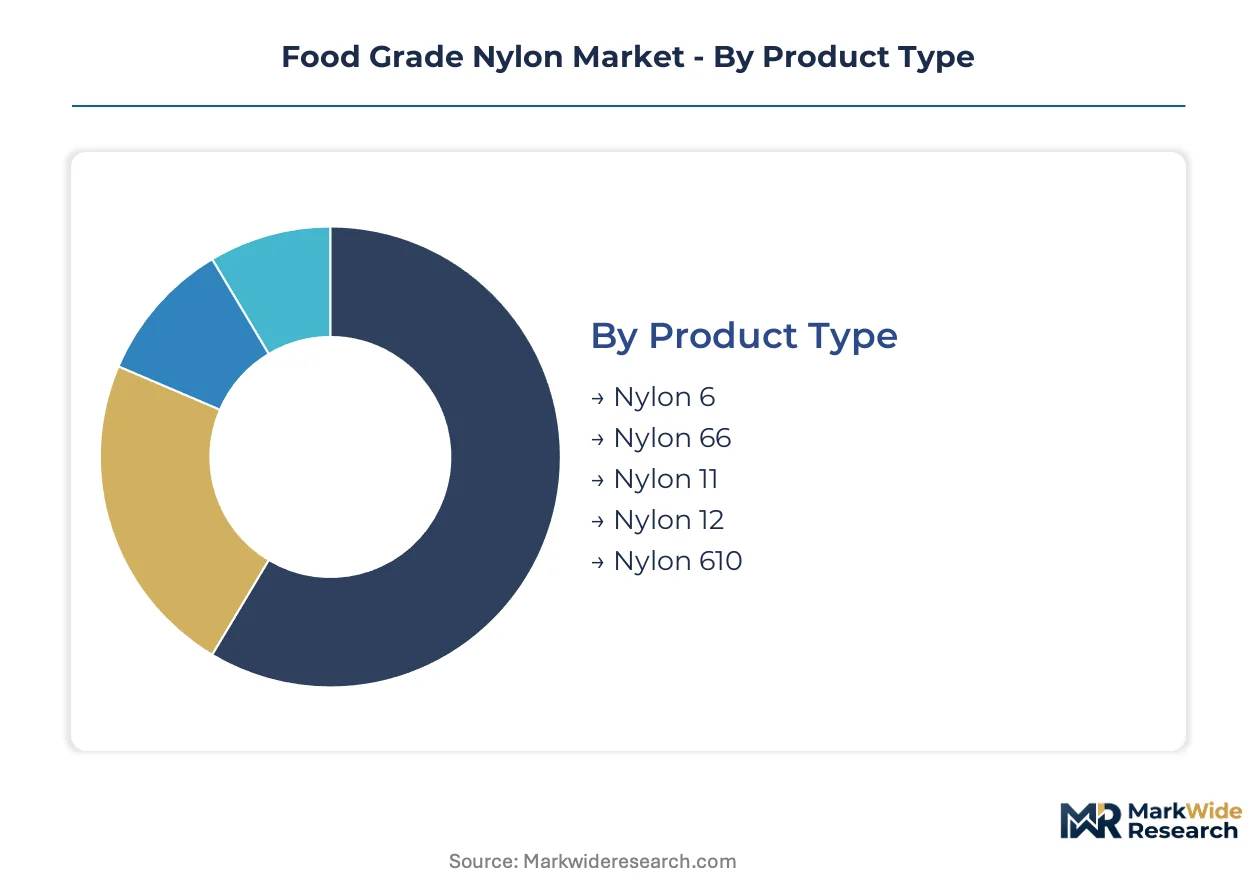
Food grade nylon segmentation reflects divergent technical requirements across barrier performance, processing methods, and regulatory exposure. Each dimension shapes compounder formulation priorities and end-user procurement criteria.
Product Type:
Mature polyamide chemistries dominate volume flows while specialty grades capture margin expansion from stringent migration limits.
- Nylon 6:Ring-opened polycaprolactam with molecular weights of 15,000–30,000 g/mol serves as the workhorse for extruded films and thermoformed trays. German dairy converters specify this grade for modified-atmosphere cheese packaging where cost efficiency outweighs moisture sensitivity.
- Nylon 66:Condensation polymer of adipic acid and hexamethylenediamine delivers superior thermal stability for high-temperature filling lines. Chinese meat processors favor this grade for retort pouches requiring sustained barrier integrity above 121°C.
- Nylon 11:Bio-derived polyamide from castor oil feedstock offers renewable content positioning for brand-owner sustainability mandates.
- Nylon 12:Lower moisture absorption and exceptional chemical resistance command premium pricing in fatty acid contact tubing applications.
- Nylon 610:Partially bio-based diamine chemistry serves niche pharmaceutical-food hybrid packaging with extended hydrolytic stability.
Nylon 6 retains volume leadership; Nylon 12 holds the steepest expansion curve.
Form:
Processing methodology dictates form selection, with melt-extrusion feedstock commanding the largest industrial offtake.
- Granules:Standardized pellet geometry enables precise dosing in twin-screw compounding lines. BASF's Ludwigshafen facility ships food-certified granules to compounders across Germany, the Netherlands, and Belgium for downstream film extrusion.
- Film:Pre-extruded rolls or sheets accelerate converter throughput for vacuum packaging and lidding applications. US retail meat packers specify coextruded nylon film from DuPont for oxygen scavenging layers in case-ready beef programs.
- Sheet:Calendered or extruded flat stock serves thermoforming operations for rigid food trays and containers.
- Rod:Solid cylindrical stock machined into bearings, gears, and wear components for food processing machinery.
- Tube:Extruded hollow profiles deliver chemical resistance in fluid transfer lines and pneumatic systems.
Granules anchor industrial procurement volumes; film is expanding most quickly from ready-meal packaging proliferation.
Application:
Barrier functionality requirements separate commodity packaging from specialized equipment-grade specifications.
- Packaging:Multilayer flexible films, rigid thermoformed containers, and lidding structures constitute the dominant demand channel. French supermarket private-label mandates favor monomaterial nylon 6 designs to satisfy extended producer responsibility frameworks.
- Industrial Films:Heavy-gauge sheeting for bulk food storage and transport applications requires puncture resistance and weldability.
- Consumer Goods:Kitchen utensils, appliance components, and reusable food containers leverage nylon's temperature tolerance and dishwasher durability.
- Food Processing Equipment:Gears, bearings, scraper blades, and conveyor components exposed to washdown cycles specify FDA-compliant grades with enhanced wear resistance.
Packaging commands the largest revenue pool; food processing equipment is gaining share fastest from automation investment.
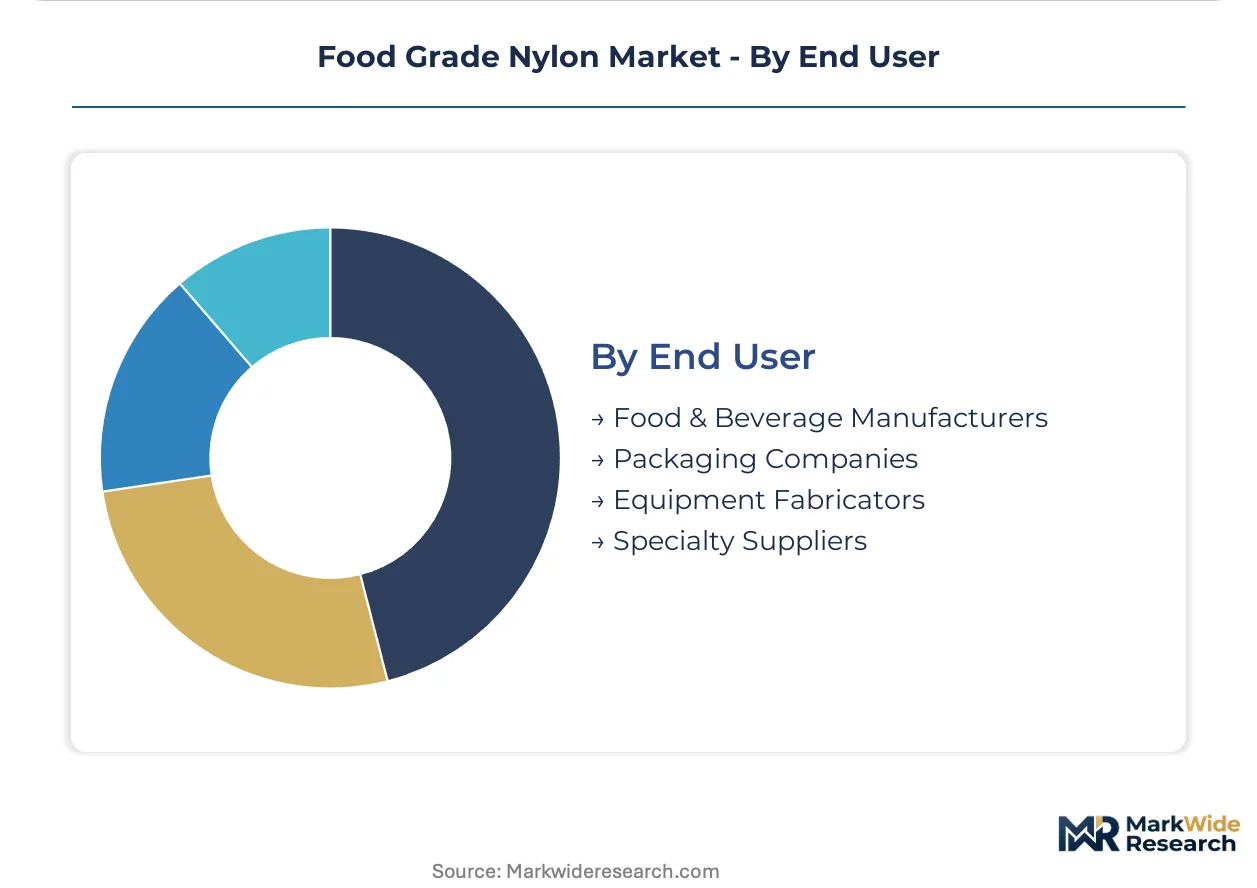
End User:
Procurement sophistication varies sharply between integrated manufacturers and specialized fabricators.
- Food & Beverage Manufacturers:Nestlé, PepsiCo, and Tyson Foods operate technical audit protocols that supersede generic resin specifications with compounder-specific migration documentation. These stakeholders drive certification depth requirements across the supply base.
- Packaging Companies:Amcor, Sealed Air, and Berry Global purchase resin at scale for converter operations, prioritizing melt-flow consistency and lot-to-lot color stability.
- Equipment Fabricators:OEMs producing filling lines, slicing equipment, and material handling systems specify machined or molded nylon components for FDA-compliant contact surfaces.
- Specialty Suppliers:Niche compounders and distributors serve regional processors with smaller volume requirements and customized additive packages.
Food & beverage manufacturers set compliance benchmarks; specialty suppliers are climbing the fastest from small-batch customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA migration protocols anchor the United States as the dominant geography, with Germany and China following as regulatory complexity and manufacturing scale concentrate supply chain decisions in these three markets.
United States
Case-ready meat programs and modified-atmosphere cheese packaging drive resin offtake from compounders serving Tyson Foods and Nestlé operations. FDA 21 CFR 177.1500 compliance documentation requirements exceed 18-month completion cycles, freezing supplier qualification schedules. Wilmington, Delaware anchors North American technical development through DuPont's specialized polymer grades engineered for low-migration film applications.
Germany
Supermarket private-label mandates for monomaterial packaging architectures accelerate nylon 6 recyclate demand from French and German retail chains. EU Regulation 10/2011 harmonized testing protocols reduce regulatory fragmentation for compounders seeking multi-jurisdiction approval. Ludwigshafen hosts BASF's integrated caprolactam-to-polymer site sustaining European food-grade output with backward control over feedstock supply.
China
Domestic meat processors favor nylon 66 for retort pouches requiring sustained barrier integrity above 121°C in high-temperature filling lines. National Health Commission supplementary food-contact material standards impose import clearance requirements foreign suppliers must navigate. State-backed chemical parks in Yangtze River Delta provinces add compounding lines, narrowing the gap between domestic polyamide supply and food-contact certification capacity.
India
Domestic compounders lack certified food-grade nylon capacity, creating import substitution potential for qualified foreign suppliers serving regional processed food manufacturers. FSSAI compliance gaps in local testing infrastructure extend certification timelines for new material introductions. Maharashtra industrial corridors concentrate packaging converter operations that currently rely on imported granule feedstock from European and East Asian sources.
Japan
Premium ready-meal segments specify oxygen-absorbing nylon layers hybridized with natural antioxidant inserts for extended shelf-life applications. METI industrial standards for food-contact materials align with EU migration limit frameworks, simplifying multi-market approval pathways. Kanto region polymer compounders serve domestic dairy and seafood packaging converters with specialized film-grade formulations.
Food Grade Nylon Market Competitive Landscape
Integrated petrochemical conglomerates and specialized polyamide compounders split the market into distinct capability tiers. Consolidation around caprolactam feedstock control and migration testing documentation depth creates structural barriers for new entrants. Three archetypes dominate: backward-integrated resin producers with captive monomer supply, independent compounders with formulation flexibility, and regional distributors with certification navigation expertise. Competitive moves center on capacity expansion in China and Germany plus strategic partnerships linking resin producers to film converter networks.
Within the integrated-resin-producer tier, BASF and DuPont exemplify archetype dominance through geographic anchoring in Ludwigshafen and Wilmington respectively. EMS-Chemie represents the Swiss specialist model with concentrated European positioning. These three entities occupy positions where regulatory documentation depth and feedstock integration create defensive moats against Asian competitors still building food-contact certification infrastructure.
| Leading Market Players |
|---|
| DuPont |
| BASF |
| Invista |
| Ascend Performance Materials |
| Solvay |
| Toray Industries |
| EMS-Chemie |
| Evonik Industries |
| Honeywell International |
| Others |
Supply & Pricing Matrix
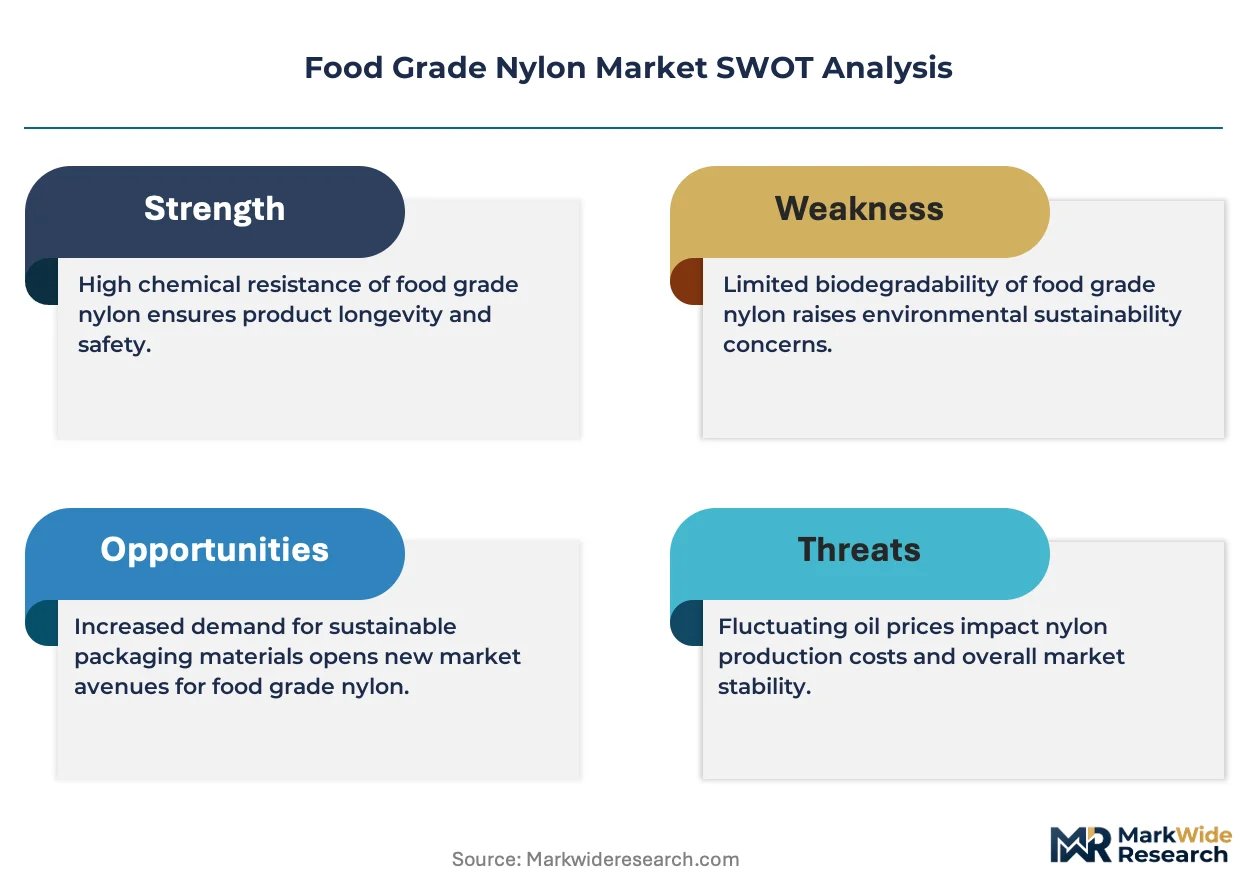
Caprolactam price volatility, tethered to benzene crude differentials, compresses compounder margins unpredictably and forces tiered pricing separation between certified food-grade resin and industrial-grade alternatives. This feedstock instability concentrates pricing power with backward-integrated producers in Germany and the United States while fragmenting procurement options for Asian compounders lacking captive monomer supply.
Pricing Analysis
German and Chinese resin quotations diverge by certification tier, with FDA 21 CFR 177.1500-compliant material commanding substantial premiums over industrial grades. Pricing stratifies across migration-test-certified, food-contact-declared, and uncertified economy tiers based on documentation depth and lot traceability. Cost compression in standard-grade nylon 6 is intensifying because of caprolactam oversupply from Yangtze River Delta expansions. Packaging converters at Amcor and Sealed Air exhibit highest price sensitivity, while pharmaceutical-food hybrid manufacturers absorb premiums for Nylon 12 tubing with minimal negotiation.
Supply Chain Analysis
EU REACH restrictions on per- and polyfluoroalkyl substances limit barrier-coating alternatives, redirecting resin flows toward polyamide compounders with existing food-contact approvals. Feedstock concentration centers on Germany, China, and the United States, where caprolactam production corridors sustain polymer output. The supply chain draws from benzene-derived monomers, adipic acid intermediates, and specialized heat-stabilizer additive packages. Single-source vulnerability around Ludwigshafen and Wilmington technical-grade facilities creates geographic chokepoint exposure. Distribution runs through certified compounder networks into film converter operations across Belgium, the Netherlands, and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Nestlé, PepsiCo, and Tyson Foods as their technical audit protocols displace generic resin specifications, forcing supplier consolidation around documentation-heavy compounders.
For Market Incumbents: Entrench certification depth as a defensive moat by accelerating FDA 21 CFR 177.1500 protocol completion for expanded resin grades, countering emerging Asian compounders with faster 18-24 month regulatory timelines. Prioritize backward integration into caprolactam feedstock through Ludwigshafen or Yangtze River Delta capacity additions, neutralizing margin compression from benzene price swings. For New Entrants and Emerging Players: Pursue India's FSSAI compliance gap where domestic compounders lack certified food-grade nylon capacity, offering import substitution to Maharashtra packaging converters currently sourcing European granules. Target active packaging convergence segments—oxygen-absorbing nylon layers for premium ready-meal applications—where technical differentiation supersedes price competition and certification barriers remain surmountable. For Investors and Strategic Acquirers: EU 10/2011 enforcement timelines reshapes the acquisition landscape by compressing substitution decisions into 24-month windows for PFAS-displaced barrier technologies. Long-term viability over the mid-term projection horizon favors compounders with dual petrochemical and bio-based caprolactam feedstock sourcing. Watch ECHA per- and polyfluoroalkyl substance restriction expansion as the signal indicating accelerated nylon substitution velocity in paperboard food packaging.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | BASF's Ludwigshafen site secures feedstock autonomy against benzene price volatility. |
| FDA 21 CFR 177.1500 Certification Acceleration | DuPont leverages Wilmington technical center to compress 18-month migration test cycles. |
| Bio-Based Caprolactam Feedstock Sourcing | European dairy converters pilot renewable-content grades for carbon reduction mandates. |
| Active Packaging Layer Development | Nordic producers specify oxygen-absorbing nylon hybridized with natural antioxidant inserts. |
| Monomaterial Packaging Architecture Design | German supermarket private-label mandates boost Nylon 6 recyclate demand from French retail chains. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR 177.1500 compliance databases, EU Regulation 10/2011 migration test submissions, and caprolactam trade flow customs records. Interviews with polymer plant managers, packaging converter procurement leads, food-contact regulatory affairs directors, and film extrusion technical operators informed demand-side validation. Secondary sources include SEC 10-K filings from integrated resin producers, Cefic chemical industry reports, and National Health Commission food-contact material standards. Bottom-up resin volume estimates triangulate against top-down packaging industry consumption models.
Forecast inputs span polyamide grade tier, end-use application intensity, packaging format migration, and regional regulatory cluster stringency across the analysis window. Segmentation dimensions modeled include Nylon 6/66/12 chemistry splits, granule versus film form factors, and food processing equipment versus packaging end-use channels. CAGRs derive from regression against historical caprolactam price elasticity and food-contact certification adoption curves. Industry-specific forecast inputs incorporate REACH PFAS restriction enforcement phasing and FSSAI infrastructure development timelines in India.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, benzene derivative costs, or euro-dollar exchange rate volatility would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement consistency and certification timeline stability. Material shifts in EU per- and polyfluoroalkyl substance restriction scope or FDA migration protocol duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Shear Mixer Market
Industrial Materials
Bamboo Products Market
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Paint Knife Market
Industrial Materials
Extruders Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Plastic Molds Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Fly Ash Market
Industrial Materials
Fiberglass Tanks Market