
 Bamboo Products Market | 2026-2036
Bamboo Products Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Products Market Analysis
Subscription-based maintenance for bamboo-flooring installations is decoupling product revenue from long-term customer value. MOSO International B.V. leverages its Dutch design hub to dominate premium European specification channels. Jiangxi Feiyu Bamboo Industry Group anchors China's engineered-bamboo supply through captive plantation-to-factory logistics. Smith & Fong Co. differentiates by specializing in FSC-certified strand-woven products for North American commercial projects.
Bamboo products comprise processed and engineered goods derived from fast-growing perennial grasses in the Bambusoideae subfamily, with Moso bamboo reaching harvest maturity in three to five years and yielding cellulose fiber densities comparable to hardwoods. The primary commercial purpose centers on substituting timber and synthetic materials in load-bearing construction, interior finishes, and durable consumer goods. Bamboo flooring commands the largest value pool among product types due to established installation infrastructure and warranty-backed performance claims, while bamboo textiles represent the fastest-expanding category as closed-loop viscose processing reduces chemical-input intensity. Eco-conscious consumers within the end-user dimension generate disproportionate margin capture because certification premiums offset higher procurement costs.
EPA formaldehyde-emission standards under TSCA Title VI govern bamboo-composite panel imports into the United States, compelling overseas manufacturers to reconfigure resin formulations. EUDR traceability requirements and REACH chemical restrictions shape European market access for bamboo kitchenware and textile suppliers. China's GB/T standards for bamboo flooring mandate density and swelling-rate thresholds that filter low-capability producers. Stakeholders must monitor how carbon-border adjustment mechanisms reclassify bamboo's biogenic carbon status relative to competing biomaterials.
Market Dynamics
Carbon-border adjustment mechanisms are forcing bamboo producers to document biogenic carbon credentials through chain-of-custody systems, compressing margins for uncertified suppliers while rewarding plantation-to-factory traceability investments.
Growth Catalysts
- EUDR Due-Diligence Protocols:European retailers now mandate deforestation-free sourcing documentation, pulling Vietnamese furniture exporters toward certified bamboo supply chains.
- Strand-Woven Processing:Dense compression technology transforms lower-grade culms into load-bearing structural panels, opening commercial construction specification channels.
- Vietnam's Export Corridor:Manufacturers cluster near Ho Chi Minh City port infrastructure to minimize lead times for EU and North American furniture orders.
Market Restraints
- Adhesive Cost Volatility:Phenol-formaldehyde resin prices fluctuate with petrochemical feedstock markets, squeezing engineered-bamboo panel margins.
- Plantation Concentration Risk:Anhui and Jiangxi provinces in China control over sixty percent of industrial Moso supply, creating single-source vulnerability.
- Dimensional Stability Limits:Natural fiber hygroscopicity restricts bamboo flooring deployment in high-humidity commercial kitchens and spa environments.
Strategic Opportunities
- India's Building Code Revision:BIS standards for non-timber structural materials create first-mover advantage for engineered-bamboo beam suppliers in affordable housing.
- Closed-Loop Viscose:Lyocell solvent-recovery systems slash chemical-input intensity, positioning bamboo textiles for premium apparel brand sourcing.
- Direct-to-Contractor Platforms:Digital procurement portals bypass traditional distributor markups for mid-scale residential developers in Germany and Netherlands.
Industry Challenges
- FSC Chain-of-Custody Auditing:Multi-site certification complexity delays market access for smallholder-integrated cooperatives in Fujian province.
- Legacy Resin Curing Infrastructure:Hot-press equipment designed for wood particleboard requires retrofitting to achieve optimal bamboo fiber densification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Products Market |
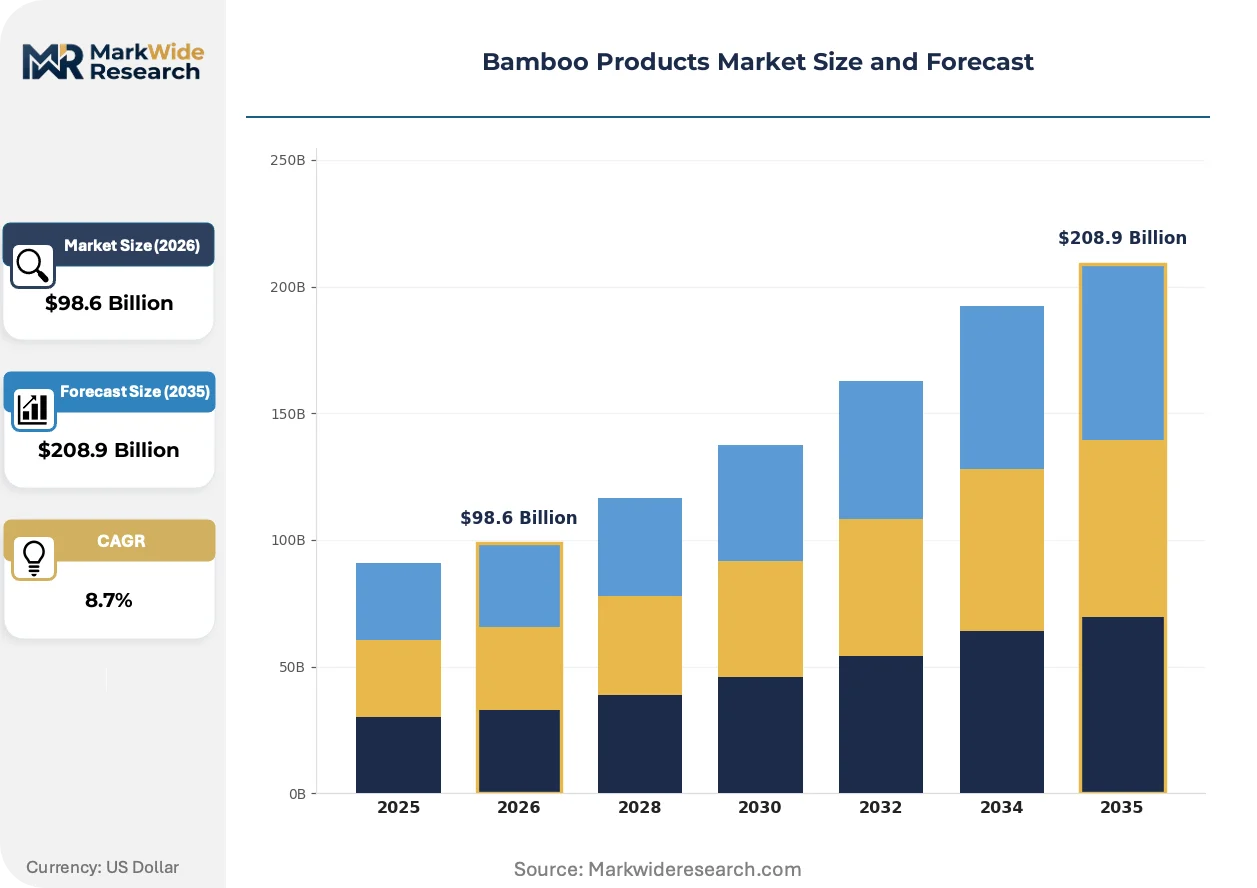
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo Flooring, Bamboo Furniture, Bamboo Kitchenware, Bamboo Textiles End User: Residential, Commercial, Industrial, Eco-conscious Consumers Application: Construction, Home Décor, Utensils, Textile Manufacturing Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | EcoPlanet Bamboo Group, Dasso Group, MOSO International B.V., Jiangxi Feiyu Bamboo Industry Group, Anji Tianzhen Bamboo Flooring Co., Ltd., Bamboo Village Company Limited, The Bamboo Company, Southern Bamboo Inc., Smith & Fong Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Products Market Emerging Trajectories
Digital traceability infrastructure and low-carbon processing chemistry are compressing traditional supply hierarchies while opening premium specification channels for verified-sustainable bamboo materials.
Cross-laminated bamboo (CLB) panel systems are consolidating structural engineering acceptance through fire-rated performance testing. German and Austrian mid-rise developers specify CLB for residential cores, displacing glulam timber in cost-sensitive segments. The technology is consolidating market position by satisfying both EPD transparency requirements and accelerated construction timelines.
China's GB/T 30364 standard revision for bamboo flooring mandates stricter density and swelling-rate thresholds, filtering low-capability producers from export eligibility. MIIT enforcement timelines compress factory upgrade windows. Vietnamese manufacturers with pre-certified lab partnerships capture displaced EU orders from non-compliant Chinese competitors.
Specification buyers now unbundle material procurement from installation warranties, forcing producers to certify installer networks or cede margin to third-party service platforms. Netherlands-based housing associations pilot this model for social housing retrofits. The shift concentrates purchasing power with asset managers who prioritize lifecycle carbon data over upfront material cost.
Bamboo Products Market Segmentation
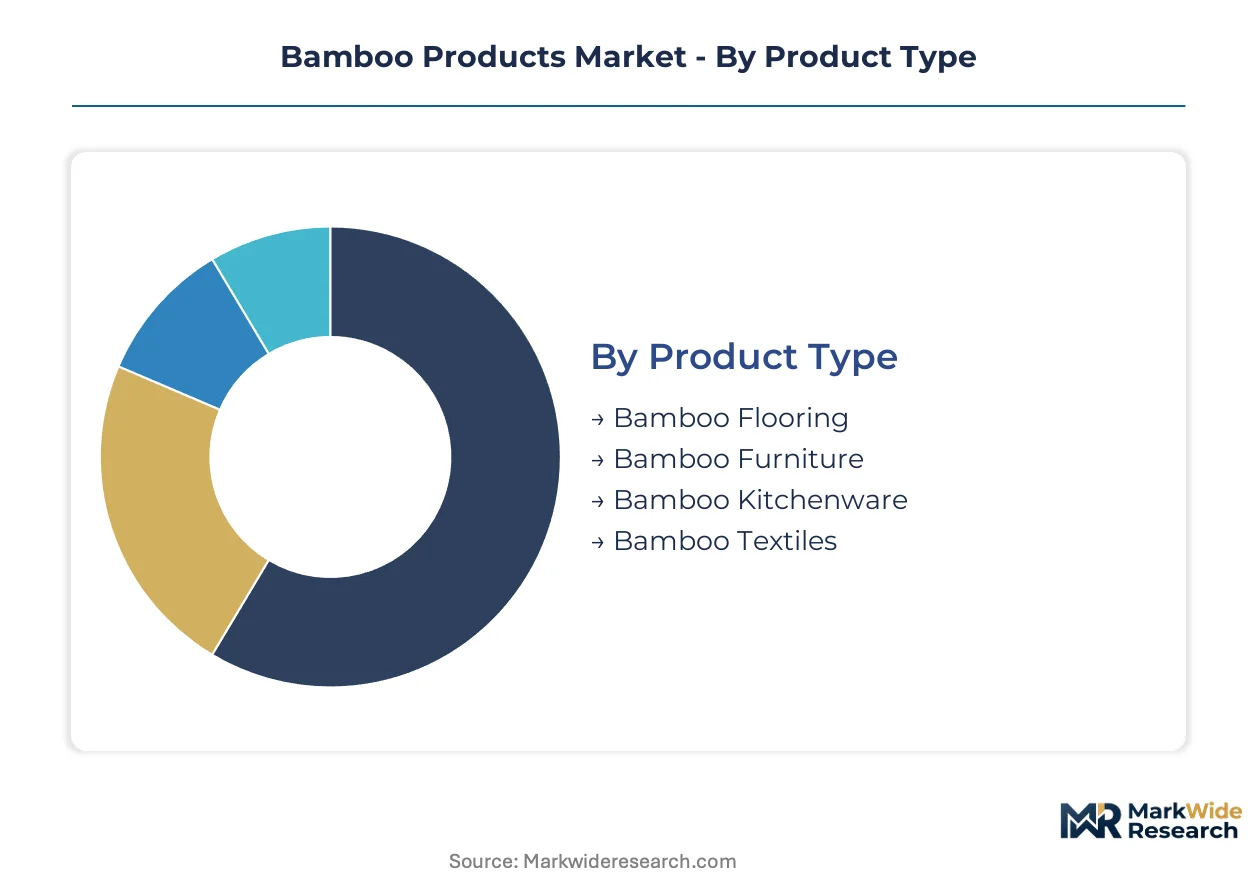
Bamboo product specifications diverge sharply between commodity-grade exports and certified premium channels. Segmentation discipline separates volume-driven manufacturers from margin-capturing specialists.
Product Type:
Customization intensity ranges from standardized dimensional lumber to engineered composites with proprietary resin formulations.
- Bamboo Flooring:Engineered planks and solid-strip formats dominate residential specification. Vietnamese exporters near Ho Chi Minh City supply European retailers under EUDR due-diligence protocols. Strand-woven variants penetrate commercial load-bearing applications through density advantages.
- Bamboo Furniture:Flat-pack assembly systems and finished case goods split the value chain. Manufacturers cluster in Vietnam's export corridor to minimize lead times for EU orders.
- Bamboo Kitchenware:Cutting boards and utensil sets serve mass-market channels with minimal certification overhead.
- Bamboo Textiles:Closed-loop viscose processing reduces chemical-input intensity for premium apparel sourcing.
Most installed capacity flows through Bamboo Flooring. Expansion is steepest in Bamboo Textiles.
End User:
Price sensitivity and certification willingness create distinct procurement behaviors across customer types.
- Residential:Homeowners prioritize warranty-backed performance claims and installation support. Southeast Asian builders specify tensile strength and carbon-sequestration profiles.
- Commercial:Asset managers prioritize lifecycle carbon data over upfront material cost. Netherlands housing associations pilot unbundled procurement models.
- Industrial:Processors of raw culm stock demand consistent fiber density for downstream panel production.
- Eco-conscious Consumers:Certification premiums offset higher procurement costs for this disproportionate margin-capture segment.
Volume concentrates in Residential procurement. Steepest expansion trajectory belongs to Eco-conscious Consumers.
Application:
Performance requirements vary from structural load-bearing to aesthetic surface finishing.
- Construction:Cross-laminated bamboo panel systems consolidate structural engineering acceptance through fire-rated performance testing. German and Austrian mid-rise developers specify CLB for residential cores.
- Home Décor:Interior finish applications demand dimensional stability in variable humidity environments.
- Utensils:Food-contact safety compliance shapes resin selection and surface treatment protocols.
- Textile Manufacturing:Lyocell solvent-recovery systems position bamboo fiber for closed-loop apparel production.
Construction channels absorb the heaviest material tonnage. Home Décor applications are climbing the fastest.
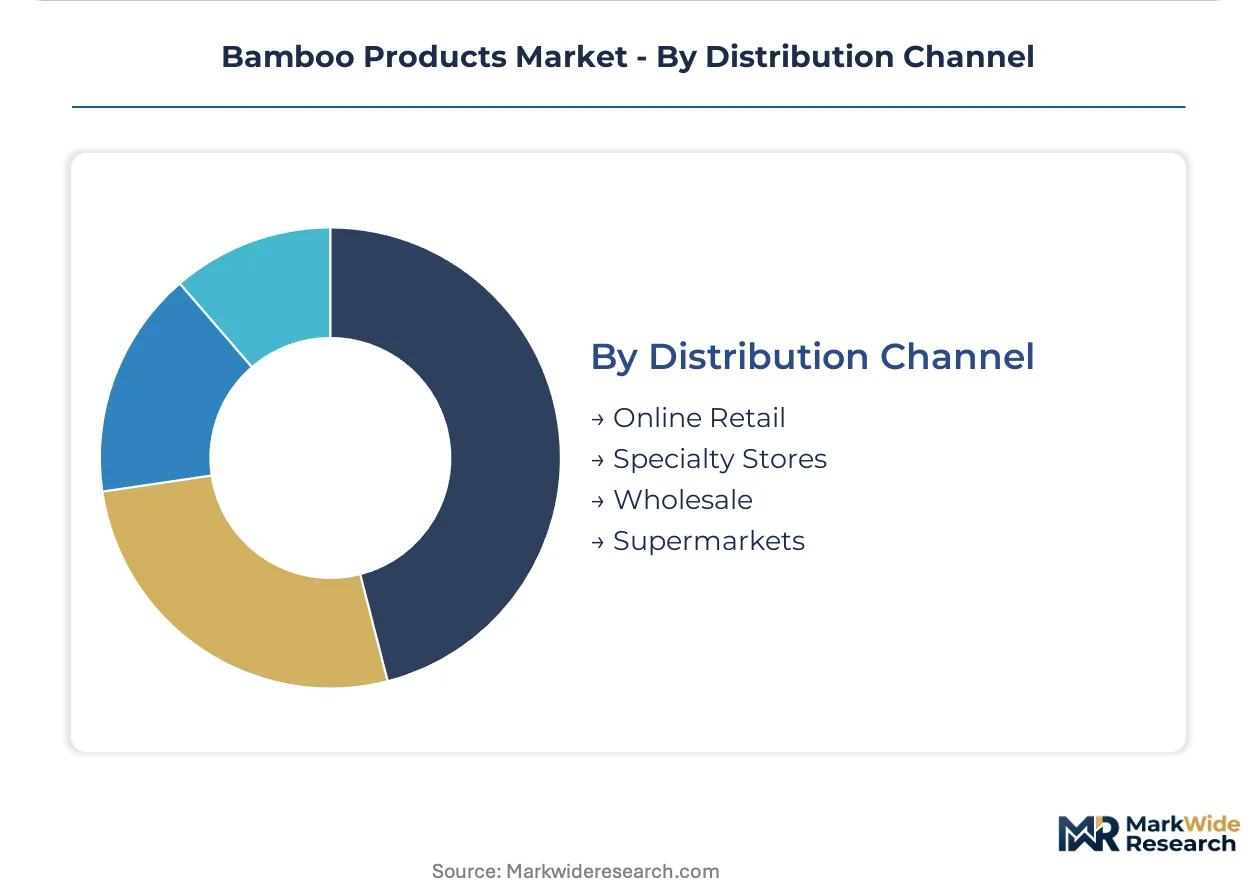
Distribution Channel:
Channel economics separate high-touch specification sales from transactional commodity flows.
- Online Retail:Direct-to-consumer platforms bypass traditional distributor markups for mid-scale residential developers in Germany and Netherlands.
- Specialty Stores:Installer network certification requirements concentrate purchasing power with asset managers.
- Wholesale:Volume consolidation favors plantation-to-factory traceability investments.
- Supermarkets:Mass-market kitchenware and small home goods compete on shelf price with synthetic alternatives.
Wholesale channels move the greatest product volume. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting engineered-bamboo production toward jurisdictions with streamlined certification pathways. Vietnam and Indonesia capture displaced capacity as Chinese exporters face compressed compliance timelines under revised GB standards.
China
Anhui and Jiangxi provinces control over sixty percent of industrial Moso supply, creating concentrated feedstock access for panel manufacturers. MIIT enforcement of GB/T 30364 density and swelling-rate thresholds is filtering low-capability producers from export eligibility. Factory upgrade windows are compressing as pre-certified lab partnerships become decisive for EU order capture.
Vietnam
Furniture exporters near Ho Chi Minh City supply European retailers under EUDR due-diligence protocols with minimized port lead times. Manufacturers cluster around port infrastructure to satisfy accelerated construction timelines for German and Dutch mid-rise developers. The export corridor is absorbing displaced orders from non-compliant Chinese competitors.
Germany
German housing associations pilot unbundled procurement models that separate material sourcing from installation warranties. Asset managers prioritize lifecycle carbon data over upfront material cost in social housing retrofits. Cross-laminated bamboo panel systems consolidate structural engineering acceptance through fire-rated performance testing for residential cores.
Netherlands
Dutch design hubs dominate premium European specification channels for flooring and interior finishes. Direct-to-contractor digital platforms bypass traditional distributor markups for mid-scale residential developers. Specification buyers concentrate purchasing power with asset managers who demand EPD transparency and plantation-to-factory traceability.
United States
EPA formaldehyde-emission standards under TSCA Title VI govern bamboo-composite panel imports, compelling overseas manufacturers to reconfigure resin formulations. North American commercial projects drive demand for FSC-certified strand-woven products. West Coast and Northeast metropolitan markets show disproportionate certification willingness among eco-conscious consumer segments.
Bamboo Products Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium specification channels favoring design-forward names while commodity flows concentrate among plantation-integrated producers. The vendor base organizes around three archetypes: vertically integrated plantation-to-factory operators, certification-focused specification specialists, and volume-driven flat-pack furniture exporters. Consolidation pressure is accelerating as carbon-border documentation requirements raise compliance fixed costs. Dominant competitive moves include captive plantation acquisition and third-party certification pre-positioning for EUDR market access.
Among Dutch-based branded specialists, MOSO International B.V. occupies a position exemplifying premium European channel dominance through design-hub proximity. Jiangxi Feiyu Bamboo Industry Group represents the plantation-integrated archetype with captive logistics spanning Anhui and Jiangxi supply zones. Smith & Fong Co. anchors the certification-specialist tier, with its name signaling North American commercial-market positioning around third-party verified supply chains.
| Leading Market Players |
|---|
| EcoPlanet Bamboo Group |
| Dasso Group |
| MOSO International B.V. |
| Jiangxi Feiyu Bamboo Industry Group |
| Anji Tianzhen Bamboo Flooring Co., Ltd. |
| Bamboo Village Company Limited |
| The Bamboo Company |
| Southern Bamboo Inc. |
| Smith & Fong Co. |
| Others |
Supply Flow & Price Mechanics
Family-owned plantation operators across Jiangxi and Anhui provinces anchor feedstock pricing through captive Moso supply, while private-equity-rolled-up flooring specialists in Vietnam exploit EUDR certification gaps to command premium realizations. Sovereign-backed industrial parks near Ho Chi Minh City compress logistics costs, enabling margin capture that eludes fragmented Chinese competitors facing MIIT compliance deadlines.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for European-bound engineered bamboo, compressing margins for uncertified Chinese exporters while rewarding plantation-to-factory traceability investments. Three-tier pricing structure across FSC-certified premium, GB-compliant standard, and spot-market economy levels separates specification buyers from mass-market retailers. Cost compression in strand-woven panel production is intensifying because phenol-formaldehyde resin prices track volatile petrochemical feedstocks. Commercial asset managers show least price sensitivity, prioritizing lifecycle carbon data over upfront material cost.
Supply Chain Analysis
Moso culm supply rests on concentrated plantation holdings in China, Vietnam, and Indonesia, with Anhui and Jiangxi provinces controlling over sixty percent of industrial feedstock. Phenol-formaldehyde resins, lyocell solvents for textile processing, and fire-retardant chemical treatments constitute critical input dependencies. Single-source vulnerability pervades the Anhui-Jiangxi supply zone, where weather shocks or MIIT enforcement disruptions cascade through global panel availability. Distribution runs through Ho Chi Minh City port clusters for EU furniture orders, Dutch design hubs for premium flooring specification, and direct-to-contractor digital platforms for German residential developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bamboo products market reads as a late-cycle quality story, with specification buyers unbundling material procurement from installation warranties and concentrating purchasing power with asset managers demanding EPD transparency and plantation-to-factory traceability.
For Market Incumbents: Acquire FSC-certified plantation assets in Vietnam and Indonesia before EUDR enforcement tightens feedstock eligibility. Deepen backward integration into captive resin formulation to buffer phenol-formaldehyde cost volatility. Defend against emerging Chinese competitors with pre-certified lab partnerships by locking exclusive installer network agreements in Netherlands and German social housing channels. For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms targeting mid-scale German and Dutch residential developers underserved by traditional distributor markups. Penetrate India's affordable housing segment ahead of BIS structural code revisions for non-timber materials. White-space exists in closed-loop lyocell textile production for premium apparel brand sourcing. For Investors and Strategic Acquirers: Valuations sit cheapest among plantation-integrated mid-caps with captive logistics spanning Anhui-Jiangxi supply zones and pre-certified EU lab partnerships. Long-term viability over a five-to-ten year window hinges on carbon-border adjustment mechanism positioning and biogenic carbon credential documentation. Watch MIIT enforcement timelines and EUDR due-diligence protocol expansion as inflection signals for capacity displacement from non-compliant competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Acquisition | Locks EUDR-compliant feedstock access ahead of traceability mandate expansion. |
| Pre-Certified Lab Partnership | Accelerates GB/T 30364 compliance timelines for EU order capture from displaced rivals. |
| Direct-to-Contractor Platform Launch | Bypasses traditional distributor markups for German and Dutch residential developers. |
| Closed-Loop Lyocell Investment | Positions bamboo textiles for premium apparel sourcing through solvent-recovery systems. |
| Installer Network Certification | Captures unbundled procurement value from Netherlands housing association pilots. |
Methodological Framework
Multiple input streams — executive interviews with plantation operators and flooring manufacturers, technical consultations with resin chemists and textile processors, and validation sessions with Dutch design-hub specification buyers — were reconciled against customs trade records, MIIT enforcement disclosures, and EUDR implementation guidance documents. Bottom-up volume estimates from individual facility capacities were triangulated with top-down demand projections derived from construction permit data and retail procurement patterns.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product type, end-user procurement behavior, application performance requirements, and distribution channel economics. CAGRs were derived through iterative convergence of supply-side capacity buildout schedules and demand-side specification shift trajectories. Forecast inputs incorporated GB/T standard revision compliance timelines, EUDR due-diligence protocol adoption curves, and carbon-border adjustment mechanism implementation signals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT enforcement acceleration or EUDR traceability mandate expansion scenarios. Assumptions reflect current regulatory trajectories and plantation yield stability. A small set of triggers — phenol-formaldehyde feedstock price spikes, Anhui-Jiangxi weather disruptions, and FSC chain-of-custody audit backlogs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Steel Processing Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Steel Cord Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Catalyst Bins Market