
 Fly Ash Market | 2026-2036
Fly Ash Market Size, Share, and Industry Trends Forecast 2026-2036
Fly Ash Market Intelligence
The adoption of asset-light business models for fly ash beneficiation and logistics is reconfiguring market access for regional suppliers. This shift allows smaller entities to compete without owning capital-intensive processing facilities. Global players like CEMEX S.A.B. de C.V. leverage their vast cement distribution networks to integrate fly ash. In contrast, specialists such as The SEFA Group differentiate through proprietary technologies for ash quality management. Holcim Ltd. operates a global sourcing and supply strategy to ensure consistent material for its concrete products.
Fly ash is a fine powder that results from the combustion of pulverized coal in electric power generation plants. It is a pozzolan, containing aluminous and siliceous material that, in the presence of water, chemically reacts with calcium hydroxide to form compounds with cementitious properties. Its primary purpose is as a supplementary cementitious material in concrete production. Class F fly ash, derived from bituminous coal, holds the dominant market share. The concrete admixtures application remains the largest end-use, valued for its ability to enhance durability and reduce permeability.
Regulatory frameworks are critical for market development and product acceptance. Standards such as ASTM C618 in the United States and EN 450 in Europe define the chemical and physical requirements for fly ash used in concrete. Similarly, China's GB standards govern its use in construction. These regulations ensure material quality and performance, building confidence among construction contractors and infrastructure developers. Navigating the decreasing supply from retiring coal-fired power plants while meeting these stringent quality standards is the central challenge for all participants.
Market Dynamics
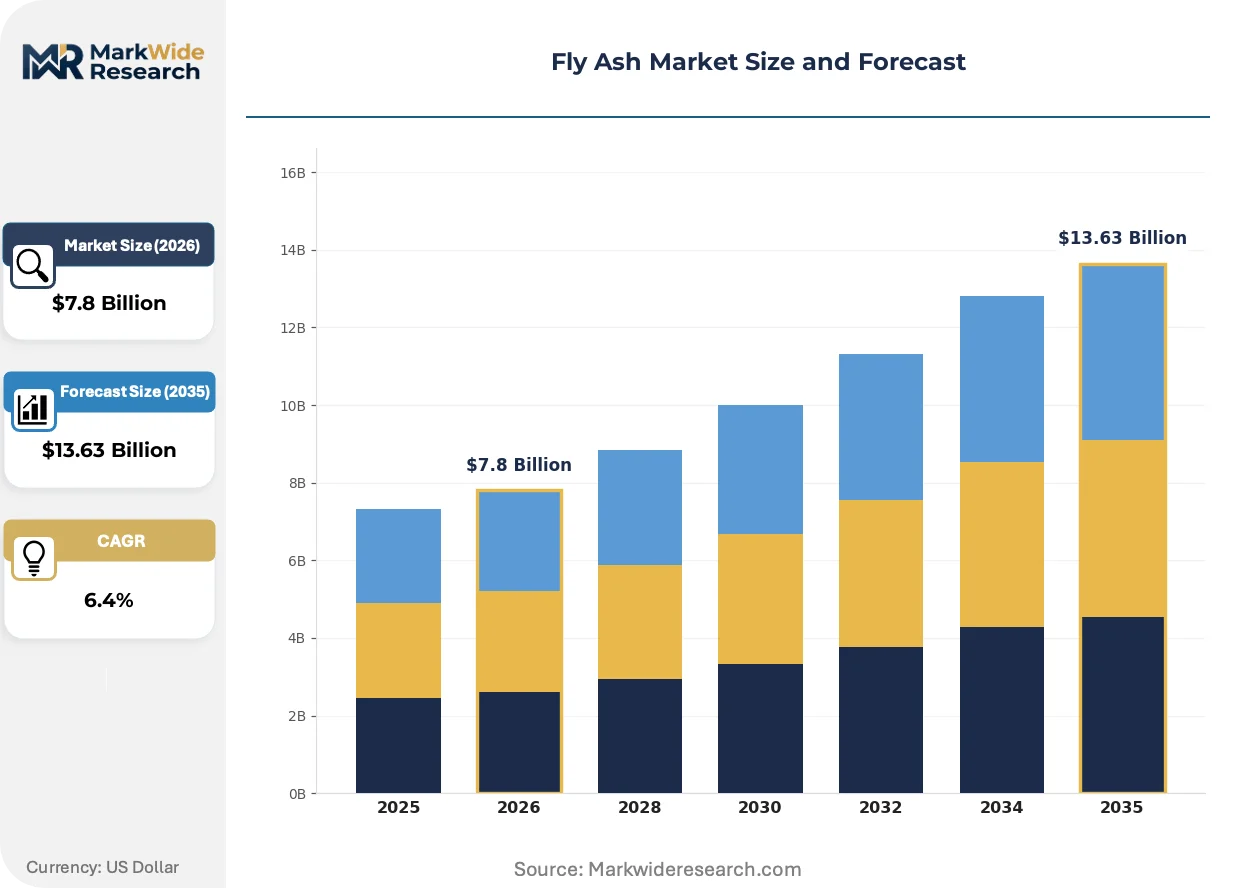
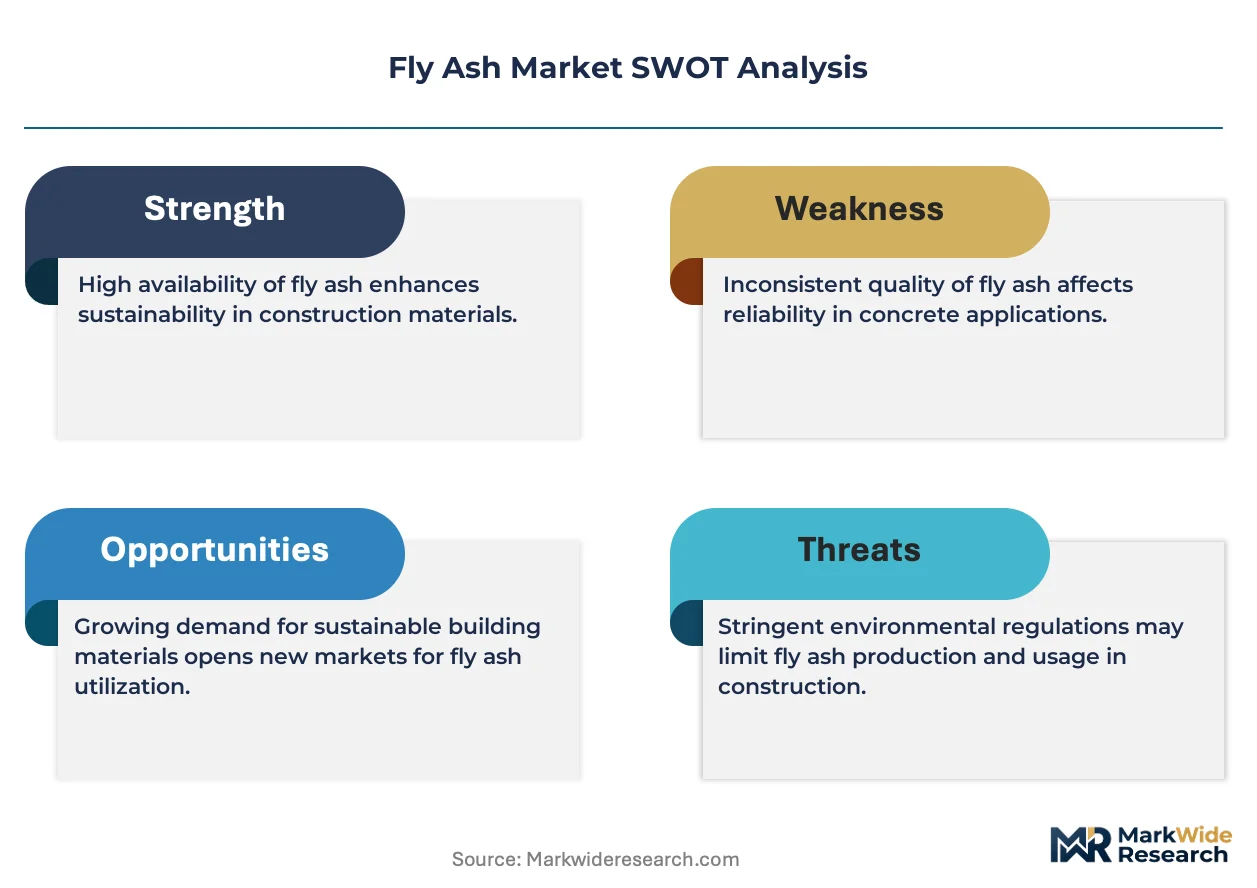
The market's central tension stems from the global energy transition. As nations phase out coal-fired power plants to meet decarbonization goals, the primary source of fly ash is diminishing, creating a supply constraint against a backdrop of rising demand from sustainable construction initiatives.
Growth Catalysts
- Sustainable Construction Mandates:Government-led green building codes and infrastructure projects, particularly in India, are specifying the use of supplementary cementitious materials to reduce the carbon footprint of concrete.
- Circular Economy Policies:China's dual carbon goals and Europe's circular economy action plan incentivize the recycling of industrial byproducts like fly ash, creating a strong policy-driven demand pull.
- Performance Enhancement in Concrete:The technical advantages of fly ash, such as improved workability, reduced permeability, and enhanced long-term strength, drive its adoption in high-performance and mass concrete applications.
Market Restraints
- Declining Coal Power Generation:The systematic closure of coal-fired power stations in Europe and the United States, driven by environmental policy, structurally constricts the primary source of raw fly ash supply.
- Inconsistent Material Quality:Fly ash exhibits significant variability in its chemical and physical properties based on coal source, often failing to meet stringent ASTM C618 or EN 450 standards without beneficiation.
- Substitution from Other SCMs:Ground granulated blast-furnace slag (GGBFS) and silica fume compete directly with fly ash for specification in concrete mixes, particularly in markets with active steel or silicon production.
Strategic Opportunities
- Harvesting Legacy Ash Deposits:Developing and deploying technologies for the reclamation and beneficiation of fly ash from historical landfills and ponds presents a significant new supply source.
- Expansion into Geopolymer Concrete:The use of fly ash as a primary aluminosilicate precursor for non-Portland cement-based geopolymer concrete offers a high-value, low-carbon alternative building material.
- Emerging Markets in Southeast Asia:Markets like Vietnam and Indonesia, with ongoing infrastructure development and active coal power fleets, offer growth potential as cement demand and sustainability awareness rise.
Industry Challenges
- Logistical Cost-to-Value Ratio:The high cost of transporting and storing a low-density powder limits the economically viable distribution radius from a power plant, creating regional supply-demand mismatches.
- Complex Quality Assurance:Ensuring consistent quality to meet divergent standards like ASTM C618 and EN 450 requires extensive, real-time testing and process control, adding operational complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fly Ash Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Class F, Class C, Silica Fume, Natural Pozzolan Application: Concrete Admixtures, Cement Production, Road Construction, Brick Manufacturing End User Industry: Construction Contractors, Infrastructure Developers, Cement Manufacturers, Brick Makers Form: Powder, Pelletized, Granulated, Activated |
| Companies Covered | Ashtech India Pvt. Ltd., Boral Limited, CEMEX S.A.B. de C.V., Charah Solutions Inc., Holcim Ltd., Salt River Materials Group, Titan America LLC, Eco Material Technologies, The SEFA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fly Ash Market Strategic Shifts & Innovations
The market is transitioning from managing a waste byproduct to engineering a consistent, value-added construction material. This evolution is driven by technological advancements in quality management and a re-evaluation of its role in a low-carbon built environment.
Real-time quality monitoring systems, integrating technologies like X-ray fluorescence (XRF), provide continuous analysis of fly ash chemistry. Beneficiation specialists and integrated cement producers are deploying these systems at processing hubs. This instrumentation is digitizing quality control, enabling precise blending to create a product meeting strict construction specifications.
India’s Ministry of Environment, Forest and Climate Change has mandated 100% utilization of fly ash from thermal power plants. This regulation shifts disposal responsibility to producers, compelling them to establish offtake agreements and develop end-markets. The cement and brick manufacturing sectors in India are most impacted, adapting production to absorb this mandated supply.
Concrete producers are increasingly procuring fly ash through specialized ash marketing providers rather than directly from power plants. This disintermediates the direct utility-to-user relationship, replacing it with a service model focused on quality assurance and logistics. The model is gaining traction in North America, where a fragmented supply landscape makes third-party aggregation essential.
Fly Ash Market Segmentation
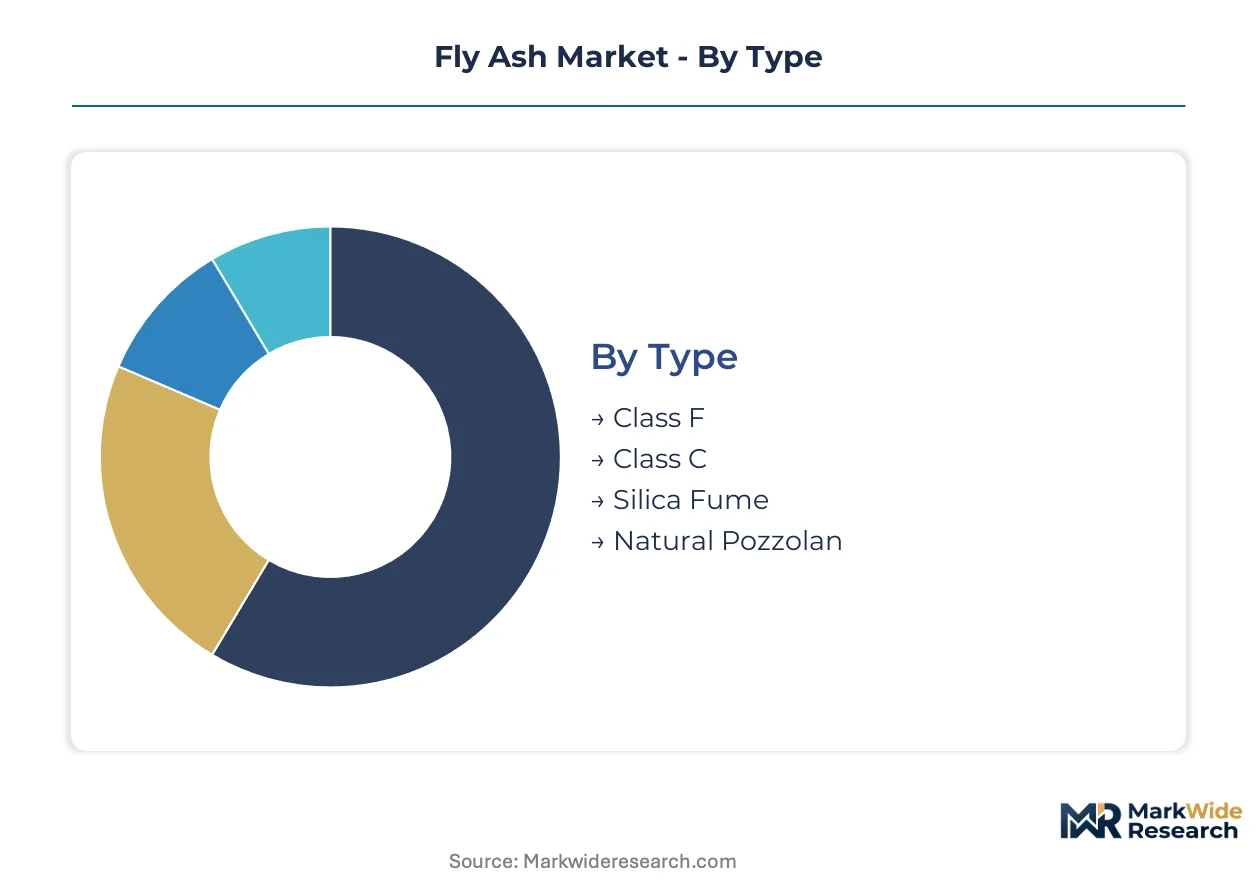
The Fly Ash Market segmentation reveals distinct product characteristics, application pathways, and end-user requirements that shape competitive dynamics. Understanding these categories is essential for participants to navigate supply constraints and capitalize on evolving demand patterns. Each segment presents unique opportunities for value creation and market penetration.
Type:
The various fly ash types exhibit different reactivity profiles and processing cycle times, influencing their suitability for diverse construction applications.
- Class F:This pozzolanic material results from the combustion of bituminous or sub-bituminous coal, containing less than 10% CaO. Its fine particle size and spherical shape enhance concrete workability and long-term durability. Demand for Class F fly ash concentrates in large-scale infrastructure projects requiring high-performance concrete in India and the United States.
- Class C:Originating primarily from lignite or sub-bituminous coal, Class C fly ash possesses both pozzolanic and cementitious properties due to its higher calcium oxide content (over 20%). This dual reactivity allows for self-cementing behavior when mixed with water. China's extensive road networks and building construction utilize Class C fly ash for its strength development.
- Silica Fume:A byproduct of silicon or ferrosilicon alloy production, silica fume is an amorphous pozzolan known for its extremely fine particles and high silica content.
- Natural Pozzolan:These are naturally occurring siliceous or siliceous and aluminous materials, such as volcanic ash or diatomaceous earth, which react with calcium hydroxide.
Class F fly ash anchors the volume base while Class C gains share at the steepest rate due to its broader reactivity.
Application:
Different applications for fly ash vary significantly in their volume requirements and technical specifications, driving distinct procurement strategies across the construction sector.
- Concrete Admixtures:Fly ash acts as a supplementary cementitious material in concrete, improving workability, reducing heat of hydration, and enhancing resistance to sulfate attack. This application remains the largest end-use, valued for its ability to enhance durability and reduce permeability in structures across Europe.
- Cement Production:Fly ash replaces a portion of clinker in cement manufacturing, leading to reduced CO2 emissions and lower production costs. Cement manufacturers in India integrate fly ash to meet sustainable construction mandates and optimize material composition.
- Road Construction:Fly ash stabilizes soil, serves as a sub-base material, and can be used in roller-compacted concrete for road pavements.
- Brick Manufacturing:Fly ash replaces clay in brick production, creating lighter, stronger, and more energy-efficient bricks for various building projects.
The market for Concrete Admixtures remains foundational, even as Cement Production applications expand rapidly.
End User Industry:
End-user industries for fly ash are differentiated by their project scale, material procurement practices, and direct influence on material specifications.
- Construction Contractors:These entities directly utilize fly ash in concrete mixes for various building projects, prioritizing consistent quality and reliable supply chains. Contractors in the United States often procure through specialized ash marketing providers to ensure material compliance.
- Cement Manufacturers:Cement producers integrate fly ash into their finished cement products, leveraging its pozzolanic properties to meet performance standards and reduce clinker content. Global players like Holcim Ltd. rely on fly ash for their concrete products.
- Infrastructure Developers:These organizations oversee large-scale public works projects, often specifying fly ash to meet sustainability goals and enhance project longevity.
- Brick Makers:Manufacturers of bricks and blocks incorporate fly ash to improve product properties and reduce raw material costs in their production processes.
While Construction Contractors represent the largest direct procurement, Cement Manufacturers influence broader material specifications in the market.
Form:
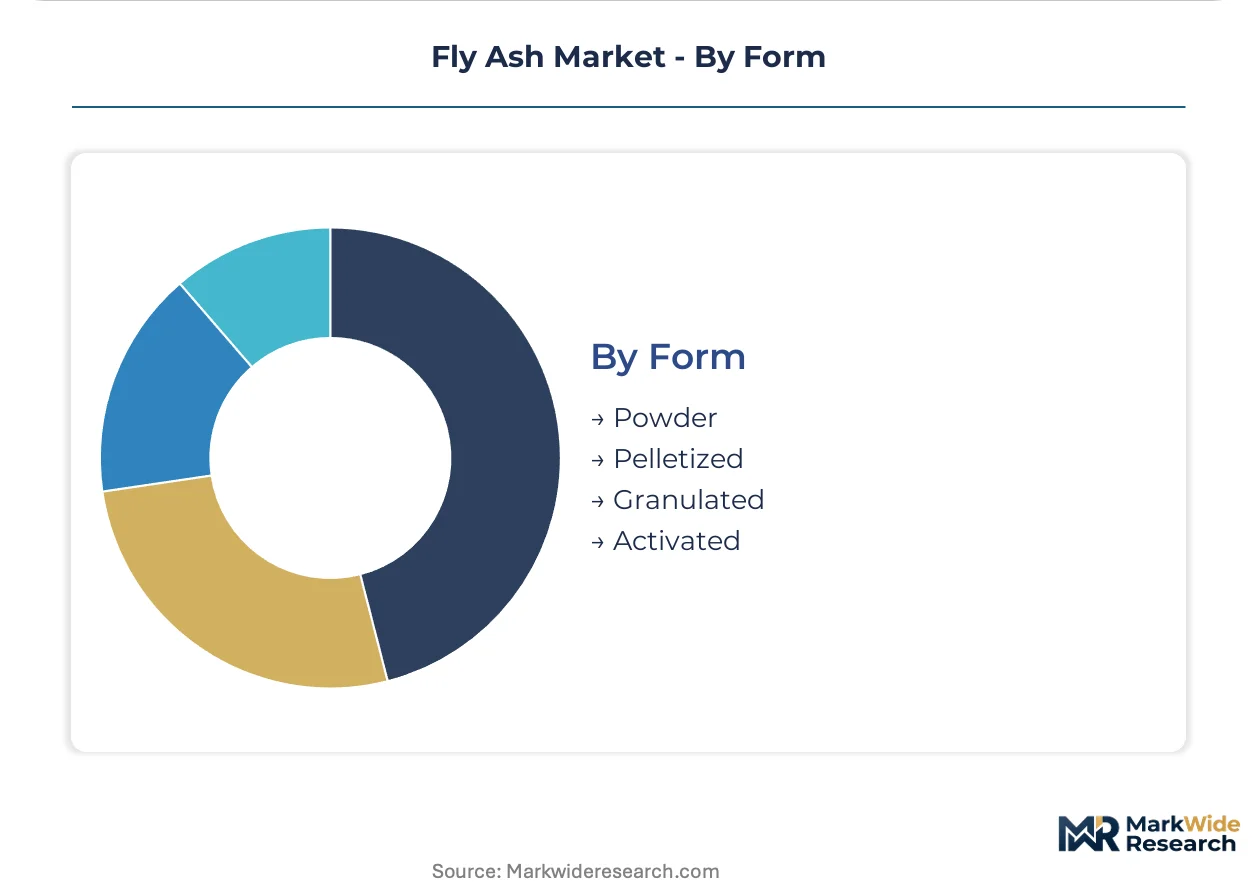
The physical form of fly ash dictates its handling, transportation logistics, and the specific processing required before end-use application.
- Powder:This is the most common and direct form of fly ash, collected dry from power plant precipitators, requiring careful storage and transport to prevent dusting. Powdered fly ash is widely used in concrete production for its fine particle size and reactivity.
- Granulated:Granulated fly ash involves processing the powder into larger, more stable particles, often through techniques like pelletization, which reduces dusting and improves handling. This form finds utility in applications where ease of handling and reduced environmental impact during transport are critical.
- Pelletized:Fly ash pellets are formed by agglomerating fine ash particles with a binder and water, creating a dust-free product suitable for bulk handling.
- Activated:Activated fly ash undergoes chemical or mechanical treatment to enhance its pozzolanic reactivity, making it suitable for specialized high-performance applications.
Standard Powder forms enable widespread utility, with specialized Activated products addressing niche performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and cement manufacturers form the core demand base for fly ash, driving regional market dynamics. These key buyer archetypes prioritize consistent material quality and reliable supply chains for their projects. India's robust infrastructure development and China's sustainable construction mandates significantly influence global fly ash consumption.
India
India's large-scale government-led infrastructure projects create substantial demand for sustainable construction materials. The Ministry of Environment, Forest and Climate Change mandates 100% utilization of fly ash from thermal power plants. Cement and brick manufacturing sectors in states like Maharashtra and Gujarat actively integrate this mandated supply.
China
China's extensive road networks and building construction utilize fly ash for enhanced strength development. The nation's dual carbon goals incentivize industrial waste recycling, creating favorable market conditions. Major construction hubs in the Yangtze River Delta region widely adopt Class C fly ash for its unique properties.
United States
US construction contractors widely adopt fly ash in concrete mixes for improved workability and durability. Standards such as ASTM C618 define stringent chemical and physical requirements for fly ash use. Specialized ash marketing providers in regions like the Pacific Northwest ensure material compliance for diverse projects.
Germany
German infrastructure developers specify fly ash to meet sustainability goals and enhance project longevity. Europe's circular economy action plan encourages the recycling of industrial byproducts like fly ash. Concrete admixture applications in urban centers like Berlin and Munich benefit from its performance enhancements.
Vietnam
Vietnam's ongoing infrastructure development and rising cement demand generate new opportunities for fly ash utilization. The government encourages sustainable construction practices within its national development plans. Active coal power fleets in regions like the Mekong Delta provide a consistent supply for local construction.
Fly Ash Market Key Industry Players
Channel-controlling players compete with product-specialist players in the fly ash market, creating a tiered competitive structure. Integrated cement manufacturers, specialized beneficiation providers, and ash marketing and logistics specialists represent the primary strategic archetypes. These diverse entities engage in distinct competitive strategies, ranging from global sourcing and distribution to localized quality management. Geographic expansion into emerging markets and proprietary technology development for advanced ash quality enhancement are dominant competitive moves across the industry.
Global cement manufacturers anchor a significant portion of the fly ash market. CEMEX S.A.B. de C.V., for instance, leverages its extensive cement distribution networks to integrate fly ash into its product offerings. Holcim Ltd. exemplifies this approach with its global sourcing and supply strategy, ensuring consistent material for its concrete products. Conversely, specialists like The SEFA Group differentiate through proprietary technologies for ash quality management, serving niche high-performance applications. These players collectively shape the market's supply dynamics and product standards.
| Leading Market Players |
|---|
| Ashtech India Pvt. Ltd. |
| Boral Limited |
| CEMEX S.A.B. de C.V. |
| Charah Solutions Inc. |
| Holcim Ltd. |
| Salt River Materials Group |
| Titan America LLC |
| Eco Material Technologies |
| The SEFA Group |
| Others |
Cost & Logistics Intelligence
Undercapacity in high-quality fly ash supply, driven by declining coal power generation, drives both supplier behavior and pricing posture. This structural shift encourages investment in beneficiation technologies while placing upward pressure on prices for certified material.
Pricing Analysis
Certification level, specifically compliance with ASTM C618 or EN 450 standards, creates the primary spread in fly ash pricing. The dominant pricing model involves contract-based long-term offtake agreements for consistent supply, complemented by spot market transactions for variable demand. Geographic delivery cost significantly influences final prices, reflecting the low density and high transport expense of fly ash. Pricing pressure stems from the diminishing supply of raw ash, despite rising demand from green construction mandates. Construction contractors, especially those working on large-scale infrastructure projects, exhibit the highest price sensitivity for bulk volumes.
Supply Chain Analysis
Energy transition policies, which restrict the long-term flow of coal-fired power generation, fundamentally constrain the fly ash supply chain. Supply concentration centers in countries with active coal fleets and high utilization mandates, such as India and China. The supply chain relies heavily on the continuous operation of thermal power plants for its raw material. A structural risk involves the inconsistent material quality of raw ash, necessitating costly beneficiation processes. Downstream distribution runs through specialized ash marketing providers and integrated cement manufacturers, who manage logistics and quality assurance for end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fly Ash Market presents a fragmentation opportunity, as sustainable construction mandates create distinct niches for specialized material and processing solutions.
For Market Incumbents: Pre-empt supply scarcity by strategically investing in the reclamation and beneficiation of legacy ash deposits. Secure long-term offtake agreements with remaining thermal power plants to stabilize raw material access. Leverage existing distribution networks to efficiently deliver consistent, quality-assured fly ash, mitigating the threat from inconsistent regional supply. Focus R&D on advanced beneficiation technologies to meet stringent quality standards like ASTM C618.
For New Entrants and Emerging Players: Build out specialized capabilities in ash beneficiation, particularly for processing inconsistent or legacy ash sources. Target emerging markets in Southeast Asia like Vietnam, where infrastructure development and active coal fleets provide growth potential. A viable go-to-market angle involves offering comprehensive quality assurance and logistics services, directly addressing the market's central challenge of material consistency. Focus on developing geopolymer concrete applications as a high-value, low-carbon alternative.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized ash marketing providers and beneficiation technology firms. The long-term viability of fly ash is anchored in its essential role for sustainable construction and circular economy initiatives. Identify acquisition targets with proprietary beneficiation technologies or established access to legacy ash reserves. A signal to watch is the increasing adoption rate of geopolymer concrete in large-scale infrastructure projects, indicating a shift towards higher-value fly ash applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Legacy Ash Reclamation | Secures new, long-term supply sources amidst declining fresh fly ash availability. |
| Develop Proprietary Beneficiation Technologies | Ensures consistent material quality to meet stringent construction specifications like EN 450. |
| Expand Geopolymer Concrete Applications | Unlocks high-value markets for fly ash as a primary binder in low-carbon construction. |
| Establish Global Sourcing and Distribution Networks | Mitigates regional supply-demand imbalances and logistical cost challenges for Holcim Ltd. |
| Integrate Real-time Quality Monitoring Systems | Digitizes quality control, enabling precise blending and material compliance for CEMEX S.A.B. de C.V. |
Research Approach
A standing panel of power plant operators, cement manufacturers, construction contractors, and ash marketing specialists provided ongoing calibration for market dynamics. This study combines insights from primary interviews with industry stakeholders and secondary validation through comprehensive data analysis. Key secondary sources include ASTM C618 and EN 450 standards, government infrastructure reports, and environmental agency publications. Bottom-up and top-down triangulation ensured robust data integrity.
The scenario-bracketing framing informed the analytical framework across the analysis window, accounting for potential shifts in market conditions. Segmentation dimensions modeled include fly ash type, application, end-user industry, form, and regional regulatory policies. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected future trends. Industry-specific forecast inputs included coal plant retirement schedules and infrastructure spending projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated cement producers or specialized beneficiation providers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological progression in alternative SCMs. Material shifts in global energy policy or unforeseen breakthroughs in geopolymer concrete technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Pultrusion Products Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Tooling Board Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Silica Fume Market
Industrial Materials
Asia-Pacific Wood Based Panel Market