
 GCC Heat Treating Market | 2026-2036
GCC Heat Treating Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Heat Treating Market Insights
AS9100-grade vacuum heat treatment is redrawing competitive boundaries across the GCC. SECO/WARWICK leverages its European furnace technology heritage to anchor premium aerospace contracts in the Emirates. Bodycote sustains market presence through geographic density across Saudi industrial cities. FTV Proclad (U.A.E.) dominates localized cladding and heat treatment integration for oilfield equipment refurbishment.
Heat treating encompasses controlled thermal cycles applied to ferrous and non-ferrous alloys to modify hardness, tensile strength, fatigue resistance, and microstructural grain boundaries through austenitizing, quenching, tempering, and case-hardening protocols. Vacuum heat treatment and nitriding command margin premiums for aerospace and defense end users demanding distortion-free surfaces and precise case depths. Tool steel and alloy steel product categories absorb the majority of value given their deployment in high-wear drilling, cutting, and forming applications across heavy machinery and energy sectors.
SASO mandates compliance with Gulf Standardization Organization (GSO) technical regulations for industrial heat processing equipment, while the Emirates Authority for Standardization and Metrology (ESMA) enforces CE-aligned safety protocols for imported furnace systems. These frameworks elevate capital requirements for new entrants and reinforce incumbent technical certification advantages. Stakeholders must monitor evolving national content requirements tied to Saudi Vision 2030 and UAE Operation 300bn as localization thresholds reshape supplier qualification criteria.
Market Dynamics
AS9100-grade vacuum heat treatment is redrawing competitive boundaries across the GCC. SECO/WARWICK leverages its European furnace technology heritage to anchor premium aerospace contracts in the Emirates. Bodycote sustains market presence through geographic density across Saudi industrial cities. FTV Proclad (U.A.E.) dominates localized cladding and heat treatment integration for oilfield equipment refurbishment.
Growth Catalysts
- Saudi Vision 2030 localization mandates:Domestic content thresholds are compelling international heat treaters to establish joint ventures with Saudi partners, accelerating capacity buildout in Jubail and Yanbu industrial zones.
- Aerospace outsourcing surge:Turbine component OEMs in the Eastern Province are divesting captive heat treatment assets, creating dedicated demand for third-party vacuum furnace services.
- Gas turbine refurbishment cycles:Aging installed base across Saudi Aramco and ADNOC facilities is driving recurring demand for precision nitriding and stress-relieving of power generation hardware.
Market Restraints
- Specialized alloy import dependency:Premium tool steels and nickel-based superalloys for aerospace applications remain sourced from European and Japanese mills, exposing processors to currency volatility and extended lead times.
- Equipment supplier concentration:High-specification vacuum furnace systems are dominated by SECO/WARWICK, Ipsen, and ALD Vacuum Technologies, limiting buyer negotiating leverage and service parts availability.
- SASO certification complexity:Gulf Standardization Organization technical regulations for industrial heat processing equipment impose multi-month approval timelines that delay greenfield project commissioning.
Strategic Opportunities
- Kuwait and Bahrain greenfield penetration:These markets currently lack AS9100-certified vacuum heat treatment capacity, creating first-mover advantage for qualified entrants establishing regional satellite facilities.
- Additive manufacturing post-processing convergence:Metal 3D-printed aerospace and medical components require specialized stress relief and hot isostatic pressing, opening adjacent service lines for incumbent heat treaters.
- UAE Operation 300bn industrial incentives:Federal funding for domestic manufacturing capability is subsidizing capital expenditure for heat treatment infrastructure serving defense and space verticals.
Industry Challenges
- Certified metallurgist scarcity:AS9100 and NADCAP audit requirements demand qualified personnel for process validation and documentation, yet GCC technical universities produce limited heat treatment specialists.
- Legacy furnace integration complexity:Established facilities in Dammam and Jebel Ali operate mixed-vendor equipment fleets, complicating unified process control software deployment and data traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Heat Treating Market |
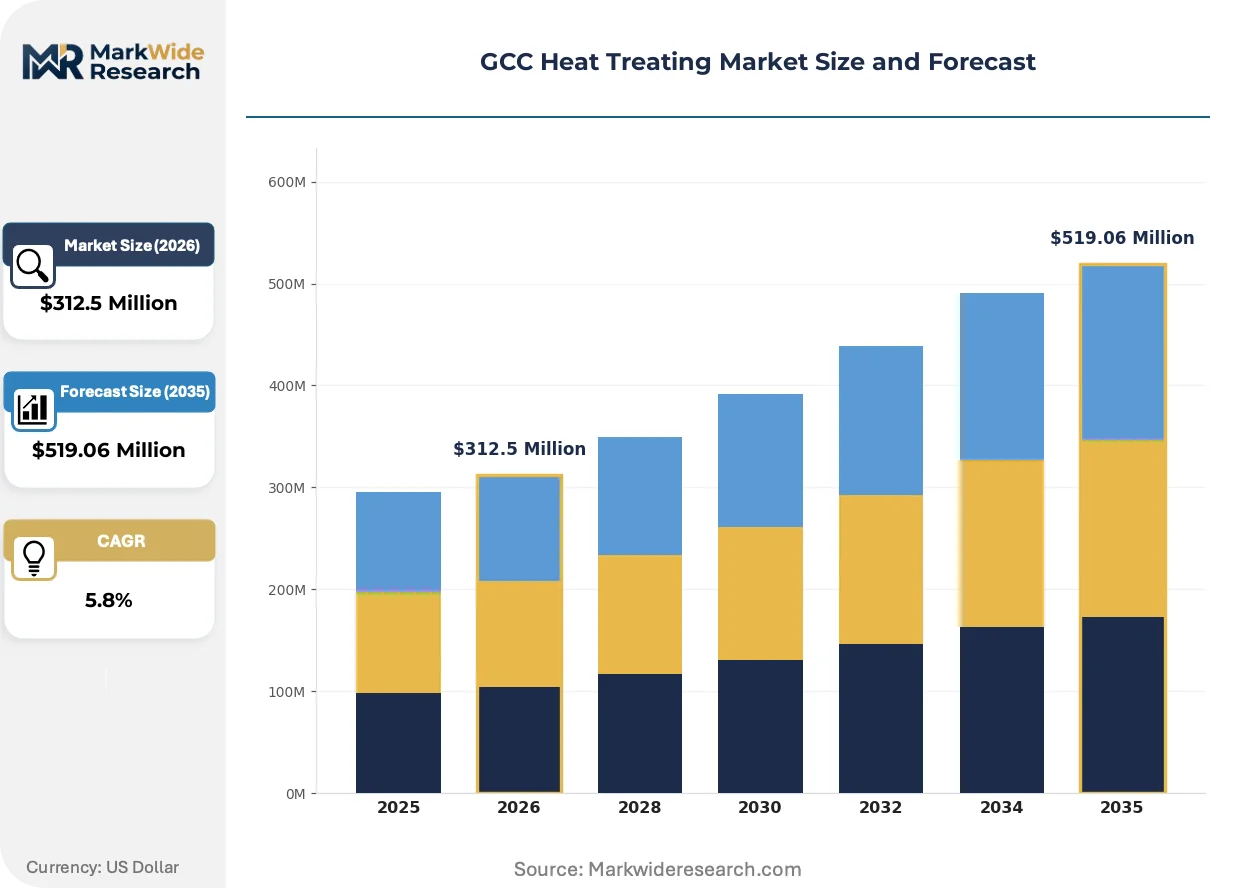
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Induction Heating, Flame Hardening, Vacuum Heat Treatment, Nitriding Product Type: Tool Steel, Alloy Steel, Carbon Steel, Stainless Steel End User: Aerospace, Automotive Component Manufacturers, Heavy Machinery, Defense Service Type: On-site Treatment, Custom Treatment, Batch Treatment, Mass Treatment |
| Companies Covered | General Metal Heat Treating, FTV Proclad (U.A.E.), Bluewater Thermal Solutions, SECO/WARWICK, Rawabi Holding, American Metal Treating, Bodycote, Nabertherm GmbH, East-Lind Heat Treat, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Heat Treating Market Trends and Innovations
Digital process monitoring and predictive maintenance systems are transforming quality assurance protocols across GCC heat treatment operations. Real-time thermal profiling and automated quench severity measurement are compressing certification cycles while reducing distortion rejection rates.
Low-pressure carburizing with high-pressure gas quenching is displacing conventional atmosphere carburizing with oil quenching in precision gear and bearing applications. Aerospace tier-one suppliers in Saudi Arabia's Eastern Province are specifying this technology for helicopter transmission components. The shift is displacing established atmosphere furnace operators unable to fund vacuum system upgrades, consolidating premium aerospace contracts among capital-rich incumbents.
ESMA's alignment of furnace safety standards with CE marking directives is elevating import compliance burdens for Asian equipment manufacturers. European-built systems now command preference in UAE tender evaluations due to pre-certified conformity. Medical device and aerospace segments are absorbing the highest compliance costs, passing through equipment premiums via long-term service agreements.
Integrated supplier-managed inventory programs are restructuring procurement relationships between heat treaters and their oilfield equipment customers. Saudi Aramco-approved processors in Jubail are assuming responsibility for customer-owned tooling storage, conditioning, and just-in-time processing rather than transactional batch scheduling. This model is most advanced in directional drilling component supply chains serving Saudi unconventional gas developments.
GCC Heat Treating Market Segmentation
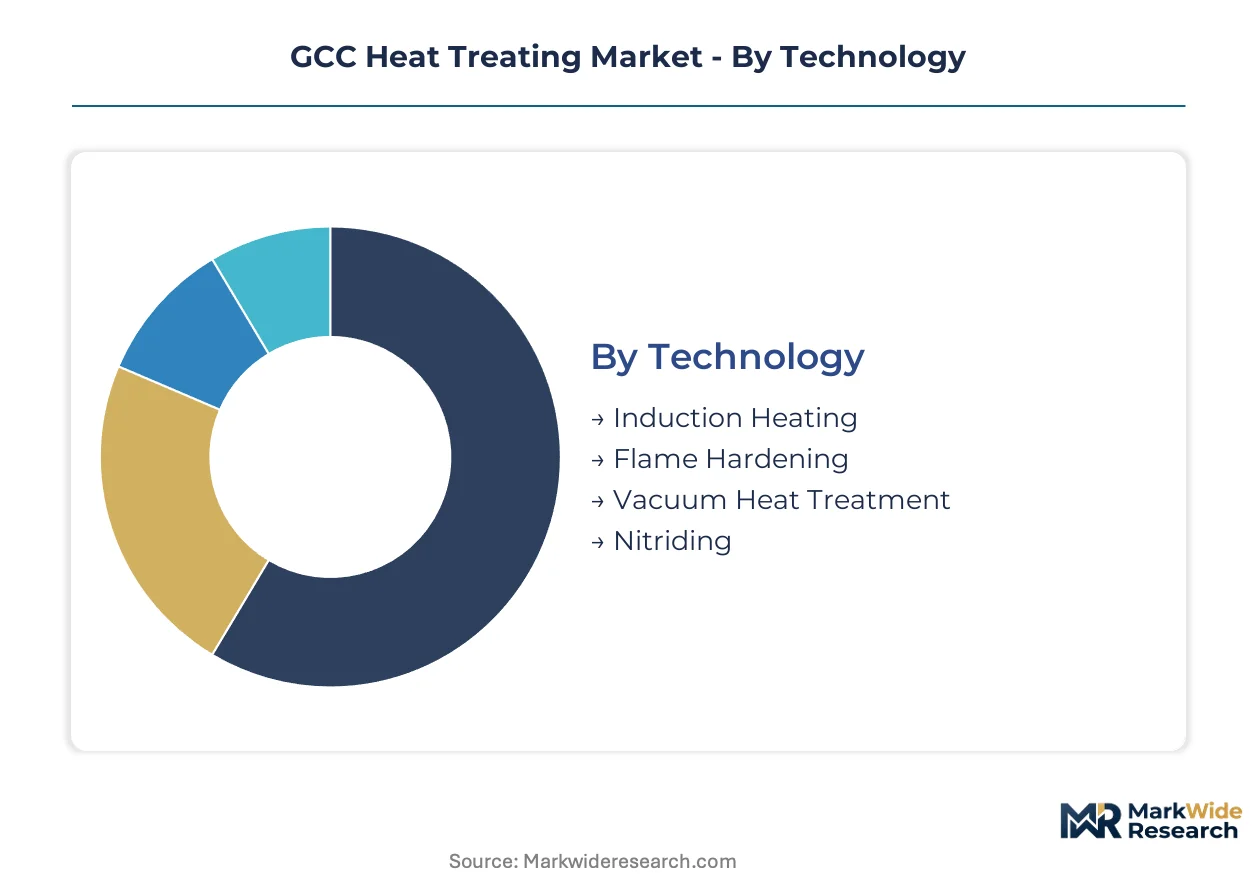
Technology and material specifications determine channel economics across GCC heat treatment procurement. Aerospace OEMs route high-value vacuum services through long-term agreements, while oilfield equipment suppliers favor flexible batch arrangements for irregular refurbishment cycles.
Technology:
Channel mix splits between captive in-house operations and third-party service bureaus, with premium aerospace work concentrating at specialized providers holding NADCAP accreditation.
- Vacuum Heat Treatment:AS9100-grade thermal processing eliminates oxidation and distortion through controlled atmosphere cycles. Saudi Arabia's Eastern Province aerospace cluster anchors demand as turbine OEMs divest captive assets. NADCAP audit requirements limit qualified suppliers to capital-rich incumbents.
- Nitriding:Surface hardening through nitrogen diffusion delivers precise case depths for power generation hardware. Aging gas turbine fleets across Saudi Aramco and ADNOC facilities drive recurring refurbishment contracts. Process validation documentation satisfies stringent OEM warranty terms.
- Induction Heating:Localized hardening of shaft and gear components serves automotive and heavy machinery sectors through job-shop networks.
- Flame Hardening:Cost-effective surface treatment for large-diameter rolls and cylinders dominates legacy steel mill maintenance.
Vacuum Heat Treatment dominates installed base value. Nitriding is where expansion concentrates as power generation refurbishment cycles accelerate.
Product Type:
Cost tiering separates premium alloy grades commanding process premiums from commodity carbon steels competing on throughput efficiency.
- Tool Steel:High-carbon, high-chromium alloys requiring precise austenitizing and triple tempering for cutting and forming applications. Dammam-Jubail manufacturing corridor absorbs volume for drilling equipment and plastic injection molds. SASO certification complexity elevates qualified processor margins.
- Alloy Steel:Nickel-chromium-molybdenum formulations balance toughness and wear resistance for heavy machinery powertrain components. Yanbu industrial zone demand concentrates around mining and construction equipment rebuild programs. Import dependency on European and Japanese mill sources constrains supply flexibility.
- Carbon Steel:General-purpose hardening and tempering serves construction and agricultural equipment through high-volume batch operations.
- Stainless Steel:Corrosion-resistant precipitation hardening supports medical device and food processing equipment applications with specialized cleanliness protocols.
Tool Steel commands margin premiums through technical complexity. Alloy Steel is climbing the fastest as mining equipment refurbishment expands.
End User:
Customer type determines service model, with aerospace and defense requiring dedicated quality systems while heavy machinery tolerates flexible scheduling.
- Aerospace:Turbine blade and transmission component processing demands vacuum heat treatment with full thermal profile traceability. Saudi Vision 2030 localization mandates are restructuring supplier qualifications toward joint venture structures. AS9100 and NADCAP certifications create substantial entry barriers.
- Defense:UAE Operation 300bn incentives are subsidizing domestic capability for armored vehicle and weapons system components. Federal funding streams favor capital expenditure on high-specification furnace infrastructure.
- Heavy Machinery:Mining, construction, and agricultural equipment rebuild programs drive cyclical demand for surface hardening and stress relieving.
- Automotive Component Manufacturers:Transmission gear and bearing applications are shifting toward low-pressure carburizing with high-pressure gas quenching for distortion control.
Aerospace dominates value concentration. Defense is where capacity investment concentrates under federal industrial policy.
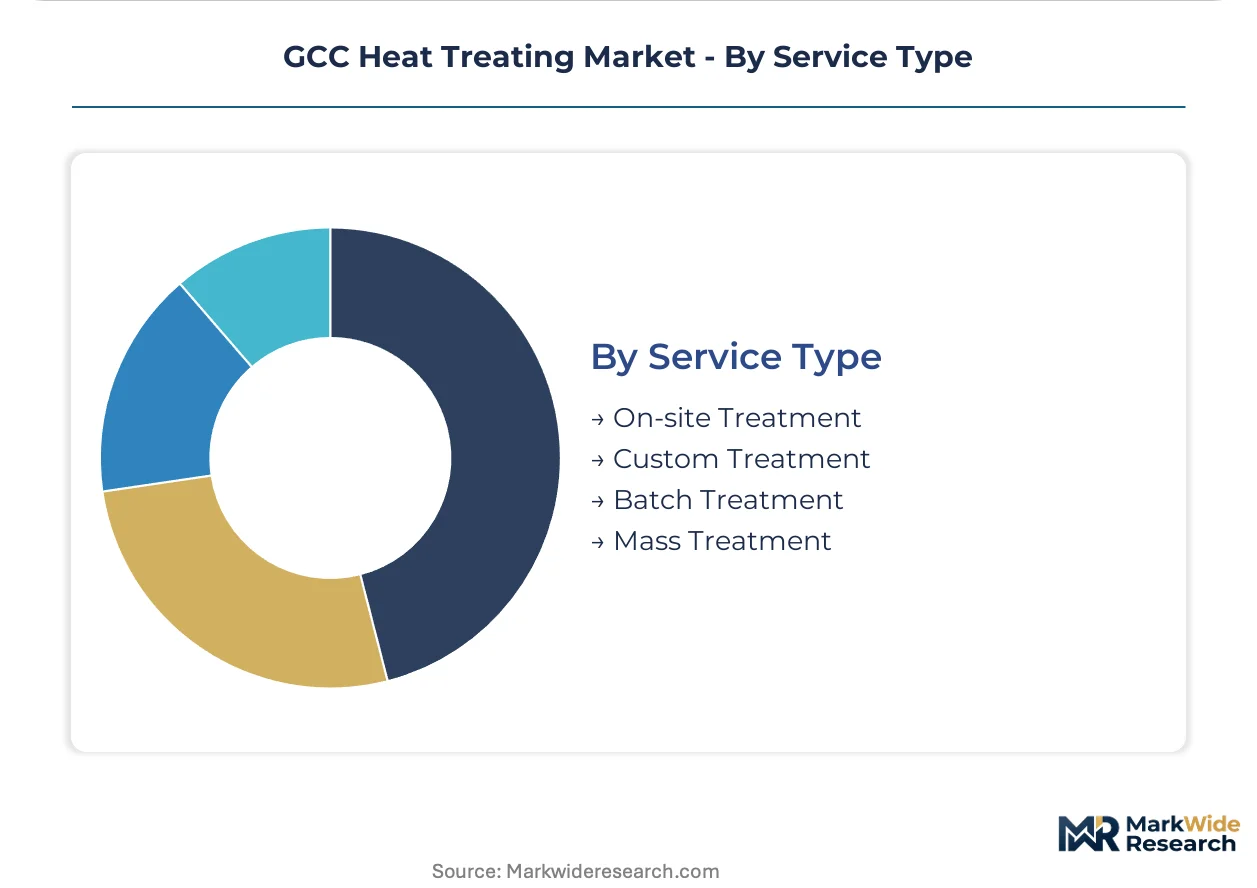
Service Type:
Volume scale and margin structure differentiate transactional batch processing from integrated supplier-managed inventory arrangements.
- Custom Treatment:Engineering-intensive protocols for prototype and low-volume aerospace components command premium pricing. Technical sales cycles extend six to twelve months with embedded process development. Saudi Aramco-approved processors in Jubail are advancing this model for directional drilling tooling.
- On-site Treatment:Mobile induction and flame hardening units serve infrastructure and ship repair at customer facilities. Port and pipeline maintenance contracts in Ras Al-Khair and Fujairah anchor regional deployment.
- Batch Treatment:Flexible scheduling accommodates irregular oilfield equipment refurbishment demand across mixed furnace capacities.
- Mass Treatment:High-throughput continuous furnace operations serve automotive fastener and construction hardware commoditized segments.
Custom Treatment dominates technical differentiation. On-site Treatment is gaining share fastest as infrastructure maintenance outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports precision heat-treated turbine components to European aerospace OEMs, while the UAE serves as the primary re-export hub for furnace equipment entering the wider Middle East and North Africa corridor.
Saudi Arabia
SASO certification mandates and Vision 2030 localization thresholds are restructuring supplier qualifications toward joint venture structures. The Eastern Province industrial corridor anchored by Jubail and Dammam manufacturing clusters concentrates demand for vacuum heat treatment of drilling equipment and aerospace components. Turbine OEMs in Ras Al-Khair are divesting captive heat treatment assets, creating dedicated third-party service demand.
United Arab Emirates
ESMA furnace safety standards aligned with CE marking directives are elevating import compliance burdens for Asian equipment manufacturers. Dubai and Abu Dhabi industrial zones absorb federal Operation 300bn subsidies for defense and space vertical heat treatment infrastructure. Jebel Ali manufacturing clusters host the region's densest concentration of NADCAP-accredited vacuum furnace capacity.
Kuwait
Absence of AS9100-certified vacuum heat treatment capacity creates first-mover advantage for qualified entrants establishing regional satellite facilities. The country's national industrial development authority is soliciting foreign investment for specialty metals processing capabilities. Al-Zour refinery expansion and associated petrochemical maintenance programs are generating latent demand for precision nitriding services.
Bahrain
Underdeveloped heat treatment infrastructure relative to neighboring industrial economies presents greenfield penetration opportunities for accredited operators. The national oil and gas holding company's maintenance procurement is shifting toward integrated supplier-managed inventory models. Sitra industrial area and Askar fabrication yards represent concentrated demand nodes for oilfield equipment refurbishment cycles.
Qatar
North Field gas expansion megaprojects are driving procurement of specialized stress-relieving capacity for subsea pipeline components. The national standardization body is drafting technical regulations for industrial heat processing equipment that mirror SASO frameworks. Ras Laffan industrial city maintenance yards are outsourcing legacy flame hardening operations to specialized third-party providers.
GCC Heat Treating Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and capital intensity dimensions, producing a bifurcated structure where premium aerospace contracts concentrate at NADCAP-accredited incumbents while commodity batch processing fragments across regional job shops. European furnace technology heritage confers decisive advantage in high-specification vacuum system procurement evaluations. Three archetypes dominate: capital-rich integrated service bureaus, equipment-anchored technology licensors, and oilfield-specialized cladding integrators. Competitive dynamics center on strategic partnerships with national oil companies and capacity expansion into certification-scarce neighboring markets.
Within the technology-licensor tier, SECO/WARWICK represents European furnace heritage penetration into Emirates aerospace procurement, while Bodycote occupies a position exemplifying geographic density strategies across Saudi industrial cities. FTV Proclad anchors the oilfield-specialized archetype through localized cladding and heat treatment integration for equipment refurbishment cycles. These three entities collectively illustrate how certification accumulation, geographic proximity to demand clusters, and vertical service bundling constitute the primary vectors of competitive differentiation across GCC procurement evaluations.
| Leading Market Players |
|---|
| General Metal Heat Treating |
| FTV Proclad (U.A.E.) |
| Bluewater Thermal Solutions |
| SECO/WARWICK |
| Rawabi Holding |
| American Metal Treating |
| Bodycote |
| Nabertherm GmbH |
| East-Lind Heat Treat |
| Others |
Pricing and Supply Chain Analysis
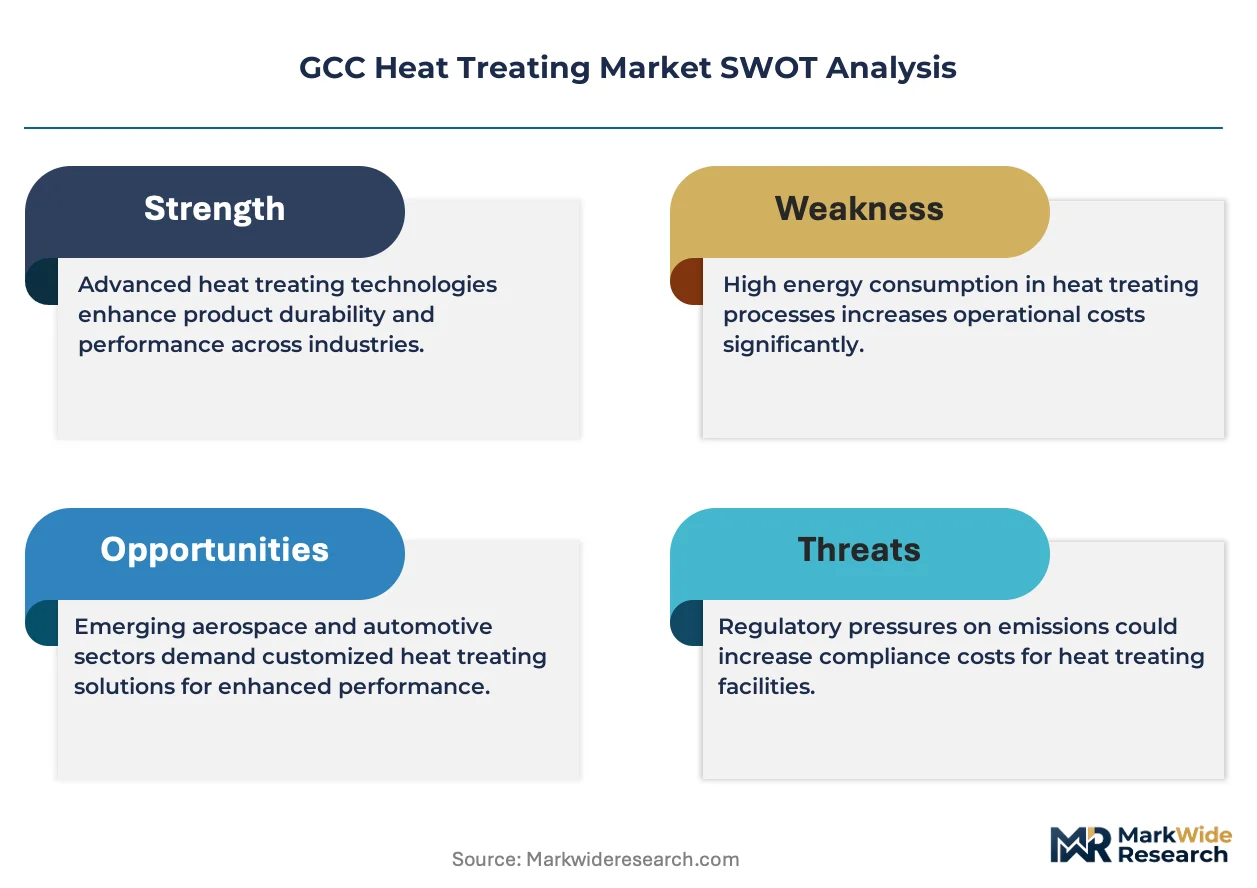
Ninety-day European mill lead times for premium tool steels and nickel-based superalloys compress inventory buffers across Saudi and UAE processors, amplifying pricing power for NADCAP-accredited incumbents while exposing commodity operators to margin erosion from spot market volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across GCC heat treatment procurement. Three-tier pricing structure across NADCAP-premium, AS9100-standard, and uncertified-economy levels separates aerospace turbine work from oilfield batch processing. Pricing pressure stems from European furnace equipment premiums and SASO certification delays that extend commissioning timelines. Defense and aerospace OEMs exhibit lowest price sensitivity given warranty liability exposure, while construction hardware distributors drive hardest bargain negotiations.
Supply Chain Analysis
Germany, Austria, and Poland anchor high-specification vacuum furnace system fabrication for GCC import demand. Critical inputs draw from Japanese and European specialty alloy mills, SECO/WARWICK and Ipsen equipment licensors, and regional industrial gas suppliers. Single-source vulnerability concentrates in AS9100-grade vacuum chamber components with no qualified Asian alternatives. Distribution runs through Jebel Ali re-export hub for wider MENA corridor penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where NADCAP and AS9100 certification moats compound over multi-year audit cycles, creating switching costs that cement incumbent positioning.
For Market Incumbents: Shield aerospace contract retention by embedding supplier-managed inventory programs at Saudi Aramco and ADNOC maintenance yards. Expand vacuum furnace capacity in Ras Al-Khair before turbine OEM captive divestiture peaks. Deepen backward integration into European alloy mill partnerships to compress ninety-day lead time exposure.
For New Entrants and Emerging Players: Anchor in Kuwait and Bahrain where AS9100-certified vacuum capacity absence creates first-mover whitespace. Target Al-Zour refinery expansion nitriding demand and Sitra fabrication yard oilfield refurbishment cycles. Pursue joint venture structures with national industrial development authorities to satisfy localization thresholds.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum heat treatment infrastructure as European CE-aligned equipment premiums widen. Five-to-ten year viability favors processors with embedded aerospace OEM relationships and multi-certification stacking. Acquisition target archetype: NADCAP-accredited mid-cap operators in certification-scarce geographies. Signal to watch: SASO approval timeline compression indicating regulatory maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| NADCAP Accreditation Investment | Unlocks Saudi Aramco and ADNOC turbine component contracts under OEM warranty terms. |
| European Equipment Supplier Partnership | Secures CE-pre-certified vacuum furnace procurement advantage in ESMA-aligned UAE tenders. |
| Kuwait Greenfield Facility Establishment | Captures first-mover premium in AS9100-vacuum-scarce market before competitor entry. |
| Supplier-Managed Inventory Program | Transforms transactional batch relationships into embedded directional drilling tooling partnerships. |
| Additive Manufacturing Post-Processing Line | Addresses metal 3D-printed aerospace component stress relief demand from Saudi Eastern Province cluster. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with heat treatment plant managers, aerospace OEM procurement leads, national oil company maintenance directors, and European furnace equipment suppliers; and secondary validation through SASO technical regulation filings, ESMA safety standard alignments, SEC 10-K disclosures of listed processors, and customs import records for vacuum furnace systems. Bottom-up capacity modeling across Jubail, Dammam, Jebel Ali, and Ras Al-Khair industrial zones triangulated against top-down GCC manufacturing output projections.
Across the projection horizon, the analytical framework segmented volume and value outputs by technology tier, material specification, end-use vertical, and service model intensity. CAGRs derived from equipment installation pipelines, aerospace outsourcing announcement tracking, and power generation refurbishment cycle timing. Industry-specific forecast inputs incorporated Saudi Vision 2030 localization threshold announcements and UAE Operation 300bn federal funding disbursement patterns.
Material uncertainties — alloy import tariff shifts, SASO certification timeline variability, and aerospace OEM captive divestiture acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions around regulatory stability and equipment supplier delivery reliability. Recalibration cycles align with material shifts in national content requirements and NADCAP audit standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Cork Material Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Fly Ash Market
Industrial Materials
Injection Molding Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Plastic Injection Mold Market