
 Infant Formula Ingredients Market | 2026-2036
Infant Formula Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Formula Ingredients Market Intelligence
Dairy processing consolidation in Europe and New Zealand is restructuring the supply base for whey and milk proteins. Fonterra Co-operative Group Limited leverages its extensive milk pool to supply foundational ingredients at scale. In contrast, Royal FrieslandCampina N.V. focuses on value-added ingredients like lactoferrin. Glanbia plc competes through its advanced protein hydrolysate solutions for specialized hypoallergenic formulas.
Infant formula ingredients are purified nutritional components assembled to nutritionally replicate human breast milk. Formulations adhere to strict compositional profiles, including specific whey-to-casein protein ratios and the addition of lipids like docosahexaenoic acid (DHA). While carbohydrates and proteins constitute the bulk of ingredient volume, lipids and probiotics represent high-value segments. Standard formulas drive overall consumption, but the hypoallergenic and organic formula applications are expanding rapidly and offer higher margin potential for ingredient suppliers.
The US FDA and the European Food Safety Authority (EFSA) establish stringent compositional mandates for all formulas sold in their jurisdictions. In parallel, China's State Administration for Market Regulation (SAMR) imposes its own unique GB standards, creating a complex compliance landscape for global suppliers. To secure future growth, ingredient producers must generate robust clinical evidence for novel bioactives like HMOs to gain regulatory approval and differentiate their portfolios.
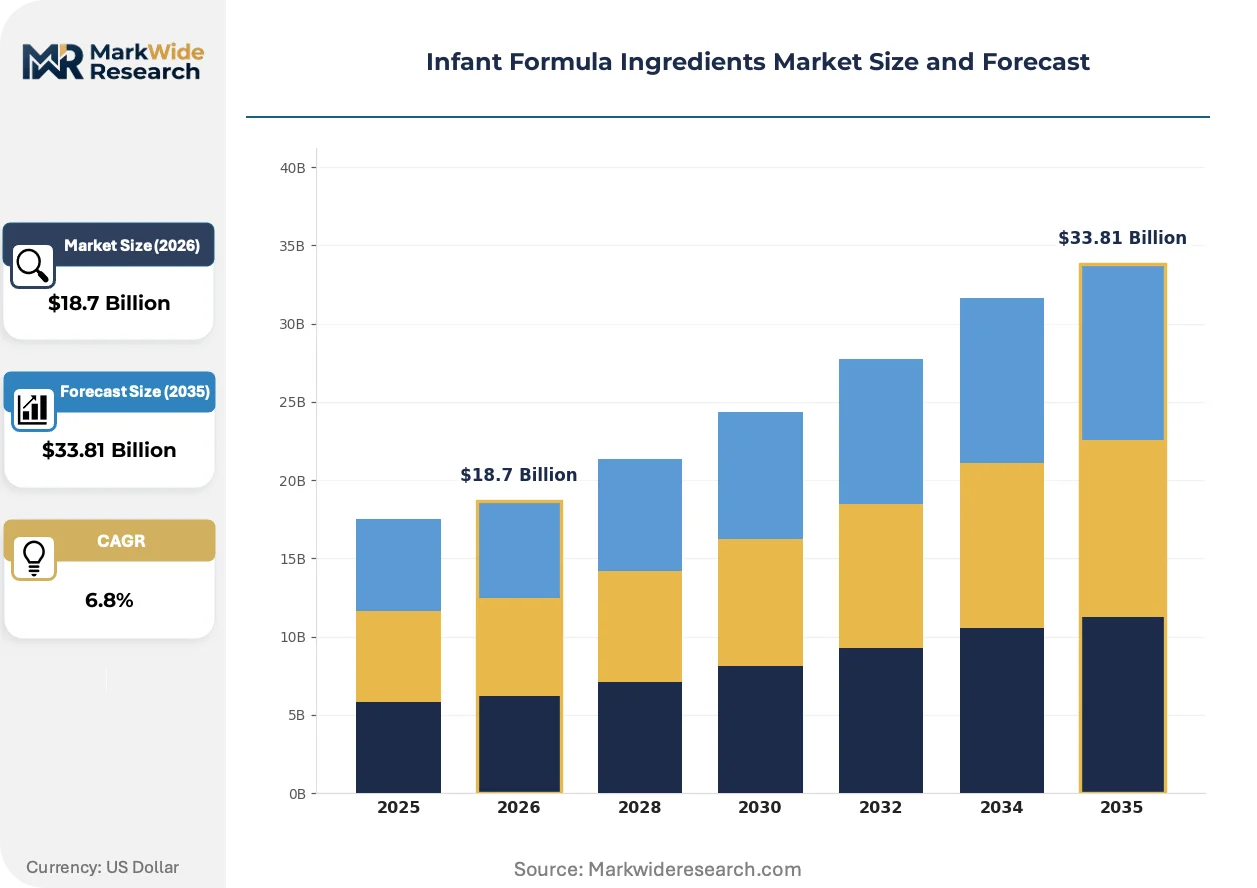
Market Dynamics
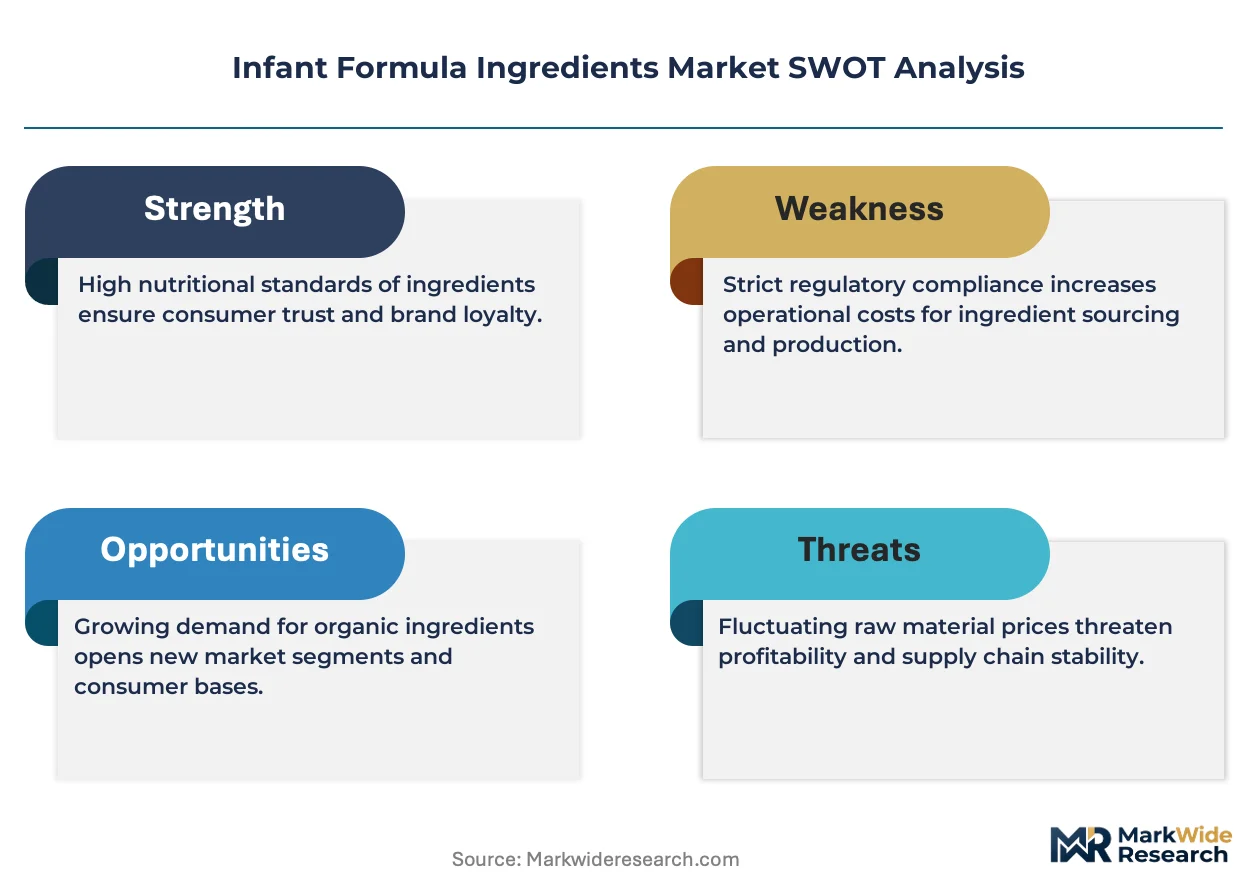
The central force shaping the market is the bifurcation of demand, driven by China's stringent GB standards and consumer preference for premium, clinically-validated ingredients. This pressure forces suppliers to maintain both high-volume standard ingredient lines and high-margin specialty portfolios.
Growth Catalysts
- Fortification with Bioactives:The incorporation of functional ingredients like Human Milk Oligosaccharides (HMOs) into mainstream formulas to support infant gut health and immunity is a primary catalyst, driven by new clinical evidence.
- Premiumization in China:Evolving consumer preferences and demographic shifts in China are fueling demand for specialized and premium ingredients, particularly advanced protein hydrolysates and lipids like docosahexaenoic acid (DHA).
- Specialty Formula Expansion:The growing incidence of allergies and digestive sensitivities supports the expansion of the hypoallergenic formula segment, creating demand for highly purified whey and casein hydrolysates.
Market Restraints
- Input Cost Volatility:The market is subject to price fluctuations for foundational dairy commodities, particularly whey and milk proteins, due to weather events, feed costs, and dairy processing consolidation in Europe and New Zealand.
- Divergent Regulatory Frameworks:A complex compliance landscape, with differing compositional mandates from the US FDA, Europe's EFSA, and China's SAMR, increases R&D costs and time-to-market for new ingredients.
- Concentrated Supply Base:The supply of foundational milk and whey proteins is concentrated among a few large dairy cooperatives, creating dependency and limiting the bargaining power of many formula manufacturers.
Strategic Opportunities
- Novel Bioactive Development:There is significant opportunity in isolating and commercializing novel bioactive compounds beyond HMOs, such as lactoferrin and specific probiotics, backed by robust clinical trials to prove efficacy and gain regulatory approval.
- Plant-Based Formulations:Developing plant-derived ingredients, such as hypoallergenic rice or pea protein hydrolysates and algae-based DHA, offers a pathway to serve niche markets for vegan or dairy-intolerant infant nutrition.
- Organic Ingredient Expansion:Meeting rising demand for certified organic ingredients in markets across North America and Europe provides a clear avenue for value-added growth, particularly for carbohydrates, proteins, and lipids.
Industry Challenges
- Clinical Validation Timelines:The extensive and costly clinical trials required by regulators like EFSA and the FDA to substantiate the safety and benefits of novel ingredients represent a significant operational hurdle for innovators.
- Global Traceability Management:Ensuring end-to-end traceability and quality control for sensitive ingredients like probiotics and DHA across complex, multi-country supply chains is a persistent and capital-intensive challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Formula Ingredients Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Proteins, Carbohydrates, Lipids, Vitamins, Minerals, Probiotics Formulation Technology: Hydrolyzed, Concentrated, Powdered, Liquid Concentrate, Spray-Dried, Encapsulated Application: Standard Formula, Hypoallergenic Formula, Organic Formula, Preterm Formula, Toddler Formula End User: Manufacturers, Pediatric Clinics, Nutritional Centers, Retailers, Hospitals |
| Companies Covered | Arla Foods amba, Fonterra Co-operative Group Limited, Royal FrieslandCampina N.V., AAK AB, Carbery Food Ingredients Limited, Glanbia plc, DSM-Firmenich, Cargill, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Formula Ingredients Market Strategic Shifts & Innovations
Precision science is guiding ingredient innovation, moving the industry beyond basic nutritional replication toward functional parity with human milk. The focus is on incorporating specific bioactive components that offer clinically proven health benefits, such as improved immunity and cognitive development.
Human Milk Oligosaccharides (HMOs) are complex prebiotics designed to support gut health and immunity. Premium and specialty infant formula segments are rapidly adopting these bioactives to differentiate their products. This focus on functional bioactives is absorbing research and development investment that was previously directed toward optimizing basic nutritional components like standard proteins and fats.
Updated regulations from China's State Administration for Market Regulation (SAMR) are reshaping formulation strategy. The GB standards impose stricter requirements on ingredient sourcing, nutritional ranges, and the number of formulas a company can register. The specialty hypoallergenic formula category is particularly impacted, as suppliers must now provide more extensive clinical data to substantiate claims.
Consumer demand for transparency is driving a clean-label movement within infant formula ingredients. This shift favors components with clear sourcing, organic or non-GMO certifications, and minimal processing, disrupting the traditional procurement focus on cost alone. This trend is most visible in North America and Europe, influencing ingredient selection for carbohydrates and lipids.
Infant Formula Ingredients Market Segmentation
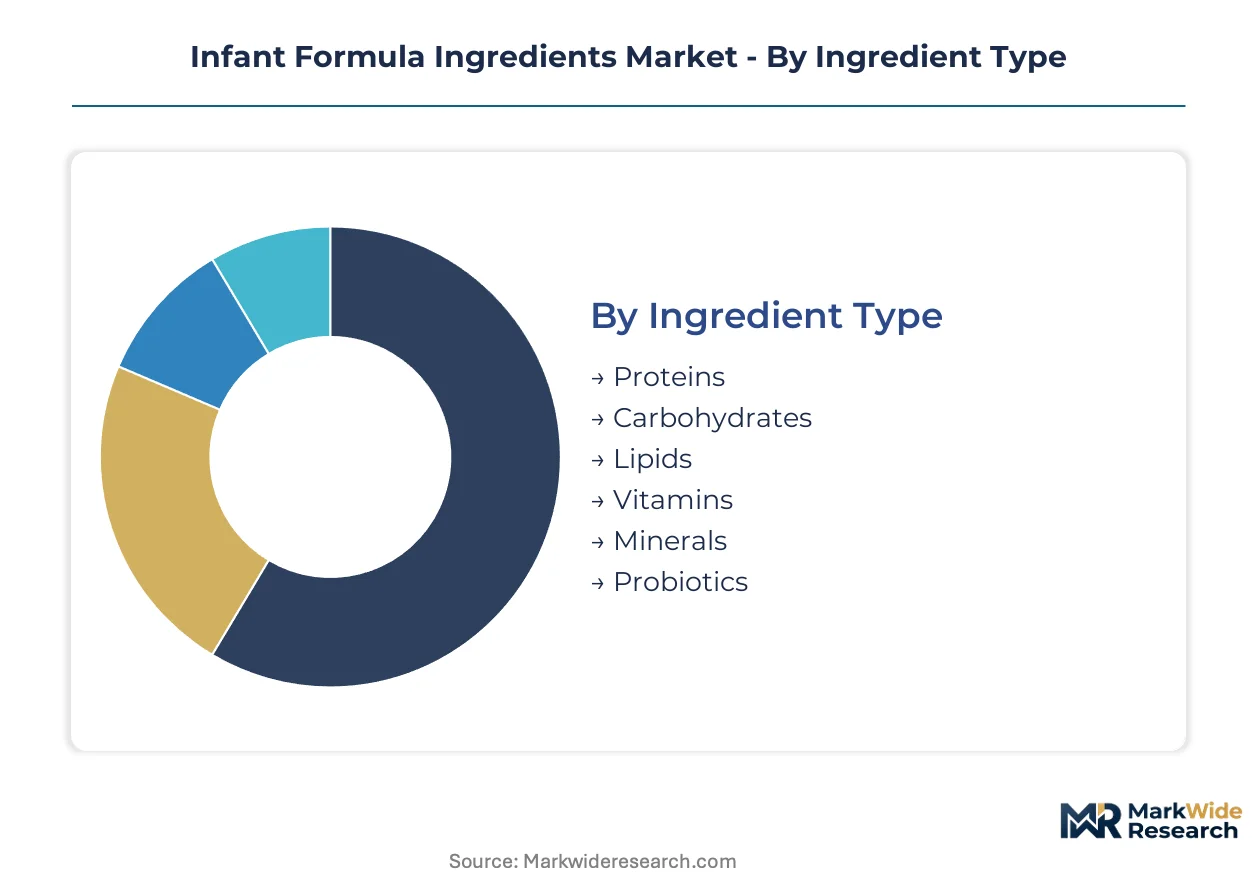
The infant formula ingredients market segments based on distinct compositional and functional attributes, reflecting the varied nutritional needs and regulatory requirements across global jurisdictions. Understanding these delineations is crucial for ingredient suppliers to align product development with evolving consumer preferences and clinical demands.
Ingredient Type:
Buyers in this category differentiate based on the core nutritional function and bioactivity required for specific formula types, balancing cost with efficacy and regulatory compliance.
- Proteins:These foundational macronutrients include whey and casein, often supplied as concentrates or isolates, with advanced protein hydrolysates catering to specialized hypoallergenic formulations. Demand for specialized protein forms is concentrating in China due to evolving dietary preferences and increased focus on infant gut health.
- Lipids:Essential fatty acids like docosahexaenoic acid (DHA) and arachidonic acid (ARA) are critical for neurological development, sourced from algae or fish oil, and are high-value components. Global demand for these high-purity lipids is accelerating, particularly in premium formula segments across North America and Europe.
- Carbohydrates:Lactose is the primary carbohydrate source, replicating human milk, while maltodextrin and corn syrup solids provide alternative energy sources in specialized formulas.
- Vitamins:A broad spectrum of essential vitamins, including A, D, E, K, and B-complex, are added to ensure comprehensive nutritional profiles as mandated by regulatory bodies like the US FDA and Europe's EFSA.
- Minerals:Iron, calcium, zinc, and selenium are vital micronutrients incorporated to support bone development, immune function, and overall growth in infants.
- Probiotics:Live microorganisms, such as Bifidobacterium and Lactobacillus strains, are included to support gut microbiome development and immune health, often alongside prebiotics like Human Milk Oligosaccharides (HMOs).
Volume sits with Proteins; growth tilts toward Probiotics.
Formulation Technology:
The cost tier of ingredients often correlates with the complexity of their processing and the functional benefits derived from specific formulation technologies.
- Hydrolyzed:Proteins are broken down into smaller peptides or amino acids, significantly reducing allergenicity, making them essential for hypoallergenic formulas. The market for hydrolyzed proteins is expanding rapidly, driven by the rising incidence of infant allergies.
- Powdered:This is the most prevalent and cost-effective form for bulk ingredients, offering extended shelf life and ease of transport for global distribution. Powdered ingredients are critical for the mass production of standard infant formulas.
- Concentrated:Ingredients like whey protein concentrate retain a higher percentage of non-protein components compared to isolates, offering a balance of purity and cost-effectiveness.
- Liquid Concentrate:These forms offer convenience for manufacturers requiring precise dosing and reduced processing steps, though they typically have shorter shelf lives than powdered alternatives.
- Spray-Dried:A common method for converting liquid ingredients into a stable powder, preserving nutritional integrity and improving solubility for reconstitution.
- Encapsulated:This technology protects sensitive bioactives like probiotics and DHA from degradation, ensuring their stability and efficacy through processing and storage.
The application of advanced formulation technologies directly impacts the stability and bioavailability of sensitive ingredients in finished products.
Application:
The volume of ingredients consumed is largely determined by the specific formula application, with standard formulas representing the largest segment while specialized categories show dynamic expansion.
- Hypoallergenic Formula:Designed for infants with cow's milk protein allergy or digestive sensitivities, these formulas rely on extensively hydrolyzed proteins and specialized lipids. Demand for these formulas is expanding most quickly in markets like Europe and North America due to increased allergy diagnoses.
- Organic Formula:These formulas use ingredients certified to organic standards, appealing to consumers seeking non-GMO and minimally processed options. The organic formula segment is gaining share fastest in premium markets, particularly in Germany and the United States.
- Standard Formula:This category encompasses basic infant nutrition for healthy, full-term infants, constituting the largest share of ingredient volume.
- Preterm Formula:Formulated with higher protein, calorie, and mineral content to support the rapid growth and development needs of premature infants.
- Toddler Formula:Designed for children aged 12-36 months, these formulas supplement a diversified diet with essential nutrients, often containing different protein and carbohydrate ratios than infant formulas.
Manufacturers are adapting ingredient portfolios to meet the specific nutritional and regulatory demands of each formula type.
End User:
The type of customer purchasing infant formula ingredients directly influences procurement patterns and the desired scale and specification of supply.
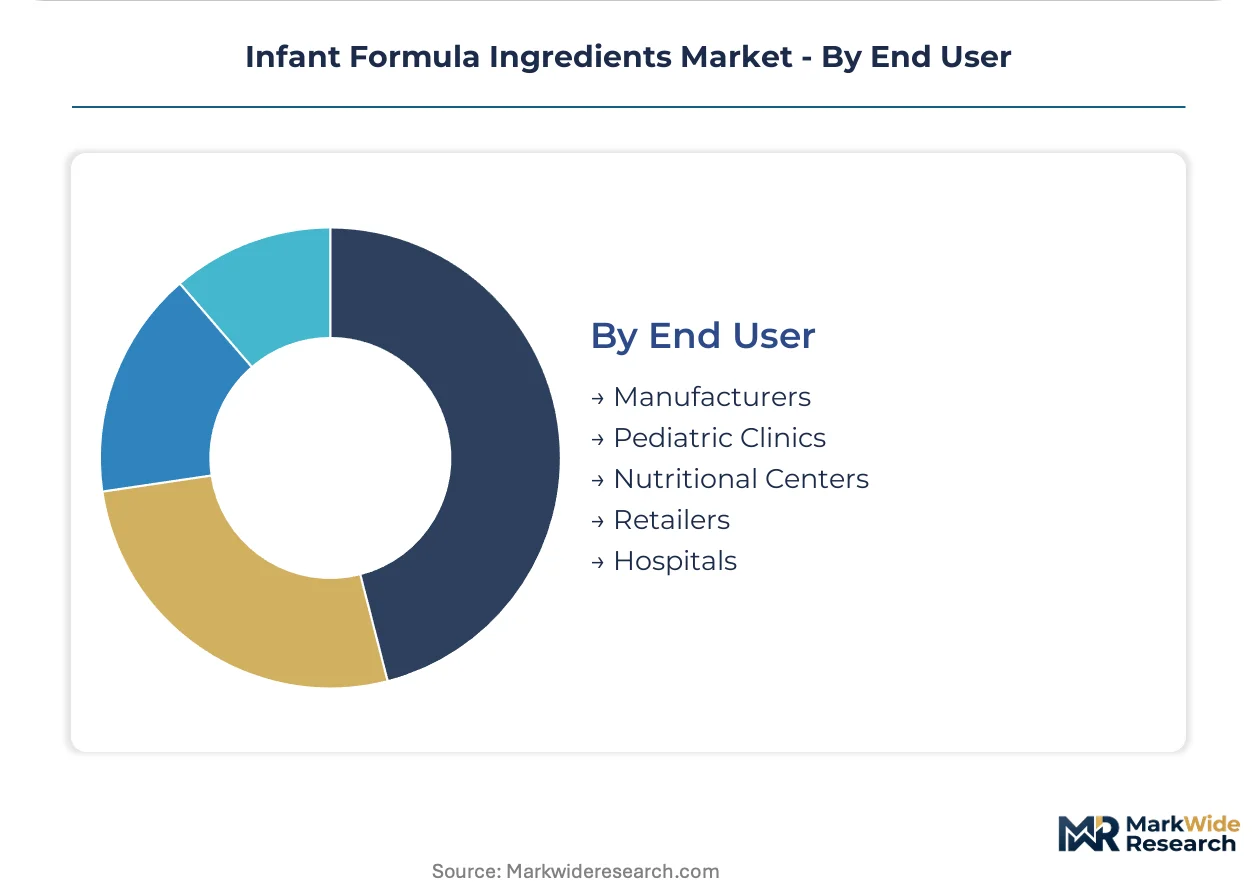
- Manufacturers:Large-scale infant formula producers represent the primary end-users, procuring vast quantities of ingredients for their production lines. These entities demand consistent quality, robust supply chains, and adherence to strict regulatory standards like China's GB standards.
- Retailers:While not direct ingredient buyers, retailers influence demand by stocking various finished formula brands and types, indirectly driving manufacturer ingredient requirements. Retailers prioritize product diversity and consumer-preferred certifications.
- Pediatric Clinics:These healthcare facilities often recommend specific formula types to parents, influencing demand for specialized ingredients and formulations.
- Nutritional Centers:Similar to clinics, these centers provide guidance on infant feeding, impacting the selection of formulas and, consequently, ingredient demand.
- Hospitals:Hospitals use infant formulas for newborns and infants requiring specialized care, often procuring directly from manufacturers or through distributors.
High-margin opportunities are concentrating with manufacturers developing specialized and premium formula lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's extensive dairy farming infrastructure anchors a significant portion of the global infant formula ingredients supply. This region provides foundational milk and whey proteins, critical for diverse formula applications. Ingredient innovation in Europe often focuses on value-added components like specialized hydrolysates and novel bioactives.
United States
Demand for premium and organic infant formula ingredients drives market activity. The US FDA mandates strict compositional profiles and safety standards for all formulas sold within its jurisdiction. California's food processing clusters actively research plant-based protein alternatives and specialized lipids for infant nutrition.
China
China's evolving consumer preferences for specialized and premium ingredients fuel ingredient demand. The country's SAMR GB standards impose stringent requirements on ingredient sourcing and formulation for market entry. Shanghai's advanced food science parks are hubs for developing and testing novel bioactives like Human Milk Oligosaccharides (HMOs).
Germany
The market for organic and hypoallergenic infant formulas is expanding due to consumer health consciousness and increased allergy diagnoses. EFSA regulations influence ingredient approval and compositional requirements across the European Union. Bavaria's dairy industry focuses on high-quality whey protein production for specialized infant formula applications.
New Zealand
Its robust dairy sector positions New Zealand as a major supplier of foundational milk and whey proteins to global markets. The country's food safety authorities ensure strict quality control for dairy exports, maintaining product integrity. Auckland's research institutions collaborate with Fonterra on advanced ingredient processing technologies and product development.
France
Demand for specialized protein hydrolysates and probiotic-fortified formulas is notable in the French market. European food safety regulations, including those from EFSA, govern ingredient formulation and claims within the country. Brittany's agricultural regions support dairy production, supplying raw materials for advanced ingredient manufacturing facilities.
Infant Formula Ingredients Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-margin specialty and bioactive ingredient segments. The market exhibits a tiered structure, with large dairy cooperatives providing foundational ingredients at scale, while specialized firms focus on value-added components like advanced protein hydrolysates and novel bioactives. This bifurcation creates distinct competitive arenas. Strategic partnerships to co-develop novel ingredients and portfolio diversification into plant-based alternatives are common competitive moves, alongside capacity expansion to meet rising demand for premium formulations.
Among the scaled dairy cooperatives, Fonterra Co-operative Group Limited exemplifies a major supplier leveraging extensive milk pools for foundational ingredients like whey and milk proteins. Royal FrieslandCampina N.V. represents a producer focused on value-added components such as lactoferrin and specialized protein fractions, catering to premium segments. Glanbia plc sits within the segment providing advanced protein hydrolysate solutions for specialized hypoallergenic formulas, demonstrating a clear focus on high-margin applications and clinical efficacy. These entities anchor different parts of the ingredient supply chain, from bulk commodities to highly refined bioactives.
| Leading Market Players |
|---|
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| Royal FrieslandCampina N.V. |
| AAK AB |
| Carbery Food Ingredients Limited |
| Glanbia plc |
| DSM-Firmenich |
| Cargill |
| Ingredion Incorporated |
Cost & Logistics Intelligence
A distinct bifurcation between standard and specialized ingredients drives pricing and supply chain strategies in the infant formula ingredients market. This divergence manifests in cost structures and supplier relationships, reflecting varied production complexities and regulatory hurdles.
Pricing Analysis
Service-level agreements often bundle technical support and regulatory guidance with specialized ingredient purchases, reflecting a value-based pricing model. Contract-based long-term offtake agreements dominate foundational ingredient procurement, particularly for whey and milk proteins. Price differentiation stems from certification levels, such as organic or non-GMO status, and the extent of clinical validation for novel bioactives like Human Milk Oligosaccharides (HMOs). Pricing pressure stems from input cost volatility for foundational dairy commodities, affecting standard formula segments most acutely. Manufacturers of hypoallergenic and premium formulas exhibit lower price sensitivity due to the specialized nature of their products.
Supply Chain Analysis
Single-source vulnerability sits with specialized bioactive suppliers, particularly for clinically validated Human Milk Oligosaccharides (HMOs) and advanced protein hydrolysates. Geographic supply concentration centers on Europe and New Zealand for foundational dairy proteins, while China's evolving demand shapes premium ingredient flows. The market draws from key inputs such as milk proteins, whey, and algae/fish oil for docosahexaenoic acid (DHA). Commodity price volatility for dairy represents a significant structural risk across the supply chain. Distribution runs through direct sales channels from ingredient producers to infant formula manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infant formula ingredients market is witnessing a vertical-integration race, with players pursuing upstream control over foundational dairy ingredients to secure consistent supply and quality.
For Market Incumbents: Lock in long-term supply agreements for foundational whey and milk proteins to mitigate input cost volatility. Invest heavily in research and development for novel bioactives, such as lactoferrin and specific probiotic strains, to counter margin pressures from emerging plant-based alternatives. Expand production capacity for advanced protein hydrolysates in key regions like Europe to meet rising demand for specialized formulas. Secure robust clinical validation for new ingredient claims to maintain competitive advantage against new entrants.
For New Entrants and Emerging Players: China's SAMR GB standards open a window for specialized ingredient suppliers that can meet stringent quality and clinical data requirements. Target niche markets for plant-based or organic infant nutrition, focusing on hypoallergenic rice or pea protein hydrolysates and algae-based DHA. Penetrate markets in North America and Europe by emphasizing clean-label certifications and sustainable sourcing practices. Go-to-market strategies should leverage digital platforms for direct engagement with formulators and emphasize transparent ingredient provenance.
For Investors and Strategic Acquirers: Re-rating potential sits with agile specialty ingredient producers given the sustained demand for premium and clinically validated bioactives. The market offers consistent growth over the long term, driven by evolving consumer preferences and scientific advancements in infant nutrition. Identify mid-cap firms specializing in novel bioactives or advanced formulation technologies as prime acquisition targets. A key signal to watch is the regulatory approval of new functional ingredients in major markets like the EU and China, indicating future growth segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Substantiates efficacy claims for novel bioactives like HMOs, gaining regulatory approval and market trust. |
| Capacity Expansion for Hydrolysates | Addresses the rising demand for hypoallergenic formulas, particularly in European and North American markets. |
| Strategic Partnership for Plant-Based Ingredients | Diversifies product portfolios and taps into niche markets for vegan or dairy-intolerant infant nutrition. |
| Regulatory Approval Pathway Acceleration | Ensures timely market entry for new ingredients, navigating complex compliance landscapes across jurisdictions. |
| Certification Investment for Organic Ingredients | Meets consumer demand for clean-label products, driving premiumization in North America and Europe. |
Research Approach
Multi-period observation of ingredient consumption trends and regulatory shifts anchored the trend analysis, supplemented by interviews with industry experts. This study integrated insights from R&D directors, procurement managers, regulatory affairs specialists, and marketing leads from infant formula manufacturers. Secondary data sources included US FDA filings, EFSA scientific opinions, China SAMR announcements, and company annual reports. Bottom-up market sizing and top-down validation ensured data consistency and accuracy across the analysis.
An input-output matrix determined market projections, segmenting the infant formula ingredients market by ingredient type, formulation technology, application, and end-user. This analytical framework also considered regional consumption patterns and regulatory frameworks across the modeling period. Compound annual growth rates were derived from historical data analysis and projected demand drivers over the projection horizon. Key industry-specific forecast inputs included infant birth rates and regulatory updates from EFSA.
The model assumes a particular technology adoption path; alternative pathways for plant-based proteins would alter the outlook for ingredient mix. Forecasts reflect assumptions regarding economic stability and consumer behavior across the analysis window. Unforeseen shifts in consumer preferences or changes in global trade policies could revise forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Standard Milk Formula Market