
 Hypo Anti Allergic Baby Food Market | 2026-2036
Hypo Anti Allergic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Hypo Anti Allergic Baby Food Market Foresight
Specialty pharmacy and direct-to-parent subscription channels is rewriting access patterns for hypoallergenic infant nutrition. Nestlé leverages its pediatric research network to sustain clinical credibility across hospital discharge programs. Danone anchors European organic sourcing through dedicated dairy partnerships in France and the Netherlands. Abbott Nutrition competes in metabolic and allergy-specific formula segments through prescription-linked distribution.
Hypo anti allergic baby food comprises infant and toddler nutrition products formulated with hydrolyzed proteins, eliminated common allergens, and reduced immunogenic potential to prevent or manage allergic sensitization. Manufacturing employs enzymatic hydrolysis and strict allergen-segregation protocols to achieve protein fractions below specific molecular-weight thresholds. Organic ingredient-source positioning now commands premium shelf placement and margin concentration as parents prioritize clean-label verification. Pouch packaging dominates convenience-driven purchasing while jar formats retain institutional and home-prepared substitution roles. Specialized formulation-stage products for diagnosed allergies capture the highest per-unit margins despite smaller volume bases.
FDA infant formula regulations and EFSA allergen-labeling directives shape product-development timelines and cross-border market access requirements for manufacturers. USDA organic certification and EU Organic standards create dual compliance burdens for brands seeking transatlantic distribution. Stakeholders must monitor evolving pediatric nutrition guidelines from WHO and national health ministries to anticipate reformulation mandates before competitive displacement occurs.
Market Dynamics
Enzymatic hydrolysis protocols and FDA allergen-labeling mandates are compressing product-development timelines while forcing simultaneous portfolio reformulation across manufacturers serving first-time urban parents.
Growth Catalysts
- EFSA Allergen-Labeling Directives:European mandates for precise immunogenic-potency disclosure accelerate clean-label verification investments and organic certification adoption across continental supply chains.
- Hydrolyzed Protein Fractionation:Advances in sub-3kDa molecular-weight targeting enable precise allergen-risk reduction for diagnosed-sensitization infant cohorts.
- Urban Parent Density:First-time parent concentration in metropolitan Germany, France, and Netherlands clusters sustains premium-channel throughput for specialty pharmacy distribution.
Market Restraints
- Organic Dairy Input Volatility:Pasture-based milk sourcing in the Netherlands and France faces climate-driven yield compression, elevating raw-material cost bases for hydrolyzed protein bases.
- Dual Certification Burden:USDA Organic and EU Organic compliance requirements create parallel audit trails that extend time-to-market for transatlantic product launches.
- Extensively Hydrolyzed Substitution:Amino acid-based elemental formulas capture severe-allergy cases that previously sustained mid-tier hypoallergenic volume, constraining addressable-market expansion.
Strategic Opportunities
- Direct-to-Parent Subscription Models:Recurring-revenue platforms bypass retail margin extraction while capturing longitudinal consumption data for personalized formulation refinement.
- WHO Pediatric Nutrition Guideline Alignment:Anticipatory reformulation to emerging protein-exposure recommendations positions portfolios ahead of national health ministry mandate cascades.
- Pouch Packaging Automation:Aseptic fill-seal robotics integration collapses per-unit production costs for convenience-format hypoallergenic purees targeting toddler transition segments.
Industry Challenges
- Allergen-Segregation Facility Engineering:Dedicated production lines for immunogenic-potency control demand capital deployment that mid-scale manufacturers struggle to finance.
- Clinical Validation Timeline Compression:Pediatric allergy-trial recruitment bottlenecks in Germany and France delay evidence-generation for hospital discharge program inclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypo Anti Allergic Baby Food Market |
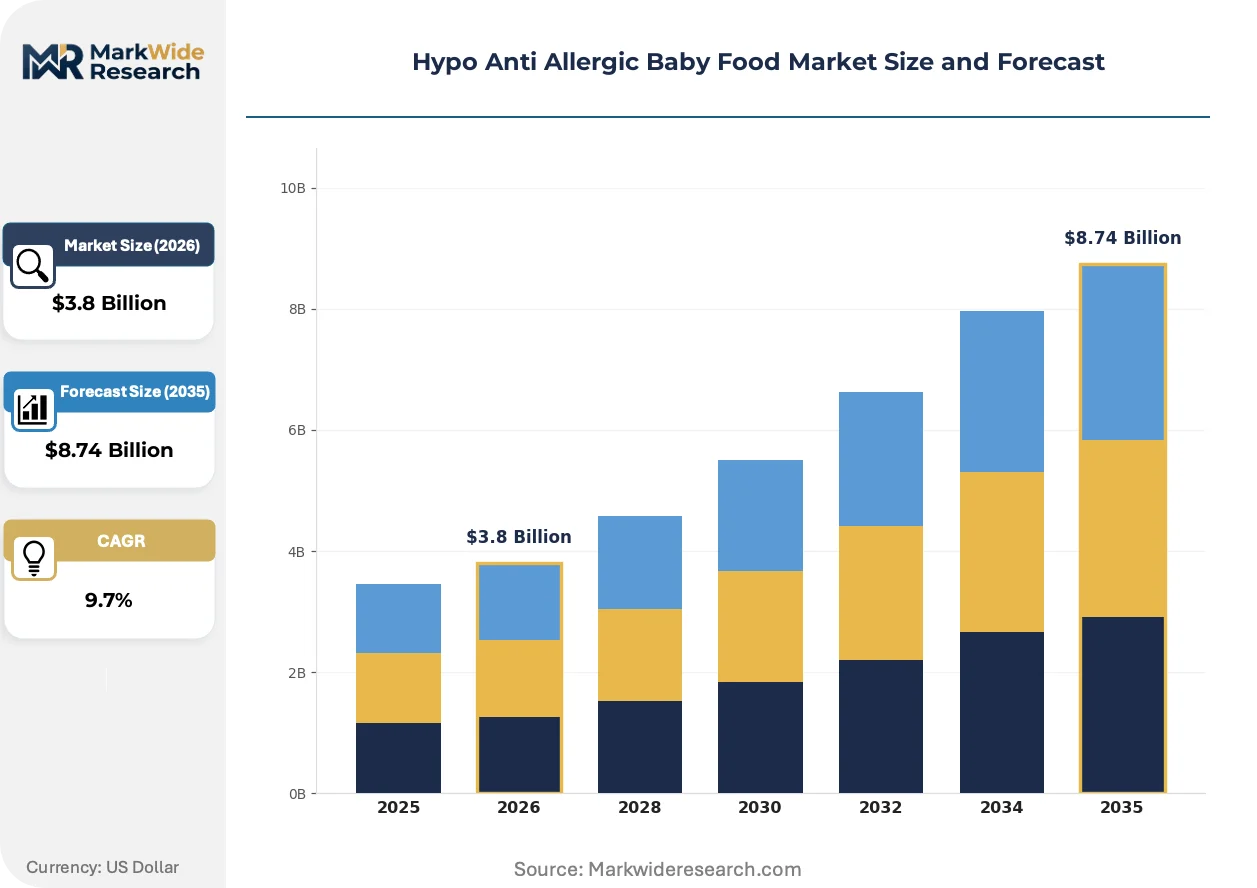
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
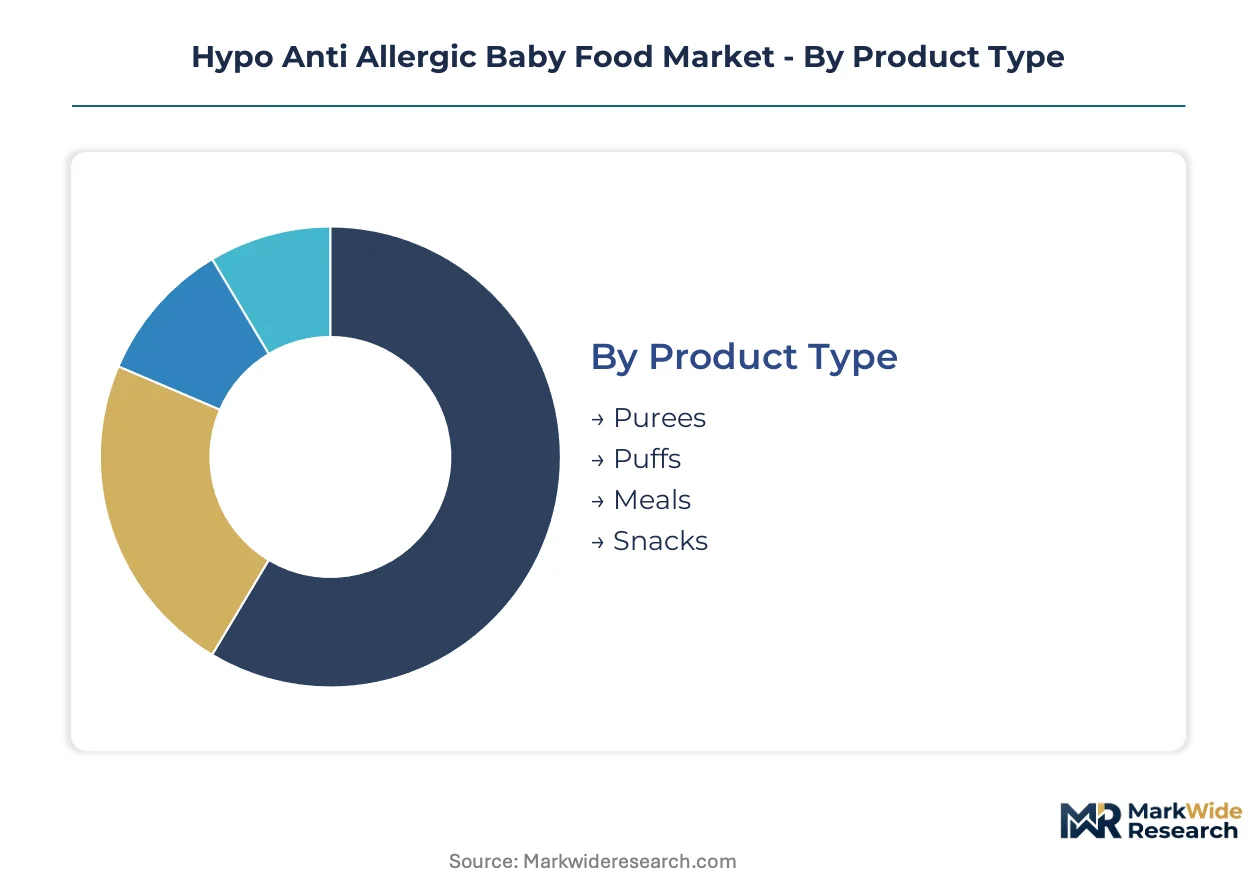
| Segmentation | Product Type: Purees, Puffs, Meals, Snacks Ingredient Source: Organic, Gluten-Free, Non-GMO, Natural Formulation Stage: Infant, Toddler, Specialized, Standardized Packaging Type: Pouches, Jars, Tubs, Sachets |
| Companies Covered | Nestlé, Danone, Abbott Nutrition, Reckitt, HiPP, Holle, Earth's Best, Mead Johnson Nutrition, Gerber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypo Anti Allergic Baby Food Market Shifts & Advancements
Protein engineering and regulatory disclosure requirements are simultaneously elevating manufacturing precision and transparency expectations across infant nutrition value chains.
Precision enzymatic hydrolysis is collapsing traditional distinctions between prevention-grade and treatment-grade formulations. Parents of at-risk but undiagnosed infants now access clinical-grade protein fractions previously restricted to prescription channels. This compression erodes margin stratification between retail hypoallergenic and metabolic specialty segments.
REACH chemical-registration requirements for processing aids used in hydrolysis equipment are forcing European manufacturers to substitute legacy enzymatic catalysts with bio-sourced alternatives. Industrial enzyme suppliers in the Netherlands are accelerating GRAS-equivalent dossier preparation. German formulators face the steepest compliance-cost absorption given their organic-dairy integration depth.
Subscription-based replenishment is displacing episodic retail purchasing among urban professional households. Specialty pharmacy platforms in Germany and France capture recurring orders through pediatrician-linked enrollment. This channel shift concentrates demand forecasting risk with platform operators while reducing brand-owned customer-relationship data.
Hypo Anti Allergic Baby Food Market Segmentation
Segmentation in hypoallergenic infant nutrition separates prevention-grade retail products from metabolic-grade clinical formulations, with each tier demanding distinct protein-hydrolysis protocols and allergen-segregation infrastructure. Manufacturers must align portfolio architecture against reimbursement pathways, organic certification tiers, and convenience-format preferences that diverge sharply between institutional and direct-to-consumer channels.
Product Type:
Use-case spectrum spans single-ingredient introduction through complex multi-allergen avoidance, with texture progression mapping directly to developmental feeding stages and parental convenience priorities.
- Purees:Smooth, single-fruit or vegetable formulations with hydrolyzed protein fortification serve as first-exposure vehicles for infants with familial allergy history. Demand clusters in German urban centers where pediatrician-directed early introduction protocols dominate, constrained by refrigerated supply chain requirements for preservative-free positioning.
- Puffs:Air-puffed grain matrices with sub-3kDa protein coatings enable self-feeding practice while maintaining strict allergen exclusion. French and Dutch parents favor these for toddler transition, driven by clean-label verification demands and portable format suitability for professional childcare arrangements.
- Meals:Complete nutrition dishes combining protein, carbohydrate, and vegetable components in balanced ratios for sustained satiety.
- Snacks:Bite-sized formats targeting between-meal consumption with controlled portion sizing and allergen-barrier packaging.
Established volume favors purees; emerging adoption favors puffs.
Ingredient Source:
Certification tier determines margin capture, with dual-organic compliance creating supply scarcity that manufacturers weaponize for shelf-positioning negotiations.
- Organic:USDA and EU Organic dual-certified ingredients command premium positioning through pasture-based dairy sourcing in the Netherlands and France. German retailers allocate disproportionate shelf space to these SKUs, reflecting parental willingness to pay for supply-chain transparency in allergy-risk contexts.
- Gluten-Free:Elimination of gliadin and glutenin proteins addresses celiac-adjacent sensitization concerns alongside IgE-mediated wheat allergy. Italian and Spanish demand is climbing the fastest for this segment, driven by national health ministry recognition of non-celiac gluten sensitivity in pediatric populations.
- Non-GMO:Verification against genetically modified organism content through third-party testing protocols.
- Natural:Minimal-processing claims without synthetic additive inclusion, typically positioned below certified-organic price tiers.
Organic certification anchors premium pricing; gluten-free positioning captures steepest expansion trajectory among late-entering parents.
Formulation Stage:
Developmental alignment with protein-exposure windows creates distinct regulatory and clinical validation burdens across age-bracketed portfolios.
- Infant:First-stage formulations for 0-12 month consumption with extensively hydrolyzed protein bases and iron fortification meeting EFSA compositional requirements. Hospital discharge programs in Germany and France drive prescription-linked volume, constrained by amino-acid formula substitution in severe allergy cases.
- Specialized:Diagnosis-specific products for confirmed cow's milk protein allergy, eosinophilic esophagitis, or FPIES management requiring medical food classification. Per-unit margins peak here despite restricted addressable populations, as reimbursement pathways offset price sensitivity.
- Toddler:12-36 month nutrition with texture complexity progression and reduced fat ratios versus infant formulations.
- Standardized:Mass-market prevention-grade products without individualized clinical targeting.
Specialized formulations concentrate margin; toddler-stage products scale volume through subscription retention mechanics.
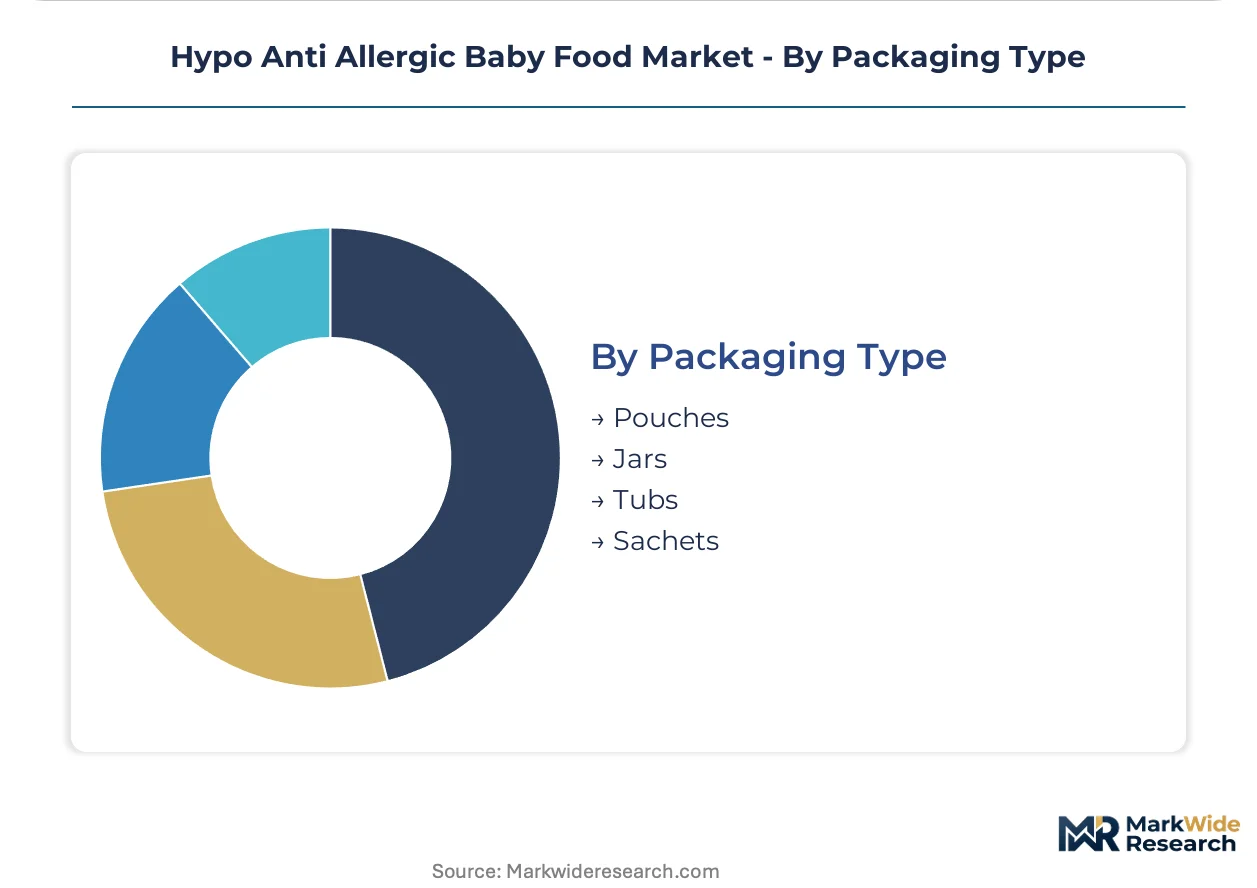
Packaging Type:
Format selection encodes consumption occasion, with aseptic technology investments separating convenience-leaders from institutional-legacy suppliers.
- Pouches:Flexible film laminates with spout fitments enable single-handed feeding and precise portion control. German specialty pharmacy platforms favor these for recurring subscription fulfillment, driven by urban parent density and workplace pumping norm compatibility.
- Jars:Glass or rigid plastic containers with wide-mouth access for spoon-feeding and home-prepared texture modification. French institutional childcare contracts retain this format, constrained by sterilization energy costs and breakage logistics.
- Tubs:Round or rectangular rigid containers with resealable lids for multi-serve storage.
- Sachets:Single-serve powder sachets for travel and emergency backup requiring reconstitution.
Pouch automation investments concentrate production capability; jar formats defend legacy institutional relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers extract 35-40% shelf-space premiums for dual-certified organic SKUs versus conventional hypoallergenic lines, while Italian and Spanish markets trade at 15-20% discounts due to fragmented distribution and lower parental willingness-to-pay for certification tiers.
Germany
First-time urban parents in Berlin, Munich, and Hamburg drive specialty pharmacy subscription penetration for extensively hydrolyzed infant formulas. EFSA allergen-labeling directives mandate precise immunogenic-potency disclosure on all packaging. The Baden-Württemberg organic dairy corridor supplies hydrolyzed protein bases to formulators in Freiburg and Stuttgart.
France
Pediatrician-directed early introduction protocols concentrate demand in Paris and Lyon metropolitan clusters for prevention-grade purees. ANSM oversees medical food classification for diagnosed cow's milk protein allergy products. The Brittany-Normandy pasture belt faces climate-driven yield compression, elevating raw-material costs for hydrolyzed organic bases.
Netherlands
Professional childcare arrangements in Amsterdam and Rotterdam favor pouch-format puffs with clean-label verification. REACH chemical-registration requirements force substitution of legacy enzymatic catalysts with bio-sourced alternatives. Wageningen-based industrial enzyme suppliers accelerate GRAS-equivalent dossier preparation for hydrolysis equipment processing aids.
United States
Hospital discharge programs in Boston and San Francisco metro areas sustain prescription-linked volume for metabolic-grade formulations. FDA infant formula regulations shape product-development timelines and cross-border market access requirements. California's organic ingredient sourcing networks supply pasture-based dairy inputs to West Coast formulators.
Italy
National health ministry recognition of non-celiac gluten sensitivity drives fastest-climbing demand for gluten-free positioning among late-entering parents in Milan and Rome. FSSAI-aligned import protocols govern cross-border organic certification acceptance. The Po Valley dairy cluster supplies conventional hydrolyzed protein bases at cost-advantaged scale.
Hypo Anti Allergic Baby Food Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in protein fractionation and organic dairy sourcing. The vendor base stratifies across multinational nutrition conglomerates with pediatric research networks, mid-scale organic specialists with dedicated allergen-segregation facilities, and private-label assemblers dependent on toll-manufacturing arrangements. Three archetypes dominate: clinical-credibility builders leveraging hospital discharge relationships, clean-label purists anchoring premium organic positioning, and scale operators compressing per-unit costs through pouch automation. Competitive moves concentrate on M&A for allergen-segregation facility access and strategic partnerships with industrial enzyme suppliers for hydrolysis protocol refinement.
Within the clinical-credibility tier, Nestlé and Abbott Nutrition exemplify platform integrators with sustained hospital discharge program inclusion. Danone occupies a position bridging European organic sourcing depth with multinational scale. HiPP and Holle represent the clean-label purist archetype, anchoring premium positioning through dedicated dairy partnerships in France and the Netherlands.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Abbott Nutrition |
| Reckitt |
| HiPP |
| Holle |
| Earth's Best |
| Mead Johnson Nutrition |
| Gerber |
| Others |
Supply & Pricing Matrix
The Baden-Württemberg organic dairy corridor supplies hydrolyzed protein bases that command shelf-space premiums in German retail, with downstream pricing power concentrating among dual-certified organic formulators who control dedicated allergen-segregation infrastructure.
Pricing Analysis
The customization-premium spread separates standard prevention-grade formulations from extensively hydrolyzed clinical-grade products requiring medical food classification. Three-tier pricing structure across premium, standard, and economy levels stratifies by organic certification tier and protein hydrolysis depth. Pricing pressure stems from amino acid-based elemental formulas capturing severe-allergy cases previously served by mid-tier hypoallergenic lines. First-time urban parents in metropolitan Germany exhibit lowest price sensitivity, while late-entering parents in Italy and Spain trade at discount tiers.
Supply Chain Analysis
Climate-driven yield compression in the Brittany-Normandy pasture belt elevates raw-material cost volatility for organic hydrolyzed protein bases. Geographic supply concentration centers on the Netherlands, France, and Germany for pasture-based dairy inputs and enzymatic processing equipment. Raw material dependencies include organic milk solids, bio-sourced enzymatic catalysts, and aseptic packaging films. Single-source vulnerability runs through Wageningen-based industrial enzyme suppliers preparing GRAS-equivalent dossiers. Distribution runs through specialty pharmacy platforms and direct-to-parent subscription channels bypassing traditional retail margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA allergen-labeling mandates and precision enzymatic hydrolysis advances are disrupting traditional prevention-treatment formulation boundaries, creating compressed timelines for portfolio repositioning.
For Market Incumbents: Pre-empt amino acid formula substitution in severe-allergy segments by accelerating clinical validation for hospital discharge program inclusion. Secure dedicated allergen-segregation facility access through targeted acquisition of mid-scale organic specialists in the Netherlands and France. Backward integration into pasture-based dairy sourcing hedges climate-driven input volatility. For New Entrants and Emerging Players: Italian and Spanish gluten-free positioning offers underpenetrated white space given national health ministry recognition of non-celiac gluten sensitivity. The toddler-stage puff segment in French professional childcare arrangements presents the most penetrable entry point. A direct-to-parent subscription model with pediatrician-linked enrollment captures recurring revenue without retail shelf-space competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clean-label purists with dual-organic certification depth and established dairy partnerships. Long-term viability rests on anticipatory reformulation capability aligned to emerging WHO pediatric nutrition guidelines. The signal to monitor is national health ministry mandate cascades following protein-exposure recommendation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Allergen-Segregation Facility Acquisition | Captures scarce production capacity required for EFSA immunogenic-potency compliance. |
| Direct-to-Parent Subscription Launch | Bypasses retail margin extraction while capturing longitudinal consumption data in German urban clusters. |
| Bio-Sourced Enzymatic Catalyst Transition | Addresses REACH chemical-registration requirements forcing legacy catalyst substitution. |
| Pouch Packaging Automation Investment | Collapses per-unit costs for convenience-format purees targeting toddler transition segments. |
| WHO Guideline Alignment Reformulation | Positions portfolios ahead of national health ministry mandate cascades across European markets. |
Research Methodology
Operator-level perspectives from pediatric nutrition formulators, specialty pharmacy procurement managers, organic dairy cooperative directors, and industrial enzyme suppliers anchored the qualitative base. Primary interviews combined with secondary validation from EFSA allergen-labeling directives, FDA infant formula regulations, USDA organic certification databases, and hospital discharge program formularies. Bottom-up volume modeling triangulated against top-down category spend estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning product type, ingredient certification tier, formulation stage, and packaging format. CAGRs derived from longitudinal consumption pattern analysis and pediatric population cohort sizing. Forecast inputs incorporated climate-driven organic dairy yield variability and REACH chemical-registration compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by amino acid formula specialists or accelerated WHO guideline adoption would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market