
 Organic Follow Up Formula Market | 2026-2036
Organic Follow Up Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Follow Up Formula Market Analytics
USDA Organic certification is bifurcating the competitive landscape into qualified suppliers and excluded entrants. HiPP leverages its vertically integrated European dairy network to secure raw material traceability. Danone sustains formulation leadership through dedicated pediatric nutrition R&D centers in France and the Netherlands. Earth's Best anchors its North American position through long-standing retail partnerships with natural grocery chains.
Organic follow up formula constitutes a powdered or liquid nutritional product designed for infants transitioning from breast milk or initial formula, typically containing organic lactose, whey protein, and vegetable oils without synthetic pesticides or GMO ingredients. Its primary purpose is to deliver standardized micronutrient density while meeting strict residue limits for agricultural chemicals. Powder formulations dominate volume due to shelf stability and lower logistics costs, while liquid ready-to-feed formats command premium positioning in convenience-oriented channels. Online retailers represent the fastest-growing distribution pathway as subscription models reduce customer acquisition costs for direct-to-consumer brands like Bobbie and ByHeart.
FDA infant formula regulations in the United States establish minimum nutrient profiles and manufacturing safety standards that parallel USDA Organic requirements. The EU Organic Regulation and EFSA novel food assessments collectively determine which ingredient innovations gain market access across European markets. Stakeholders must monitor evolving national organic standards in China under SAMR oversight, as import registration changes could redirect supply flows from European manufacturers toward domestically certified production.
Market Dynamics
EU Organic Regulation enforcement is compressing supply eligibility by mandating full-chain traceability from dairy farm to finished can, forcing manufacturers to rebuild procurement networks or exit the category entirely.
Growth Catalysts
- Pediatric nutrition programs:Early childhood development initiatives in Germany and France are embedding organic follow-up formula into subsidized feeding schemes, expanding institutional procurement channels beyond retail.
- SAMR registration reforms:China's streamlined organic import pathways under revised national standards are accelerating European manufacturer market access previously blocked by protracted approval timelines.
- Precision fermentation:Novel protein production methods are reducing dependency on conventional dairy supply chains while maintaining organic certification compatibility for lactose and whey alternatives.
Market Restraints
- Organic dairy input costs:Certified organic milk powder trades at 40-60% premiums over conventional, compressing gross margins for non-vertically integrated blenders.
- European supply concentration:Three dairy cooperatives control majority organic milk volumes in Germany and Austria, creating procurement bottlenecks during seasonal shortfalls.
- EFSA novel food assessments:Probiotic and HMO additive approvals face 18-24 month evaluation windows, delaying formulation upgrades versus conventional formula competitors.
Strategic Opportunities
- Subscription direct-to-consumer:Automated replenishment models bypass traditional retail slotting fees and capture lifetime value through pediatrician-endorsed enrollment programs.
- Regenerative organic certification:USDA's pilot program for soil health verification creates premium tier differentiation above baseline organic claims.
- Liquid ready-to-feed expansion:Convenience-oriented urban parents in France and Netherlands are shifting volume share from powder toward single-serve formats for travel and daycare use.
Industry Challenges
- Organic chemist recruitment:Formulation scientists with dual expertise in pediatric nutrition and residue-free processing command salaries 35% above conventional food technologist benchmarks.
- Multi-certification synchronization:Maintaining concurrent USDA Organic, EU Organic, and China Organic registrations requires dedicated compliance teams managing divergent audit cycles.
- Legacy ERP traceability gaps:Batch-level ingredient genealogy systems struggle to integrate with blockchain verification platforms demanded by major retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Follow Up Formula Market |
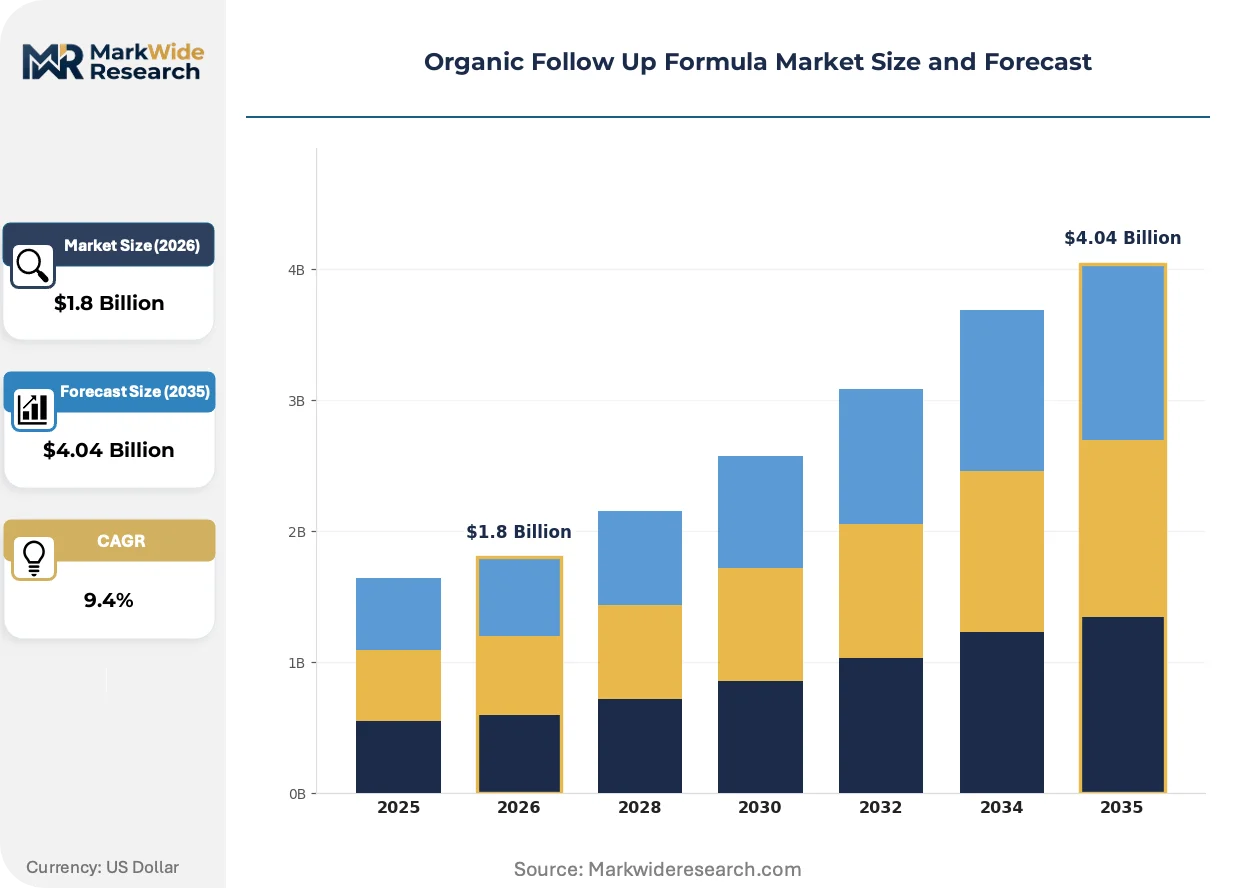
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablets, Gummies Distribution Channel: Supermarkets, Health Stores, Online Retailers, Pharmacies Customer Type: Parents, Health-Conscious Adults, Fitness Enthusiasts, Seniors Certification: USDA Organic, Non-GMO Project, Gluten-Free, Vegan |
| Companies Covered | Holle, Danone, Nestle S.A., Earth's Best, ByHeart, HiPP, Bobbie, Happy Baby, Kendamil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Follow Up Formula Market Evolving Landscape
Clean-label ingredient sourcing and manufacturing transparency are redefining competitive advantage, with digital traceability tools now table stakes for shelf placement in premium retail channels.
A2 beta-casein protein sourcing is supplanting conventional dairy inputs for digestive sensitivity positioning. German and Dutch pediatric nutrition specialists are accelerating A2 organic line launches. This protein segmentation is compressing commodity organic whey premiums and forcing suppliers to certify dual-stream production facilities.
EFSA's tightened pesticide residue maximum levels under revised EU Organic Regulation are disqualifying previously compliant ingredient batches. Manufacturers are responding by contracting dedicated organic dairy streams rather than spot-market purchasing. The Netherlands and Ireland face the steepest compliance recalibration given their historical reliance on pooled supply sourcing.
Subscription-based replenishment is fragmenting the traditional supermarket-dominant distribution model. Direct-to-consumer brands capture pediatrician referrals through digital health platforms, displacing pharmacy and grocery impulse purchases. This channel rotation is most pronounced in urban coastal markets of the United States and metropolitan France where delivery infrastructure supports cold-chain liquid formula distribution.
Organic Follow Up Formula Market Segmentation
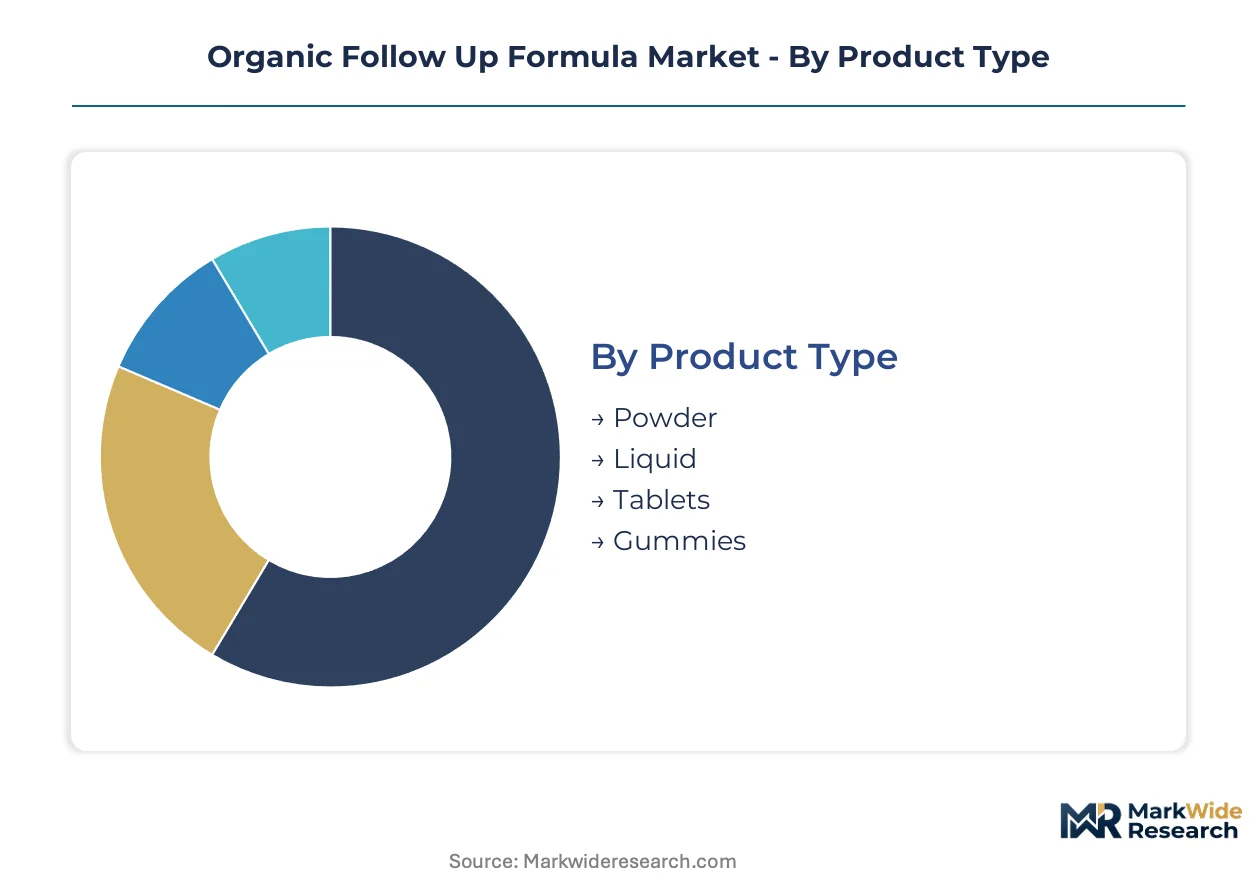
Organic follow-up formula segmentation reveals divergent growth vectors across formulation physics, channel economics, and certification premiums. Manufacturers must align production assets with the specific residue-testing and cold-chain requirements each segment demands.
Product Type:
Powder formats dominate domestic manufacturing footprints while liquid production clusters near major metropolitan demand centers to minimize cold-chain degradation.
- Powder:Dehydrated formulations with organic lactose and whey protein concentrates deliver 24-month shelf stability. Demand concentrates in German retail pharmacy chains where parents stockpile against seasonal supply disruptions. EFSA residue limits force dedicated spray-drying facilities.
- Liquid:Ready-to-feed emulsions require aseptic filling and refrigerated distribution. Urban French parents in Paris and Lyon drive volume through subscription services for daycare convenience. SAMR import registration complexity favors European domestic production over Asian sourcing.
- Tablets:Compressed nutrient formats serve pediatric travel kits and emergency backup scenarios. Limited moisture sensitivity enables ambient distribution through German drugstore chains.
- Gummies:Gelatin-based chewable variants appeal to toddler transition palates. Irish organic gelatin suppliers face EU Organic Regulation traceability audits for bovine sourcing.
Powder holds the largest share; momentum sits with liquid as convenience premiums justify cold-chain investments.
Distribution Channel:
Channel selection determines margin structure, with direct models capturing lifetime value while retail incurs slotting fees and inventory risk.
- Supermarkets:Mass-market placement demands multi-pallet volume commitments and promotional calendar participation. German REWE and EDEKA chains enforce blockchain traceability verification for organic shelf placement.
- Health Stores:Specialty retailers command 25-35% retail margins but deliver educated consumer conversion. Dutch Ekoplaza and German Alnatura networks prioritize regenerative organic tier differentiation.
- Online Retailers:Subscription platforms bypass traditional retail economics through automated replenishment. French pediatrician-endorsed digital health platforms drive customer acquisition for direct-to-consumer entrants.
- Pharmacies:Professional channel credibility supports premium positioning. German Apotheken require BfArM pharmaceutical handling licenses for liquid formula storage.
Supermarkets retain volume leadership; online retailers are expanding most quickly as subscription models reduce acquisition costs.
Customer Type:
End-user segmentation maps to distinct nutritional specification requirements and price elasticity profiles across life stages.
- Parents:Primary purchasers of infant follow-up formula demanding residue-free certification and developmental nutrient completeness. German parental willingness-to-pay premiums for EU Organic certification exceeds other European markets.
- Health-Conscious Adults:Emerging segment seeking organic nutritional density for metabolic optimization. Dutch urban professionals drive demand for clean-label adult formulations with pediatric-grade ingredient standards.
- Fitness Enthusiasts:Athletic consumers repurposing high-protein organic bases for recovery nutrition. Limited volume but high engagement with transparent supply chain documentation.
- Seniors:Digestive sensitivity positioning attracts aging populations to A2 beta-casein organic variants. French retirement community procurement channels represent institutional volume opportunity.
Parents dominate absolute volume; health-conscious adults show steepest expansion trajectory as clean-label preferences migrate across life stages.
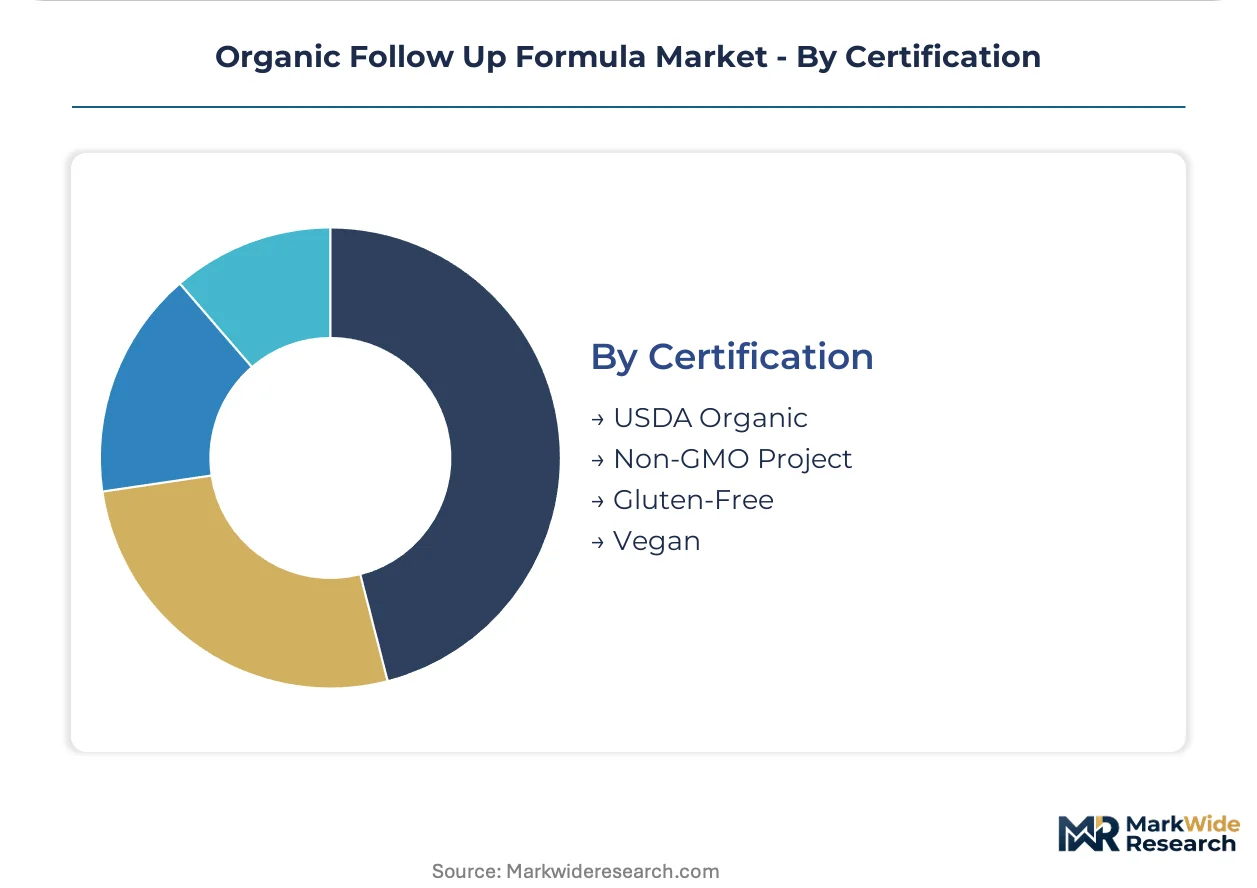
Certification:
Certification tiering creates price stratification and market access gating, with multi-certification products commanding shelf preference in premium channels.
- USDA Organic:US market entry requirement enforced through accredited certifier audits. German manufacturers seeking US export must maintain parallel EU and USDA organic systems, doubling compliance overhead.
- Non-GMO Project:Third-party verification supplements baseline organic claims for US coastal consumers. French retailers increasingly demand this overlay for transatlantic product parity.
- Gluten-Free:Allergen-specific certification enables pediatric gastroenterologist recommendations. Irish and Dutch production facilities face additional cleaning protocol audits.
- Vegan:Plant-based formulation certification excluding all animal derivatives. Precision fermentation-derived proteins enable this positioning while maintaining organic compatibility.
USDA Organic anchors revenue; vegan certification is gaining share fastest as protein diversification technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious parents in Germany, France, and the Netherlands drive premium organic formula procurement, while Chinese regulatory reforms and US subscription commerce reshape cross-border supply flows. National organic certification regimes and pediatric nutrition subsidy programs determine market access tiers.
Germany
Parents in Bavaria and Baden-Württemberg demonstrate the strongest willingness-to-pay premiums for EU Organic certified infant nutrition. BfArM pharmaceutical handling licenses govern liquid formula distribution through Apotheken channels. The EDEKA and REWE retail networks enforce blockchain traceability verification for organic shelf placement in Munich and Stuttgart metropolitan zones.
France
Urban parents in Paris and Lyon accelerate liquid ready-to-feed adoption through subscription services for daycare convenience. ANSM pharmaceutical oversight aligns with EFSA residue limits under the EU Organic Regulation. Pediatric nutrition R&D clusters in the Île-de-France region support formulation innovation for digestive sensitivity positioning.
Netherlands
Dutch Ekoplaza specialty retailers prioritize regenerative organic tier differentiation above baseline certification. The Dutch dairy cooperative concentration in Friesland and Gelderland creates procurement leverage for organic milk powder sourcing. Precision fermentation research facilities near Wageningen reduce dependency on conventional dairy supply chains.
China
SAMR streamlined organic import registration accelerates European manufacturer market access previously blocked by protracted approval timelines. First-tier city parents in Shanghai and Beijing demand multi-certification products spanning EU Organic, USDA Organic, and China Organic standards. Domestic production investments in Yangtze River Delta provinces redirect supply flows toward locally certified manufacturing.
United States
Coastal urban parents in California and New York Metro drive direct-to-consumer subscription adoption through pediatrician-endorsed digital health platforms. FDA infant formula regulations establish parallel nutrient and safety standards to USDA Organic requirements. Cold-chain liquid formula distribution concentrates near Los Angeles and New York logistics hubs.
Organic Follow Up Formula Market Competitive Landscape
Player mix skews toward European dairy-integrated multinationals and North American direct-to-consumer specialists. Consolidation pressure intensifies as EU Organic Regulation traceability mandates raise capital barriers for non-vertically integrated blenders. Three strategic archetypes dominate: legacy European dairy networks with captive organic milk supply, US subscription-native brands bypassing retail economics, and hybrid players bridging pharmaceutical channel credibility with mass-market scale. Dominant competitive moves include backward integration into organic dairy cooperatives and geographic expansion through multi-certification registration.
Within the European dairy-integrated tier, Danone and HiPP exemplify archetypes built on pediatric nutrition R&D infrastructure and vertically controlled supply chains. Among US direct-to-consumer specialists, Bobbie and ByHeart occupy positions defined by subscription-based customer acquisition and pediatrician referral networks. Earth's Best anchors the hybrid archetype through long-standing natural grocery retail partnerships spanning North American pharmacy and grocery channels.
| Leading Market Players |
|---|
| Holle |
| Danone |
| Nestle S.A. |
| Earth's Best |
| ByHeart |
| HiPP |
| Bobbie |
| Happy Baby |
| Kendamil |
| Others |
Value Network & Pricing Analysis
A2 beta-casein protein substitution for conventional organic whey is simultaneously shifting procurement geography toward German and Dutch dual-stream dairy facilities and compressing commodity organic protein premiums across the category. This input transition feeds directly into contract renegotiation patterns between blenders and cooperative suppliers, with residue-testing protocols now governing price indexation clauses.
Pricing Analysis
Cost-plus contracts with organic milk powder indexation anchor supplier agreements across German and Austrian dairy cooperatives. Three-tier pricing structure across EU Organic premium, regenerative organic ultra-premium, and baseline conventional-organic economy levels reflects certification grade and traceability depth. Pricing pressure stems from SAMR registration cost absorption for China market entry. German pharmacy channel buyers exhibit lowest price sensitivity; mass-market supermarket procurement teams show highest elasticity.
Supply Chain Analysis
Germany and the Netherlands anchor organic dairy powder production through Friesland and Bavarian cooperative networks. Certified organic lactose, A2 beta-casein whey, and vegetable oil blends draw from dedicated farm-to-can traceability systems. Single-source vulnerability concentrates in seasonal organic milk shortfalls across Alpine dairy regions. Distribution runs through refrigerated liquid hubs near Paris and Lyon alongside ambient powder logistics through Rotterdam and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EU Organic traceability mandates create entrenchment advantages for incumbent certifiers. Switching costs for parents locked into pediatrician-endorsed subscription programs compound this defensive structure.
For Market Incumbents: Secure captive organic milk supply through cooperative equity stakes or long-term offtake agreements with Friesland and Bavarian dairy networks. Elevation of EFSA residue limits poses direct margin threat to spot-market dependent blenders. Channel control through Apotheken-exclusive liquid distribution in Germany reinforces pricing power against retail-centric challengers. For New Entrants and Emerging Players: SAMR streamlined registration fast-tracks offer lowest barrier entry point for European manufacturers previously blocked by Chinese approval timelines. White-space concentrates in direct-to-consumer subscription models bypassing German supermarket slotting fees. Pediatrician-endorsed digital health platform partnerships provide credible customer acquisition angle against legacy retail dependence. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer specialists holding subscription revenue visibility but lacking backward integration into dairy supply. Five-to-ten year viability hinges on multi-certification registration moats spanning USDA, EU, and China Organic standards. Inflection signal to monitor: SAMR domestic production subsidy announcements redirecting supply flows from European import toward Yangtze River Delta manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Dairy Cooperatives | Captive milk supply secures traceability compliance under tightened EU Organic Regulation enforcement. |
| Multi-Certification Registration Investment | Concurrent USDA, EU, and China Organic approvals unlock shelf placement in premium pharmacy and specialty retail channels. |
| Direct-to-Consumer Subscription Launch | Automated replenishment bypasses supermarket slotting fees and captures lifetime value through pediatrician referrals. |
| Precision Fermentation Protein Sourcing | Novel lactose and whey alternatives reduce dependency on seasonal organic dairy supply volatility. |
| Liquid Ready-to-Feed Cold-Chain Expansion | Urban French and Dutch daycare convenience demand justifies refrigerated distribution infrastructure investment. |
Research Methodology
Operator-level perspectives from pediatric nutrition R&D directors, organic dairy cooperative procurement managers, pharmacy category buyers, and SAMR registration consultants anchored the qualitative base. Secondary validation drew from EFSA novel food assessment databases, FDA infant formula regulatory filings, EU Organic Regulation enforcement bulletins, and German BfArM pharmaceutical handling license records. Bottom-up volume modeling triangulated against top-down category expenditure estimates across the analysis window.
Sensitivity analysis tested forecast outputs against regulatory timeline acceleration scenarios and organic dairy input cost volatility assumptions. Segmentation dimensions spanned formulation physics, distribution channel economics, certification tier premiums, and customer life-stage nutritional specifications. CAGRs were derived from fitted growth curves incorporating pediatric nutrition program enrollment trajectories and subscription commerce penetration rates across metropolitan demand clusters.
Underlying assumptions cover SAMR registration pathway stability, EU Organic Regulation enforcement consistency, and organic dairy cooperative supply reliability, with deviation risk concentrated in China domestic production subsidy announcements and EFSA residue limit recalibration cycles. Recalibration cycles align with material shifts in regulatory approval timelines and cooperative supply contract renegotiation windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Kids Food and Beverages Market