
 Disposable Tea Flask Market | 2026-2036
Disposable Tea Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Tea Flask Market Outlook
Premium-grade insulation specifications is bifurcating the competitive landscape into performance-tier and value-tier camps. Huhtamaki Oyj leverages its European manufacturing footprint to supply temperature-stable laminates for high-end café chains. Dart Container Corporation anchors North American volume through its captive resin-to-cup production network. Pactiv Evergreen Inc. differentiates via chilled-chain compatibility across its foodservice portfolio.
A disposable tea flask is a single-use or limited-use vessel engineered with multi-layer barrier films or vacuum-insulated walls to maintain beverage temperature for defined durations, typically incorporating polyethylene or aluminum substrates sealed through thermoforming or injection-stretch blow molding. The device serves commercial foodservice operators and retail consumers requiring portable, hygienic tea consumption without cleaning logistics. Plastic material type dominates current output volumes due to cost scalability, though paper-based alternatives are capturing premium positioning in European regulatory environments. Medium size configurations lead household penetration, while large-format units command higher per-unit margins in catering services where batch dispensing replaces individual cup orders.
China's SAMR enforces GB 4806 food-contact material standards that restrict certain plasticizers in disposable hot-beverage containers. India's FSSAI mandates specific migration limits for packaging in direct contact with brewed tea and herbal infusions. The EU's Single-Use Plastics Directive shapes material substitution timelines across member state import channels. Stakeholders must monitor evolving compostability certifications and regional extended producer responsibility schemes to align capacity investments with compliance trajectories.
Market Dynamics
GB 4806 compliance mandates from China's SAMR are compressing material substitution timelines, forcing converters to validate alternative barrier substrates ahead of planned capacity cycles.
Growth Catalysts
- Urban Commuter Density:Office corridor footfall in Mumbai and Delhi generates concentrated on-the-go consumption nodes that sustain high-throughput foodservice procurement.
- Compostability Certification:EU Single-Use Plastics Directive timelines accelerate demand for certified biodegradable laminates in import-dependent Northern European markets.
- Vacuum Insulation Scale-Up:Thermoforming advances enable cost-efficient multi-layer wall structures previously limited to reusable formats.
Market Restraints
- Resin Supply Concentration:Captive polyethylene production networks in the US Gulf Coast create input cost volatility for non-integrated converters.
- Migration Testing Burden:FSSAI's specific limits for brewed tea contact impose extended validation cycles on new material formulations.
- Reusable Format Competition:Stainless steel tumbler rental schemes in corporate campuses displace single-use flask orders at scale.
Strategic Opportunities
- Chilled-Chain Expansion:Iced tea and cold-brew formats open compatibility with Pactiv Evergreen's existing foodservice cold logistics infrastructure.
- Extended Producer Responsibility:India's evolving EPR schemes create first-mover advantage for domestic recyclate-integrated production.
- Digital Print Personalization:Variable-data decoration enables micro-batch branding for regional café chains without plate-change costs.
Industry Challenges
- Barrier Film Talent Scarcity:Formulation chemists with co-extrusion expertise command premium compensation in tight labor markets.
- Certification Timeline Compression:SAMR's accelerated GB standard revision cycles outpace typical 18-month stability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Tea Flask Market |
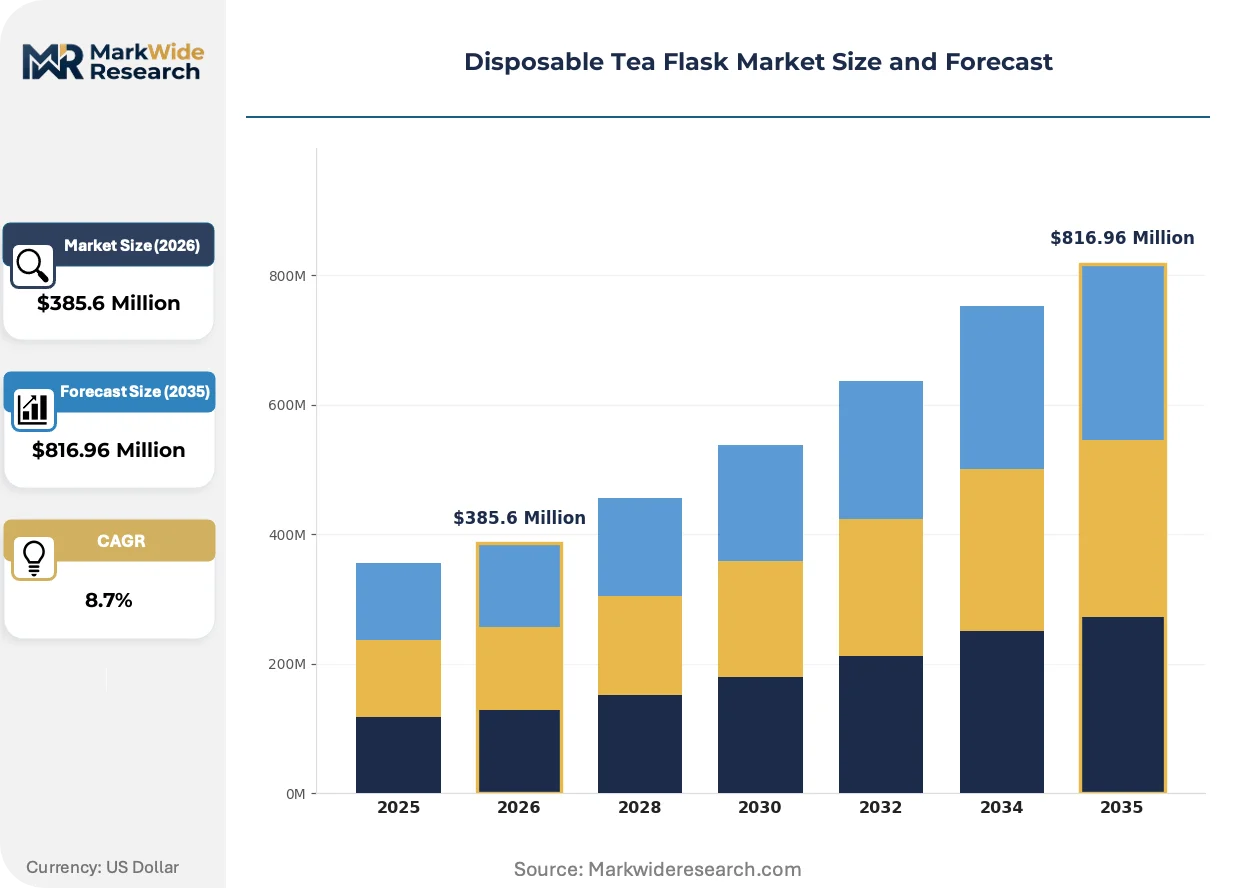
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paper Size: Small, Medium, Large, Extra Large End User: Households, Cafés, Restaurants, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Huhtamaki Oyj, Dart Container Corporation, Pactiv Evergreen Inc., Genpak LLC, Berry Global Inc., Sanex Packaging Connections Pvt. Ltd., Arora Packaging Point, Shreeji Packaging Solutions, EcoFlask Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Tea Flask Market Strategic Shifts
Active barrier technologies and digital manufacturing are compressing product development cycles while regulatory stringency forces material portfolio diversification.
Aluminum-oxide-coated polyethylene terephthalate films are displacing conventional metallized layers in high-temperature tea applications. Premium café chains in Germany and Switzerland have adopted these substrates for their superior oxygen barrier under humid conditions. This performance tier is bifurcating the converter base into qualified laminate specialists and commodity cup producers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from hot-beverage contact materials. European importers now require fluorine-free barrier declarations backed by third-party testing. High-volume foodservice distributors are consolidating procurement around pre-certified supply bases to avoid customs detention risk.
Direct-to-operator digital platforms are displacing traditional foodservice distribution intermediaries in mid-market café procurement. Mumbai-based chain operators now configure private-label flask specifications through browser-based interfaces with real-time quoting. This channel compression is most visible in India's metropolitan clusters where distributor markups previously absorbed 12-15 percent of landed cost.
Disposable Tea Flask Market Segmentation
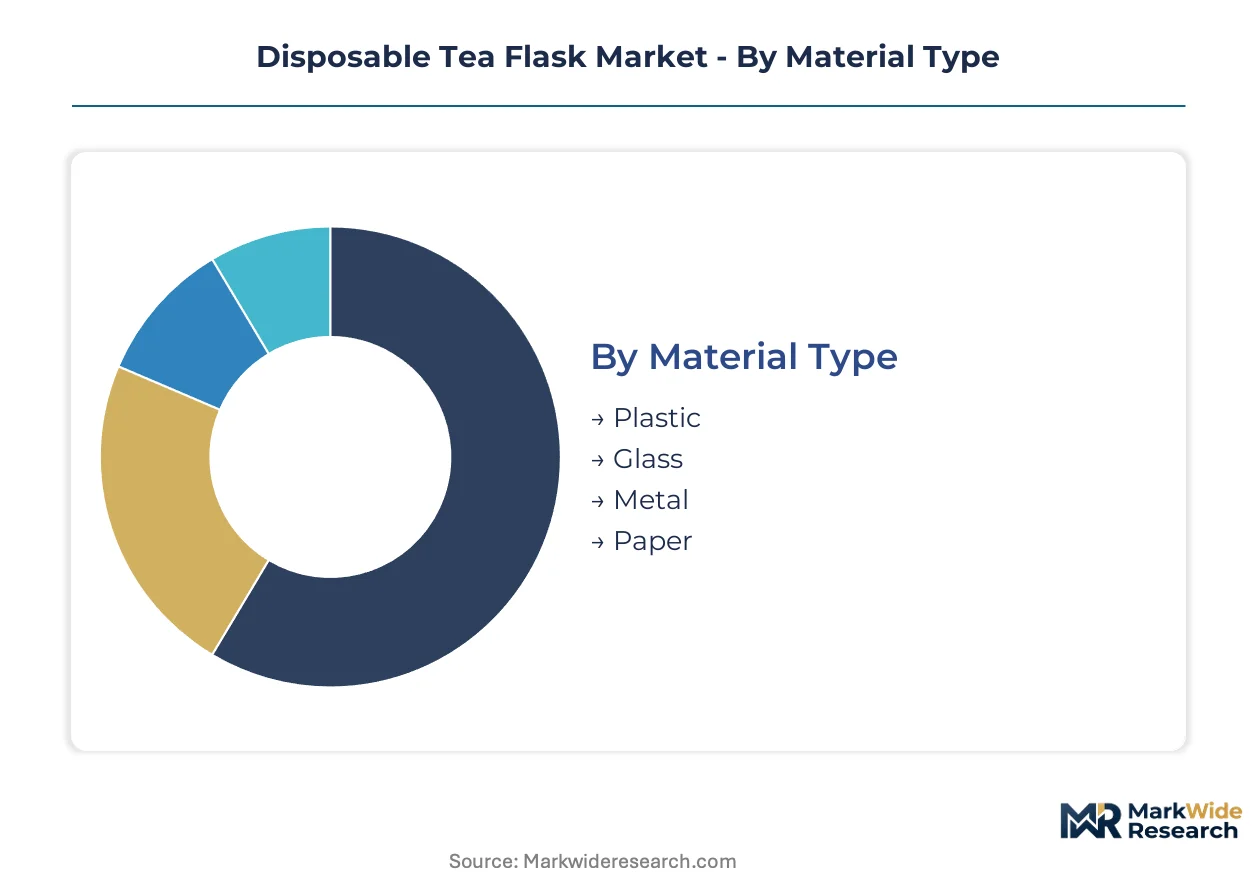
Segmentation in disposable tea flasks reveals how regulatory pressure and consumption context reshape material and format priorities. Each dimension carries distinct compliance burdens and margin structures that determine competitive positioning.
Material Type:
Regulatory differentiation across China, India, and the EU is fragmenting material adoption curves, with migration limits and compostability mandates forcing portfolio diversification.
- Plastic:Multi-layer polyethylene and polypropylene laminates dominate current output through thermoforming scalability. Mumbai and Delhi foodservice corridors absorb high volumes despite FSSAI migration testing burdens for brewed tea contact.
- Paper:Fiber-based barriers with bio-coatings are climbing fastest in Northern European import channels where EU Single-Use Plastics Directive timelines accelerate certified compostable demand. Premium café chains in Germany have adopted these for brand differentiation.
- Glass:Borosilicate and soda-lime formats serve temperature-sensitive specialty tea segments with higher per-unit margins but limited scalability.
- Metal:Aluminum substrates with internal lacquer coatings occupy niche premium positioning for gift and ceremonial tea applications.
Plastic handles the majority of throughput; Paper is expanding most quickly on share.
Size:
Volume concentration in catering procurement and commuter retail creates divergent margin profiles across the size spectrum.
- Medium:Household penetration peaks here as individual consumption formats align with single-serve brewing systems. Office corridor vending in Indian metropolitan clusters sustains replenishment rates.
- Large:Catering services command higher per-unit margins where batch dispensing replaces individual cup orders at corporate events and institutional foodservice.
- Small:Sampling and promotional formats serve tea brand marketing campaigns with seasonal demand spikes.
- Extra Large:Bulk institutional formats target railway and airline galley operations with extended temperature retention specifications.
Medium configurations anchor household volume; Large formats deliver the steepest margin expansion.
End User:
Customer type determines compliance depth and procurement scale, with commercial operators facing stricter material validation than retail consumers.
- Cafés:Premium chains in Germany and Switzerland specify aluminum-oxide-coated PET barriers for oxygen performance under humid conditions, bifurcating supplier qualification requirements.
- Catering Services:Event and institutional operators consolidate large-format procurement through direct-to-operator digital platforms that compress distributor markups.
- Households:Retail consumers prioritize cost accessibility over barrier performance, driving private-label penetration in supermarket channels.
- Restaurants:Full-service operators balance presentation quality with disposal logistics, favoring medium formats with printable surfaces for brand customization.
Cafés concentrate premium specification demand; Catering Services is gaining share fastest through channel compression.
Distribution Channel:
Channel structure determines working capital intensity and customer data access, with digital platforms disrupting traditional foodservice intermediaries.
- Online Retail:Direct-to-consumer platforms enable micro-batch personalization through variable-data decoration, serving regional café chains without plate-change costs.
- Wholesale:Institutional and catering procurement flows through consolidated distributors with captive logistics networks and extended payment terms.
- Supermarkets:Mass retail channels drive household penetration through private-label placement and promotional bundling with tea product lines.
- Specialty Stores:Premium tea retailers curate format assortments aligned with ceremonial and gift consumption occasions.
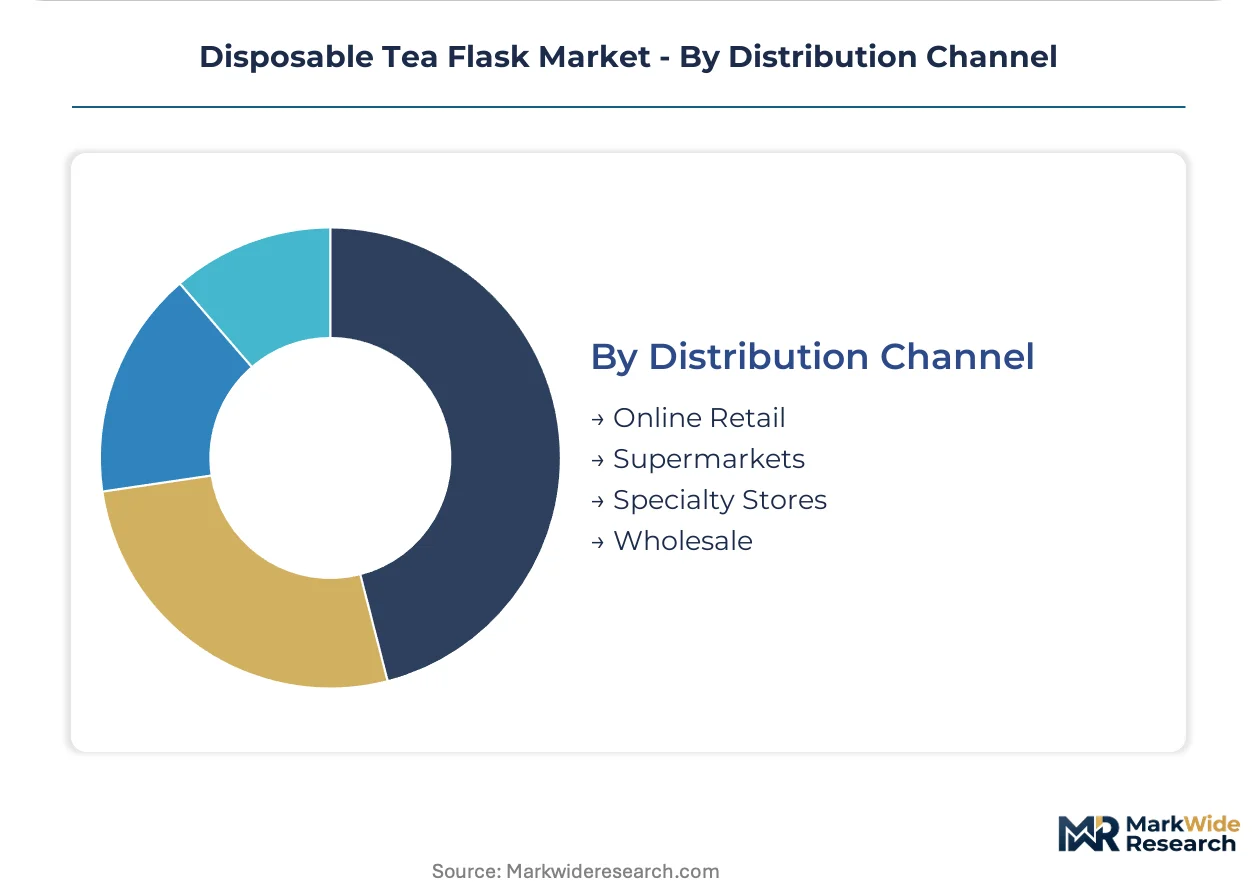
Wholesale moves the bulk of commercial volume; Online Retail is climbing the fastest on customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in China's coastal provinces and India's western manufacturing belts, with regulatory divergence forcing parallel material validation tracks across jurisdictions. Demand nodes concentrate in metropolitan corridors where commuter density sustains high-throughput foodservice procurement.
China
SAMR's GB 4806 standards compress substitution timelines for hot-beverage contact materials. The Yangtze River Delta hosts thermoforming specialists racing to validate aluminum-oxide-coated PET barriers ahead of revised migration limits. Shanghai's foodservice distributors now require fluorine-free declarations backed by third-party testing.
India
FSSAI migration limits for brewed tea contact impose extended validation cycles on new laminate formulations. Maharashtra's converter belt around Mumbai supplies high-volume orders to café chains along the Western Railway corridor. Delhi-NCR's institutional catering operators are consolidating procurement through direct-to-operator digital platforms.
Germany
REACH Annex XVII restrictions eliminate legacy PFAS coatings from import channels. Bavaria's packaging specialists supply aluminum-oxide-coated barriers to premium café chains demanding oxygen performance under humid conditions. Munich's foodservice distributors pre-certify supply bases to avoid customs detention risk.
United States
EPA state-level extended producer responsibility schemes are emerging in California and New York. The US Gulf Coast's captive polyethylene networks create input cost volatility for non-integrated converters. Texas-based resin producers supply multi-layer laminate converters serving quick-service restaurant chains.
Switzerland
Swissmedic-aligned food-contact standards exceed baseline EU requirements for specialty tea applications. Zurich's premium retailers curate borosilicate and aluminum-lacquer formats for ceremonial consumption occasions. Geneva's catering operators specify vacuum-insulated large-format units for corporate event batch dispensing.
Disposable Tea Flask Market Competitive Environment
Concentration sits with integrated laminate specialists and resin-captive volume producers. The market structure tiers into performance-grade barrier fabricators, commodity thermoformers, and cold-chain logistics integrators. Strategic moves center on material certification pre-positioning and distributor relationship compression through direct digital channels.
Among European-based laminate specialists, Huhtamaki Oyj exemplifies the performance-tier archetype through its temperature-stable supply positioning. Dart Container Corporation and Pactiv Evergreen Inc. occupy distinct volume-logistics niches, with the former representing resin-integrated scale economics and the latter anchoring chilled-chain compatibility across foodservice portfolios. These three entities illustrate how qualification depth and infrastructure control separate competitive tiers.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Dart Container Corporation |
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Berry Global Inc. |
| Sanex Packaging Connections Pvt. Ltd. |
| Arora Packaging Point |
| Shreeji Packaging Solutions |
| EcoFlask Innovations |
| Others |
Value Chain & Pricing Dynamics
Sixty-day resin inventory cycles in the US Gulf Coast create asymmetric pricing power between integrated polyethylene producers and non-captive converters, compressing margins for latter-tier participants while GB 4806 compliance costs in China and FSSAI migration testing in India layer certification premiums onto landed costs.
Pricing Analysis
GB 4806 compliance mandates from China's SAMR dictate the pricing tier structure across the disposable tea flask market. Three-tier pricing structure across premium, standard, and economy levels separates aluminum-oxide-coated PET barrier specialists from commodity thermoformers and uncoated polypropylene cup producers. Price differentiation hinges on fluorine-free certification status and vacuum insulation performance grade. Cost compression in the standard tier is intensifying because captive resin networks in Texas and Louisiana feed integrated volume players. Household retail channels exhibit highest price sensitivity; premium café chains in Germany and Switzerland demonstrate lowest sensitivity due to brand positioning requirements.
Supply Chain Analysis
Sixty-day resin inventory cycles expose non-integrated converters to input cost volatility when Gulf Coast petrochemical outages disrupt polyethylene supply. Manufacturing concentrates in China's Yangtze River Delta, India's Maharashtra belt around Mumbai, and Germany's Bavaria region. Raw material portfolios draw from polyethylene terephthalate resin, aluminum oxide coating chemistries, and bio-based barrier substrates. Single-source vulnerability sits with US Gulf Coast ethylene crackers supplying North American laminate converters. Distribution runs through direct-to-operator digital platforms in Indian metropolitan clusters and consolidated foodservice distributors in European import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as stainless steel tumbler rental schemes in corporate campuses displace single-use flask procurement at scale, requiring material certification pre-positioning and channel relationship compression to preserve wallet share.
For Market Incumbents: Secure fluorine-free barrier certification ahead of REACH Annex XVII enforcement timelines to avoid customs detention risk in European import channels. Backward integration into aluminum oxide coating capacity insulates margin structure from specialty chemical supply constraints. Channel control through direct digital platforms compresses distributor markups that previously absorbed 12-15 percent of landed cost in Indian metropolitan procurement.
For New Entrants and Emerging Players: FSSAI fast-track certification for brewed tea contact materials opens penetration into Maharashtra's converter belt supplying Mumbai café chains along the Western Railway corridor. White-space concentration sits with chilled-chain compatible formats for iced tea and cold-brew segments where Pactiv Evergreen's infrastructure creates reference customer access. Digital print personalization capability enables micro-batch branding for regional chains without plate-change tooling investment.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance premium play because migration testing burdens and compostability certification timelines create durable moats around qualified laminate specialists. Acquisition targets center on European aluminum-oxide-coated PET barrier fabricators with pre-certified supply relationships to German and Swiss premium café chains. The signal to watch is SAMR acceleration of GB standard revision cycles outpacing typical stability testing protocols, which would compress valuation multiples for non-compliant capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Certification | Eliminates customs detention risk under REACH Annex XVII for European import channels. |
| Direct-to-Operator Digital Platform | Compresses distributor markups in Indian metropolitan foodservice procurement corridors. |
| Vacuum Insulation Scale-Up | Thermoforming advances enable cost-efficient multi-layer wall structures for premium tier. |
| Extended Producer Responsibility Integration | India's evolving EPR schemes create first-mover advantage for recyclate-integrated production. |
| Aluminum Oxide Coating Backward Integration | Insulates margin structure from specialty chemical supply constraints in barrier film production. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FSSAI compliance filings, EU Single-Use Plastics Directive implementation reports, and SAMR GB standard revision notices. Primary interviews engaged thermoforming plant managers, foodservice procurement leads at Mumbai and Delhi café chains, barrier film R&D directors, and distribution channel partners in German import markets. Secondary validation drew from customs trade data, SEC 10-K disclosures by resin-integrated packaging producers, and extended producer responsibility scheme documentation. Bottom-up capacity assessments and top-down demand triangulation anchored value estimates.
Segmentation dimensions modeled include material type, size configuration, end-user category, and distribution channel structure across the analysis window. Volume and value outputs reflect reconciliation between converter capacity surveys and foodservice procurement flow analysis. CAGRs were derived from trend extrapolation of commuter density patterns, regulatory substitution timelines, and thermoforming technology adoption curves. Industry-specific forecast inputs incorporated FSSAI migration testing cycle durations and EU compostability certification penetration rates.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement intensity and no disruptive reusable format adoption acceleration; material deviation would warrant model refresh. Specific risk factors include SAMR timeline compression outpacing validation protocols, Gulf Coast resin supply disruption, and corporate campus tumbler rental scheme expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Media Bottles Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Bottle Dividers Market