
 Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market | 2026-2036
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market Foresight
Risk-sharing agreements and outcomes-based reimbursement models is reconfiguring capital deployment across the FSGS pipeline, allowing smaller developers to retain program control without full commercial infrastructure buildout. Travere Therapeutics leverages its renal-disease specialization to anchor payer negotiations for novel mechanism therapies. Genentech sustains competitive presence through deep nephrology clinical networks and biologics manufacturing scale. Vertex Pharmaceuticals differentiates via cystic fibrosis-derived precision-medicine capabilities that extend into rare kidney disease target identification.
Focal segmental glomerulosclerosis therapeutics comprise pharmacological interventions targeting podocyte injury, proteinuria reduction, and fibrosis progression in glomerular filtration barriers, with formulations spanning small molecules, monoclonal antibodies, and cell-based approaches designed to delay dialysis dependency. Immunosuppressants and corticosteroids currently dominate prescription volume but face margin compression from generic erosion, while biologics and novel small molecules capture expanding reimbursement pools due to superior proteinuria response rates and differentiated safety profiles. Injectable formulations lead in acute settings, though oral administration and sustained release systems are gaining protocol share in maintenance therapy segments where patient compliance directly correlates with renal survival outcomes.
The FDA's accelerated approval framework and EMA's orphan drug incentives shape trial design and market access timelines for FSGS developers, while the EU AI Act introduces compliance requirements for algorithmic patient stratification tools increasingly used in precision nephrology. China's NMPA has expanded priority review channels for innovative renal therapies, altering geographic launch sequencing for multinational sponsors. Stakeholders must monitor evolving biomarker qualification standards and payer evidence requirements that will determine which mechanistic classes secure durable formulary positioning.
Market Dynamics
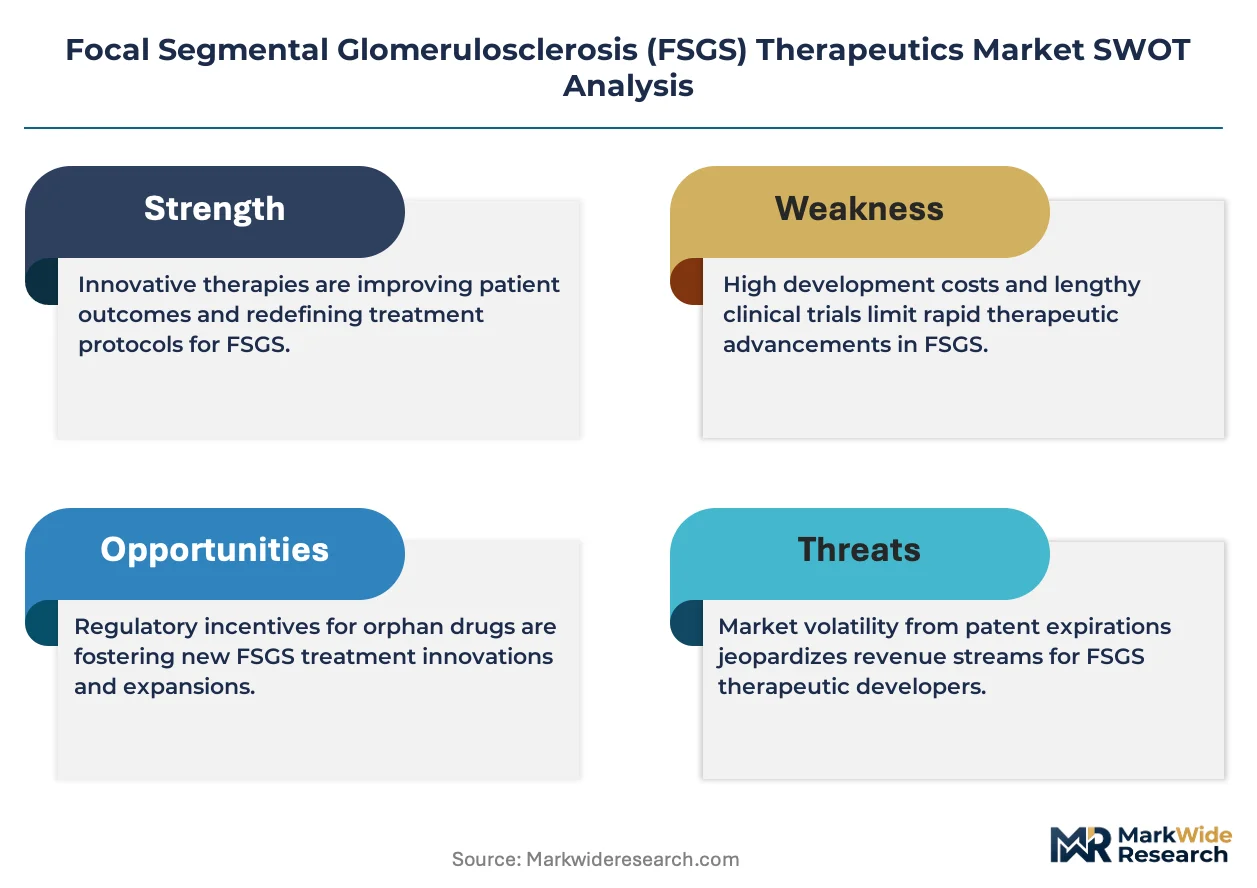
Accelerated FDA approval pathways for rare kidney diseases are compressing clinical trial timelines and redistributing capital toward mechanistic validation rather than traditional efficacy endpoints, forcing developers to build biomarker strategies before Phase II initiation.
Growth Catalysts
- EMA Orphan Drug Incentives:Extended market exclusivity provisions in Europe are sustaining investment in podocyte-targeted biologics despite small addressable populations.
- Specialty Hospital Expansion:Dedicated nephrology centers in the United States are standardizing protocol adoption for novel proteinuria-reduction therapies.
- Biomarker-Qualified Surrogate Endpoints:FDA's evolving guidance on proteinuria as a surrogate is enabling smaller, faster registrational trials.
Market Restraints
- Plasma-Derived Biologic Input Costs:Immunoglobulin and albumin supply volatility constrains manufacturing margins for antibody-based FSGS therapies.
- Single-Site Contract Manufacturing Concentration:Fill-finish capacity for injectable renal biologics clusters in the Boston-Cambridge corridor, creating geographic supply risk.
- Generic Corticosteroid Erosion:Prednisone and calcineurin inhibitor commoditization compresses pricing power in first-line maintenance segments.
Strategic Opportunities
- China NMPA Priority Review Channels:Accelerated timelines for innovative renal therapies are enabling earlier geographic diversification beyond US-EU launch sequences.
- Oral Small Molecule Formulations:Patient compliance advantages in maintenance therapy create white space against injectable biologic standards of care.
- AI-Enabled Patient Stratification:Machine learning tools for genetic risk scoring are converging with EHR integration to enable precision nephrology protocols.
Industry Challenges
- Podocyte Biology Talent Scarcity:Specialized renal pathologist and translational nephrologist recruitment bottlenecks delay preclinical-to-clinical transitions.
- Biomarker Qualification Timeline Compression:FDA's evolving evidentiary standards for proteinuria surrogates force parallel rather than sequential development paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market |
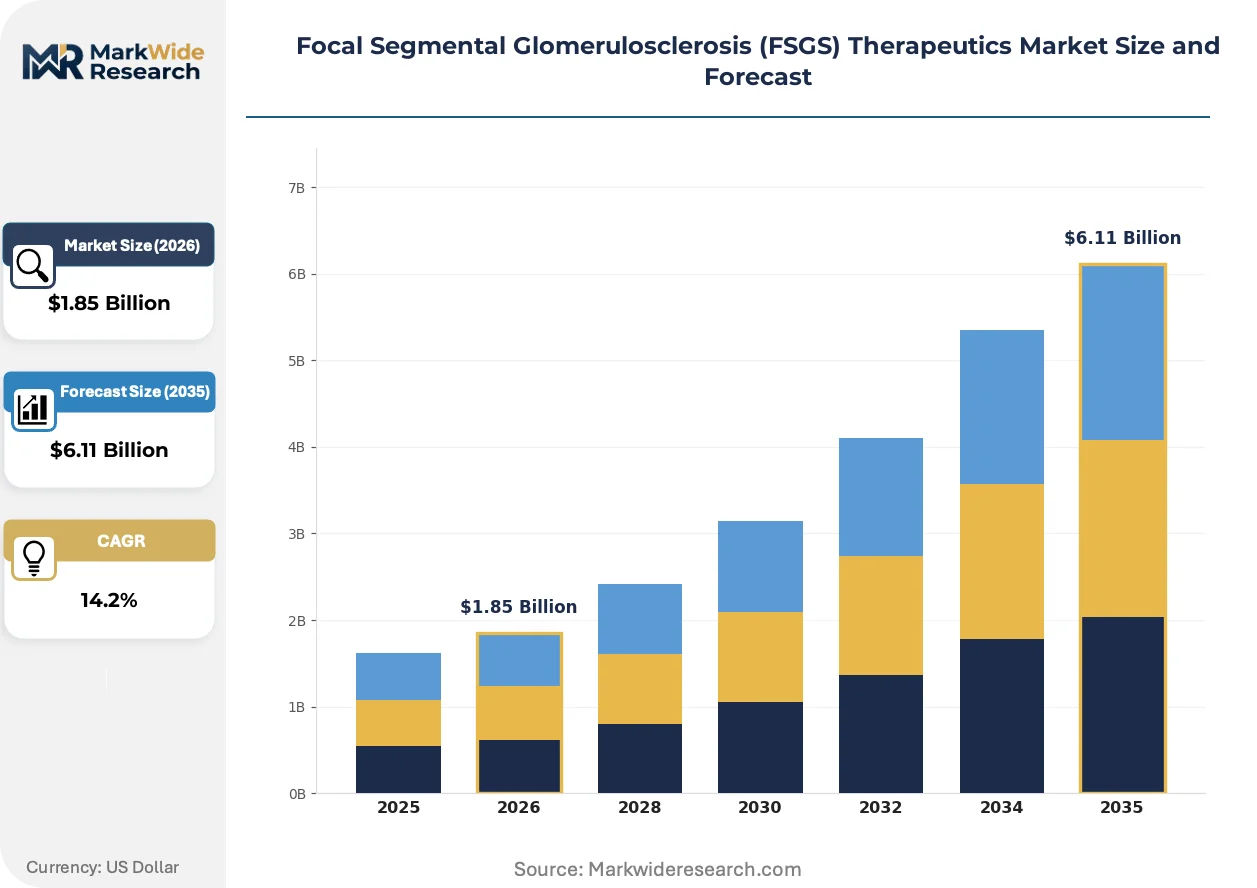
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Biologics, Novel Small Molecules, Corticosteroids, Antifibrotic Agents Therapy Area: Nephrotic Syndrome, End-Stage Renal Disease, Proteinuria Management, Chronic Kidney Disorder, Glomerular Diseases End User: Nephrology Clinics, Dialysis Centers, Specialty Hospitals, Research Institutes, Ambulatory Care Centers Delivery Mode: Oral Administration, Injectable Formulations, Intravenous Therapy, Subcutaneous Injection, Sustained Release Systems |
| Companies Covered | Travere Therapeutics, ACELYRIN Inc., Genentech, ChemoCentryx, Dimerix, Goldfinch Bio, Vertex Pharmaceuticals, AstraZeneca, Chinook Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market Shifts & Advancements
Digital biomarker infrastructure and decentralized trial models are collapsing the distance between patient identification and protocol enrollment, compressing recruitment timelines that previously stalled rare disease development.
Spatial transcriptomics platforms are virtualizing glomerular tissue analysis, enabling molecular phenotyping without repeat biopsy. Academic medical centers in the United States are adopting these systems at pilot scale. The technology is virtualizing histopathology workflows while reducing patient burden in longitudinal studies.
The EU AI Act's risk classification framework for clinical decision-support tools is imposing documentation burdens on algorithmic patient stratification systems. Nephrology developers must now maintain technical files for genetic risk scoring applications. European sites are responding by segregating AI-enabled screening from primary diagnostic workflows.
Payer contracting for FSGS therapies is fragmenting across risk-bearing entities and traditional fee-for-service arrangements. Integrated delivery networks in the United States are consolidating formulary control, displacing individual physician prescribing autonomy. This concentration is most visible in Medicare Advantage populations where capitated renal care bundles dominate.
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market Segmentation
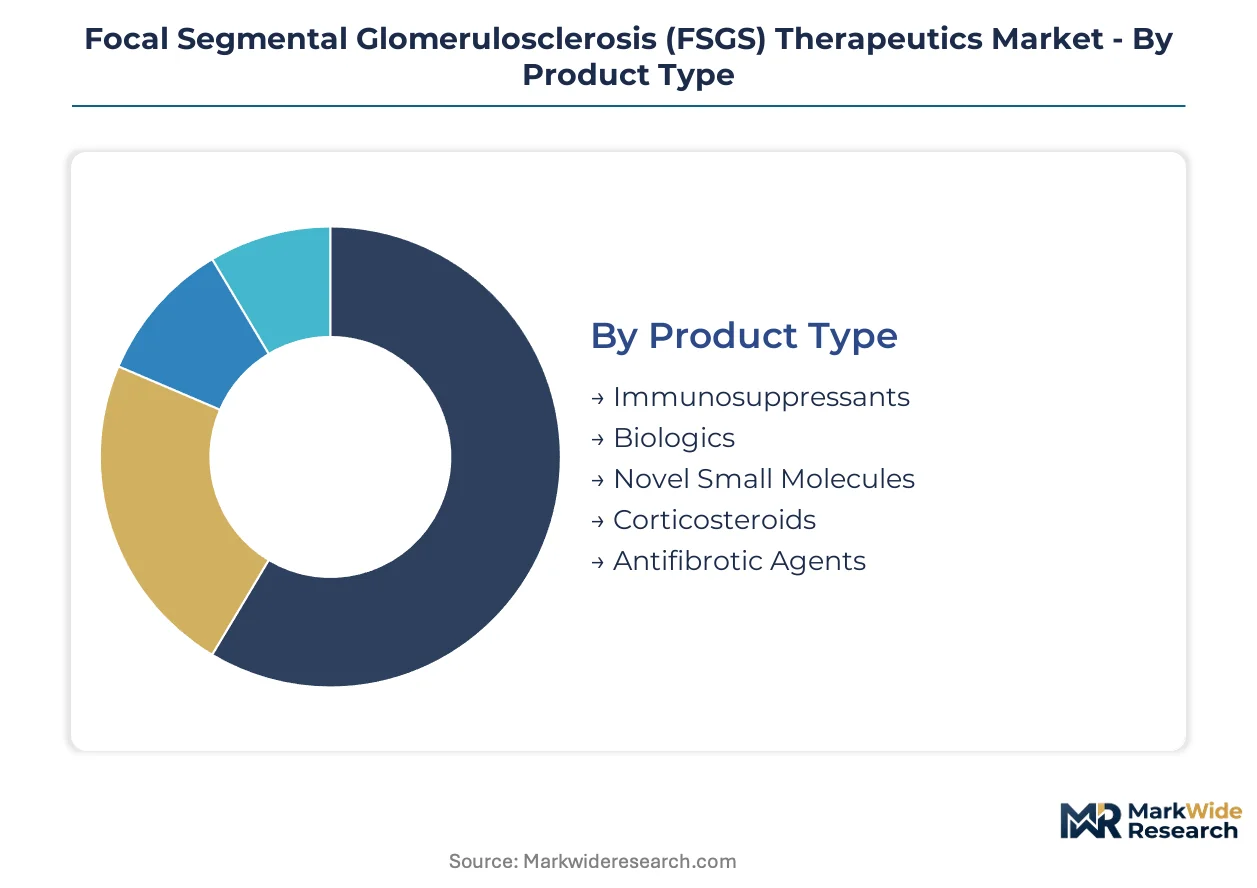
FSGS therapeutic development fragments across mechanism classes, clinical settings, and administration pathways that each carry distinct regulatory, reimbursement, and manufacturing requirements. Understanding these segment boundaries reveals where capital concentrates and where white space persists for differentiated entry.
Product Type:
Cost tier stratification separates commoditized standards of care from premium-priced novel mechanisms with differentiated efficacy evidence.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites constitute the volume backbone of maintenance therapy. Nephrology clinics in the United States prescribe these agents for steroid-dependent cases where payer formularies prioritize cost containment over mechanistic novelty.
- Biologics:Monoclonal antibodies targeting podocyte-specific pathways command reimbursement premiums through orphan drug designation. Specialty hospitals anchor adoption where integrated delivery networks negotiate risk-based contracts for proteinuria reduction outcomes.
- Novel Small Molecules:Oral agents with targeted kinase inhibition profiles are gaining protocol share in maintenance segments.
- Corticosteroids:Prednisone protocols face margin compression from generic substitution.
- Antifibrotic Agents:Emerging pipeline candidates target TGF-beta signaling in fibrosis progression.
Biologics holds installed capacity. Novel Small Molecules is rotating up the share rankings.
Therapy Area:
Application focus determines trial design complexity and the evidentiary threshold for regulatory acceptance.
- Nephrotic Syndrome:Heavy proteinuria presentations drive the largest addressable population within FSGS. Pediatric nephrology centers concentrate recruitment for novel agents targeting steroid-resistant variants where unmet need is most acute.
- Proteinuria Management:Surrogate endpoint strategies favor this segment for accelerated approval pathways. The FDA's evolving biomarker qualification standards enable smaller registrational trials when proteinuria reduction serves as the primary endpoint.
- End-Stage Renal Disease:Dialysis-dependent populations require different safety profiles given comorbidity burden.
- Chronic Kidney Disorder:Broader diagnostic category with overlapping etiologies.
- Glomerular Diseases:Histopathology-confirmed segment with highest diagnostic precision.
Nephrotic Syndrome holds installed capacity. Proteinuria Management is climbing the fastest.
End User:
Customer type concentration shapes go-to-market infrastructure requirements and prescribing autonomy patterns.
- Specialty Hospitals:Academic medical centers with dedicated nephrology divisions standardize protocol adoption for novel therapies. These institutions anchor clinical trial networks and influence downstream community prescribing through fellowship training pipelines.
- Nephrology Clinics:Outpatient-focused practices manage the majority of maintenance therapy volume. Medicare Advantage capitation models are consolidating formulary control within integrated delivery networks serving these clinics.
- Dialysis Centers:Fresenius and DaVita networks concentrate end-stage renal disease patients.
- Research Institutes:NIH-funded centers drive biomarker discovery and natural history studies.
- Ambulatory Care Centers:Lower-acuity settings with limited infusion capacity.
Specialty Hospitals holds installed capacity. Nephrology Clinics is gaining share fastest.
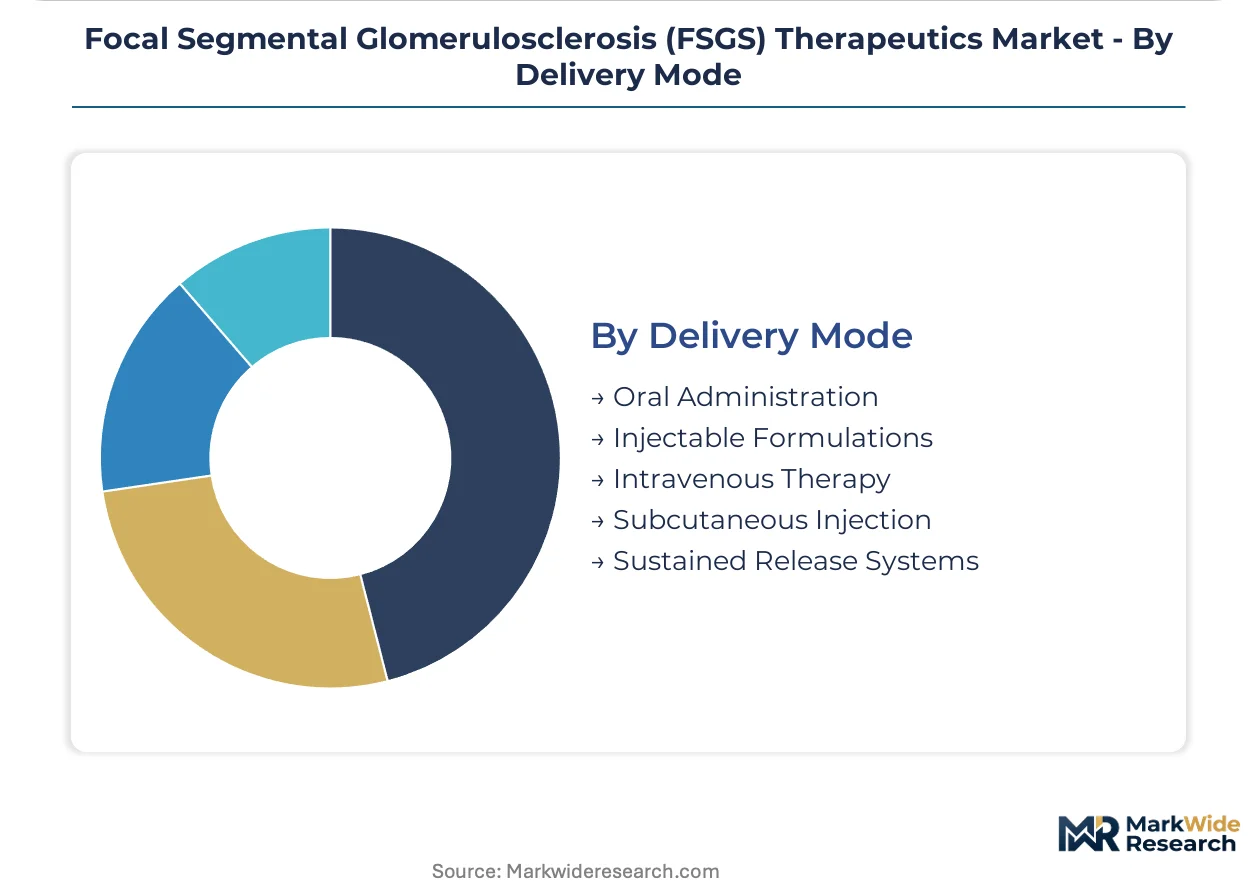
Delivery Mode:
Administration pathway selection directly correlates with patient compliance and renal survival outcomes in longitudinal maintenance settings.
- Injectable Formulations:Intravenous and subcutaneous biologics dominate acute intervention protocols. Fill-finish capacity constraints in the Boston-Cambridge corridor create geographic supply risk for these high-value products.
- Oral Administration:Small molecule tablets and capsules enable patient self-management in maintenance phases. Compliance advantages create white space against injectable standards of care where travel burden and infusion center capacity limit access.
- Intravenous Therapy:Hospital-based administration for acute proteinuria crises.
- Subcutaneous Injection:Home-administered biologics with specific cold-chain requirements.
- Sustained Release Systems:Depot formulations in development to extend dosing intervals.
Injectable Formulations holds installed capacity. Oral Administration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net therapeutic exports from the United States and Switzerland offset import dependence on biologic active pharmaceutical ingredients from China and India, creating asymmetric regional value capture in the FSGS pipeline.
United States
Specialty hospital networks in Boston and the Research Triangle anchor clinical trial enrollment for novel podocyte-targeted therapies. FDA's accelerated approval pathways for rare kidney diseases compress development timelines for sponsors. The Cambridge-Boston corridor concentrates fill-finish manufacturing capacity for injectable biologics, creating geographic supply risk during capacity constraints.
Germany
Academic medical centers in Munich and Heidelberg standardize protocol adoption for proteinuria-reduction therapies across EU nephrology networks. EMA orphan drug incentives sustain investment despite small addressable populations. The Rhine-Ruhr region hosts contract manufacturing organizations serving mid-stage biologic development programs.
China
Nephrology clinics in Shanghai and Beijing drive demand for maintenance therapy formulations as chronic kidney disease prevalence rises. NMPA priority review channels accelerate timelines for innovative renal therapies, enabling earlier geographic diversification for multinational sponsors. The Yangtze River Delta concentrates domestic biologics manufacturing investment.
Japan
Specialty hospitals in Tokyo and Osaka maintain stringent evidentiary standards for formulary inclusion of novel mechanisms. PMDA consultations on biomarker qualification shape trial designs for proteinuria surrogate endpoints. The Kansai region anchors domestic clinical research organization capacity for renal indication studies.
United Kingdom
NHS England's specialized commissioning frameworks concentrate prescribing authority for high-cost biologics in designated nephrology centers. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for rare disease therapies. The London-Oxford-Cambridge triangle hosts biomarker discovery platforms advancing precision nephrology.
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market Competitive Landscape
On the supply side, the industry is consolidating around renal-specialized biopharmaceutical developers with dedicated nephrology clinical networks and risk-sharing payer contracting capabilities. Large-cap diversified pharmaceutical companies retain presence through biologics manufacturing scale and established hospital formulary relationships. Three archetypes dominate: pure-play rare kidney disease specialists, diversified biologics manufacturers with nephrology divisions, and precision-medicine platforms extending into podocyte biology. Competitive moves center on strategic partnerships for biomarker qualification and geographic licensing arrangements for China and Japan market access.
Within the pure-play specialist tier, Travere Therapeutics and Chinook Therapeutics occupy positions defined by renal-disease focus and payer negotiation specialization. Among diversified biologics manufacturers, Genentech exemplifies scale-driven clinical network leverage. Vertex Pharmaceuticals sits within the precision-medicine archetype, extending genetic disease capabilities into rare kidney target identification. These three represent distinct strategic postures without implying specific market share or pipeline prioritization.
| Leading Market Players |
|---|
| Travere Therapeutics |
| ACELYRIN Inc. |
| Genentech |
| ChemoCentryx |
| Dimerix |
| Goldfinch Bio |
| Vertex Pharmaceuticals |
| AstraZeneca |
| Chinook Therapeutics |
| Others |
Supply & Pricing Matrix
Fill-finish undercapacity in the Boston-Cambridge corridor concentrates bargaining power among contract manufacturers, enabling premium pricing for injectable biologics while forcing developers to accept extended lead times or anchor production in lower-cost geographies. This utilization asymmetry shapes how Travere Therapeutics and Chinook Therapeutics structure risk-sharing contracts with integrated delivery networks, trading price concessions for formulary access.
Pricing Analysis
Integrated delivery networks anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on orphan drug designation status and proteinuria response rate certification. Cost compression in the corticosteroid maintenance tier is intensifying because generic prednisone substitution has eroded branded pricing power. Nephrology clinics in Medicare Advantage capitation models exhibit highest price sensitivity, while specialty hospitals negotiating outcomes-based contracts show lowest sensitivity due to risk-bearing structures.
Supply Chain Analysis
Extended payment terms from multinational sponsors now fund working capital for plasma-derived biologic suppliers, shifting financial risk upstream. Manufacturing concentrates in the United States, Switzerland, and China. Active pharmaceutical ingredients draw from immunoglobulin fractionation facilities, recombinant cell culture media, and specialized fill-finish equipment. Single-source vulnerability clusters in the Boston-Cambridge fill-finish corridor. Distribution runs through cold-chain logistics networks serving specialty hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-enabled patient monitoring services expand faster than pharmaceutical hardware, creating recurring-revenue layers that outperform traditional drug margins. This service-attach dynamic reconfigures how developers structure payer contracts and clinical trial offerings.
For Market Incumbents: Build regulatory data moats through accelerated FDA approval pathway expertise. Anchor formulary positioning by deepening nephrology clinical network penetration against emerging podocyte-targeted biologics. Invest in biomarker qualification capabilities before Phase II initiation to compress competitor trial timelines. Lock in fill-finish capacity through long-term manufacturing agreements in the Boston-Cambridge corridor. For New Entrants and Emerging Players: Build out oral small molecule development capabilities to exploit compliance advantages in maintenance therapy segments. Target nephrology clinics in Medicare Advantage networks where capitated renal care bundles concentrate prescribing authority. Penetrate China NMPA priority review channels ahead of US-EU launch sequences. Establish risk-sharing pilot programs with integrated delivery networks to secure initial formulary access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among renal-specialized biopharmaceutical developers with biomarker-enabled monitoring platforms. Long-term viability favors archetypes combining precision nephrology target identification with payer negotiation specialization. Target acquisition profiles center on podocyte biology talent density and qualified proteinuria surrogate endpoint packages. Watch FDA biomarker guidance evolution as the signal for which mechanistic classes secure durable reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Pathway | FDA's evolving proteinuria surrogate standards enable smaller registrational trials for podocyte-targeted therapies. |
| Risk-Sharing Contract Structure | Outcomes-based agreements with integrated delivery networks displace traditional fee-for-service prescribing autonomy. |
| Geographic Licensing Arrangement | China NMPA priority review channels accelerate market entry beyond conventional US-EU launch sequencing. |
| Manufacturing Scale-Up | Fill-finish capacity expansion in the Boston-Cambridge corridor reduces geographic supply concentration risk. |
| Pipeline Diversification | Oral small molecule programs target maintenance therapy compliance gaps against injectable biologic standards. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists anchors the qualitative findings. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up modeling of prescription volumes and top-down reconciliation against therapeutic class expenditure estimates completes the triangulation.
Calibration against historical proteinuria endpoint qualification timelines and orphan drug approval patterns shapes the analytical framework across the analysis window. Segmentation dimensions include mechanism class, therapy area, end-user setting, and administration route. CAGRs derive from fitted growth curves applied to biomarker adoption rates and payer contracting velocity. Forecast inputs incorporate evolving FDA accelerated approval guidance and EMA orphan drug incentive utilization.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision-medicine platforms or diversified biologics manufacturers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Prescription Drugs Market