
 Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market | 2026-2036
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market Foresight
Pharmaceutical-grade flavor purity specifications are redrawing competitive boundaries in OTC formulations. Givaudan SA leverages its integrated taste-modulation platform to supply compliant flavor systems for pediatric acetaminophen syrups. International Flavors & Fragrances Inc. anchors North American supply through its dedicated pharma flavor division with USP-grade certification. Symrise AG specializes in natural masking technologies that neutralize bitter active pharmaceutical ingredients without synthetic additives.
Flavors into over-the-counter pharmaceuticals encompasses the formulation, compounding, and integration of organoleptically optimized taste agents into non-prescription drug products, typically involving volatile oil concentrations of 0.1-2.0% w/v, emulsion stability parameters, and compatibility testing with APIs such as dextromethorphan or ibuprofen to ensure shelf-life stability and patient acceptability. The primary commercial purpose is to reduce medication refusal rates, particularly among pediatric and geriatric populations, thereby improving therapeutic outcomes and brand loyalty for self-medication products. Analgesics and cough & cold remedies represent the most mature flavor application segments where mint and citrus profiles dominate established brand portfolios, while vitamins & supplements constitute the fastest-expanding category as gummy and liquid formats attract adult consumers seeking palatable daily regimens. Berry and herbal flavor types are capturing margin pools in premium-positioned products targeting wellness-oriented demographics through natural-positioned labeling claims.
FDA compliance with 21 CFR requirements for inactive ingredients and USP-NF monograph standards governs flavor incorporation into OTC products, while EMA guidelines on excipient quality and ICH Q3C residual solvent specifications shape formulation protocols for multinational portfolios. The EPA's oversight of flavor chemical manufacturing emissions and OSHA permissible exposure limits for volatile organic compounds in compounding facilities add operational compliance layers that influence supplier qualification and site selection. Stakeholders must monitor evolving pediatric palatability guidance from FDA and EMA, as these agencies tighten child-appropriate taste assessment protocols that will determine which flavor houses retain preferred supplier status in regulated OTC supply chains.
Market Dynamics
Pediatric medication adherence failures are forcing reformulation investments across OTC portfolios, as bitter active pharmaceutical ingredients drive refusal rates above 40% in children under 12. Flavor houses now compete on USP-grade certification and natural-positioned masking technologies rather than commodity taste profiles.
Growth Catalysts
- FDA pediatric palatability guidance:Updated protocols for child-appropriate taste assessment are mandating standardized testing, expanding demand for validated flavor systems in acetaminophen and ibuprofen syrups.
- Gummy format migration:Adult vitamin and supplement buyers are rejecting tablet formats, pulling pharmaceutical-grade flavoring into chewable delivery systems at double-digit volume expansion.
- Pharmacy chain private-label prioritization:US retail consolidation around consumer-tested flavor profiles for cough and cold remedies is concentrating procurement with certified suppliers capable of rapid SKU replication.
Market Restraints
- Natural extract supply volatility:Berry and herbal flavor sourcing from agricultural regions faces climate-driven harvest inconsistency, compressing margin stability for clean-label positioned products.
- Swissmedic excipient purity thresholds:Stricter residual solvent specifications than FDA baselines are fragmenting supplier qualification, forcing dual-track formulation development for multinational portfolios.
- Synthetic flavor substitution pressure:Cost-sensitive mass-market analgesic producers in developing markets are reverting to artificial taste agents, constraining premium natural flavor penetration.
Strategic Opportunities
- Geriatric dysphagia formulations:Japan's aging population is driving demand for palatable orally disintegrating tablets, opening specialized flavor-masking applications beyond pediatric defaults.
- EMA sustainability-linked procurement:Green chemistry incentives for bio-based flavor production are creating preferred supplier status for houses with verified carbon-reduction pathways.
- Direct-to-consumer subscription channels:Wellness brands bypassing pharmacy retail are commissioning custom flavor profiles for personalized vitamin regimens, fragmenting traditional B2B concentration.
Industry Challenges
- Cross-functional formulation expertise scarcity:Chemists combining organoleptic science with API stability knowledge command premium compensation, constraining mid-tier flavor house expansion.
- Legacy ERP integration with track-and-trace mandates:US DSCSA serialization requirements are forcing costly software overhauls for smaller compounders serving regional OTC brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market |
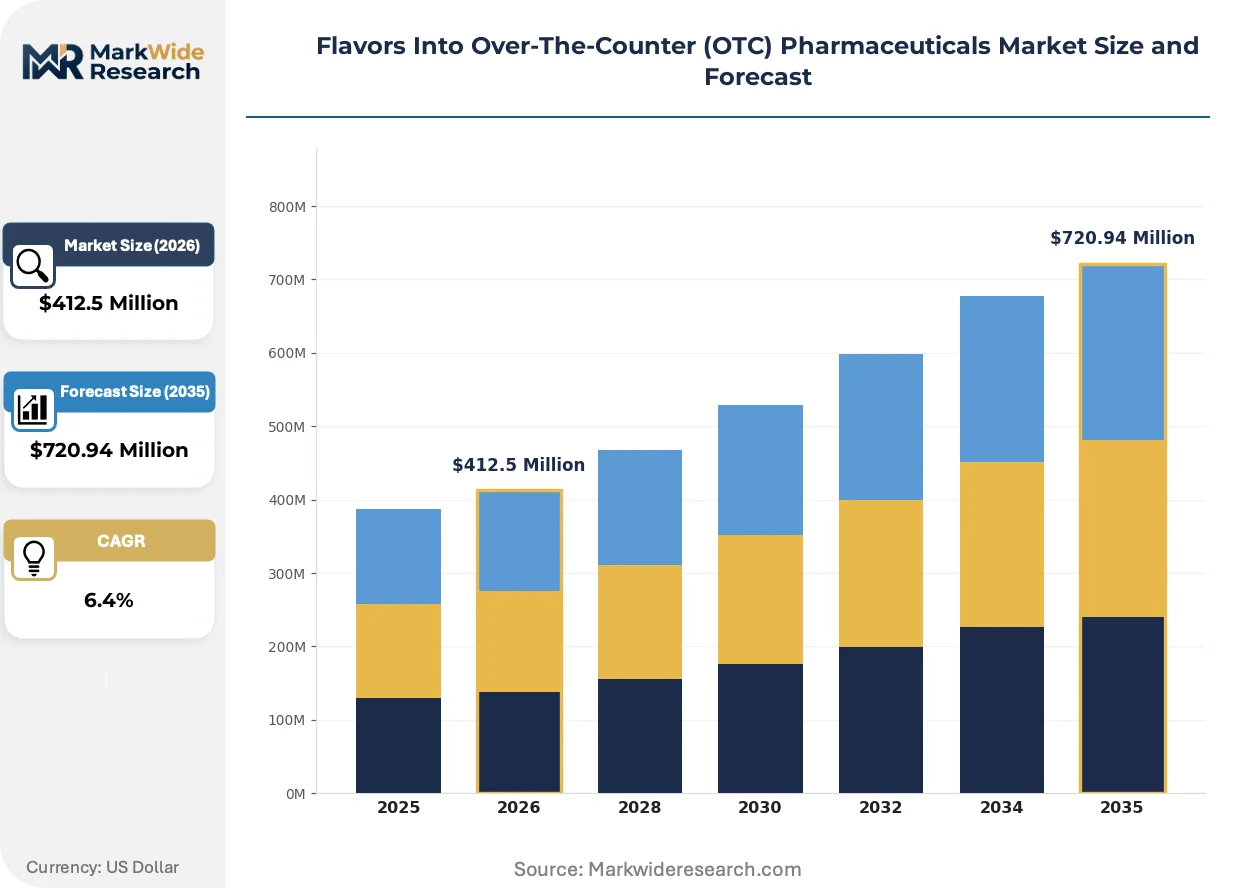
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Cough & Cold Remedies, Antacids, Vitamins & Supplements, Topical Ointments Flavor Type: Mint, Citrus, Berry, Herbal, Vanilla, Spices End User: Pharmacies, Drug Stores, Hospitals, Clinics, Health & Wellness Centers Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Mass Merchandisers, Direct Sales |
| Companies Covered | Givaudan SA, International Flavors & Fragrances Inc., Symrise AG, Kerry Group, DSM-Firmenich, Sensient Technologies Corp., Frutarom, Firmenich, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market Shifts & Advancements
Clean-label positioning is compressing synthetic additive tolerance across OTC categories, forcing flavor suppliers to demonstrate natural-origin provenance through blockchain-verified supply chains. Reformulation velocity is accelerating as brand owners respond to palatability failures in real-time through social media monitoring.
Encapsulated bitter-blocking technologies using cyclodextrin complexes are displacing traditional sucrose-based taste masking in pediatric liquid formulations. Major acetaminophen syrup producers in the United States are adopting these systems within 18-month procurement cycles. The shift is displacing conventional flavor-overload strategies that relied on high sweetness intensity to mask API astringency, reducing sugar content claims that conflict with pediatric dental health positioning.
REACH restrictions on volatile organic compound emissions from flavor manufacturing are tightening residual solvent thresholds for European-bound OTC products. ECHA enforcement is pushing reformulation of mint and citrus oil emulsions toward aqueous-based delivery systems. Cough and cold remedy producers exporting to Germany and France are accelerating solvent substitution programs to maintain market access under evolving hazard classification protocols.
Retailer-controlled quality scorecards are reshaping supplier selection beyond price-point bidding. Pharmacy chains in the United States now weight consumer taste-test performance at 35% of procurement decisions, displacing legacy relationships based on volume discounts alone. This behavioral pivot concentrates contract awards with flavor houses maintaining dedicated sensory evaluation facilities capable of rapid consumer panel execution.
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market Segmentation
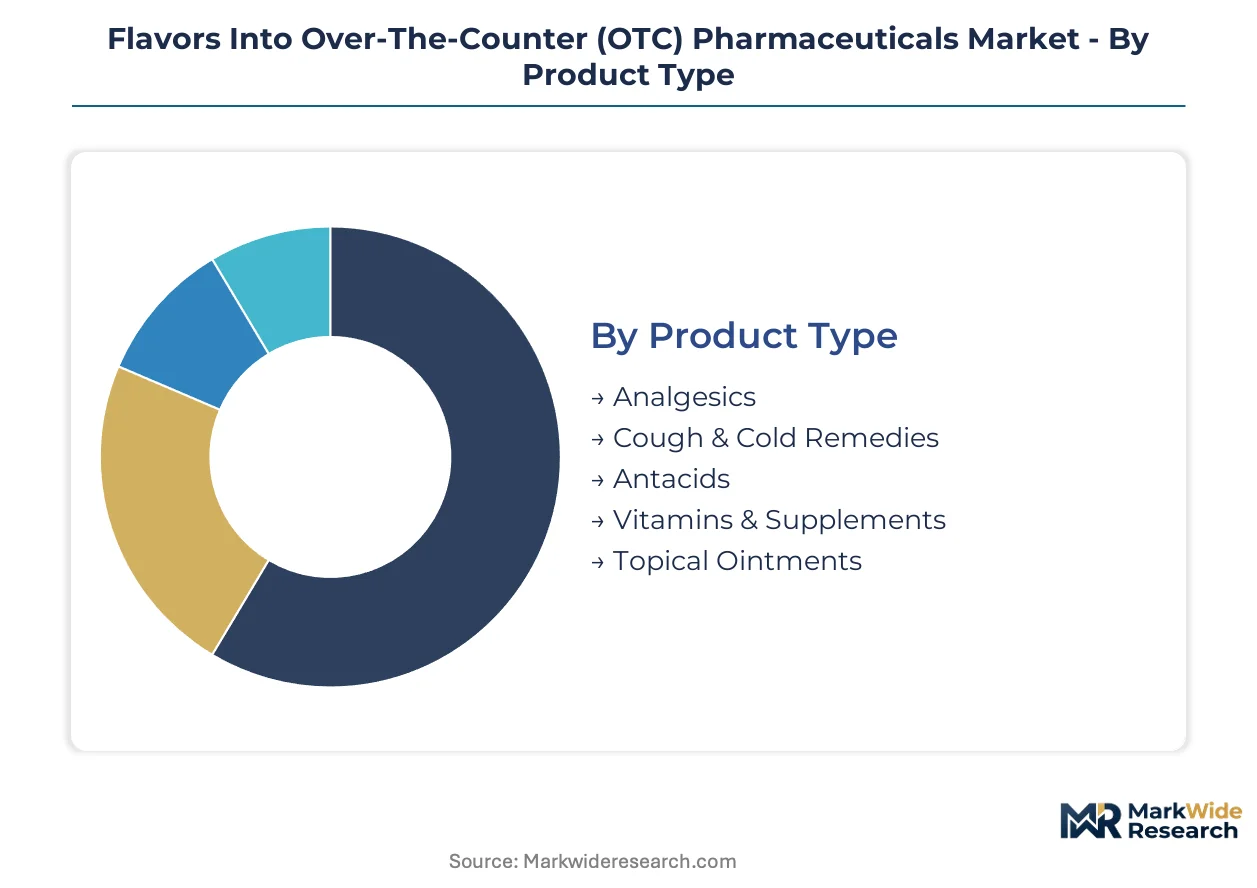
Segmentation in flavors for OTC pharmaceuticals reveals how formulation requirements diverge across therapeutic categories and patient populations. Each dimension carries distinct technical specifications, regulatory pathways, and procurement behaviors that shape supplier strategies.
Product Type:
Domestic consumption in the United States dominates analgesics and cough formulations, while vitamins and supplements show stronger export orientation toward European wellness markets.
- Analgesics:Acetaminophen and ibuprofen syrups require high-intensity masking systems to neutralize bitter API profiles, with mint and cherry flavors commanding procurement budgets at major US pharmacy chains.
- Cough & Cold Remedies:Dextromethorphan-based liquids depend on emulsion-stable flavor oils that withstand thermal processing; demand clusters in seasonal procurement cycles with private-label concentration at CVS and Walgreens.
- Antacids:Calcium carbonate suspensions need flavor systems compatible with high-pH matrices, typically citrus or mint profiles.
- Vitamins & Supplements:Gummy and liquid formats are pulling pharmaceutical-grade flavoring into chewable delivery systems at double-digit volume expansion.
- Topical Ointments:Menthol-camphor bases use volatile oil concentrations of 0.5-2.0% w/v for olfactory masking rather than taste.
Analgesics holds the largest share; momentum sits with vitamins and supplements.
Flavor Type:
Cost tier differentiation separates commodity synthetic profiles from premium natural-extract positioning, with price spreads of 3-5x between base and certified-organic grades.
- Mint:Peppermint and spearmint oils dominate analgesic and antacid applications through established USP-NF monograph compliance; sourcing concentrates in Midwestern US distillation facilities.
- Citrus:Orange and lemon profiles anchor pediatric cough syrups with high consumer recognition; cold-pressed oil volatility creates supply chain constraints.
- Berry:Strawberry and raspberry extracts command premium positioning in gummy vitamins through natural-label claims.
- Herbal:Echinacea and ginger profiles target wellness-oriented demographics with botanical provenance requirements.
- Vanilla:Synthetic vanillin remains cost-competitive for mass-market applications despite clean-label pressure.
- Spices:Cinnamon and clove find niche use in throat spray formulations with warming sensory cues.
Mint and citrus together dominate volume; berry and herbal are climbing the fastest on premium positioning.
End User:
Customer type determines formulation complexity, with hospital and clinic procurement demanding batch-level documentation that retail channels rarely require.
- Pharmacies:Chain-owned locations in the United States now weight consumer taste-test performance at 35% of procurement decisions, concentrating contract awards with houses maintaining dedicated sensory facilities.
- Drug Stores:Independent operators prioritize price-point bidding over flavor innovation, constraining supplier margin.
- Hospitals:Pediatric wards drive demand for validated palatability testing under FDA guidance protocols.
- Clinics:Urgent care settings favor single-dose flavor sachets for on-site compounding flexibility.
- Health & Wellness Centers:Subscription vitamin services commission custom profiles for personalized regimens, fragmenting traditional B2B concentration.
Pharmacies hold the largest share; momentum sits with health and wellness centers on direct-to-consumer bypass.
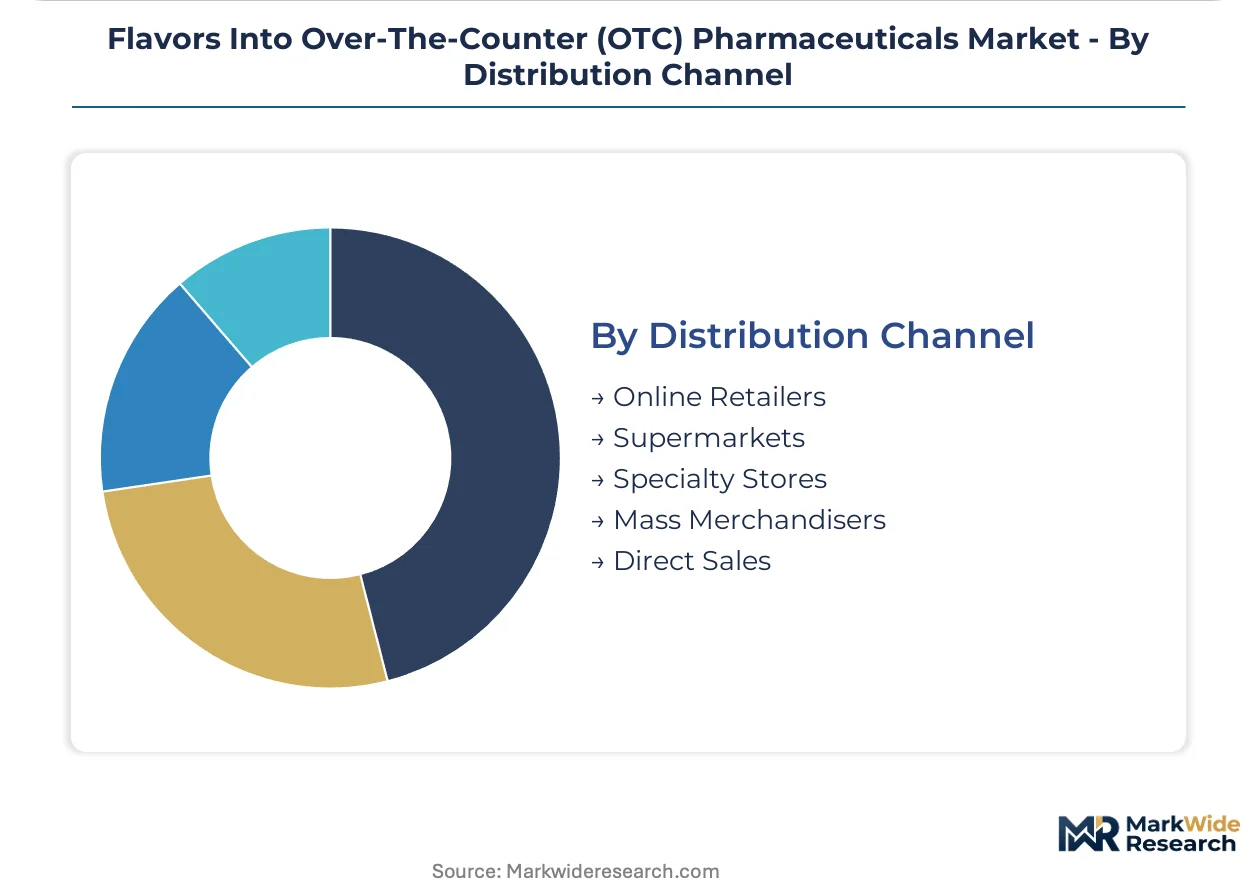
Distribution Channel:
Supply concentration varies sharply, with mass merchandisers and online retailers capturing volume while specialty stores maintain premium positioning.
- Online Retailers:Amazon and direct-brand storefronts enable rapid SKU testing with consumer feedback loops that accelerate reformulation cycles.
- Supermarkets:Kroger and Albertsons prioritize private-label cough and cold remedies with consumer-tested flavor profiles.
- Specialty Stores:GNC and Vitamin Shoppe demand USP-grade certification for supplement flavoring with full supply chain documentation.
- Mass Merchandisers:Walmart and Target concentrate procurement through centralized flavor specification programs.
- Direct Sales:Wellness brands bypass pharmacy retail entirely, commissioning exclusive flavor profiles for subscription vitamin regimens.
Mass merchandisers hold the largest share; momentum sits with online retailers on data-driven flavor optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland exports pharmaceutical-grade flavor systems to United States pharmacy chains, while India supplies natural extract intermediates to European wellness formulators. Trade corridors concentrate certified supply between regulatory jurisdictions with harmonized USP-grade standards.
United States
CVS and Walgreens private-label procurement drives demand for consumer-validated flavor profiles in cough and cold remedies. FDA pediatric palatability guidance mandates standardized taste testing for acetaminophen syrups. New Jersey and Pennsylvania host compounding clusters where flavor houses maintain dedicated sensory evaluation facilities.
Germany
EMA sustainability-linked procurement incentives pull bio-based flavor production into preferred supplier programs. REACH restrictions on volatile organic compound emissions tighten residual solvent thresholds for mint and citrus oil emulsions. Frankfurt-Rhine-Main corridor concentrates reformulation services for cough remedy exporters.
India
CDSCO alignment with ICH Q3C specifications enables contract manufacturing for multinational OTC brands seeking cost-optimized natural masking. FSSAI excipient quality standards govern berry and herbal extract processing for gummy vitamin exports. Maharashtra and Gujarat host agricultural distillation clusters facing climate-driven harvest volatility.
Japan
PMDA geriatric dysphagia guidance accelerates demand for palatable orally disintegrating tablet formats beyond pediatric defaults. METI green chemistry incentives favor carbon-verified flavor houses in procurement scoring. Kansai region anchors taste-modulation R&D partnerships between flavor suppliers and pharmaceutical compounders.
Switzerland
Swissmedic excipient purity thresholds exceed FDA baselines, fragmenting supplier qualification for multinational portfolios. Geneva and Basel clusters integrate taste-modulation platforms with USP-grade certification for pediatric analgesic supply. The country's regulatory stringency positions its flavor houses as premium-tier validators for global OTC brands.
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and natural-origin provenance. The vendor base concentrates around three tiers: integrated taste-modulation platforms with pharma-dedicated divisions, natural masking technology specialists, and regional compounders serving price-sensitive mass markets. Strategic moves center on USP-grade certification acquisition and blockchain-verified supply chain documentation.
Within the integrated platform tier, Givaudan SA and International Flavors & Fragrances Inc. represent archetypes of vertically organized supply. Symrise AG occupies a position emphasizing natural-origin technologies. These three exemplify how competitive positioning now depends on regulatory compliance breadth rather than commodity flavor pricing.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Kerry Group |
| DSM-Firmenich |
| Sensient Technologies Corp. |
| Frutarom |
| Firmenich |
| Takasago International Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for USP-grade natural extracts concentrate procurement power with certified flavor houses in Switzerland and the United States, compressing margin flexibility for mid-tier compounders serving price-sensitive mass-market analgesic producers. This inventory bandwidth differential separates premium-certified suppliers from commodity synthetic flavor blenders.
Pricing Analysis
Pharmacy chain procurement teams anchor pricing stratification across premium, standard, and economy tiers. USP-NF certification and blockchain-verified natural-origin provenance command 3-5x spreads over synthetic vanillin baselines. Cost compression in economy-tier cough syrups intensifies as Indian contract manufacturers revert to artificial taste agents. Independent drug stores exhibit highest price sensitivity; CVS and Walgreens private-label buyers prioritize consumer-validated flavor performance over unit cost.
Supply Chain Analysis
India and Switzerland anchor global supply for natural extract intermediates and pharmaceutical-grade certification respectively. Peppermint oil distillation draws from Midwestern US agricultural clusters; berry and herbal extracts hinge on Maharashtra and Gujarat harvest cycles. Climate-driven crop volatility constitutes the dominant supply risk. Distribution runs through pharmacy chain centralized procurement programs and direct-to-consumer wellness brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent flavor houses face substitution pressure from vertically integrated pharmaceutical compounders developing captive taste-modulation capabilities in-house.
For Market Incumbents: Consolidate certification depth through USP-grade facility investments in New Jersey and Pennsylvania compounding clusters. Deepen backward integration into natural extract sourcing to defend margin position against climate-driven supply volatility. For New Entrants and Emerging Players: Differentiate on EMA sustainability-linked procurement scoring by demonstrating carbon-verified production pathways. Target Japan's geriatric dysphagia formulation segment with specialized orally disintegrating tablet flavor systems. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate flavor divisions lacking dedicated pharmaceutical-grade certification infrastructure. Watch FDA pediatric palatability guidance enforcement as inflection signal for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| USP-Grade Certification Acquisition | FDA pediatric palatability mandates raise entry barriers for uncertified compounders. |
| Blockchain Supply Chain Verification | Clean-label positioning demands provenance documentation from agricultural source to finished flavor. |
| Natural Masking Technology R&D | Cyclodextrin complex adoption displaces sucrose-based taste masking in acetaminophen syrups. |
| Sensory Evaluation Facility Expansion | Retailer scorecards weight consumer taste-test performance at 35% of procurement decisions. |
| Direct-to-Consumer Channel Partnership | Wellness subscription brands commission exclusive flavor profiles outside traditional pharmacy retail. |
Research Methodology
Cross-validation between primary interviews with flavor house R&D directors, pharmacy chain procurement managers, and pediatric formulation specialists and secondary FDA guidance documents, EMA excipient quality guidelines, and USP-NF monograph standards anchors the qualitative findings. Customs records tracking natural extract import flows and pharmaceutical compounding facility registrations provide bottom-up volume triangulation against top-down therapeutic category consumption models.
Sensitivity analysis across the projection horizon tests forecast robustness against regulatory timing shifts and climate-driven agricultural yield variance. Segmentation dimensions include product type, flavor origin tier, end-user channel, and regional regulatory cluster. CAGRs derive from modeled API consumption growth, flavor intensity coefficients per dosage form, and substitution elasticity between synthetic and natural masking systems.
Material uncertainties — FDA pediatric palatability guidance implementation pace, REACH residual solvent threshold revisions, and monsoon pattern disruption to Indian herbal extract harvests — sit outside the modeled envelope. Recalibration cycles align with material shifts in regulatory enforcement and agricultural supply conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market