
 Chronic Kidney Disease (CKD) Drugs Market | 2026-2036
Chronic Kidney Disease (CKD) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Kidney Disease (CKD) Drugs Market Outlook
The CKD drugs market is rebalancing between premium biologic erythropoiesis stimulating agents and commodity oral ACE inhibitors, with reimbursement pressure widening the gap between hospital-administered and take-home therapies. AstraZeneca leverages its SGLT2 inhibitor portfolio to anchor growth in cardiorenal overlap indications. Pfizer, Inc. competes through sustained R&D investment in late-stage mineralocorticoid receptor antagonists. Amgen Inc. dominates the erythropoiesis segment through manufacturing scale and long-standing dialysis channel relationships.
Chronic Kidney Disease drugs comprise pharmaceutical agents targeting progressive renal function decline, including small-molecule modulators of the renin-angiotensin-aldosterone system and recombinant biologics stimulating erythropoiesis, formulated for oral, intravenous, or subcutaneous delivery to slow glomerular filtration rate deterioration and manage mineral-bone disorder complications. ACE Inhibitors and ARBs retain the largest volume share as foundational hypertension management in early-stage patients, though margin pools are thinning due to generic saturation. Erythropoiesis Stimulating Agents command premium pricing in dialysis-dependent populations but face biosimilar erosion in European markets. The Oral administration route captures the fastest expansion as homecare and clinic settings shift away from infusion-center dependency.
The FDA, EMA, and WHO set divergent purity and post-market surveillance standards that fragment approval timelines and shape regional launch sequencing for novel renal therapies. REACH and RoHS compliance requirements in Europe add manufacturing cost layers for device-drug combination products in dialysis settings. Stakeholders must monitor how CMS national coverage determinations and FDA Breakthrough Therapy designations interact to redefine commercial access for combination CKD-cardiovascular therapies.
Market Dynamics
Medicare reimbursement structures in the United States are compressing hospital margins on infused erythropoiesis-stimulating agents while accelerating oral SGLT2 inhibitor substitution in outpatient nephrology clinics.
Growth Catalysts
- FDA Breakthrough Therapy designations:Accelerated approval pathways for cardiorenal combination therapies compress development timelines and expand addressable patient populations.
- Homecare administration shift:Dialysis providers are expanding subcutaneous delivery training to reduce infusion-center dependency and capture Medicare bundled payment savings.
- Renin-angiotensin-aldosterone system modulation:Next-generation mineralocorticoid receptor antagonists demonstrate superior cardiovascular outcomes in late-stage trials.
Market Restraints
- Biosimilar erosion in European markets:EMA-approved erythropoiesis-stimulating agent biosimilars are compressing pricing power in Germany, France, and Italy.
- REACH and RoHS compliance costs:Device-drug combination products for dialysis settings face elevated manufacturing overhead in European Union member states.
- Generic saturation of ACE inhibitors:Patent-expired angiotensin-converting enzyme inhibitors dominate early-stage CKD prescribing with minimal margin contribution.
Strategic Opportunities
- Underpenetrated Japanese market:PMDA regulatory harmonization with FDA cardiovascular outcome trial standards is opening pathways for SGLT2 inhibitor label expansion.
- Non-dialysis CKD populations:Oral formulation development targets the larger pre-dialysis patient base currently managed by primary care physicians.
- Integrated cardiorenal protocols:Hospital systems are consolidating hypertension, diabetes, and nephrology formularies around single-molecule dual indications.
Industry Challenges
- Nephrology workforce constraints:Fellowship-trained specialists concentrate in academic medical centers, limiting rural and community hospital access to guideline-directed therapy initiation.
- Legacy electronic health record integration:Estimated glomerular filtration rate calculation standardization across Epic, Cerner, and Meditech platforms delays automated CKD stage alerts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Kidney Disease (CKD) Drugs Market |
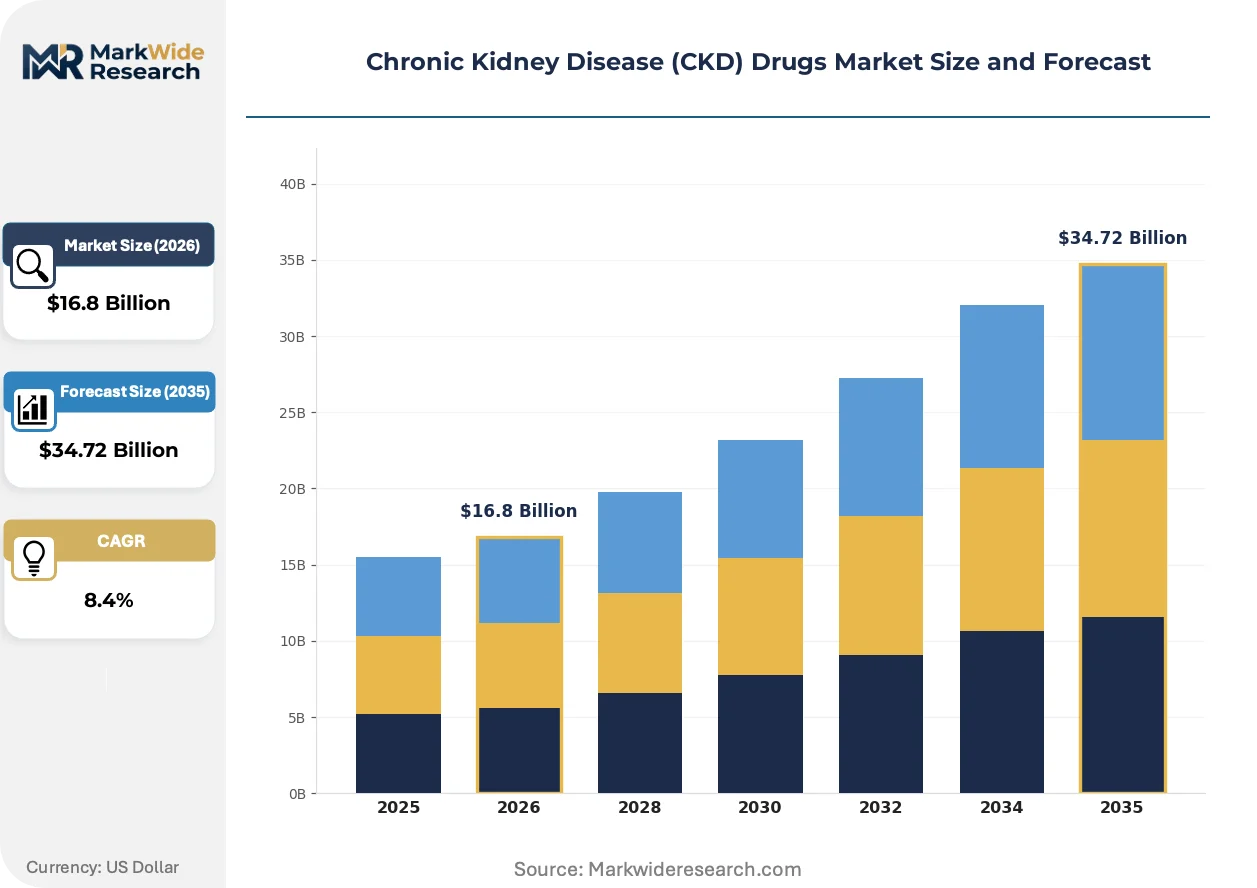
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: ACE Inhibitors, ARBs, Diuretics, Erythropoiesis Stimulating Agents Administration Route: Oral, Intravenous, Subcutaneous, Inhalation End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Indication: Hypertension, Hyperphosphatemia, Anemia, Metabolic Acidosis |
| Companies Covered | AstraZeneca, F. Hoffmann-La Roche Ltd., Pfizer, Inc., Sanofi, GSK plc, AbbVie Inc., Amgen Inc., Boehringer Ingelheim, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Kidney Disease (CKD) Drugs Market Strategic Shifts
Continuous glucose monitoring data streams are reshaping how nephrologists titrate diabetes medications in CKD patients, creating demand for interoperable renal-cardiovascular platforms.
Artificial intelligence-enabled image analysis is integrating into ultrasound-based kidney function assessment workflows. Large nephrology practices in the United States are piloting FDA-cleared algorithms for automated cortical thickness measurement. This technology is integrating radiology and nephrology departmental budgets while compressing specialist consultation backlogs.
EMA's updated guideline on clinical investigation of medicinal products in CKD mandates cardiovascular outcome inclusion regardless of primary renal endpoint design. Pharmaceutical sponsors must now power trials for dual primary outcomes, extending recruitment timelines. Oral SGLT2 inhibitor developers are responding by prioritizing US-EU simultaneous submission strategies to amortize trial costs.
Hospital procurement committees are unbundling erythropoiesis-stimulating agent contracts from dialysis service agreements. Independent purchasing organizations in Texas and Florida are negotiating direct manufacturer arrangements, bypassing legacy group purchasing organization markups. This disintermediation is most visible in for-profit dialysis chains seeking to offset Medicare reimbursement compression.
Chronic Kidney Disease (CKD) Drugs Market Segmentation
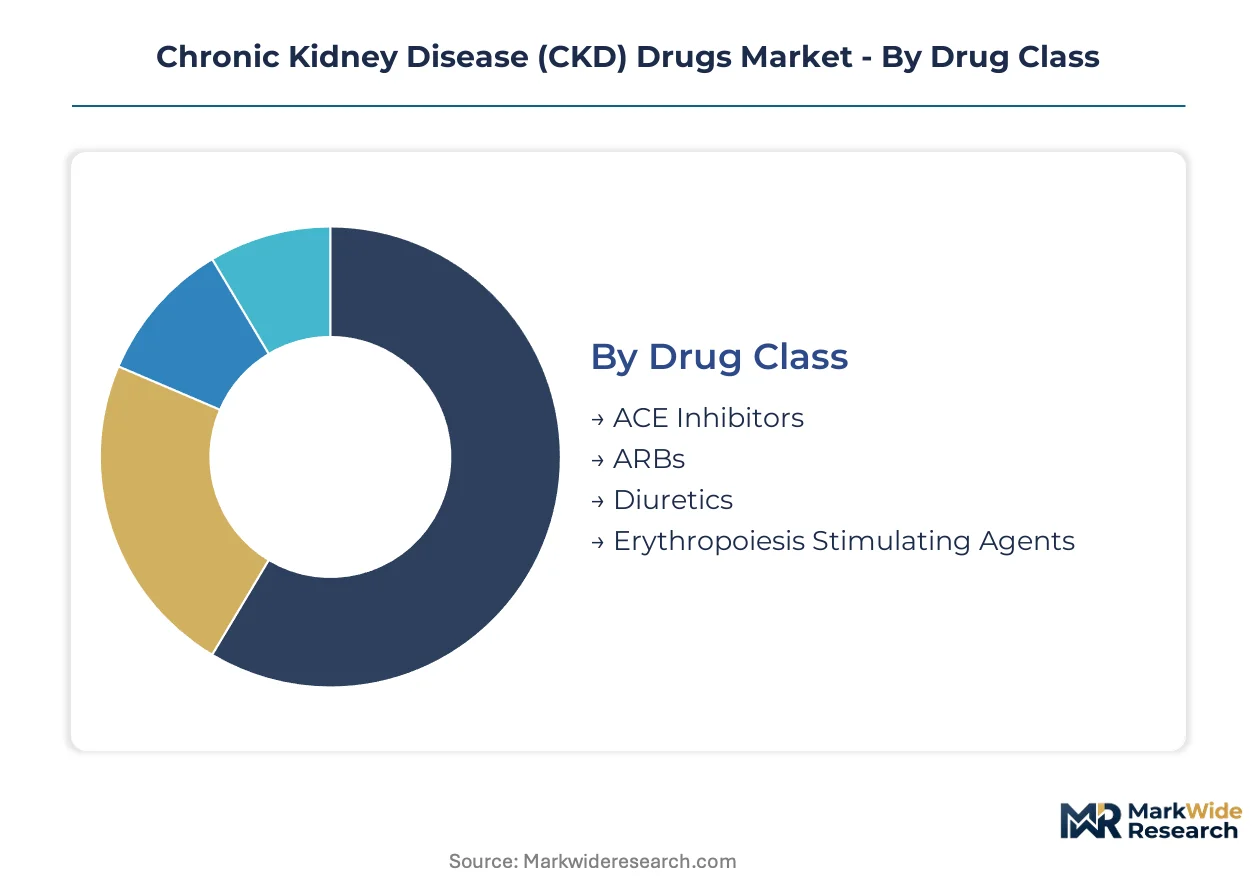
CKD drug segmentation reveals divergent margin structures across administration modes and care settings. Manufacturers align formulation investments with reimbursement pathways and site-of-care economics rather than clinical severity alone.
Drug Class:
Prescribing authority and reimbursement tier separate hospital-based biologics from outpatient oral therapies.
- ACE Inhibitors:Small-molecule renin-angiotensin system blockers formulated for once-daily oral dosing. Volume concentrates in United States Medicare Part D formularies where generic substitution rates exceed 90 percent, compressing manufacturer margins to pharmacy benefit manager rebate levels.
- Erythropoiesis Stimulating Agents:Recombinant erythropoietin analogs and darbepoetin alfa requiring cold-chain distribution. Demand clusters in dialysis-dependent populations across United States hospital outpatient departments, where CMS bundled payments incentivize biosimilar adoption over originator products.
- ARBs:Angiotensin II receptor antagonists with comparable efficacy to ACE inhibitors but distinct tolerability profiles.
- Diuretics:Loop and thiazide agents managing volume overload in early-stage disease.
Volume sits with ACE Inhibitors; growth tilts toward Erythropoiesis Stimulating Agents.
Administration Route:
Site-of-care migration from infusion centers to home settings restructures delivery economics and patient adherence monitoring.
- Oral:Tablet and capsule formulations including SGLT2 inhibitors and fixed-dose RAAS combinations. United States nephrology clinics are expanding take-home prescribing to capture Medicare chronic care management billing codes, reducing hospital outpatient visit frequency.
- Intravenous:Iron supplementation and erythropoiesis agents administered in dialysis suites. United States for-profit dialysis chains are renegotiating iron sucrose contracts outside legacy group purchasing organizations to offset reimbursement compression.
- Subcutaneous:Self-administered erythropoiesis agents requiring patient training programs.
- Inhalation:Experimental dry-powder formulations targeting pulmonary drug delivery for systemic absorption.
Intravenous dominates current revenue; oral formulations are climbing the fastest as homecare protocols mature.
End User:
Procurement sophistication and formulary control separate institutional buyers from dispersed retail channels.
- Hospitals:Academic medical centers and community hospitals with integrated pharmacy and therapeutics committees. United States health systems are consolidating nephrology formularies across hypertension, diabetes, and cardiology service lines to reduce therapeutic duplication.
- Homecare:Medicare-certified home health agencies and patient self-administration programs. United States dialysis providers are expanding subcutaneous training to capture bundled payment savings and reduce transportation-dependent no-show rates.
- Clinics:Independent nephrology practices and hospital outpatient departments.
- Long-term Care Facilities:Skilled nursing facilities managing polypharmacy in elderly CKD populations.
Hospitals retain the steepest expansion trajectory through integrated cardiorenal protocol adoption; homecare is gaining share fastest on site-of-care shift.
Indication:
Complication prevalence and monitoring infrastructure availability determine addressable population sizing.
- Anemia:Erythropoiesis deficiency requiring hemoglobin monitoring and iron repletion coordination. United States dialysis facilities maintain dedicated anemia management protocols with monthly lab tracking mandated by CMS conditions for coverage.
- Hypertension:RAAS-mediated blood pressure elevation preceding measurable GFR decline. United States primary care networks drive volume through guideline-directed therapy initiation before nephrology referral.
- Hyperphosphatemia:Mineral-bone disorder requiring phosphate binder administration with meals.
- Metabolic Acidosis:Bicarbonate deficiency managed with oral alkali supplementation.
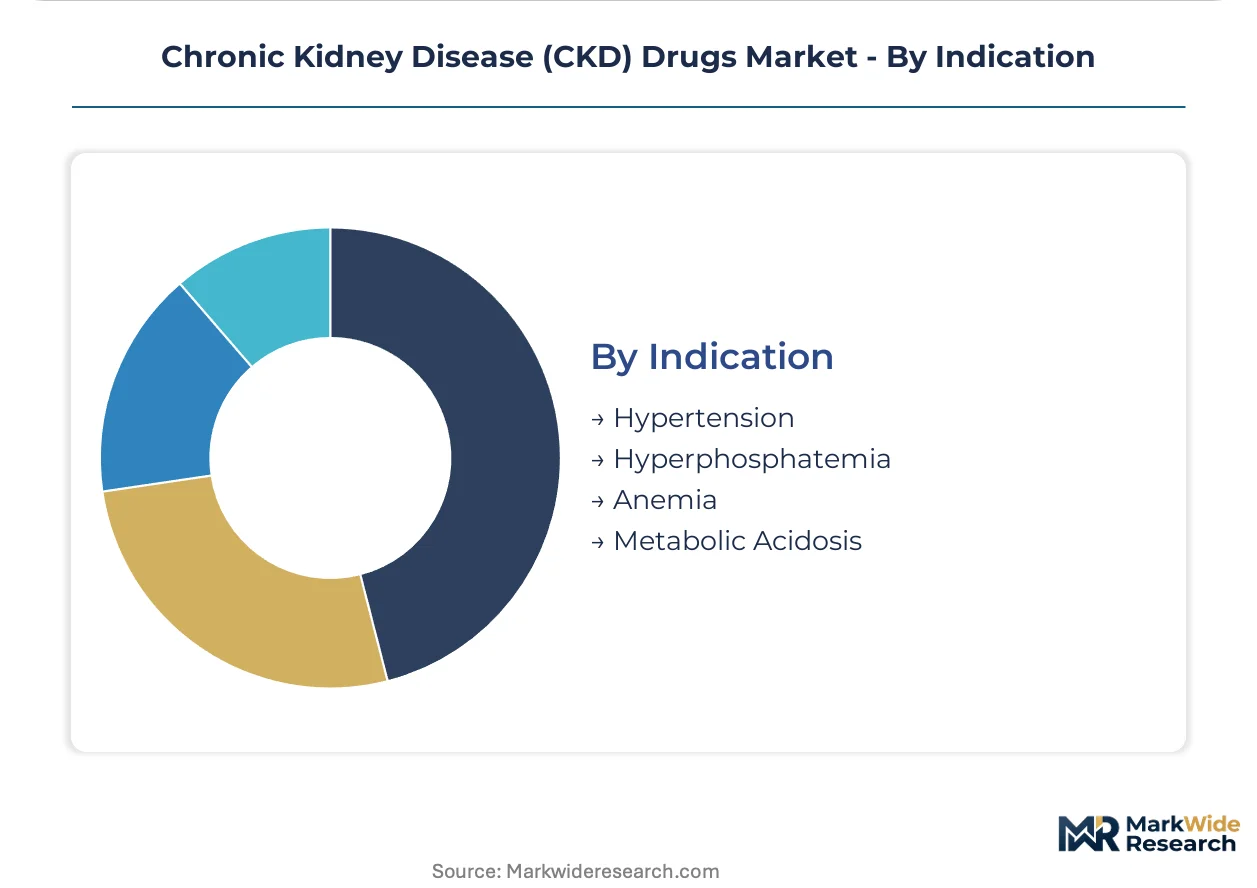
Hypertension captures current volume through early-stage prescribing; anemia presents the steepest expansion trajectory on dialysis population growth and biosimilar access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cambridge, Massachusetts anchors the densest concentration of nephrology clinical trial operations in the United States, with Mass General Brigham and Harvard-affiliated sites driving FDA Breakthrough Therapy submissions for cardiorenal combination therapies.
United States
Medicare bundled payment reforms and CMS chronic care management billing codes accelerate oral SGLT2 inhibitor prescribing in outpatient nephrology clinics. The FDA's accelerated approval pathways for renal therapies compress development timelines for sponsors. The Research Triangle Park corridor in North Carolina hosts contract research organizations specializing in cardiovascular outcome trial design for CKD populations.
Germany
EMA-approved erythropoiesis-stimulating agent biosimilars compress pricing power in dialysis-dependent populations across Bavaria and North Rhine-Westphalia. REACH compliance requirements for device-drug combination products elevate manufacturing overhead for dialysis delivery systems. The Munich metropolitan cluster concentrates nephrology-focused pharmaceutical manufacturing and cold-chain distribution infrastructure.
Japan
PMDA regulatory harmonization with FDA cardiovascular outcome trial standards opens pathways for SGLT2 inhibitor label expansion in non-dialysis CKD populations. METI incentives for rare disease drug development attract multinational sponsors to Tokyo-Osaka clinical trial networks. The Kansai region hosts specialized contract manufacturing organizations for biologic erythropoiesis agents.
Switzerland
Swissmedic's alignment with EMA centralized procedures accelerates market access for mineralocorticoid receptor antagonists in hypertension-nephrology crossover indications. Basel anchors European headquarters operations for major nephrology drug developers, with proximity to Novartis and Roche research campuses driving preclinical renal fibrosis programs.
India
CDSCO streamlined approval pathways for biosimilar erythropoiesis-stimulating agents expand access in dialysis-dependent populations across Maharashtra and Gujarat. Government PLI scheme incentives for active pharmaceutical ingredient production reduce import dependency for ACE inhibitor raw materials. The Hyderabad-Visakhapatnam corridor concentrates generic formulation manufacturing for oral RAAS modulators.
Chronic Kidney Disease (CKD) Drugs Market Competitive Environment
Premium-margin players sit above commodity-margin players across the biologic-oral therapy divide, with recombinant erythropoiesis agents commanding hospital outpatient reimbursement tiers while generic ACE inhibitors compete on pharmacy benefit manager rebate levels. The vendor base stratifies into three archetypes: integrated cardiorenal portfolio holders, dialysis channel specialists, and late-stage mineralocorticoid receptor antagonist developers. Consolidation pressures concentrate among mid-cap firms lacking SGLT2 inhibitor or biosimilar manufacturing scale. Dominant competitive moves include strategic partnerships for cardiovascular outcome trial cost-sharing and geographic licensing to amortize dual-primary endpoint study expenses.
Within the integrated portfolio tier, AstraZeneca and Pfizer occupy positions defined by cardiorenal overlap indication strategies, with AstraZeneca representing the SGLT2 inhibitor-centric archetype and Pfizer exemplifying late-stage mineralocorticoid receptor antagonist development. Amgen sits within the biologic manufacturing scale tier, anchoring dialysis channel relationships through erythropoiesis-stimulating agent supply agreements. These three entities exemplify distinct competitive positioning vectors without implying specific market share claims or strategic action timelines.
| Leading Market Players |
|---|
| AstraZeneca |
| F. Hoffmann-La Roche Ltd. |
| Pfizer, Inc. |
| Sanofi |
| GSK plc |
| AbbVie Inc. |
| Amgen Inc. |
| Boehringer Ingelheim |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Oral SGLT2 inhibitor manufacturing scale-up is simultaneously compressing unit production costs and concentrating active pharmaceutical ingredient sourcing among contract manufacturers in India and China. This dual shift enables aggressive Medicare Part D formulary positioning while exposing supply networks to single-source dependencies for key starting materials.
Pricing Analysis
Cardiovascular outcome trial data serves as the value-based pricing anchor for next-generation mineralocorticoid receptor antagonists in hospital outpatient settings. Three-tier pricing structure across originator biologics, licensed biosimilars, and commodity ACE inhibitors separates dialysis-dependent populations from pre-dialysis managed care. Cost compression in the erythropoiesis-stimulating agent segment is intensifying because CMS bundled payment reforms incentivize biosimilar substitution. Dialysis-dependent populations show highest price sensitivity due to fixed reimbursement ceilings, while integrated health systems demonstrate lowest sensitivity through formulary consolidation gains.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredient production is reshaping sourcing patterns for oral RAAS modulators, reducing import dependency for ACE inhibitor raw materials. Cold-chain distribution for biologic erythropoiesis agents draws from manufacturing clusters in the United States, Switzerland, and Japan. Single-source vulnerability concentrates in recombinant protein production for dialysis populations. Distribution runs through hospital outpatient departments, specialty pharmacy networks, and direct-to-clinic arrangements with for-profit dialysis chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CKD drugs market sits in a formulation-transition phase as subcutaneous delivery protocols displace infusion-center dependency and oral SGLT2 inhibitors displace legacy diuretic-first prescribing.
For Market Incumbents: Acquire late-stage mineralocorticoid receptor antagonist pipelines to offset biosimilar erosion in erythropoiesis-stimulating agents. Secure backward integration into oral SGLT2 inhibitor active pharmaceutical ingredient production to defend margin position against Indian and Chinese contract manufacturing competition. Prioritize FDA Breakthrough Therapy designation pursuit for cardiorenal combination indications. For New Entrants and Emerging Players: Capture the non-dialysis CKD population managed by United States primary care networks before nephrology referral, where SGLT2 inhibitor penetration remains incomplete. Target Japanese regulatory harmonization pathways for label expansion in cardiovascular outcome trial-aligned submissions. Lead with Medicare chronic care management billing code capture as the go-to-market anchor. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap firms with late-stage mineralocorticoid receptor antagonist assets but lacking SGLT2 inhibitor manufacturing scale. Long-term viability hinges on integrated cardiorenal portfolio breadth rather than single-molecule concentration. Watch FDA Breakthrough Therapy designation density as the inflection signal for reimbursement access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Dual-primary endpoint trials for cardiovascular and renal outcomes satisfy EMA and FDA harmonized standards. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses development timelines for cardiorenal combination therapies. |
| Manufacturing Scale-Up | Cold-chain biologic production expansion secures dialysis channel supply agreements against biosimilar competition. |
| Pipeline Diversification | Mineralocorticoid receptor antagonist development hedges against SGLT2 inhibitor class commoditization. |
| Licensing Agreement | Geographic licensing to Japanese partners amortizes dual-primary endpoint cardiovascular outcome trial costs. |
Study Parameters
FDA filings, EMA regulatory submissions, and ClinicalTrials.gov protocol databases formed the secondary backbone for this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists validated market sizing assumptions. Bottom-up prescription volume modeling and top-down reimbursement expenditure analysis provided triangulation across the analysis window.
Historical trendline analysis of Medicare Part D formulary placement rates and dialysis facility procurement patterns anchored the projection framework. Segmentation modeling spanned drug class, administration route, end-user setting, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to prescription volume and expenditure trajectories. Forecast inputs incorporated CMS national coverage determination timing and PMDA regulatory harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA approval pathway disruptions, biosimilar launch sequencing, and nephrology workforce distribution constraints. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory alignment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Tetanus Market