
 Injectable Potassium Phosphate Market | 2026-2036
Injectable Potassium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Potassium Phosphate Market Foresight
Single-source API procurement for sterile phosphate salts is realigning toward multi-source qualification programs among leading manufacturers. Fresenius Kabi AG leverages its European manufacturing network to sustain supply continuity for hospital customers across multiple continents. Baxter International Inc. anchors its position through captive production of premixed infusion bags, while Hikma Pharmaceuticals PLC competes on cost-efficient injectable suspensions for emerging markets.
Injectable potassium phosphate comprises sterile, pyrogen-free solutions or suspensions of dibasic and monobasic potassium phosphate salts, typically formulated at concentrations of 0.5 to 3 mM/mL with pH adjusted to 6.5–8.0 for intravenous administration, serving primarily to correct hypophosphatemia and support parenteral nutrition regimens. Injection solutions dominate current production volumes due to their compatibility with centralized pharmacy admixture operations, while premixed solutions represent the fastest-expanding category as hospitals seek to reduce compounding error risk and streamline clinical workflow. The end-user landscape tilts heavily toward hospitals, where bulk purchasing contracts and formulary control create concentrated margin pools that dialysis centers and home healthcare providers struggle to replicate.
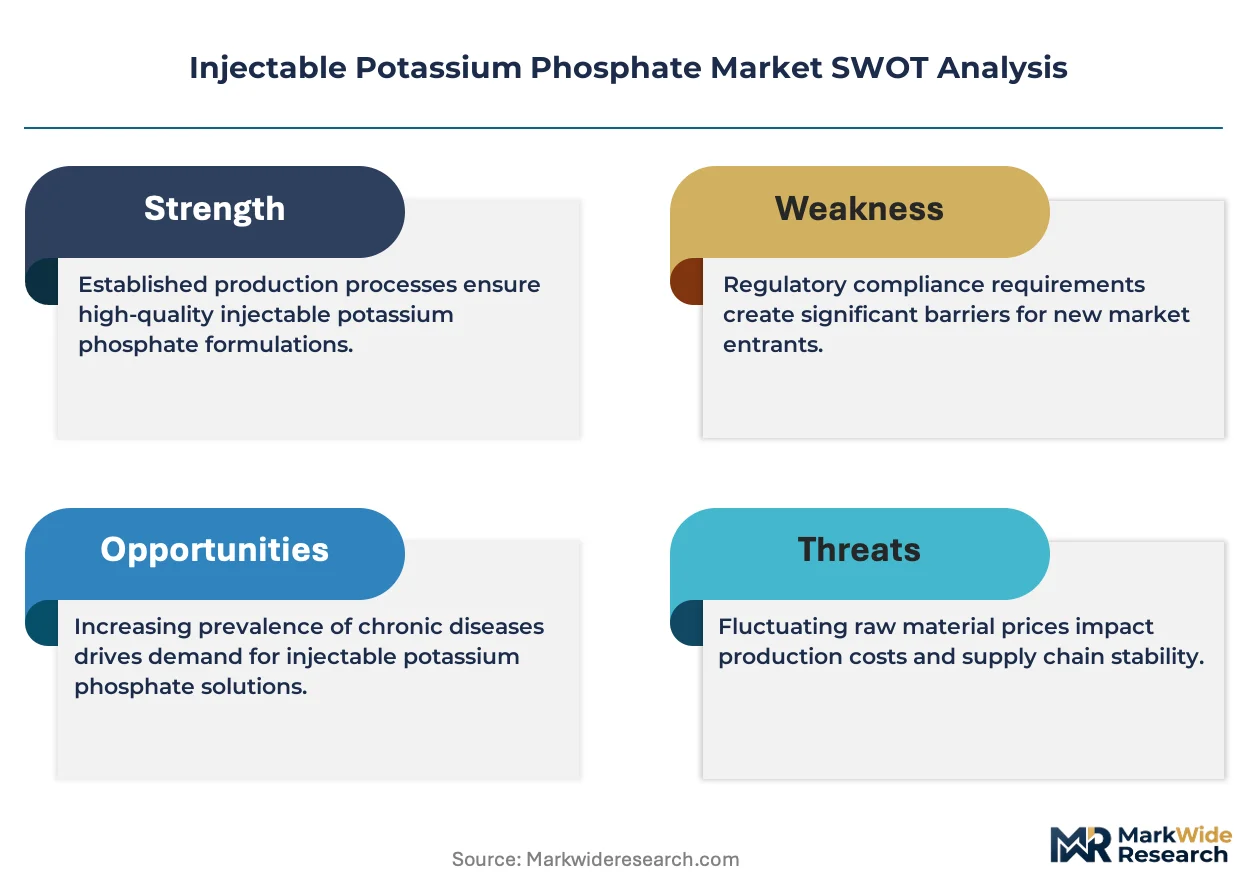
FDA enforcement of cGMP standards for sterile injectables, combined with USP Chapter 797 compounding regulations and EMA's GMP Annex 1 revisions for sterile medicinal products, elevates compliance costs and favors manufacturers with validated aseptic processing capabilities. These frameworks restrict market access for smaller compounders while creating structured demand for documented supply chain traceability from API source to patient administration. Stakeholders must monitor evolving pharmacopeial harmonization efforts and assess whether backward integration into phosphate salt refining or strategic partnerships with certified API suppliers offer more durable competitive protection.
Market Dynamics
Hospital pharmacy consolidation is concentrating purchasing power among integrated delivery networks, forcing sterile injectable suppliers to restructure contract terms around guaranteed volume commitments rather than spot-market pricing.
Growth Catalysts
- USP Chapter 797 revisions:The FDA's updated sterile compounding standards mandate beyond-use dating and environmental monitoring, driving demand for commercially manufactured premixed potassium phosphate bags that eliminate hospital compounding liability.
- Parenteral nutrition expansion:Oncology and critical care units are expanding phosphate supplementation protocols for refeeding syndrome prevention, creating protocol-driven demand independent of episodic hypophosphatemia treatment.
- Home infusion migration:Discharge planning protocols are shifting stable electrolyte replacement to home healthcare settings, opening new channel volume for ambulatory-compatible packaging formats.
Market Restraints
- API supply concentration:Refined phosphate salt production clusters in Chinese and Moroccan mining-to-chemical processing corridors, exposing manufacturers to export licensing delays and shipping cost volatility.
- Aseptic processing capex barriers:Isolator technology and continuous manufacturing lines require capital deployment that exceeds mid-tier compounder balance sheet capacity, freezing market entry.
- Oral phosphate substitution:Enteric-coated sodium phosphate tablets are capturing stable chronic hypophosphatemia cases, compressing addressable volume for intravenous formulations in outpatient settings.
Strategic Opportunities
- Indian hospital sector expansion:Corporate hospital chains in Maharashtra and Karnataka are installing centralized pharmacy automation, creating demand for standardized premixed electrolyte bags compatible with robotic compounding systems.
- EMA Annex 1 alignment:Manufacturers achieving barrier-isolation certification for sterile phosphate production gain automatic qualification for EU hospital tenders, reducing competitive field width.
- Real-time release testing:In-process analytical technologies combined with parametric release protocols are compressing lot-release timelines from weeks to days, enabling just-in-time inventory models for hospital customers.
Industry Challenges
- Qualified personnel scarcity:Aseptic processing operators with isolator technology certification command wage premiums that inflate manufacturing overhead by double-digit percentages at greenfield facilities.
- Legacy ERP integration:Serialization and track-and-trace mandates require middleware deployment to connect decades-old manufacturing execution systems with modern supply chain visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Potassium Phosphate Market |
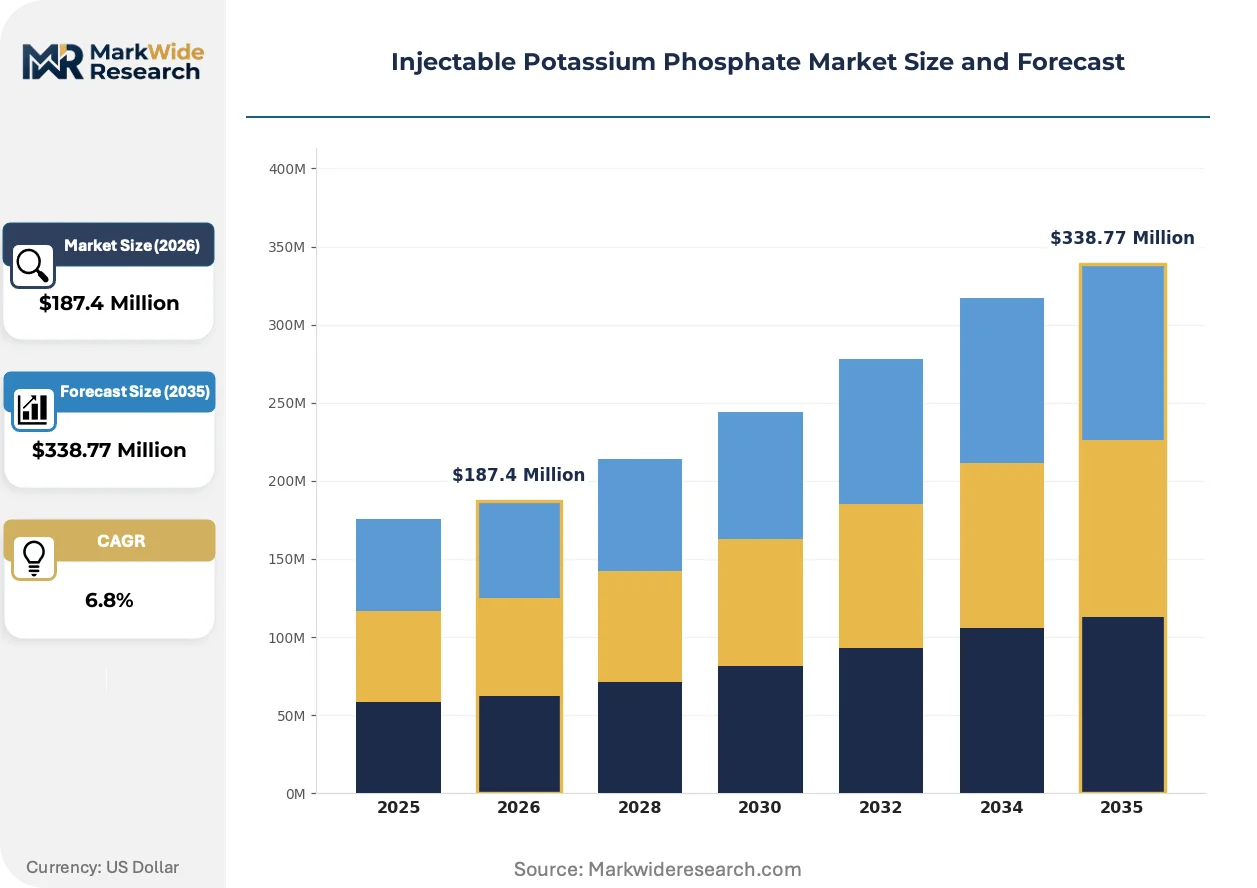
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Solutions, Injectable Suspensions, Premixed Solutions, Infusion Bags End User: Hospitals, Dialysis Centers, Home Healthcare, Rehabilitation Facilities Application: Electrolyte Replenishment, Nutritional Support, Heart Health, Kidney Function Distribution Channel: Direct Sales, Wholesale Distributors, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Fresenius Kabi AG, Baxter International Inc., Pfizer Inc., Hikma Pharmaceuticals PLC, B. Braun Melsungen AG, American Regent, Inc., ICU Medical, Inc., Merck KGaA, Innophos Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Potassium Phosphate Market Shifts & Advancements
Closed-system transfer devices and barrier-isolation manufacturing are displacing traditional cleanroom operations, while real-time supply chain monitoring and hospital formulary automation reshape how potassium phosphate moves from API to patient.
Barrier isolator technology is electrifying sterile phosphate manufacturing by eliminating human intervention during filling operations. Fresenius Kabi and Baxter have deployed isolator lines across European and North American plants, compressing contamination risk profiles and enabling extended beyond-use dating for premixed bags. This shift is electrifying competitive positioning by rewarding capital-intensive manufacturers with formulary lock-in through stability-proven products.
EMA's 2022 revision to GMP Annex 1 imposes stricter environmental monitoring and contamination control strategy documentation for sterile medicinal products. Manufacturers must now validate rapid microbial detection methods and demonstrate closed-system integrity throughout the product lifecycle. EU hospital procurement committees are prioritizing suppliers with documented Annex 1 compliance, creating certification-driven preference shifts in tender evaluations.
Hospital pharmacy directors are consolidating electrolyte purchasing through prime vendor agreements that bundle potassium phosphate with calcium, magnesium, and sodium chloride solutions. Integrated delivery networks in Texas, Florida, and Ohio are replacing multi-source spot buying with single-source contracts tied to inventory management technology. This concentration is most visible in US acute care settings where pharmacy benefit managers now influence sterile injectable formulary decisions previously controlled by individual clinicians.
Injectable Potassium Phosphate Market Segmentation
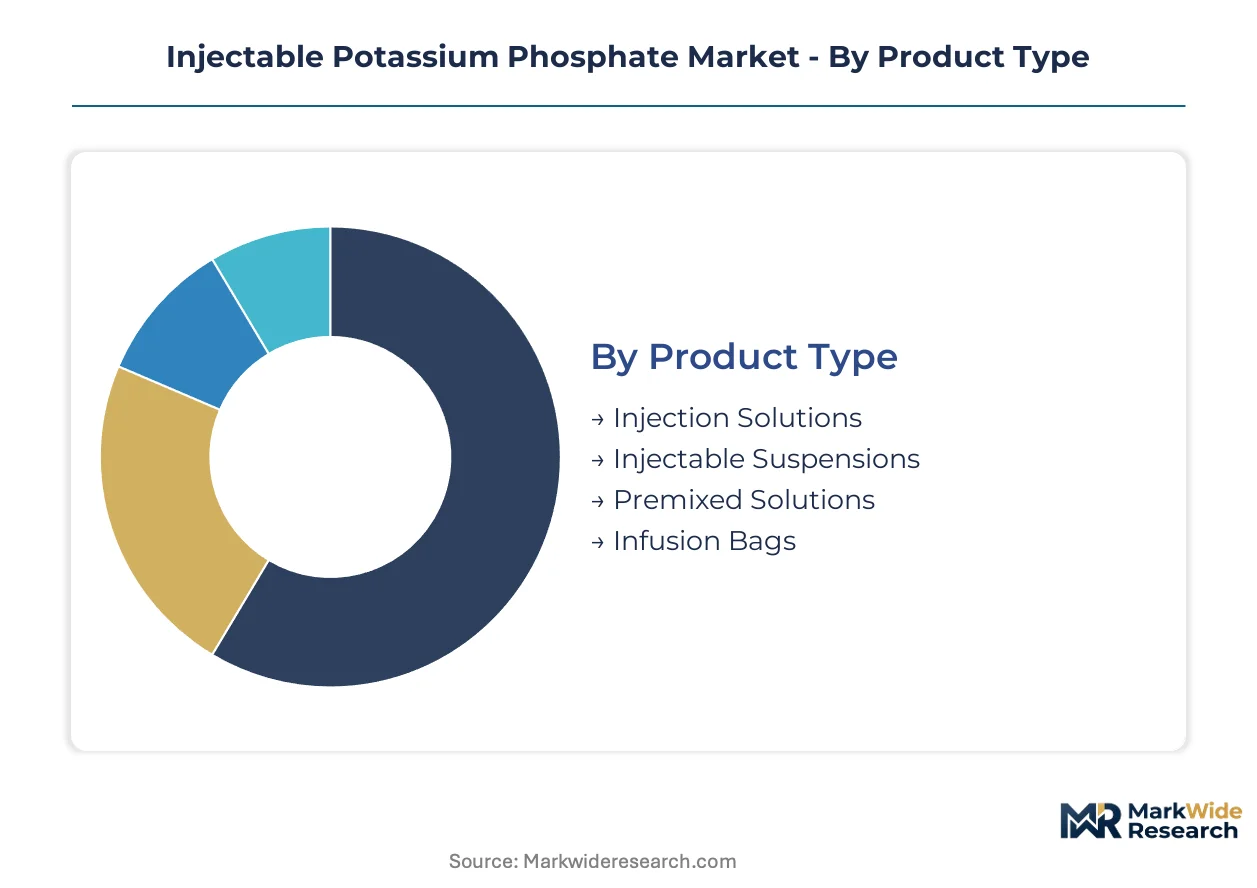
Injectable potassium phosphate segments diverge sharply by clinical workflow integration and regulatory burden. Product form determines compounding liability exposure, while end-user concentration shapes contract pricing power and channel strategy.
Product Type:
Hospital pharmacy directors select product forms based on centralized admixture capabilities versus error-risk tolerance.
- Injection Solutions:Sterile, pyrogen-free aqueous formulations of dibasic and monobasic potassium phosphate salts at 0.5–3 mM/mL concentrations, pH-adjusted to 6.5–8.0. Demand concentrates in US acute care facilities with established IV compounding infrastructure, though USP Chapter 797 compliance costs are forcing evaluation of alternatives.
- Premixed Solutions:Ready-to-administer sterile preparations in standardized concentrations, eliminating hospital compounding steps and reducing beyond-use dating liability. Growth tilts toward integrated delivery networks in Texas and Florida seeking formulary automation compatibility.
- Injectable Suspensions:Particulate formulations requiring reconstitution, serving cost-sensitive procurement channels with lower stability requirements.
- Infusion Bags:Large-volume parenteral containers for continuous electrolyte replacement, dominant in dialysis center purchasing.
Volume sits with injection solutions; growth tilts toward premixed solutions.
End User:
Procurement scale and formulary control intensity separate buyers across this category.
- Hospitals:Integrated delivery networks wield concentrated purchasing power through prime vendor agreements bundling electrolytes with calcium and magnesium solutions. US acute care facilities generate the dominant share of protocol-driven phosphate supplementation for refeeding syndrome prevention.
- Home Healthcare:Discharge planning protocols are shifting stable electrolyte replacement from inpatient to ambulatory settings, opening channel volume for portable packaging formats compatible with infusion pump systems.
- Dialysis Centers:Freestanding renal care facilities purchasing bulk infusion bags for intra-dialytic phosphate management, constrained by reimbursement rate pressures.
- Rehabilitation Facilities:Skilled nursing and post-acute settings with intermittent IV therapy needs and limited pharmacy infrastructure.
Revenue concentrates in hospitals; expansion accelerates fastest in home healthcare.
Application:
Clinical indication determines dosing protocol standardization and prescriber specialty concentration.
- Electrolyte Replenishment:Correction of hypophosphatemia in critical care, oncology, and post-surgical settings, driven by protocol-driven replacement algorithms rather than episodic treatment decisions.
- Nutritional Support:Parenteral nutrition regimens requiring phosphate supplementation to prevent refeeding syndrome, expanding with oncology and ICU nutrition protocol adoption.
- Heart Health:Cardiac rhythm stabilization applications in emergency and electrophysiology settings.
- Kidney Function:Phosphate management in renal replacement therapy and chronic kidney disease progression.
Electrolyte replenishment commands current volume; nutritional support climbs the fastest.
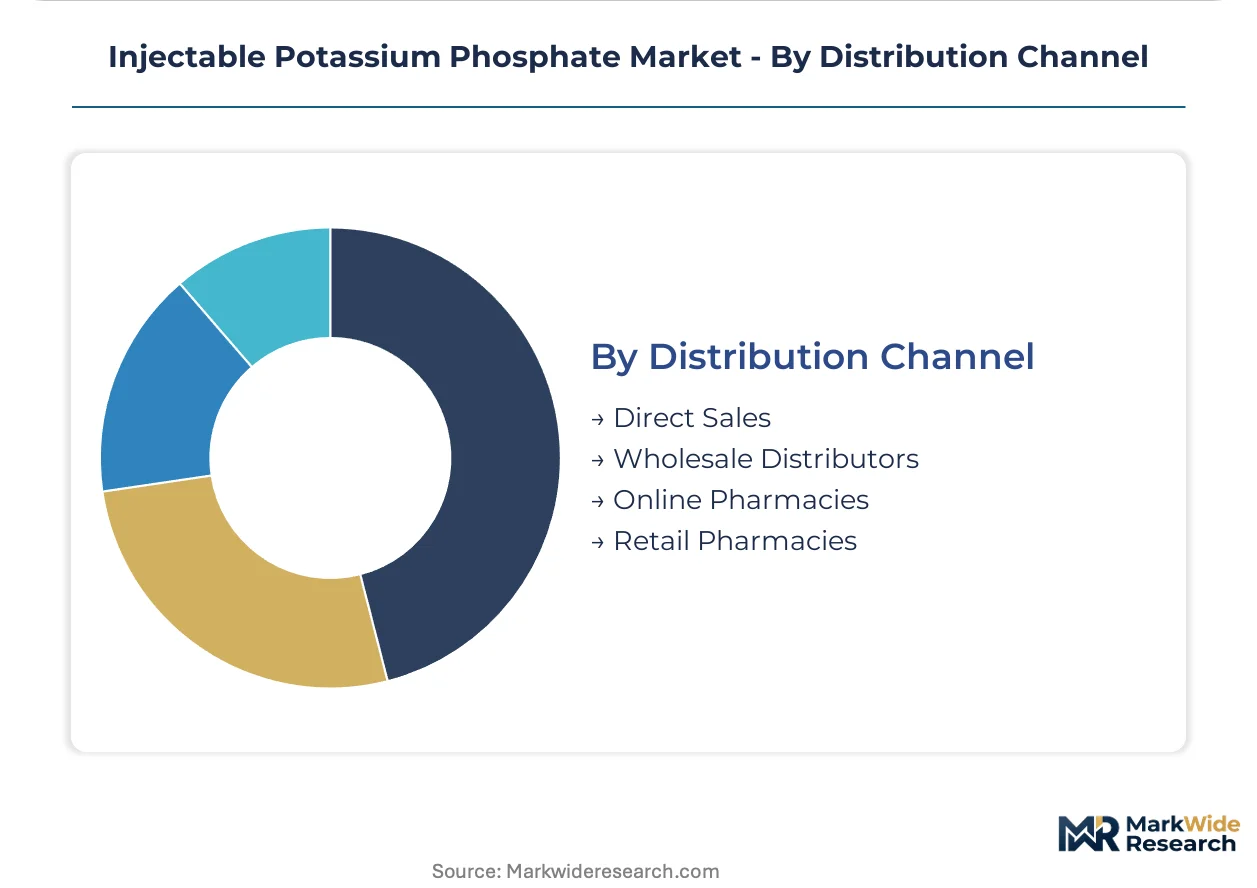
Distribution Channel:
Channel selection reflects order frequency, cold-chain requirements, and formulary integration depth.
- Wholesale Distributors:McKesson and Cardinal Health anchor hospital supply chains with just-in-time inventory models and consolidated electrolyte bundling.
- Direct Sales:Manufacturer-to-hospital contracts for integrated delivery networks with guaranteed volume commitments and inventory management technology integration.
- Online Pharmacies:Emerging channel for home healthcare discharge prescriptions and ambulatory infusion therapy supplies.
- Retail Pharmacies:Limited role for emergency oral-to-IV bridge prescriptions and specialty pharmacy networks.
Wholesale distributors handle current volume; direct sales gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan and Chinese phosphate mining corridors supply the refined salts that feed sterile injectable production worldwide. Hospital procurement patterns diverge sharply across major economies based on regulatory maturity and pharmacy infrastructure depth.
United States
Integrated delivery networks in Texas and Florida drive premixed solution demand through formulary automation investments. FDA enforcement of USP Chapter 797 compounding standards compels hospitals to outsource electrolyte preparation to certified manufacturers. The Northeast corridor concentrates specialty pharmacy operations serving home infusion migration.
Germany
Fresenius Kabi anchors European sterile phosphate supply from its manufacturing network serving hospital customers across multiple continents. EMA's GMP Annex 1 revision mandates barrier-isolation certification that filters supplier pools for EU hospital tenders. The Baden-Württemberg pharmaceutical cluster houses advanced aseptic processing capabilities.
India
Corporate hospital chains in Maharashtra and Karnataka install centralized pharmacy automation creating demand for standardized premixed electrolyte bags. CDSCO oversight of sterile injectable manufacturing tightens quality requirements for domestic producers. The Delhi-NCR region concentrates contract manufacturing organizations serving export markets.
China
Domestic phosphate salt refining capacity supports both captive injectable production and API export to international formulators. NMPA implementation of GMP standards for sterile medicinal products elevates compliance barriers for compounders. The Yangtze River Delta clusters pharmaceutical manufacturing with integrated chemical processing.
Japan
PMDA regulation of parenteral nutrition components maintains stringent stability and pyrogen testing protocols. METI industrial policy supports domestic production of critical electrolyte solutions for hospital supply security. The Kanto region around Tokyo concentrates medical device and infusion therapy manufacturing.
Injectable Potassium Phosphate Market Competitive Landscape
Global majors compete with regional champions across sterile manufacturing certification and hospital contract bundling. Market structure tilts toward consolidated supply among validated aseptic processors, with mid-tier compounders retreating under compliance cost pressure. Three archetypes dominate: integrated pharmaceutical conglomerates with captive API-to-finished-dose chains, specialized sterile injectable houses with barrier-isolation expertise, and regional cost competitors on basic suspension formulations. Competitive moves concentrate on prime vendor agreement expansion and backward integration into phosphate salt refining.
Among European-based pharmaceutical conglomerates, Fresenius Kabi AG exemplifies the integrated archetype with multi-continent manufacturing reach. Baxter International Inc. occupies a position emphasizing premixed infusion bag standardization for hospital workflow integration. Hikma Pharmaceuticals PLC represents cost-efficient production targeting emerging market procurement channels.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Baxter International Inc. |
| Pfizer Inc. |
| Hikma Pharmaceuticals PLC |
| B. Braun Melsungen AG |
| American Regent, Inc. |
| ICU Medical, Inc. |
| Merck KGaA |
| Innophos Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Refined phosphate salt feedstock costs cascade through sterile injectable production into three-tier pricing structure across premium, standard, and economy levels, with barrier-isolation certification and extended beyond-use dating separating premium premixed bags from basic injection solutions. Chinese and Moroccan mining-to-chemical processing corridors anchor upstream supply, while hospital pharmacy consolidation in Texas and Florida compresses margin pools through prime vendor bundling.
Pricing Analysis
Beyond-use dating warranties and stability documentation separate bundled premium offerings from unbundled economy tiers. Price differentiation hinges on USP Chapter 797 compliance certification and isolator technology validation, with volume scale driving contract discounts for integrated delivery networks. Cost compression in standard-grade injection solutions is intensifying because oral phosphate substitution captures stable chronic cases, while dialysis centers exhibit highest price sensitivity and EMA Annex 1-certified suppliers command lowest.
Supply Chain Analysis
EMA barrier-isolation certification and FDA cGMP validation gate supplier qualification, filtering the vendor pool for hospital tenders. Refined phosphate salt production clusters in China, Morocco, and the United States, with sterile manufacturing drawing from dibasic and monobasic potassium phosphate API, isolator equipment, and pyrogen-free water systems. Single-source vulnerability in Chinese export licensing exposes manufacturers to shipping cost volatility. Distribution runs through wholesale distributors McKesson and Cardinal Health with just-in-time inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing isolator capacity scarcity props pricing premiums, as qualified operator shortages and capital deployment thresholds freeze greenfield entry. Hospital procurement concentration through prime vendor agreements reinforces supply-constrained market structure.
For Market Incumbents: Acquire barrier-isolation manufacturing assets in the Baden-Württemberg pharmaceutical cluster to secure EMA Annex 1 qualification for EU hospital tenders. Expand captive phosphate salt refining partnerships to reduce Chinese export licensing exposure. Certification investment in real-time release testing compresses lot-release timelines, defending against mid-tier compounders seeking formulary automation contracts. For New Entrants and Emerging Players: The price-point gap between premium isolator-certified premixed bags and economy-grade injectable suspensions opens white-space in Indian corporate hospital chains installing centralized pharmacy automation. Target Maharashtra and Karnataka for robotic compounding-compatible standardized electrolyte bags. Pursue contract manufacturing partnerships with Delhi-NCR CMOs serving export markets as the go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized sterile injectable houses with isolator expertise in European manufacturing corridors over commodity suspension producers. Long-term viability frames around 5-10 year hospital formulary automation adoption curves. Watch CDSCO enforcement tightening on domestic Indian producers as inflection signal for contract manufacturing demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Isolation Certification Investment | EMA Annex 1 compliance filters EU hospital tender pools, locking out non-certified competitors. |
| Backward Integration into Phosphate Salt Refining | Captive API supply from Moroccan and Chinese corridors reduces export licensing vulnerability. |
| Real-Time Release Testing Deployment | In-process analytical technologies compress lot-release timelines from weeks to days for hospital just-in-time models. |
| Prime Vendor Agreement Expansion | Bundled electrolyte contracts with Texas and Florida integrated delivery networks lock in volume commitments. |
| Home Infusion Packaging Development | Ambulatory-compatible formats capture discharge planning protocol shifts from inpatient to home healthcare settings. |
Research Methodology
Multi-period observation of hospital pharmacy automation adoption rates, sterile compounding regulatory enforcement patterns, and phosphate salt trade flows anchored the trend analysis, supplemented by interviews with hospital procurement managers, aseptic processing operators, formulary directors, and CDSCO regulatory affairs leads. Secondary validation drew from FDA 483 inspection observations, EMA GMP inspection databases, USP Chapter 797 revision documentation, and customs trade data for refined phosphate salts. Bottom-up modeling of product-form volumes and top-down cross-check against hospital expenditure patterns ensured triangulation integrity.
Segment-weighting across injection solutions, premixed solutions, and infusion bags combined with end-user concentration factors for hospitals, home healthcare, and dialysis centers shaped the analytical framework over the projection horizon. Product type, end-user procurement scale, application protocol standardization, and distribution channel integration depth defined segmentation dimensions. CAGRs derived from elasticity-adjusted volume projections and pricing trajectory assumptions, with barrier-isolation capacity deployment schedules and oral substitution capture rates as key forecast inputs.
Inputs from EMA inspection databases and FDA enforcement records were available through the study window; gaps in real-time hospital purchasing transaction data introduce uncertainty bands around contract pricing assumptions. Forecasts reflect documented assumptions on regulatory harmonization timelines and isolator technology diffusion curves. A model refresh is warranted upon material change in USP Chapter 797 enforcement intensity or Chinese phosphate export licensing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Pharmaceutical Water Market