
 Middle East and Africa Protective Packaging Market | 2026-2036
Middle East and Africa Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Protective Packaging Market Foresight
Asset-light leasing models for automated packaging lines is reconfiguring competitive entry barriers across the Middle East and Africa, allowing mid-sized distributors to access enterprise-grade cushioning equipment without capital expenditure commitments. Sealed Air Corporation leverages its regional service network to sustain long-term contracts with pharmaceutical cold-chain operators. DS Smith PLC anchors its position through corrugated fiberboard specialization for FMCG export corridors linking Dubai to East African ports.
Protective packaging encompasses engineered containment systems designed to absorb mechanical shock, control moisture ingress, and maintain dimensional stability during transit, typically incorporating multi-layer laminates, expanded cellular structures, or molded pulp matrices with specified compression resistance thresholds. Its primary commercial purpose centers on reducing product damage rates across extended supply chains with variable handling intensity. Foam products dominate high-value electronics transit from Gulf manufacturing zones to African consumer markets, while paper-based wraps capture share in food service and quick-commerce channels seeking fiber-based alternatives. Plastic bags retain volume in pharmaceutical distribution where moisture barrier properties remain non-negotiable.
Saudi Arabia's SFDA and South Africa's Department of Forestry, Fisheries and the Environment enforce diverging compliance pathways—pharmaceutical serialization requirements in the Kingdom elevate barrier specification standards, while Pretoria's extended producer responsibility framework imposes material recovery obligations on importers. The UAE's Emirates Authority for Standardization and Metrology coordinates Gulf-standard harmonization for packaging recyclability claims, reducing fragmentation for multinational suppliers. Stakeholders must monitor how divergent national implementation timelines for circular economy mandates reshape regional manufacturing location decisions.
Market Dynamics
Extended producer responsibility mandates across South Africa and the Gulf Cooperation Council are compelling manufacturers to redesign material compositions, creating divergent compliance pathways that reshape regional production footprints and supplier qualification requirements.
Growth Catalysts
- E-commerce logistics expansion:Gulf Cooperation Council operators are scaling molded fiber and air-cushion systems for fragile goods transit, driving specification upgrades across fulfillment networks.
- Saudi SFDA pharmaceutical serialization:Barrier specification standards for cold-chain packaging have elevated technical requirements, opening premium segments for compliant suppliers.
- Jebel Ali free trade zone infrastructure:The UAE's distribution hub operations concentrate regional demand, creating procurement scale effects for protective packaging vendors.
Market Restraints
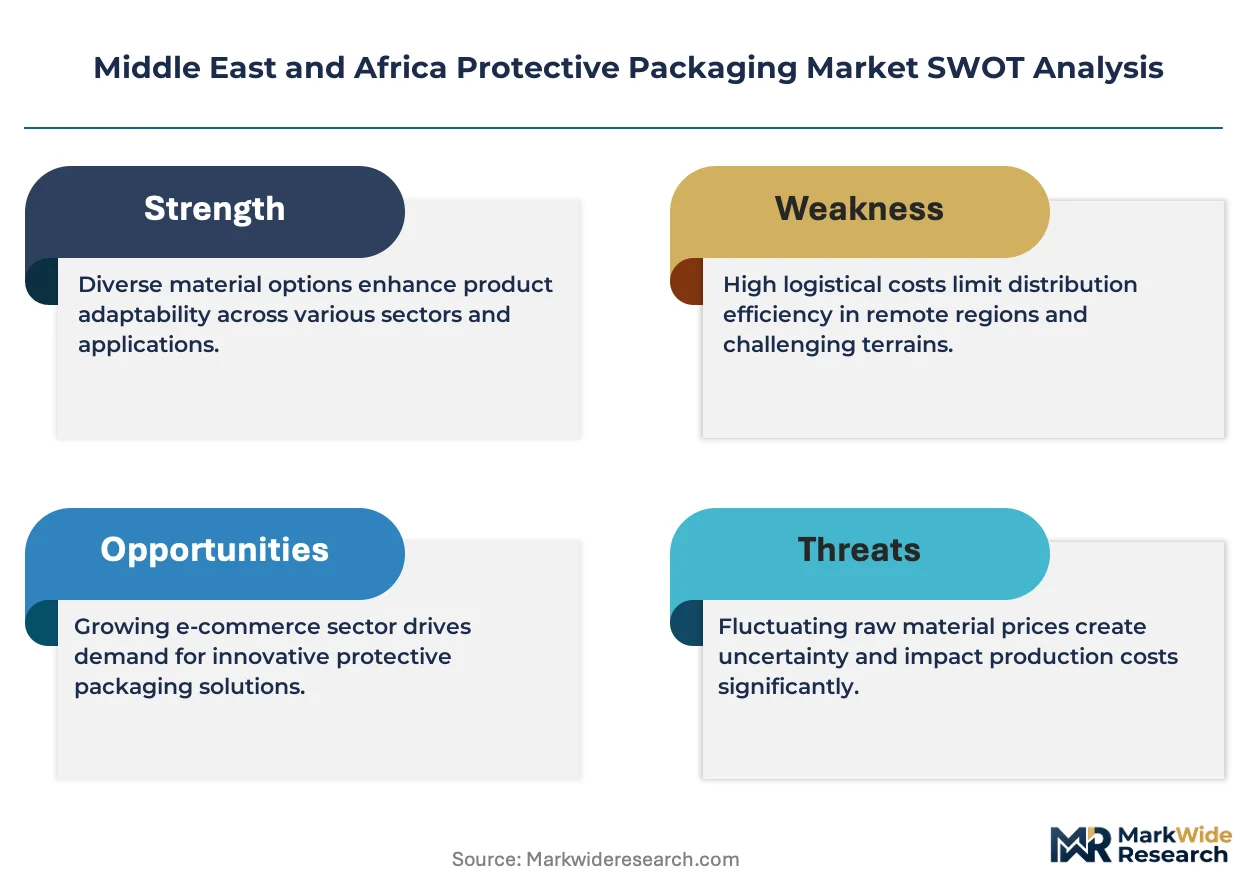
- Petrochemical input volatility:Foam product margins remain exposed to polymer feedstock price swings, compressing working capital flexibility for converters.
- Recyclability claim fragmentation:The UAE's Emirates Authority for Standardization and Metrology coordinates Gulf-standard harmonization, yet national implementation timelines create certification duplication costs.
- Paper-based moisture barrier limitations:Pharmaceutical distributors retain plastic bag specifications where fiber alternatives fail ingress protection thresholds.
Strategic Opportunities
- East African port corridors:FMCG export routes linking Dubai to Mombasa and Dar es Salaam present corrugated fiberboard volume expansion potential.
- Asset-light equipment leasing:Automated packaging line rental models are lowering capital barriers for mid-sized distributors seeking enterprise-grade cushioning capabilities.
- South Africa's EPR framework:Material recovery obligations on importers are creating circular economy service revenue streams for compliant packaging providers.
Industry Challenges
- Multi-jurisdiction certification timelines:Suppliers must navigate divergent SFDA, Department of Forestry Fisheries and Environment, and Emirates Authority for Standardization and Metrology approval processes simultaneously.
- Legacy warehouse automation incompatibility:New cushioning equipment formats require retrofitting existing Gulf distribution centers, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Protective Packaging Market |
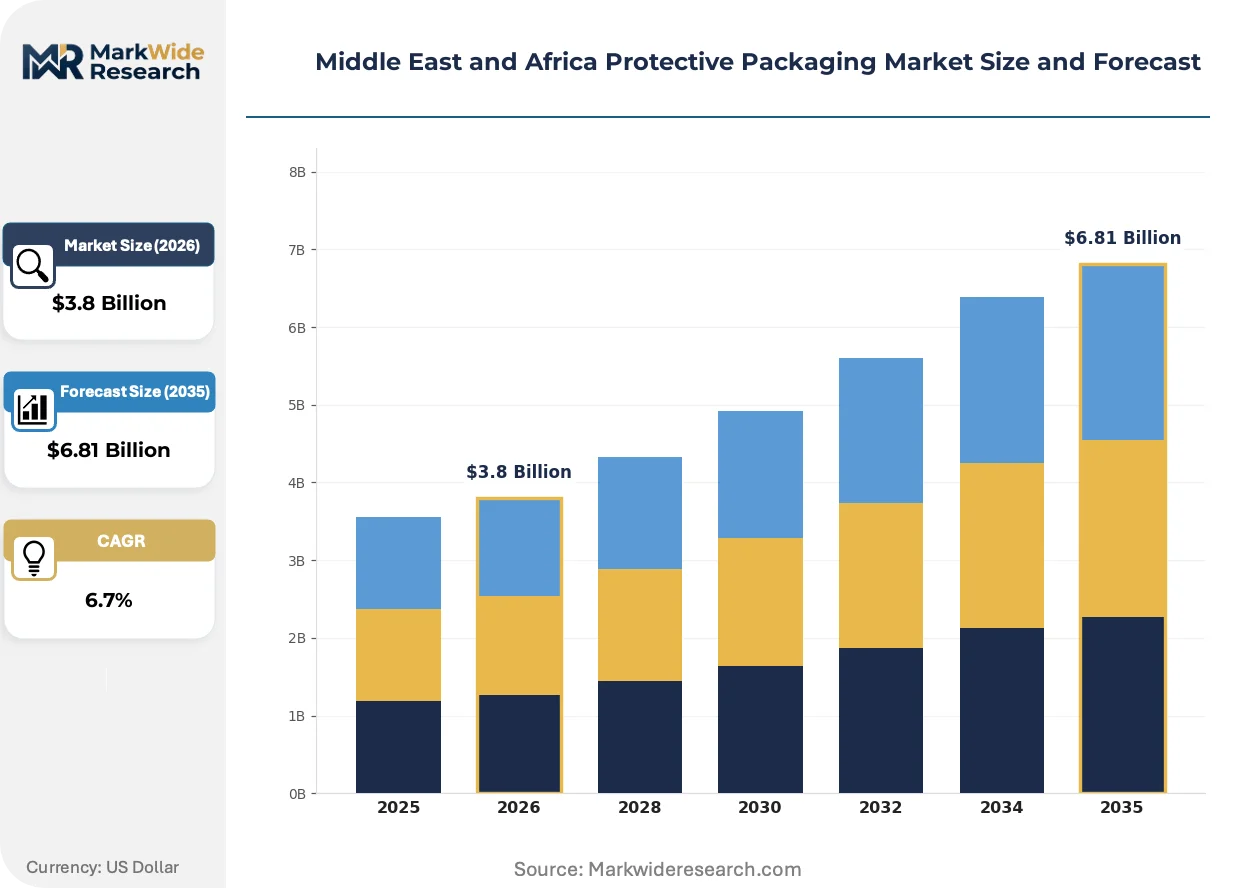
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Boxes, Foam, Wraps Material: Plastic, Paper, Metal, Glass End User: Food, Electronics, Pharmaceuticals, Cosmetics Application: Shipping, Storage, Retail, Distribution |
| Companies Covered | Sealed Air Corporation, DS Smith PLC, Storopack Hans Reichenecker GmbH, International Paper Company, Mondi Plc, Sonoco Products Company, Huhtamaki Oyj, Matco Packaging LLC, Smurfit Kappa Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Protective Packaging Market Shifts & Advancements
Material science advances and regulatory harmonization efforts are compressing traditional product lifecycles, with fiber-based alternatives gaining specification share against established polymer systems across temperature-controlled and fragile goods segments.
Molded pulp technology is migrating from secondary cushioning applications into primary pharmaceutical and electronics containment roles. Cold-chain operators in Saudi Arabia and the UAE are piloting fiber-based insulated shippers for last-mile delivery. This shift is enabling local material sourcing while compressing reliance on imported expanded polystyrene volumes.
South Africa's Department of Forestry, Fisheries and Environment has activated extended producer responsibility regulations for packaging waste, imposing material recovery obligations on importers and domestic manufacturers. The framework mandates audited recycling targets and eco-modulated fee structures. Pharmaceutical and FMCG packagers are responding by redesigning multi-material laminates into mono-fiber configurations.
Quick-commerce channels are consolidating supplier relationships around integrated protective packaging and fulfillment services. Food service aggregators across Dubai and Riyadh are bundling temperature retention and shock protection specifications into single-source contracts. This concentration is most visible in the UAE, where platform economics favor vendors offering design-to-delivery packaging programs over commodity material supply.
Middle East and Africa Protective Packaging Market Segmentation
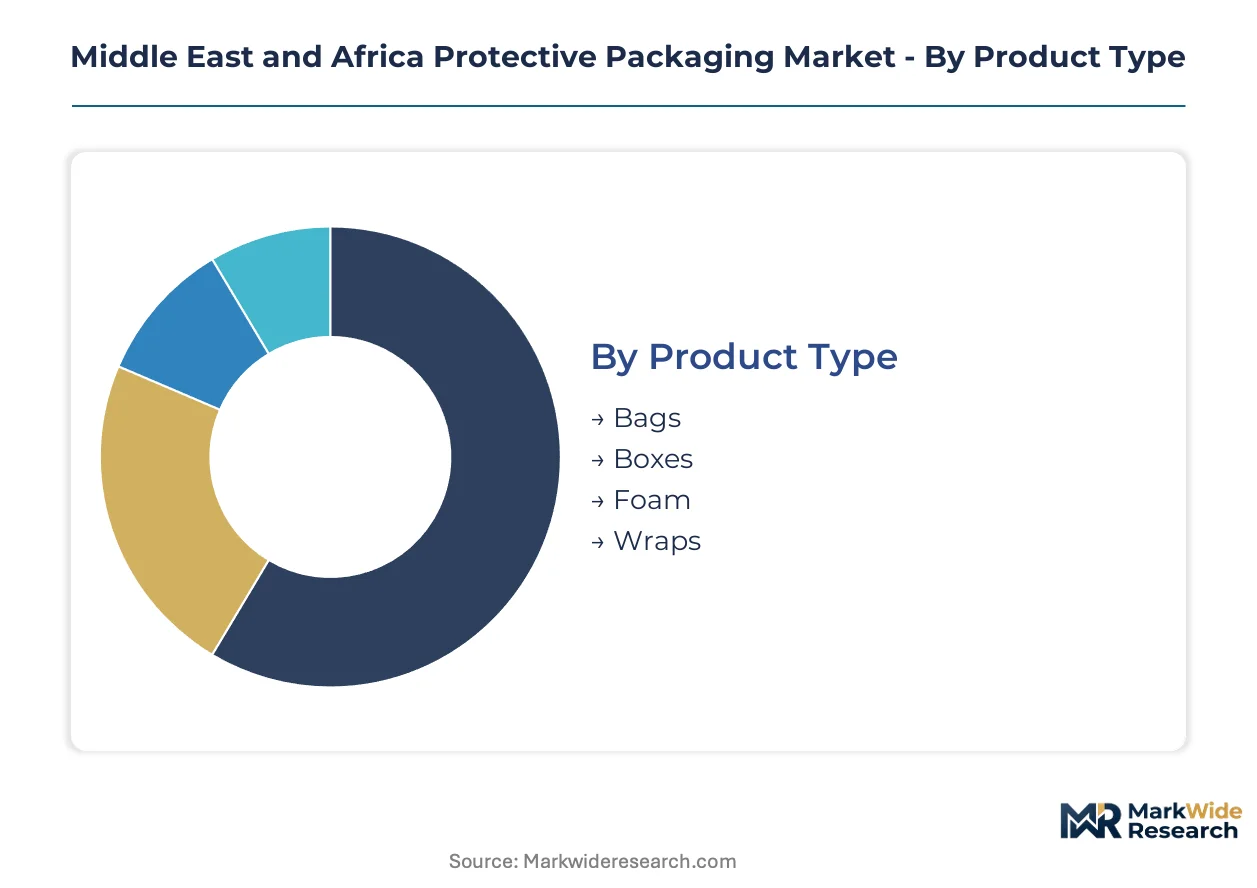
Protective packaging segmentation in the Middle East and Africa reflects divergent compliance pressures and supply chain configurations across the Gulf Cooperation Council and sub-Saharan Africa. Material specifications vary sharply between Saudi pharmaceutical corridors requiring SFDA-compliant barrier properties and South African FMCG channels navigating extended producer responsibility mandates.
Product Type:
End-use requirements span temperature-controlled pharmaceutical transit, shock-sensitive electronics handling, and moisture-resistant food distribution, creating distinct performance thresholds across each format.
- Foam:Expanded polystyrene and polyethylene formulations deliver specified compression resistance for high-value electronics moving from Gulf manufacturing zones to East African consumer markets. Saudi Arabia's cold-chain operators are piloting fiber-based insulated alternatives, though polymer systems retain dominance where thermal performance is non-negotiable.
- Wraps:Multi-layer laminates and molded pulp sheets absorb mechanical shock during last-mile delivery across Dubai's quick-commerce networks. Paper-based wraps capture specification share in food service channels seeking fiber-based alternatives to polymer films.
- Bags:Plastic barrier bags retain volume in pharmaceutical distribution where moisture ingress protection meets SFDA serialization requirements.
- Boxes:Corrugated fiberboard containers anchor FMCG export corridors linking Jebel Ali to Mombasa and Dar es Salaam, with DS Smith PLC specialization concentrated in this segment.
Established volume favors Boxes; emerging adoption favors Wraps.
Material:
Cost tiers separate commodity feedstocks from engineered substrates, with recyclability premiums reshaping procurement calculations under divergent national implementation timelines.
- Plastic:Polymer films and foams dominate high-barrier applications where moisture protection is mandatory. Petrochemical input volatility compresses converter margins, yet pharmaceutical cold-chain operators retain plastic specifications where fiber alternatives fail ingress thresholds.
- Paper:Molded pulp and corrugated fiberboard gain specification share as South Africa's Department of Forestry, Fisheries and Environment imposes material recovery obligations. Quick-commerce channels in Dubai and Riyadh are consolidating supplier relationships around integrated paper-based fulfillment services.
- Metal:Aluminum laminates serve niche pharmaceutical and cosmetics applications requiring absolute light and oxygen barrier properties.
- Glass:Rigid containment for high-value cosmetics and specialty pharmaceuticals remains limited by weight and fragility constraints in extended African supply chains.
Procurement is shifting toward Paper in food and consumer channels; Plastic retains defensive positioning in regulated pharmaceutical segments.
End User:
Customer type determines specification intensity, with serialization mandates and temperature requirements creating tiered compliance burdens.
- Pharmaceuticals:Saudi SFDA barrier specifications and UAE cold-chain standards elevate technical requirements for shippers and insulated containers. Sealed Air Corporation sustains long-term contracts through regional service network coverage.
- Electronics:Shock protection for smartphones, computers, and components transiting from Gulf assembly zones to African markets drives foam and air-cushion system demand.
- Food:Temperature retention and moisture control specifications bundle into single-source contracts for Dubai and Riyadh food service aggregators.
- Cosmetics:Premium positioning demands aesthetic presentation layers alongside functional protection, favoring multi-material laminates.
Pharmaceuticals command premium pricing; Food represents the steepest expansion trajectory as quick-commerce penetration deepens.
Application:
Supply chain position determines handling intensity and protection duration, from single-touch retail to multi-leg international distribution.
- Shipping:Extended transit from Gulf manufacturing hubs through East African port corridors demands compression-resistant containment with tracked damage rate accountability.
- Distribution:Jebel Ali's free trade zone infrastructure concentrates regional procurement scale, creating volume concentration effects for protective packaging vendors serving hub-and-spoke networks.
- Storage:Warehouse conditioning requirements vary across climate zones, with humidity control specifications more stringent in coastal Gulf facilities than inland African depots.
- Retail:Shelf-ready presentation and theft-deterrent features layer onto base protection functions for cosmetics and electronics in mall-based and e-commerce pickup formats.
Distribution captures procurement volume concentration; Shipping is gaining share fastest as direct-to-consumer cross-border volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement managers at pharmaceutical distributors and FMCG exporters concentrate demand across Gulf Cooperation Council logistics hubs and South African manufacturing corridors, with specification intensity varying by national regulatory enforcement.
United Arab Emirates
Jebel Ali's free trade zone infrastructure anchors regional distribution hub operations, with fulfillment networks scaling molded fiber and air-cushion systems for fragile goods transit. The Emirates Authority for Standardization and Metrology coordinates Gulf-standard harmonization for packaging recyclability claims. Dubai's quick-commerce channels consolidate supplier relationships around integrated protective packaging and fulfillment services.
Saudi Arabia
SFDA pharmaceutical serialization requirements elevate barrier specification standards for cold-chain packaging, opening premium segments for compliant suppliers. The Kingdom's national pharmaceutical regulator enforces diverging compliance pathways from neighboring Gulf states. Riyadh's food service aggregators bundle temperature retention and shock protection specifications into single-source contracts.
South Africa
The Department of Forestry, Fisheries and the Environment imposes material recovery obligations on importers through extended producer responsibility regulations. Pretoria's framework mandates audited recycling targets and eco-modulated fee structures. Cape Town and Durban manufacturing corridors are redesigning multi-material laminates into mono-fiber configurations to meet compliance.
Egypt
Nile Delta manufacturing zones serve as entry points for European protective packaging technologies into North African markets. The country's national standards body maintains alignment with Gulf Cooperation Council technical regulations where feasible. Alexandria's port infrastructure supports transshipment volumes for FMCG exporters targeting Levantine consumer markets.
Israel
High-value electronics transit from Gulf manufacturing zones drives specification demand for shock-absorbing containment systems. The national standards institute participates in regional technical harmonization dialogues. Tel Aviv's logistics technology sector pilots automated packaging line integration for e-commerce fulfillment networks.
Middle East and Africa Protective Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent national compliance pathways, with procurement scale effects concentrating around Jebel Ali hub operations and Saudi pharmaceutical corridors. The vendor base spans multinational material science conglomerates with regional service networks and mid-sized converters leveraging asset-light equipment leasing models. Three archetypes dominate: integrated material-format specialists, regional logistics service bundlers, and compliance-focused pharmaceutical packaging providers. Competitive moves center on strategic partnerships with e-commerce platform operators and portfolio diversification into fiber-based alternatives.
Within the integrated material-format tier, Sealed Air Corporation and DS Smith PLC occupy anchor positions. Sealed Air exemplifies the regional service network archetype sustaining long-term contracts with pharmaceutical cold-chain operators. DS Smith represents corrugated fiberboard specialization for FMCG export corridors. Storopack Hans Reichenecker GmbH sits within the molded foam and air-cushion systems segment serving electronics transit requirements.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| DS Smith PLC |
| Storopack Hans Reichenecker GmbH |
| International Paper Company |
| Mondi Plc |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Matco Packaging LLC |
| Smurfit Kappa Group |
| Others |
Supply & Pricing Matrix
Undercapacity in South Africa's molded fiber converter base is compressing lead times and elevating spot pricing for compliant packaging, forcing Gulf buyers to absorb freight premiums or accept longer procurement cycles from distant suppliers.
Pricing Analysis
Certification level creates the primary spread between SFDA-compliant pharmaceutical shippers and standard-grade FMCG containers. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance, serialization readiness, and cold-chain validation depth. Cost compression in the standard tier is intensifying because petrochemical input volatility squeezes converter margins on polymer-based alternatives. Pharmaceutical distributors exhibit the lowest price sensitivity due to non-negotiable serialization mandates, while quick-commerce food aggregators drive hard volume discounts.
Supply Chain Analysis
Extended payment terms from Jebel Ali distribution hub operators are financing upstream converter inventory positions across the UAE, Saudi Arabia, and Egypt. Raw material feeds draw from GCC petrochemical complexes for polymer foams, Nordic pulp mills for fiberboard, and Indian laminate suppliers for barrier films. Single-source vulnerability concentrates in imported expanded polystyrene volumes for electronics cushioning. Distribution runs through hub-and-spoke networks anchored at Jebel Ali, with last-mile fragmentation across East African port corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through an EPR-driven compliance wave, with South Africa's material recovery mandates and Saudi serialization requirements creating divergent premium tiers that favor prepared suppliers.
For Market Incumbents: Entrench through backward integration into GCC pulp molding capacity and exclusive service contracts with Dubai's quick-commerce platforms. DS Smith PLC's corrugated specialization and Sealed Air Corporation's cold-chain service networks demonstrate how certification depth blocks substitution. Threat: Asset-light leasing models erode capital barrier advantages for mid-sized distributors. For New Entrants and Emerging Players: East African port corridors from Mombasa to Dar es Salaam offer the most penetrable geography, with corrugated fiberboard demand outpacing local converter capacity. Target FMCG exporters seeking mono-fiber configurations to preempt South African EPR compliance costs. Go-to-market angle: bundled design-to-delivery programs mimicking Dubai's integrated fulfillment services. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical packaging providers with SFDA-validated cold-chain capabilities. Long-term viability centers on fiber-based thermal protection technology migration. Acquisition archetype: regional converters with installed molded pulp capacity and Gulf regulatory relationships. Signal to monitor: Emirates Authority for Standardization and Metrology acceleration of recyclability claim harmonization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Molding | Captures margin from Nordic pulp suppliers while meeting South African EPR mandates. |
| SFDA Certification Investment | Opens premium pharmaceutical segments with barrier specification premiums in Saudi Arabia. |
| Asset-Light Equipment Leasing | Lowers capital barriers for mid-sized distributors seeking automated cushioning capabilities. |
| East African Distribution Partnership | Secures volume corridors linking Jebel Ali to Mombasa and Dar es Salaam FMCG exporters. |
| Quick-Commerce Platform Integration | Consolidates supplier relationships around bundled temperature retention and shock protection. |
Research Methodology
A standing panel of packaging procurement managers, cold-chain logistics directors, regulatory compliance officers, and converter plant engineers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with customs data, Emirates Authority for Standardization and Metrology filings, and SEC disclosures from listed packaging multinationals. Bottom-up volume estimates from end-use segments triangulated against top-down trade flow analysis.
Scenario-bracketing anchored projections across regulatory implementation timelines and petrochemical price volatility bands. Segmentation dimensions spanned material type, product format, end-use vertical, and national compliance cluster. CAGRs derived from elasticity modeling against e-commerce penetration and pharmaceutical export growth. Industry-specific inputs included SFDA serialization rollout pace and South African EPR audited recovery rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian pulp molders or accelerated Gulf standard harmonization would shift outcomes. Macroeconomic deviation, regulatory enforcement delays, or breakthrough fiber-based thermal performance could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market