
 Packaging and Protective Packaging Market | 2026-2036
Packaging and Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging and Protective Packaging Market Analytics
Modular packaging configurations is decoupling bulk procurement from just-in-line replenishment across consumer goods supply chains. Sealed Air Corp. leverages film-based automation platforms to sustain contract logistics relationships. Mondi Plc anchors European kraft paper supply through integrated pulp-to-box operations. Berry Global Inc. differentiates via multi-layer barrier films for medical sterilization applications.
Packaging and protective packaging encompasses engineered enclosures, cushioning systems, and containment structures manufactured from plastics, paper substrates, metals, or glass, with specifications spanning barrier permeability coefficients, drop-test resilience, and seal-integrity thresholds designed to preserve product condition through distribution cycles. Flexible packaging leads material conversion economics due to source-reduction potential and transport efficiency, while rigid formats retain dominance in premium spirits and pharmaceutical stability applications. Protective packaging segments concentrate margin pools around inflatable void-fill and molded fiber technologies as e-commerce damage-rate sensitivity intensifies.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks shape material substitution timelines across European converter operations, while FDA food-contact notification requirements govern barrier coating approvals in U.S. nutrition markets. China's GB standards and SAMR circular economy directives are accelerating post-consumer recycled content mandates for domestic fast-moving consumer goods. Stakeholders must monitor regulatory divergence between extended producer responsibility schemes and chemical migration limits when configuring multi-territory product portfolios.
Market Dynamics
E-commerce fulfillment velocity is compressing damage-rate tolerances across last-mile networks, forcing protective packaging specifications upward while material lightweighting mandates pull in the opposite direction. This structural tension between performance and sustainability is redrawing converter investment priorities.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds are accelerating film-to-paper substrate conversions across German and French converter bases.
- India food processing:Flexible pouch demand from ready-to-eat and spice packaging segments is expanding biaxially oriented polypropylene capacity in Gujarat and Maharashtra clusters.
- Inflatable void-fill automation:Warehouse robotics integration is standardizing air cushion systems as the default protective format for electronics and cosmetics fulfillment.
Market Restraints
- Polypropylene resin volatility:Propylene feedstock exposure in Middle Eastern and North American supply corridors creates margin compression for film extruders without long-term offtake contracts.
- Kraft pulp concentration:Nordic and Brazilian pulp-to-paper integration limits independent converter access to virgin fiber during demand spikes.
- Multi-layer film recyclability:EVOH and metallized barrier layers remain technically incompatible with mechanical recycling streams under current sorting infrastructure.
Strategic Opportunities
- Vietnam electronics manufacturing:Samsung and Foxconn expansion in Bac Ninh and Hai Phong is creating localized protective packaging demand currently served by imported formats.
- FDA food-contact notification pathways:Bio-based barrier coatings derived from agricultural waste streams qualify for expedited approval, opening premium positioning in U.S. organic food channels.
- Reusable transport packaging:Pooling system operators are penetrating automotive and beverage closed-loop supply chains with RFID-tracked intermediate bulk containers.
Industry Challenges
- Barrier coating chemist scarcity:Formulation expertise for oxygen and moisture migration control concentrates in legacy German and Japanese research centers, constraining rapid product development elsewhere.
- Extended producer responsibility compliance:Divergent national registration and fee structures across EU member states fragment packaging portfolio management for pan-European brands.
- Legacy heat-seal equipment retrofit:Ultrasonic and laser sealing technologies require substantial line reconfiguration that disrupts continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging and Protective Packaging Market |
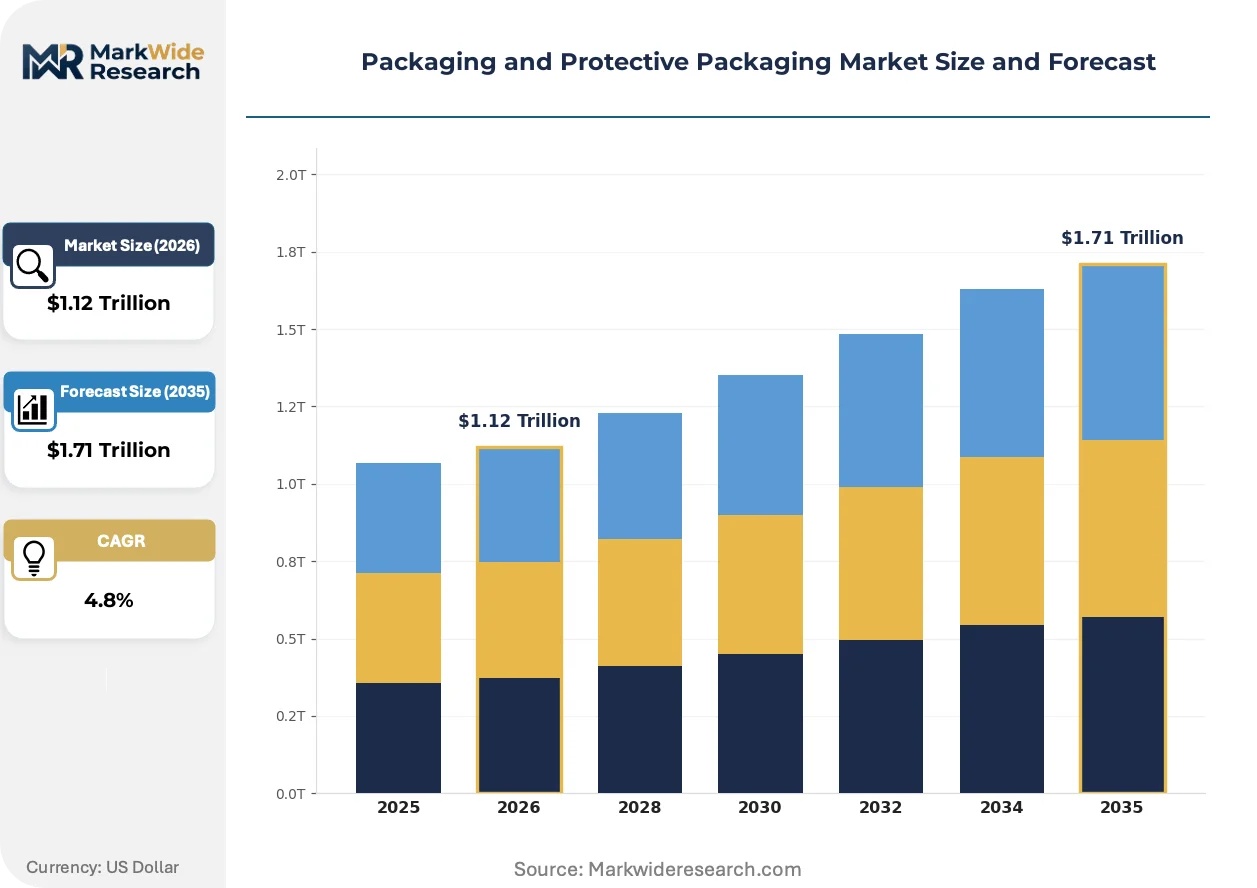
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.71 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Labels, Protective Packaging Material: Plastic, Paper, Metal, Glass End User: Food & Beverage, Healthcare, Electronics, Retail Application: Food Packaging, Medical Packaging, Consumer Goods, Industrial Packaging |
| Companies Covered | Smurfit Kappa Group, Sealed Air Corp., DS Smith Plc, Berry Global Inc., Sonoco Products Company, Crown Holdings Inc., International Paper Co., Mondi Plc, WestRock Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging and Protective Packaging Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from pharmaceutical cold chain into fresh food and high-value electronics segments. Material science advances and regulatory pressure are converging to accelerate format substitution timelines.
Monomaterial barrier films is rewriting compatibility with existing polyethylene and polypropylene recycling streams. Major European retailers are mandating single-substrate specifications for private-label packaging by 2025. This technology is compressing multi-layer laminate market share in snack and dry goods categories where shelf-life requirements permit.
REACH chemical authorization restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant coatings from paper foodservice applications. Fluorine-free barrier alternatives derived from biomass are scaling through pilot programs in Nordic markets. Bakery and fast-food packaging segments are reformulating specifications fastest where national bans precede EU-wide harmonization.
Direct-to-consumer subscription models are fragmenting order sizes and compressing replenishment cycles. Third-party logistics providers are replacing corrugated shipper cases with right-sized flexible mailers and paper-based cushioning. This pattern is most visible in U.S. beauty and supplement verticals where unboxing experience drives repeat purchase rates.
Packaging and Protective Packaging Market Segmentation
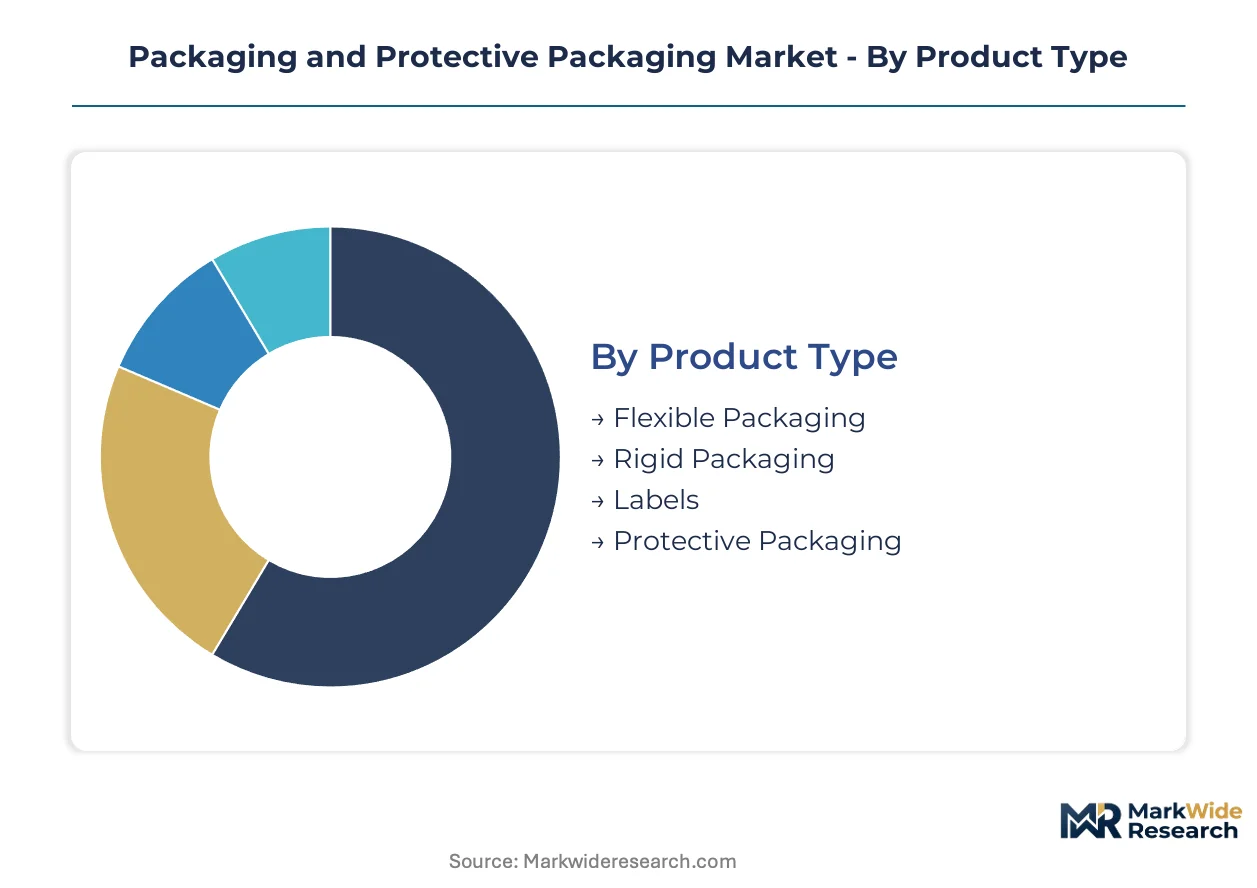
Segmentation in packaging markets tracks how material specifications, regulatory thresholds, and end-use damage sensitivity reshape procurement priorities across converter operations. Buyers configure specifications around barrier performance, recyclability mandates, and automation compatibility rather than unit cost alone.
Product Type:
Application requirements for shelf-life extension and transit protection determine format selection more than material cost differentials.
- Flexible Packaging:Multi-layer films and pouches deliver source reduction through gauge optimization and conformability to irregular product geometries. Demand concentrates in India's spice and ready-to-eat segments where BOPP capacity expansion in Gujarat clusters serves domestic food processors.
- Protective Packaging:Inflatable void-fill, molded fiber, and foam-in-place systems absorb mechanical stress during distribution cycles. E-commerce fulfillment velocity in Asia-Pacific logistics corridors is accelerating specification upgrades for electronics and cosmetics damage-rate thresholds.
- Rigid Packaging:Bottles, jars, and thermoformed trays provide structural integrity for premium spirits and pharmaceutical stability applications where barrier permeability coefficients are non-negotiable.
- Labels:Pressure-sensitive and shrink-sleeve formats carry regulatory compliance markings and authentication features across pharmaceutical and food contact applications.
Volume sits with flexible formats; growth tilts toward protective packaging as last-mile damage sensitivity intensifies.
Material:
Recyclability infrastructure maturity and chemical migration limits now override traditional cost-per-unit metrics in material specification.
- Plastic:Polyethylene and polypropylene dominate conversion economics through thermal processability and moisture barrier performance. Monomaterial specifications are displacing multi-layer laminates in European snack packaging as retailers mandate single-substrate compatibility.
- Paper:Kraft and containerboard grades serve corrugated shipper cases and molded fiber cushioning with renewable fiber credentials. Nordic pulp-to-paper integration limits independent converter access during demand spikes.
- Metal:Aluminum and steel cans deliver absolute barrier performance for oxygen-sensitive beverages and retort-processed foods.
- Glass:Premium spirits and pharmaceutical stability applications retain inert surface properties despite weight penalties in transport economics.
Plastic retains volume leadership; paper gains share fastest where EU recycled content mandates accelerate film-to-substrate conversions.
End User:
Regulatory scrutiny intensity and damage-rate tolerance thresholds diverge sharply across buyer categories.
- Food & Beverage:Barrier coating specifications must satisfy FDA food-contact notification pathways and EU REACH chemical compliance for migration limits. Bio-based alternatives from agricultural waste streams qualify for expedited approval in U.S. organic channels.
- Electronics:Static-dissipative and moisture-vapor-transmission specifications protect semiconductor components through Asia-Pacific manufacturing corridors. Samsung and Foxconn expansion in Vietnam's Bac Ninh province is creating localized protective packaging demand.
- Healthcare:Medical sterilization applications require multi-layer barrier films with seal-integrity thresholds validated for gamma and ethylene oxide exposure.
- Retail:Third-party logistics providers are replacing corrugated shipper cases with right-sized flexible mailers for direct-to-consumer subscription models in U.S. beauty verticals.
Food and beverage commands volume; electronics expands most quickly as manufacturing gravity shifts toward Vietnam and India.
Application:
Process integration requirements and automation compatibility separate commodity specifications from premium positioning.
- Food Packaging:Modified atmosphere and vacuum configurations extend shelf life through oxygen scavenging and moisture control. Fluorine-free barrier alternatives are scaling through Nordic pilot programs as REACH restrictions eliminate PFAS coatings.
- Medical Packaging:Sterile barrier systems combine Tyvek or medical-grade paper with thermoformed trays for surgical instrument containment. Seal-integrity validation protocols govern converter qualification timelines.
- Consumer Goods:Unboxing experience specifications drive rigid box and molded pulp adoption in premium cosmetics where repeat purchase rates correlate with presentation quality.
- Industrial Packaging:Intermediate bulk containers and drum formats serve chemical and lubricant distribution with UN certification requirements for hazardous material transit.
Food packaging anchors volume; medical packaging climbs the fastest as sterile barrier complexity concentrates margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in pulp-integrated Nordic operations and resin-based extrusion corridors, while consumption tilts toward e-commerce fulfillment zones in Asia-Pacific and North American logistics networks. This geographic disconnect shapes converter investment flows and regional trade balances.
United States
Third-party logistics providers in Memphis and Louisville hubs are replacing corrugated shipper cases with right-sized flexible mailers for direct-to-consumer beauty and supplement verticals. FDA food-contact notification requirements govern barrier coating approvals in nutrition markets. Midwest converter operations in Ohio and Wisconsin supply molded fiber cushioning to electronics distribution centers.
Germany
REACH chemical authorization restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant coatings from paper foodservice applications. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that accelerate film-to-paper substrate conversions. Bavarian converter clusters near Munich specialize in medical sterilization barrier films.
China
GB standards and SAMR circular economy directives accelerate post-consumer recycled content mandates for domestic fast-moving consumer goods. Yangtze River Delta manufacturing corridors generate protective packaging demand for semiconductor components. Shenzhen and Dongguan electronics assembly operations specify static-dissipative formats for export shipments.
India
Flexible pouch demand from ready-to-eat and spice packaging segments expands biaxially oriented polypropylene capacity in Gujarat and Maharashtra clusters. FSSAI compliance frameworks govern food-contact material specifications. Mumbai-Pune industrial corridor converters serve domestic food processors with modified atmosphere configurations.
Vietnam
Samsung and Foxconn expansion in Bac Ninh and Hai Phong creates localized protective packaging demand currently served by imported formats. The country's national industrial regulator enforces packaging material standards for electronics export certification. Northern manufacturing zones concentrate inflatable void-fill and molded fiber specification requirements.
Packaging and Protective Packaging Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-paper operators and multi-layer film specialists. Tier-one players control virgin fiber supply through captive pulp operations, while mid-scale converters compete on automation compatibility and regional logistics proximity. Three archetypes dominate: Nordic kraft paper integrators, North American corrugated scale operators, and European flexible film barrier specialists. Capacity expansion and substrate conversion partnerships represent the dominant competitive moves as regulatory timelines compress.
Among integrated paper-based operators, Smurfit Kappa Group and Mondi Plc exemplify the pulp-captive archetype with European kraft supply chain control. Sealed Air Corp. occupies a position within the automated protective systems tier, representing film-based platform specialization. These three anchors illustrate how geographic integration and technology focus separate margin pools in converter operations.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Sealed Air Corp. |
| DS Smith Plc |
| Berry Global Inc. |
| Sonoco Products Company |
| Crown Holdings Inc. |
| International Paper Co. |
| Mondi Plc |
| WestRock Co. |
| Others |
Value Network & Pricing Analysis
Third-party logistics providers in Memphis and Louisville hubs command pricing leverage through consolidated procurement volumes, compressing margins for mid-scale converters unable to match automation compatibility at scale. This buyer concentration enforces three-tier pricing stratification across premium certified, standard industrial, and economy spot-contract tiers.
Pricing Analysis
Margin tightening in standard-grade flexible film reflects propylene feedstock volatility across Middle Eastern and North American supply corridors. Three-tier pricing structure across premium barrier-certified, standard FDA-compliant, and economy non-food-contact levels separates converters by migration-limit certification. Cost-down pressure on molded fiber cushioning accelerates because kraft pulp spot markets spike during Nordic demand surges. Small-format e-commerce fulfillment buyers exhibit highest price sensitivity; medical sterilization barrier film purchasers show lowest elasticity due to seal-integrity validation requirements.
Supply Chain Analysis
Single-source vulnerability sits with Nordic kraft pulp integration controlling virgin fiber access during demand spikes. Raw material flows draw from Brazilian eucalyptus pulp, Saudi propylene derivatives, and German barrier coating chemicals. Tariff exposure on Chinese molded fiber equipment fragments converter capital expenditure timelines. Distribution runs through regional converter hubs serving last-mile logistics clusters in Vietnam's Bac Ninh province and India's Gujarat corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Packaging and Protective Packaging Market functions as a consolidation play where EU Packaging and Packaging Waste Regulation compliance costs force sub-scale converters toward exit or acquisition.
For Market Incumbents: Anticipate substrate conversion timelines compressing as German and French retailers mandate monomaterial specifications by 2025. Secure backward integration into Nordic kraft pulp supply or captive BOPP extrusion capacity in Gujarat clusters. Barrier coating formulation expertise concentrates in legacy German research centers; acquire or partner to lock scarce chemist talent before competitor consolidation. For New Entrants and Emerging Players: Vietnamese electronics contract manufacturers currently import protective formats from China and South Korea, creating white-space for localized inflatable void-fill and molded fiber production. Target FDA food-contact notification pathways for bio-based barrier coatings derived from agricultural waste streams; expedited approval opens premium positioning in U.S. organic channels with limited incumbent competition. For Investors and Strategic Acquirers: The window for entry favors mid-scale European flexible film converters with monomaterial R&D pipelines and established retailer relationships. Monitor REACH chemical authorization restrictions on PFAS coatings as inflection indicator; fluorine-free barrier alternatives will separate acquisition targets with viable substitution timelines from stranded multi-layer laminate operations.| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Film Conversion | European retailers mandate single-substrate compatibility, displacing multi-layer laminate market share in snack packaging. |
| Backward Integration into Pulp Supply | Nordic kraft paper integrators control virgin fiber access during demand spikes, securing margin stability. |
| Barrier Coating R&D Partnership | German and Japanese research centers concentrate scarce formulation expertise for oxygen migration control. |
| Localized Vietnam Production | Samsung and Foxconn expansion in Bac Ninh creates protective packaging demand currently served by imports. |
| Fluorine-Free Coating Scale-Up | REACH PFAS restrictions eliminate legacy oil-and-grease-resistant coatings from paper foodservice applications. |
Research Methodology
Multi-period observation of EU recycled content mandate implementation, Asia-Pacific e-commerce damage-rate thresholds, and propylene feedstock pricing anchored the trend analysis, supplemented by interviews with converter operations managers, barrier coating R&D directors, third-party logistics procurement leads, and food-contact regulatory affairs specialists. Secondary validation drew from ECHA REACH authorization databases, EU Packaging and Packaging Waste Regulation impact assessments, U.S. FDA food-contact notification filings, and customs trade data on BOPP film imports. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
Input-output matrices modeled volume and value projections across material substrate, end-use vertical, and geographic production cluster dimensions throughout the forecast period. CAGRs derived from regression analysis of historical capacity expansion cycles correlated with regulatory compliance timeline assumptions. Forecast inputs incorporated SAMR circular economy directive enforcement patterns in China and FSSAI food-contact specification evolution in India.
Revisions become necessary when EU member state EPR fee structures diverge substantially, when mechanical recycling infrastructure deployment lags monomaterial film adoption, or when propylene feedstock corridors experience sustained disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Insulated Shippers Market