
 Ovenable Paperboard Trays Market | 2026-2036
Ovenable Paperboard Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Ovenable Paperboard Trays Market Analytics
Finland is fragmenting ovenable paperboard tray capacity as Nordic producers expand specialty fiber operations. Stora Enso Oyj leverages integrated pulp-to-tray manufacturing across Baltic mills. Huhtamaki Oyj anchors European food service supply through coated-barrier technology leadership. Smurfit WestRock competes on scale, operating recycled fiber lines that serve private-label retail programs.
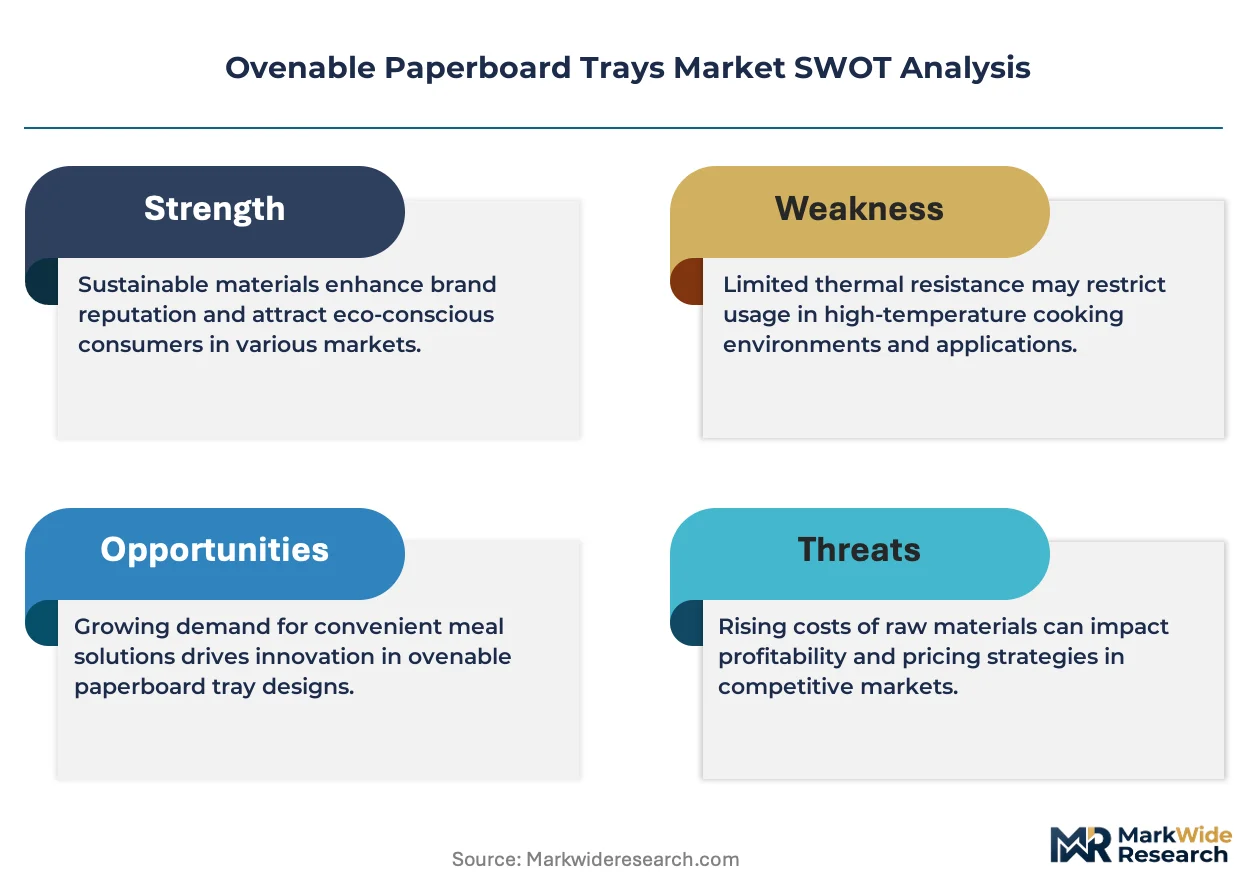
Ovenable paperboard trays are rigid, heat-stable fiber containers engineered with PET or PP barrier coatings to withstand temperatures up to 220°C without structural failure, designed for direct-to-oven food preparation and retail distribution. Single-compartment formats dominate volume in frozen entrée applications where standardization reduces tooling costs. Multi-compartment trays capture premium positioning in balanced-meal retail segments, while coated paperboard variants lead technical performance as fluorochemical-free barriers replace legacy grease-resistant chemistries.
EU F-Gas Regulation and REACH compliance frameworks restrict per- and polyfluoroalkyl substances in food-contact materials, redirecting R&D toward mineral and bio-based barrier coatings. FDA food-contact substance notifications govern US market entry for coated trays, while Germany's national packaging ordinance enforces extended producer responsibility thresholds. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions to align product development with compliance timelines.
Market Dynamics
The EU F-Gas Regulation and REACH compliance timelines are compressing product development cycles across the ovenable paperboard trays sector, forcing manufacturers to accelerate fluorochemical-free barrier validation while maintaining thermal performance thresholds above 200°C.
Growth Catalysts
- Single-use plastic directives:Europe's packaging waste regulations mandate fiber-based alternatives in food service channels, creating structural pull for oven-safe paperboard formats in ready-to-eal meal segments.
- Institutional catering:German retail chains and hospital food service operators specify recyclable, oven-direct packaging to meet extended producer responsibility thresholds.
- Coated-barrier technology:Mineral and bio-based coatings that withstand 220°C without structural failure are unlocking frozen entrée applications previously served by aluminum.
Market Restraints
- Pulp fiber cost volatility:Nordic integrated producers control specialty fiber supply, exposing mid-scale converters to input price swings when Baltic mill capacity tightens.
- PFAS regulatory friction:Divergent state-level restrictions across US jurisdictions create compliance fragmentation that delays national product rollouts.
- Aluminum tray substitution:Legacy metal formats retain cost advantages in high-volume frozen food segments where microwave-oven dual compatibility is required.
Strategic Opportunities
- Private-label retail programs:Recycled fiber lines serving German discount chains can capture volume expansion as store-brand ready meals displace branded alternatives.
- Multi-compartment premium positioning:Balanced-meal retail segments in France and Benelux reward technical differentiation with price premiums over standardized single-compartment formats.
- EU Green Deal alignment:Packaging producers certifying carbon footprint reductions through EMAS or ISO 14001 gain preferred supplier status in public procurement frameworks.
Industry Challenges
- Barrier coating validation timelines:FDA food-contact substance notifications and EFSA safety assessments require 18-24 month approval cycles that outpace product refresh rates.
- Tooling cost recovery:Custom mold investments for multi-compartment tray geometries demand volume commitments that smaller food service distributors cannot underwrite.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovenable Paperboard Trays Market |
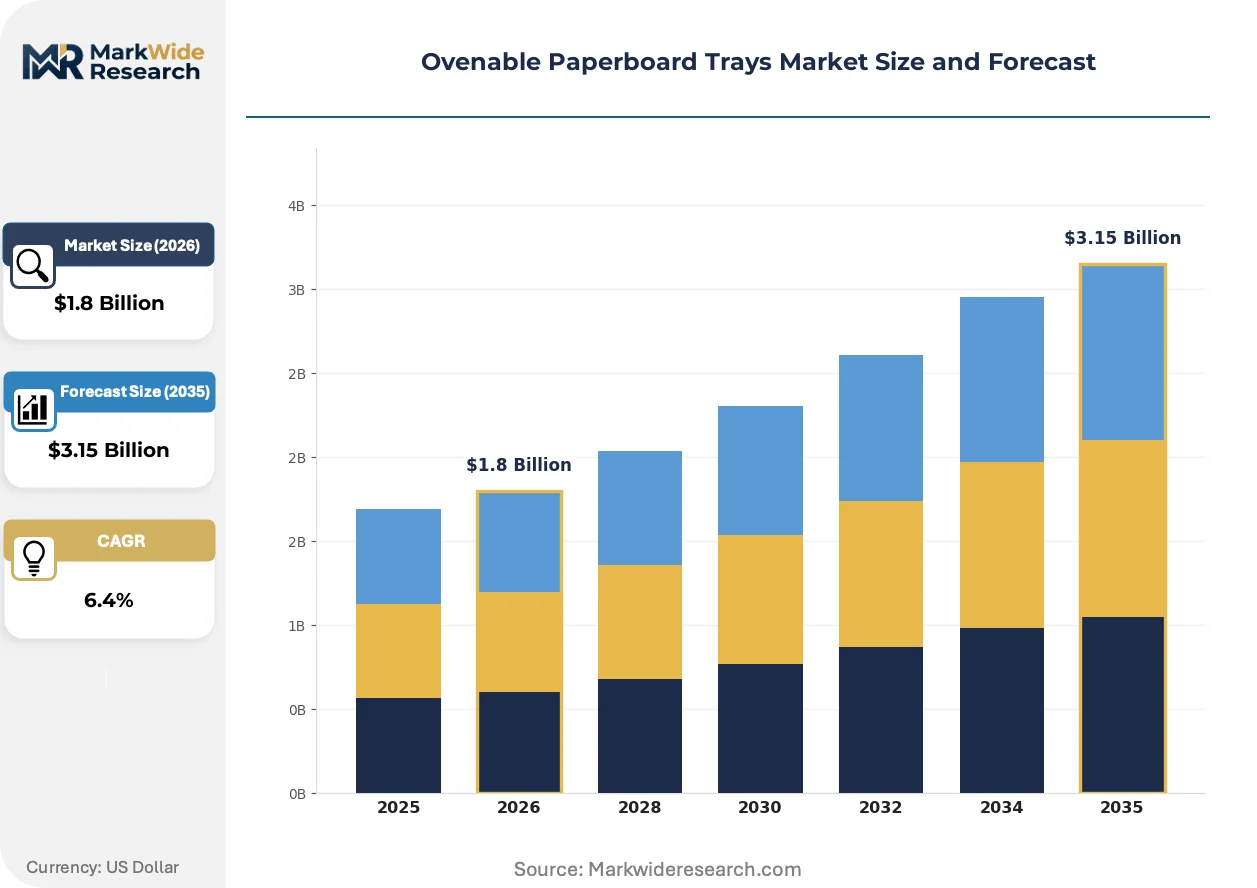
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Compartment, Multi-Compartment, Foldable, Customizable Material: Bleached Paperboard, Unbleached Paperboard, Coated Paperboard, Recycled Fiber End User: Food Service, Retail, Catering, Home Use Distribution Channel: Online Retailers, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Stora Enso Oyj, Smurfit WestRock, Huhtamaki Oyj, DS Smith, International Paper Co., WestRock Company, Mondi Group plc, Graphic Packaging International, Pactiv LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovenable Paperboard Trays Market Evolving Landscape
Barrier coating chemistry is the active frontier in ovenable paperboard tray development, with mineral-based and bio-derived formulations replacing legacy fluorochemical treatments while competing on grease resistance and heat stability metrics.
Mineral-coated paperboard is virtualizing the technical performance envelope for ovenable trays by combining calcium carbonate or clay-based barriers with PET laminates to achieve 220°C thermal thresholds without PFAS chemistry. Frozen entrée packagers in Germany and the Netherlands are qualifying these formats for lasagna and gratin applications where grease migration resistance determines shelf appeal. This technology is virtualizing the competitive boundary between fiber and aluminum containers, compressing the premium that metal formats previously commanded in high-fat food segments.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are accelerating reformulation timelines across European manufacturing operations, with ECHA guidance pushing compliance deadlines into overlapping phases that strain R&D bandwidth. The industrial consequence is a supplier shakeout favoring integrated pulp-to-tray producers with in-house coating development capabilities over converters dependent on third-party barrier film supply. Coated paperboard variants targeting the 180-200°C segment are most affected, as these applications face the tightest substitution pressure from both regulatory bans and customer PFAS-free pledges.
Food service procurement patterns are consolidating around direct specifications from retail chain sustainability offices rather than decentralized category manager decisions, compressing supplier qualification cycles and raising compliance documentation burdens. Distributors serving German and Austrian institutional caterers are replacing spot-buying with framework agreements that lock in three-year supply commitments contingent on annual carbon footprint audits. This shift is most visible in the ready-meal channel, where Aldi Nord and REWE Group central buyers now mandate recyclable packaging certifications as gate criteria for supplier onboarding.
Ovenable Paperboard Trays Market Segmentation
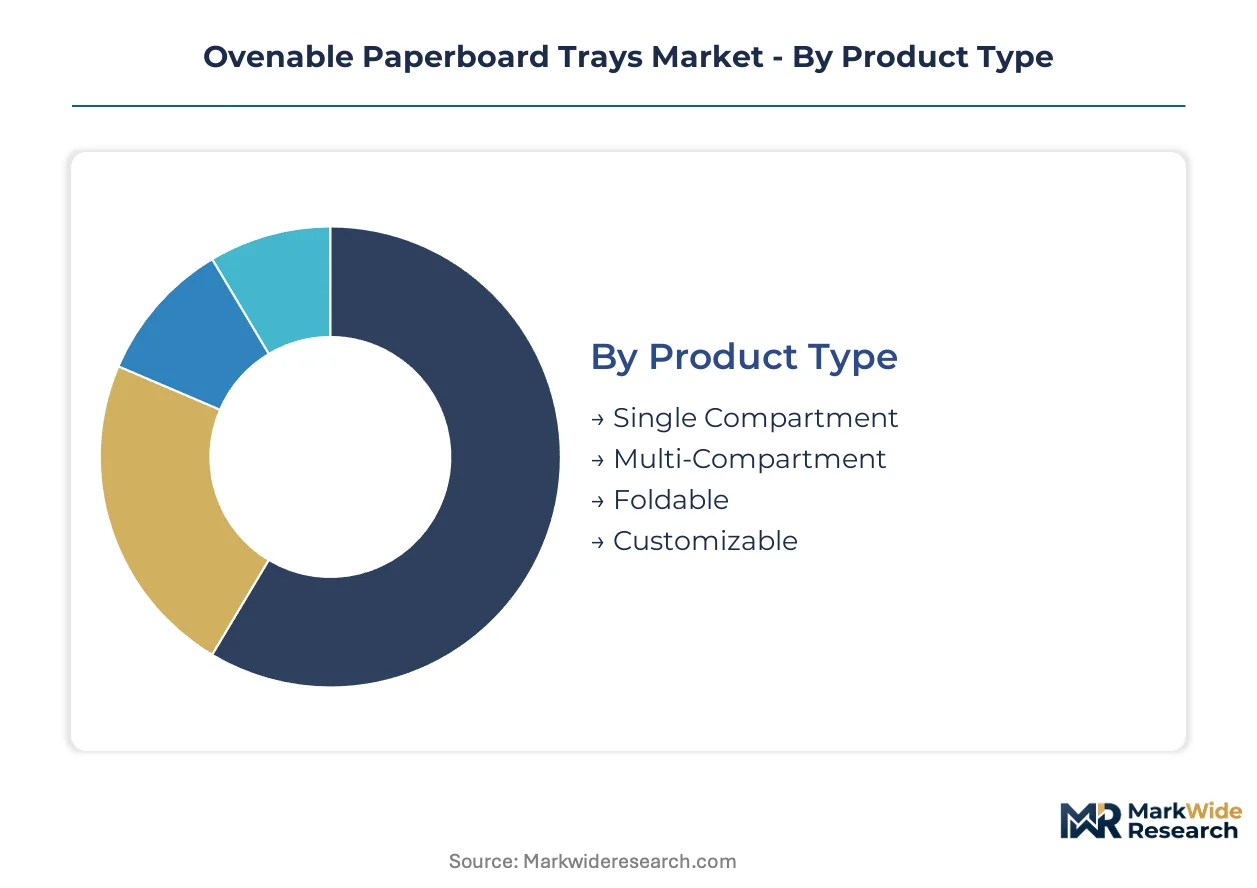
Segmentation in ovenable paperboard trays reveals how thermal performance requirements and regulatory compliance reshape procurement patterns across frozen food and ready-meal channels. Each dimension exposes distinct margin structures and supplier qualification barriers.
Product Type:
Application function determines tooling investment recovery and volume concentration across frozen entrée and food service segments.
- Single Compartment:Standardized one-cavity designs dominate frozen lasagna and gratin applications where tooling amortization spreads across high-volume SKUs. German discount chains specify these formats for private-label ready meals to minimize per-unit packaging costs.
- Multi-Compartment:Segmented cavities enable protein-starch-vegetable separation in balanced-meal retail formats. French and Benelux retailers pay technical premiums for these geometries in premium chilled meal segments.
- Foldable:Collapsible designs reduce cube utilization in frozen distribution networks. Food service distributors in Austria specify these for institutional catering contracts with space-constrained storage.
- Customizable:Bespoke mold configurations serve branded frozen food launches requiring differentiated shelf presence. Tooling cost recovery demands volume commitments that exclude smaller regional distributors.
Single compartment formats command the established base. The steepest expansion runs through multi-compartment premium positioning.
Material:
Raw fiber sourcing and barrier chemistry create tiered performance envelopes that align with regulatory pressure on PFAS-containing formulations.
- Coated Paperboard:Mineral and bio-based barrier layers achieve 220°C thermal thresholds without fluorochemical chemistry. Dutch frozen entrée packagers are qualifying these for high-fat applications where grease migration resistance determines retail acceptance.
- Recycled Fiber:Post-consumer pulp lines serve German retail chains with explicit circular economy procurement mandates. EMAS-certified producers gain preferred supplier status in REWE Group and Aldi Nord framework agreements.
- Bleached Paperboard:Virgin fiber substrates provide consistent caliper and printability for branded frozen food applications. Nordic integrated mills control specialty kraft supply for this segment.
- Unbleached Paperboard:Natural fiber aesthetics target organic and clean-label retail positioning. Limited thermal performance restricts these formats to lower-temperature applications.
Coated paperboard captures the technology frontier. Recycled fiber is climbing the fastest as extended producer responsibility thresholds tighten.
End User:
Customer type dictates compliance documentation burdens and carbon footprint audit requirements across procurement frameworks.
- Food Service:Institutional caterers and contract food operators specify oven-direct formats to eliminate transfer steps in hospital and corporate dining environments. German hospital food service operators mandate recyclable certifications as gate criteria.
- Retail:Supermarket private-label programs drive volume concentration through centralized sustainability office specifications rather than decentralized category management. Three-year framework agreements now replace spot-buying patterns.
- Catering:Event and mobile food service distributors prioritize lightweight formats for transport efficiency. Smaller order quantities limit supplier qualification to converters with flexible production scheduling.
- Home Use:Direct-to-consumer channels remain nascent, constrained by shipping damage rates and cold chain requirements for frozen meal delivery.
Food service anchors volume concentration. Retail is expanding most quickly as sustainability procurement centralizes.
Distribution Channel:
Channel structure determines supplier margin capture and inventory risk allocation between converters and distributors.
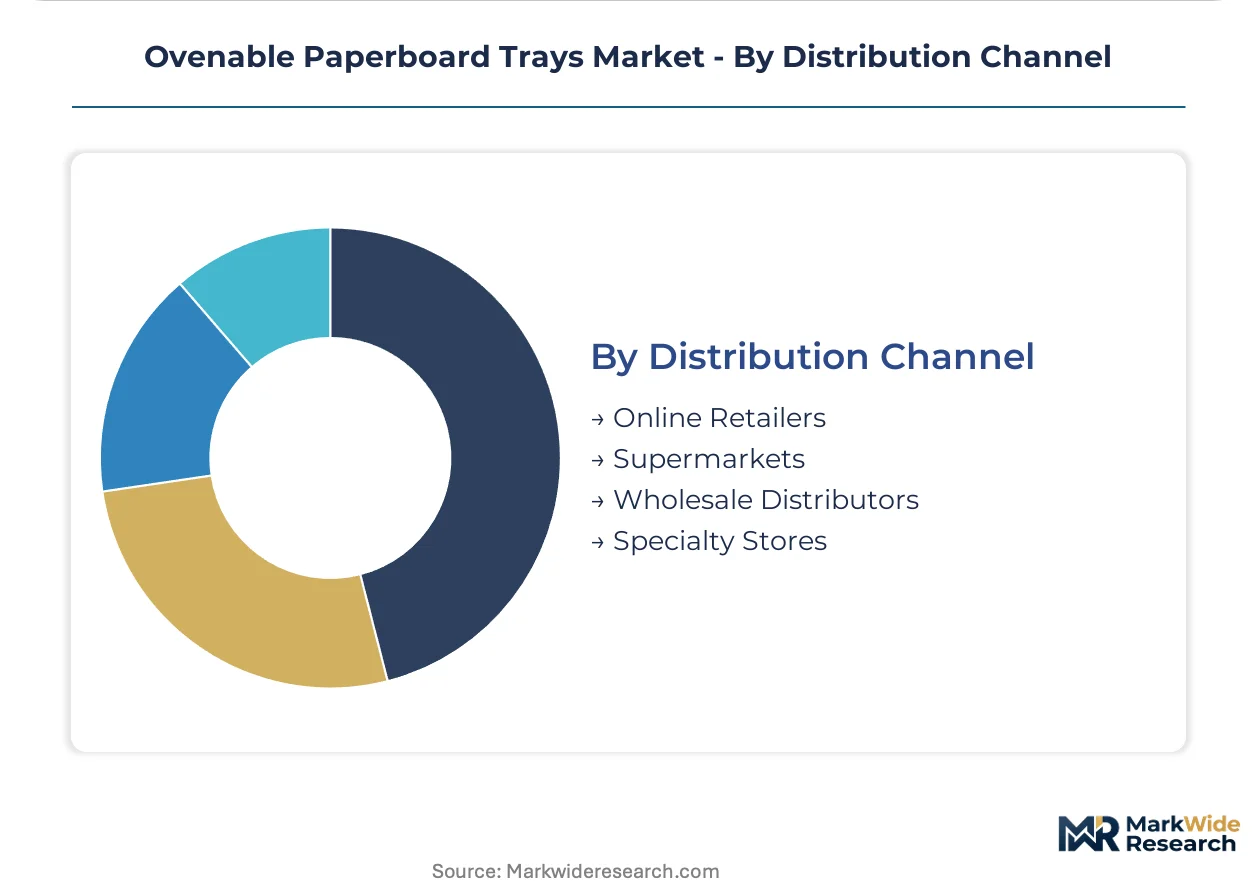
- Supermarkets:German discount and full-service chains consolidate procurement through central buyers who mandate PFAS-free barrier documentation. Store-brand ready meal growth displaces branded alternatives in this channel.
- Wholesale Distributors:Broadline food service distributors aggregate demand from fragmented institutional accounts. Inventory carrying costs favor standardized single-compartment formats with predictable turnover.
- Online Retailers:Frozen meal e-commerce remains limited by last-mile cold chain economics. Specialty frozen food subscriptions in the Netherlands test direct-to-consumer viability.
- Specialty Stores:Organic and gourmet retail channels reward unbleached fiber aesthetics and premium positioning. Lower volumes exclude these accounts from framework agreement structures.
Supermarkets command procurement gravity. Wholesale distributors are gaining share fastest as food service procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites the Netherlands' distribution dominance for frozen food packaging across northwestern Europe. German rail corridors connect Baltic pulp mills to converting facilities in the industrial heartland. This infrastructure geography concentrates ovenable tray demand in specific national markets with distinct regulatory and procurement profiles.
Germany
Hospital food service operators and discount retail chains specify oven-direct recyclable formats for ready-meal programs. The national packaging ordinance enforces extended producer responsibility thresholds that favor fiber-based alternatives. North Rhine-Westphalia hosts converting clusters serving REWE Group and Aldi Nord centralized procurement frameworks.
Netherlands
Frozen entrée packagers in the Randstad region qualify mineral-coated barriers for high-fat applications where grease resistance determines retail acceptance. ECHA guidance on PFAS restrictions accelerates reformulation timelines for Dutch manufacturers. Eindhoven-area coating specialists supply barrier technology to integrated pulp-to-tray producers.
France
Premium chilled meal segments in Île-de-France reward multi-compartment tray geometries with technical price premiums. ANSM food-contact material oversight aligns with EU REACH compliance timelines for fluorochemical-free formulations. Auvergne-Rhône-Alpes hosts dairy and prepared food processors driving specialty format demand.
United States
FDA food-contact substance notifications govern market entry for coated tray formats serving frozen food distributors. Divergent state-level PFAS restrictions create compliance fragmentation that delays national product rollouts. Midwest converting clusters supply private-label programs for retail chains with sustainability procurement mandates.
Finland
Nordic integrated producers control specialty kraft fiber supply for bleached paperboard segments. Baltic mill capacity expansions fragment regional ovenable tray manufacturing. Helsinki-Espoo metropolitan area anchors Huhtamaki Oyj's coated-barrier technology development for European food service channels.
Ovenable Paperboard Trays Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying barrier coatings and specialty substrates. The vendor base concentrates around integrated pulp-to-tray producers with captive fiber supply and independent converters dependent on third-party material sourcing. Three archetypes dominate: Nordic integrated mills with backward fiber control, European converters with coating technology partnerships, and North American scale players serving retail private-label programs. Competitive moves center on fluorochemical-free barrier validation and multi-compartment mold tooling investments.
Among Nordic integrated producers, Stora Enso Oyj and Huhtamaki Oyj exemplify contrasting strategic positions. Stora Enso Oyj occupies the upstream pulp-to-tray archetype with Baltic mill integration. Huhtamaki Oyj represents the coated-barrier technology specialist tier. Smurfit WestRock sits within the scale-driven converter segment serving recycled fiber demand.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Smurfit WestRock |
| Huhtamaki Oyj |
| DS Smith |
| International Paper Co. |
| WestRock Company |
| Mondi Group plc |
| Graphic Packaging International |
| Pactiv LLC |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge corridors transmit pulp fiber cost volatility directly into converter pricing power, compressing margins for independent operators while amplifying volume-discount leverage for integrated Baltic mill networks serving German retail procurement frameworks.
Pricing Analysis
Volume-discount tiering structures dominate procurement between Nordic integrated producers and German discount chains, with three-tier pricing stratification across premium multi-compartment, standard single-cavity, and economy recycled-fiber formats. Price differentiation hinges on PFAS-free certification status and thermal performance thresholds above 200°C. Pricing pressure stems from aluminum tray cost advantages in frozen food segments. Food service distributors exhibit highest price sensitivity, while premium retail channels absorb technical premiums for barrier-coated variants.
Supply Chain Analysis
REACH Annex XVII export-control restrictions on fluorochemical barrier technologies limit coating chemistry flows from Dutch specialists to independent converters, fragmenting supply access. Geographic concentration centers on Finland, Germany, and the Netherlands for specialty kraft and coating development. Raw material dependencies span Nordic pulp fiber, mineral barrier formulations, and PET laminates. Single-source vulnerability runs through Baltic mill capacity for bleached paperboard substrates. Distribution runs through Rotterdam port networks into German rail corridors serving North Rhine-Westphalia converting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against aluminum tray incumbents in high-volume frozen food segments, where metal formats retain microwave-oven dual compatibility that fiber-based alternatives have yet to match.
For Market Incumbents: Build regulatory compliance moats through captive PFAS-free barrier development capabilities that outpace independent converter reformulation timelines. Deepen upstream control over specialty kraft fiber supply from Nordic mills to secure input cost stability. Accelerate multi-compartment mold tooling investments to capture premium positioning in French and Benelux balanced-meal segments before aluminum competitors bridge the thermal performance gap.
For New Entrants and Emerging Players: Mid-scale recycled fiber converters in Eastern Europe represent the most penetrable entry point for private-label retail programs displacing branded alternatives. Austrian institutional catering contracts with framework agreement structures offer lower qualification barriers than German centralized procurement. Target coating technology partnerships with Eindhoven-area specialists rather than in-house R&D investments to compress barrier validation timelines.
For Investors and Strategic Acquirers: Coating technology specialists with FDA food-contact substance notification track records present asymmetric acquisition upside as US market entry becomes contingent on pre-validated barrier platforms. Long-term viability frames around five-to-ten year regulatory compliance windows rather than commodity fiber cyclicality. Monitor ECHA guidance publication timing as the critical inflection signal for PFAS restriction phase-in acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier Validation | REACH compliance timelines compress R&D cycles for fluorochemical-free coatings serving German retail mandates. |
| Multi-Compartment Mold Investment | Custom tooling for segmented geometries captures technical premiums in French premium chilled meal channels. |
| Recycled Fiber Line Expansion | Post-consumer pulp capacity addresses REWE Group and Aldi Nord circular economy procurement frameworks. |
| Coating Technology Partnership | Eindhoven-area barrier specialists accelerate mineral-based formulation deployment for high-fat frozen entrée applications. |
| Framework Agreement Lock-In | Three-year supply commitments with annual carbon audits secure volume concentration against spot-buying competitors. |
Research Methodology
Cross-validation between primary interviews with packaging procurement directors and secondary analysis of ECHA regulatory filings anchors the qualitative findings on PFAS substitution timelines. The research combined discussions with frozen food brand managers, hospital food service operators, coating R&D directors, and sustainability compliance leads at German retail chains. Secondary sources encompassed FDA food-contact substance notification databases, EU packaging ordinance implementation reports, and customs trade data on pulp fiber flows. Bottom-up demand modeling from end-use segments and top-down supply capacity assessments from Nordic mill disclosures were triangulated to validate market sizing.
Calibration against historical adoption curves for fiber-based packaging substitutions informed the projection framework across the analysis window. Segmentation dimensions modeled included product type, barrier chemistry, end-use channel, and regional regulatory cluster. CAGRs were derived from volume-weighted growth rates across frozen entrée and ready-meal application segments. Forecast inputs incorporated ECHA guidance phase-in schedules and German extended producer responsibility threshold escalations as demand drivers.
Practitioners should monitor ECHA enforcement discretion and FDA notification backlog clearance for early signals of regulatory timeline compression. Forecasts reflect assumptions on PFAS restriction implementation pacing and aluminum substitution elasticity in frozen food segments. Material shifts in EU Green Deal packaging waste targets or breakthrough microwave-compatible barrier formulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paperboard Tray Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Paper Carrier Bags Market