

Macerated Paper Padded Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Macerated Paper Padded Mailers Market Insights
Aftermarket service revenue for mailer collection and recycling infrastructure is fragmenting as brands internalize circular logistics. Mondi leverages its European pulp network to secure virgin fiber supply for premium padded grades. Ranpak competes through on-site paper conversion systems that reduce outbound freight from centralized mills. Sealed Air sustains its position via automated packing line integration, embedding mailer dispensers directly into warehouse workflows.
Macerated paper padded mailers consist of shredded or pulped paper fibers compressed into protective cushioning layers, typically bonded with starch-based adhesives and laminated to kraft paper facings between 80-150 gsm. These mailers absorb impact energy during transit while remaining fully curbside recyclable in standard paper streams. Recycled paper content dominates volume production, though kraft paper commands premium positioning in cosmetic and apparel subscription channels. Self-sealing mailers capture the fastest growth trajectory as fulfillment speed becomes critical for same-day dispatch operations. E-commerce packaging anchors overall demand, with logistics providers and subscription box companies collectively absorbing the majority of flat and gusseted formats.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and extended producer responsibility schemes across France, Germany, and Italy. FDA food-contact standards in the United States limit adhesive chemistry choices for mailers handling incidental food shipments. Stakeholders must monitor how California's SB 54 implementation tightens single-use packaging accountability beyond federal baselines, as state-level divergence creates compliance complexity for multi-hub shippers.
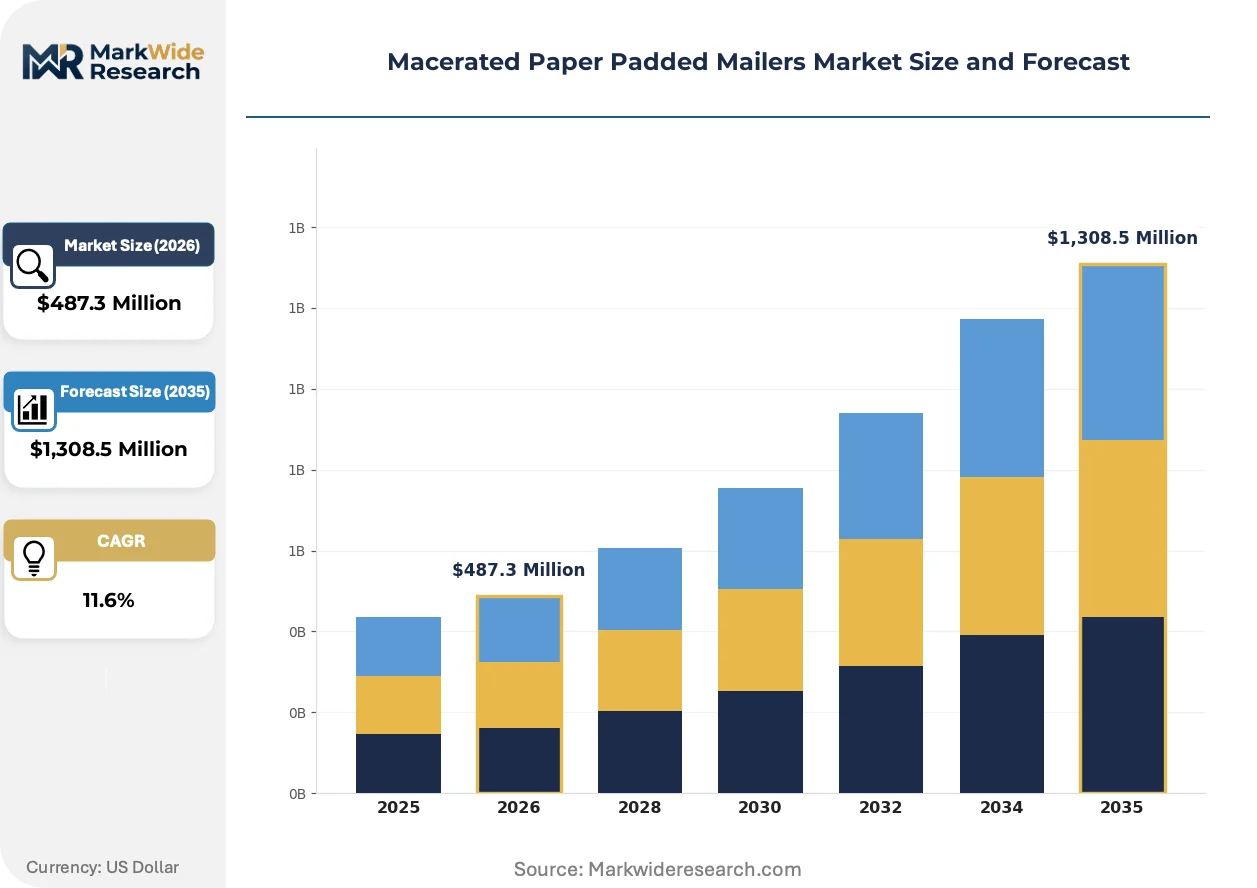
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing plastic mailer availability while e-commerce fulfillment centers accelerate kraft-based alternatives, creating a structural supply pivot toward macerated fiber cushioning systems.
Growth Catalysts
- Extended Producer Responsibility schemes:The EU Packaging and Packaging Waste Regulation mandates that brands finance end-of-life collection, driving substitution away from non-recyclable plastic bubble mailers toward curbside-recyclable paper alternatives.
- Same-day dispatch infrastructure:Automated warehouse systems require self-sealing mailer formats that integrate with high-speed packing lines, compressing handling time per parcel.
- German distribution hub concentration:Amazon and Zalando fulfillment centers in Germany are absorbing bulk volumes of gusseted formats, establishing procurement templates across European logistics networks.
Market Restraints
- Pulp fiber cost volatility:Kraft paper facing grades between 80-150 gsm depend on virgin fiber supply chains vulnerable to European pulp mill capacity constraints and energy input fluctuations.
- Moisture sensitivity limitations:Starch-based adhesive bonding in macerated cushioning layers degrades performance in high-humidity transit corridors, restricting use in certain cross-border shipping lanes.
- Plastic mailer residual cost advantage:Polyethylene bubble mailers retain lower unit economics at volume, delaying conversion in price-sensitive bulk shipping segments.
Strategic Opportunities
- On-site paper conversion systems:Fulfillment operators are deploying localized maceration and forming equipment that eliminates outbound freight from centralized mills, compressing total landed cost.
- Cosmetic and apparel subscription channels:Premium kraft-based grades with printed branding surfaces command positioning in unboxing-experience-driven verticals where curbside recyclability supports brand messaging.
- California SB 54 implementation:State-level single-use packaging accountability tightening creates compliance complexity that favors early standardization on recyclable paper formats for multi-hub shippers.
Industry Challenges
- Automated packing line integration:Mailer dispenser synchronization with existing warehouse management systems requires custom mechanical interfaces and control software adaptation.
- FDA food-contact certification timelines:Adhesive chemistry choices for mailers handling incidental food shipments face extended validation cycles under United States regulatory review.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macerated Paper Padded Mailers Market Trends and Innovations
Material science advances are compressing the performance gap between macerated fiber cushioning and synthetic alternatives while regulatory pressure accelerates format standardization across fulfillment networks.
Dual-layer macerated fiber technology is hybridizing shredded post-consumer content with virgin kraft reinforcement to achieve impact absorption metrics matching plastic bubble protection. Cosmetic subscription box operators in France and Germany are piloting these hybrid grades for premium positioning. The structural consequence is compression of the premium-standard price spread as performance parity removes the protection-quality justification for plastic retention.
REACH chemical compliance requirements in Europe are restricting adhesive chemistries to starch and bio-based binders, eliminating synthetic latex options previously used in fiber bonding. Industrial consequence includes reformulation cycles for mailer manufacturers serving EU fulfillment centers. The apparel subscription segment is responding fastest, switching suppliers to pre-certified kraft-based formats to avoid batch testing delays.
Consolidated procurement by mega-fulfillment operators is displacing fragmented distributor purchasing, with direct mill relationships replacing packaging intermediaries. Third-party logistics providers in the Benelux region are absorbing this model first, negotiating annual volume commitments for flat and gusseted format standardization. German Amazon and Zalando hubs are the visible epicenter of this purchasing concentration.
Macerated Paper Padded Mailers Market Segmentation
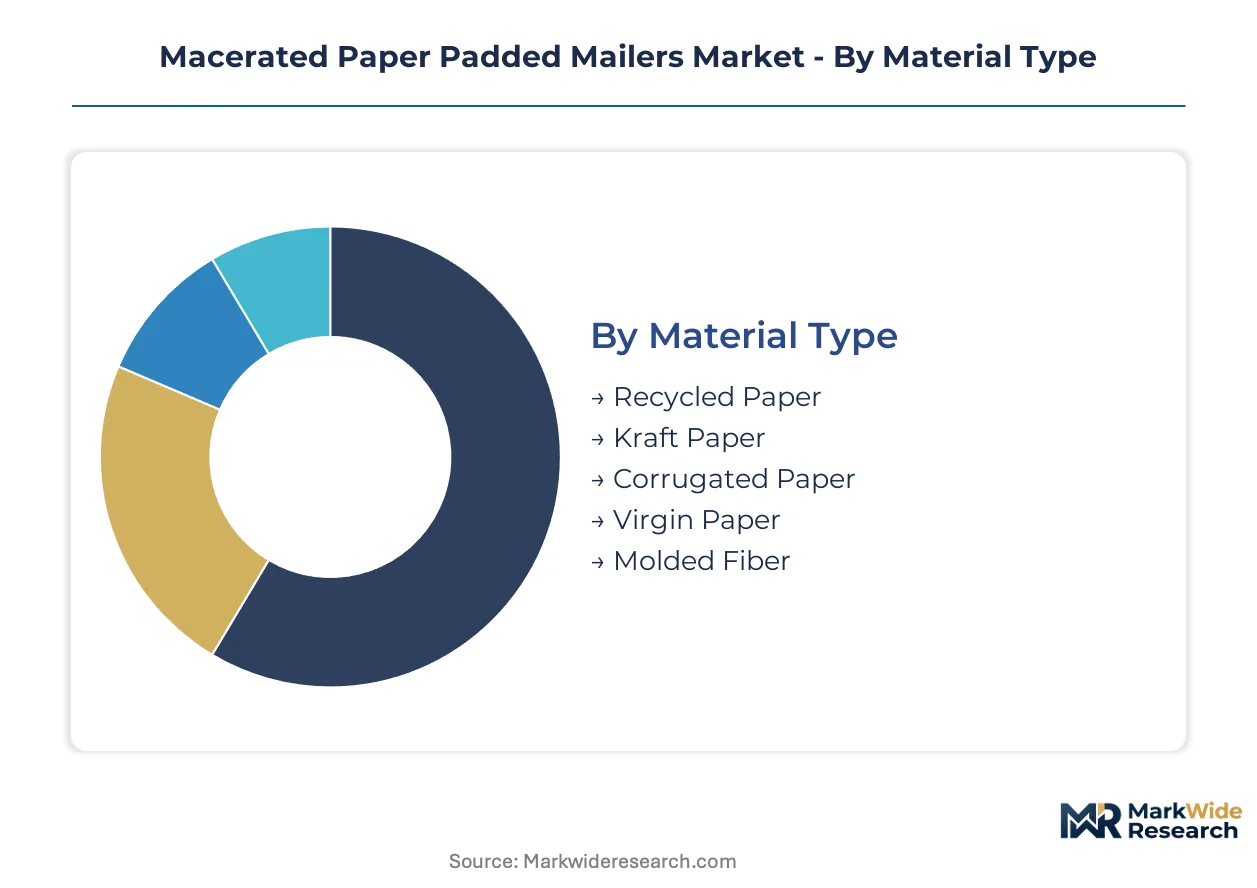
Segmentation in macerated paper padded mailers reveals how material specifications, fulfillment formats, and end-use intensity create distinct service requirements across the value chain. Each dimension carries implications for recyclability certification, automated handling compatibility, and circular logistics infrastructure investment.
Material Type:
After-sales service intensity varies sharply by fiber source, with virgin and kraft grades demanding technical support for certification maintenance while recycled grades require collection network coordination.
- Recycled Paper:Post-consumer fiber content between 80-100% dominates volume production for standard e-commerce fulfillment. Demand concentrates in German Amazon and Zalando distribution hubs where bulk procurement of curbside-recyclable formats satisfies EU Packaging and Packaging Waste Regulation compliance mandates.
- Kraft Paper:Virgin fiber reinforcement between 80-150 gsm provides premium cushioning performance for cosmetic and apparel subscription channels. French and German subscription box operators absorb these grades fastest as unboxing experience and brand messaging around sustainability drive substitution from plastic alternatives.
- Corrugated Paper:Fluted fiber layers bonded to kraft facings deliver rigid protection for heavier product categories.
- Virgin Paper:Unbleached softwood pulp offers consistent fiber length for high-performance cushioning in temperature-sensitive transit.
- Molded Fiber:Wet-pressed pulp forming creates custom-fit protection for irregular product geometries in specialty retail fulfillment.
By volume, Recycled Paper leads. By growth pace, Kraft Paper is ahead.
Application:
Application segmentation tracks how fulfillment speed requirements and product fragility specifications split demand across protective packaging intensity tiers.
- E-commerce Packaging:Automated warehouse systems require self-sealing formats that integrate with high-speed packing lines, compressing handling time per parcel for same-day dispatch operations. Logistics providers in the Benelux region and German mega-fulfillment centers absorb the majority of flat and gusseted formats.
- Product Shipping:Industrial goods distribution demands impact absorption metrics matching plastic bubble protection, with dual-layer macerated fiber technology hybridizing post-consumer content with virgin kraft reinforcement.
- Document Protection:Lightweight flat mailers with minimal cushioning protect paper goods in postal and courier networks.
- Gift Packaging:Printed branding surfaces and premium kraft facings serve unboxing-experience-driven cosmetic and apparel verticals.
- Sample Distribution:Small-format pouch mailers handle pharmaceutical and cosmetic trial-size shipments under FDA food-contact scrutiny.
E-commerce Packaging commands the largest share of tonnage. Product Shipping shows the steepest expansion trajectory as industrial shippers convert from plastic.
End User Industry:
End user segmentation reflects procurement concentration patterns, with fulfillment scale determining whether buyers source through distributor networks or direct mill relationships.
- Logistics Providers:Third-party operators in the Benelux region are absorbing consolidated procurement models first, negotiating annual volume commitments that displace fragmented distributor purchasing and establish format standardization templates.
- Subscription Box Companies:Cosmetic and apparel channels in France and Germany pilot hybrid fiber grades for premium positioning, responding fastest to REACH chemical compliance restrictions by switching to pre-certified kraft-based formats.
- Specialty Retailers:Niche product categories require custom-sized molded fiber protection with lower volume scale.
- Printing Services:Document-centric fulfillment absorbs lightweight flat mailers with minimal cushioning specifications.
- Manufacturing Units:Industrial spare parts and component shipping drives demand for heavy-duty gusseted formats.
Logistics Providers move the most units. Subscription Box Companies are climbing the fastest as unboxing experience investment accelerates format premiumization.
Packing Format:
Packing format segmentation captures the automation compatibility spectrum, from manual-handling open-ended designs to fully integrated self-sealing dispensers.
- Self-sealing Mailers:Adhesive strip integration eliminates tape application, enabling direct embedding into automated packing line workflows. Warehouse management system synchronization requirements create implementation complexity that favors early standardization by multi-hub shippers.
- Gusseted Mailers:Expandable side panels accommodate bulkier items in apparel and soft goods fulfillment, with German Amazon and Zalando hubs establishing procurement templates that propagate across European logistics networks.
- Flat Mailers:Minimal profile suits document protection and lightweight product categories with standard postal handling.
- Pouch Mailers:Compact formats handle sample distribution and small-item e-commerce with reduced material intensity.
- Open-ended Mailers:Manual closure requirements restrict use to low-volume specialty applications and gift packaging.
Flat Mailers dominate current volume. Self-sealing Mailers are gaining share fastest as same-day dispatch infrastructure spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fulfillment centers consume bulk gusseted formats for automated warehouse integration, while French cosmetic subscription channels absorb premium kraft grades for unboxing experience differentiation. This consumption-mix split between logistics infrastructure and brand-centric verticals shapes procurement patterns across European markets.
Germany
Amazon and Zalando distribution hubs in Saxony and North Rhine-Westphalia drive bulk procurement of self-sealing mailers for same-day dispatch operations. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility financing that accelerates plastic substitution. Berlin-Brandenburg logistics clusters are standardizing gusseted format specifications that propagate across continental European networks.
France
Cosmetic subscription box operators in Île-de-France pilot dual-layer hybrid fiber grades for premium unboxing positioning. REACH chemical compliance restrictions from ECHA eliminate synthetic latex adhesive options, forcing rapid supplier switches. Lyon-based apparel fulfillment centers are absorbing pre-certified kraft formats to avoid batch testing delays under tightened chemical scrutiny.
United States
E-commerce fulfillment operators in California and Texas face divergent state-level packaging accountability standards under SB 54 implementation. FDA food-contact certification timelines limit adhesive chemistry choices for mailers handling incidental food shipments. Pacific Northwest distribution hubs are standardizing on curbside-recyclable formats to preempt multi-state compliance complexity.
Netherlands
Third-party logistics providers in the Randstad region negotiate direct mill relationships that displace fragmented distributor purchasing. The EU Green Deal circular economy targets drive investment in collection infrastructure for post-consumer fiber recovery. Eindhoven-area automated warehouses are embedding mailer dispensers into high-speed packing lines for parcel handling compression.
United Kingdom
London-Southeast logistics corridors absorb flat mailer volumes for document protection and lightweight product categories. Post-Brexit regulatory divergence from EU packaging standards creates certification complexity for cross-border shippers. Midlands distribution hubs are consolidating procurement around gusseted formats compatible with both domestic and continental European handling systems.
Macerated Paper Padded Mailers Market Competitive Landscape
Capability concentration sits with integrated pulp-to-mailer operators; scale advantage sits with diversified packaging conglomerates. The market structures around three tiers: European forest products majors with captive fiber supply, North American specialty packaging firms with automated equipment integration, and regional converters with flexible short-run capacity. Strategic moves center on backward integration into pulp networks and forward integration into on-site conversion systems at customer fulfillment centers.
Within the integrated forest products tier, Mondi and Stora Enso represent operators with European pulp network control. Among specialty packaging specialists, Sealed Air occupies a position exemplifying automated packing line integration capabilities. Ranpak sits within the on-site conversion archetype, deploying localized forming equipment that eliminates outbound freight from centralized mills. These three anchors illustrate how competitive positioning splits between fiber supply security, equipment integration depth, and logistics cost compression.
| Leading Market Players |
|---|
| Mondi |
| Ranpak |
| Sealed Air |
| Pregis |
| Smurfit Westrock |
| Stora Enso |
| International Paper |
| ProAmpac |
| Uline |
| Others |
Pricing and Supply Chain Analysis
Saxony and North Rhine-Westphalia pulp mill clusters anchor European fiber supply for kraft facing grades, with capacity utilization swings transmitting directly into mailer producer margin structures and downstream contract renegotiation leverage.
Pricing Analysis
Long-term offtake agreements dominate procurement between German Amazon and Zalando fulfillment centers and integrated pulp-to-mailer operators, compressing spot market exposure. Price differentiation rests on virgin fiber certification grade and volume scale tiers, with premium kraft grades commanding positioning in cosmetic subscription channels. Cost compression in standard recycled grades is intensifying because pulp fiber input volatility and energy cost pass-through clauses are tightening. Bulk logistics providers show highest price sensitivity, while cosmetic and apparel subscription operators absorb premium positioning with limited elasticity.
Supply Chain Analysis
REACH chemical compliance restrictions from ECHA limit adhesive chemistry flows into EU fulfillment networks, forcing reformulation cycles and supplier qualification delays. Geographic supply concentration centers on Germany, France, and the Netherlands for kraft pulp and mailer conversion capacity. Raw material dependencies draw from Nordic softwood pulp, starch-based bio-binders, and post-consumer fiber recovery streams. Single-source vulnerability sits with European pulp mill capacity constraints amid energy input fluctuations. Distribution runs through direct mill relationships displacing fragmented distributor networks, with consolidated procurement by mega-fulfillment operators compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fulfillment-scale automated packing line integration represents the scarcest deployable capability, separating operators who embed mailer dispensers into warehouse workflows from commodity converters locked into manual-handling formats.
For Market Incumbents: Harden fiber supply security through backward integration into Nordic pulp networks or captive long-term offtake agreements, as European mill capacity constraints threaten input cost stability. Deepen automated dispenser integration with warehouse management systems to lock in multi-year fulfillment operator contracts before standardization templates solidify. For New Entrants and Emerging Players: Mid-tier logistics providers in the Benelux region and French apparel subscription channels represent the most penetrable entry points, as these segments lack direct mill relationships and face REACH compliance qualification backlogs. A go-to-market angle centered on pre-certified adhesive formulations and rapid batch testing turnaround compresses supplier switching timelines. For Investors and Strategic Acquirers: Long-term, this sits as a circular logistics infrastructure play because extended producer responsibility financing mandates will internalize collection and recycling economics into mailer producer balance sheets. Acquisition target archetype: regional converters with flexible short-run capacity and established post-consumer fiber collection partnerships. The signal to watch is California SB 54 implementation tightening, which would accelerate multi-hub shipper standardization on curbside-recyclable formats and reward early compliance positioning.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Conversion System Deployment | Ranpak's localized forming equipment model eliminates outbound freight from centralized mills for fulfillment operators. |
| Automated Packing Line Integration | Sealed Air's dispenser embedding into warehouse management systems compresses handling time per parcel for same-day dispatch. |
| Dual-Layer Hybrid Fiber Development | Mondi's post-consumer and virgin kraft reinforcement achieves impact absorption parity with plastic bubble protection. |
| REACH Pre-Certification Investment | Early adhesive chemistry validation avoids batch testing delays under ECHA tightened scrutiny. |
| Direct Mill Relationship Consolidation | Third-party logistics providers in the Randstad region displace fragmented distributor purchasing through annual volume commitments. |
Research Methodology
Operator-level perspectives from fulfillment center operations directors, packaging procurement managers at e-commerce platforms, pulp mill supply planners, and automated warehouse systems integrators anchored the qualitative base. These primary inputs combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation tracking, ECHA REACH compliance databases, customs trade flow records for kraft paper grades, and SEC filings from diversified packaging conglomerates. Bottom-up volume modeling across material type and packing format segments triangulated against top-down European e-commerce fulfillment infrastructure spend analysis.
Scenario-bracketing around EU regulatory enforcement intensity and pulp fiber cost volatility framed the analytical approach across the analysis window. Segmentation dimensions modeled include material type, packing format, application intensity tier, and end-user procurement scale. CAGRs derived from logistic curve adoption modeling for automated packing line integration, cross-referenced with fulfillment operator capital expenditure disclosure patterns and substitution elasticity estimates for plastic mailer displacement.
Practitioners should monitor EU Packaging and Packaging Waste Regulation enforcement calibration and Nordic pulp mill energy cost pass-through mechanisms for early signals of margin compression or supply rationing. Forecasts reflect assumptions around REACH chemical compliance timeline stability and German distribution hub procurement template propagation speed. Material shifts in California SB 54 implementation scope or European pulp capacity rationalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.