
 Subsea Well Intervention Market | 2026-2036
Subsea Well Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
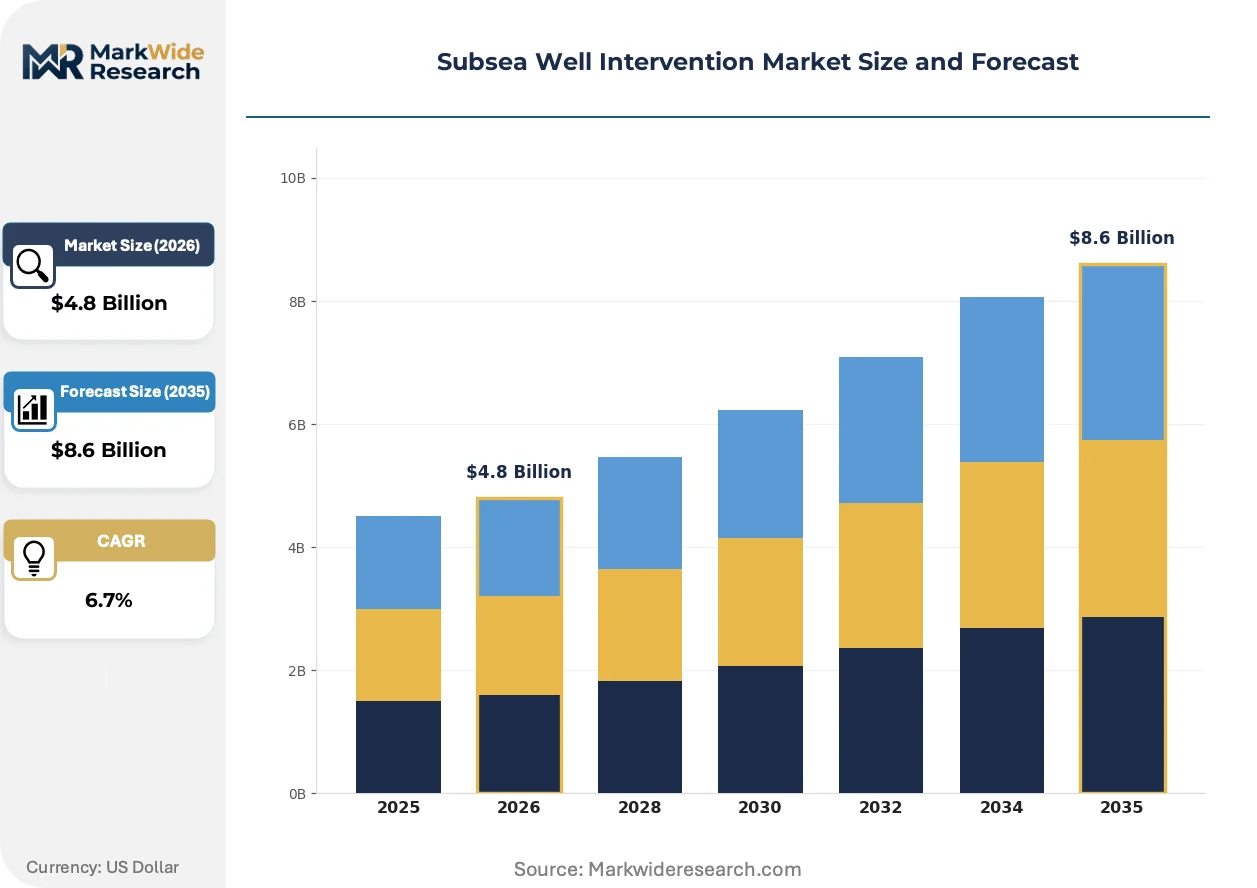
Subsea Well Intervention Market Outlook
Gulf of Mexico subsea contractor capacity is hardening as drillship and vessel availability tightens for deepwater intervention campaigns. Schlumberger Limited leverages integrated wireline and coiled tubing portfolios to capture bundled service contracts across the region. Baker Hughes Company sustains technology leadership in subsea pressure control systems for high-pressure high-temperature wells. Aker Solutions anchors Nordic market presence through specialized riserless light well intervention vessels.
Subsea well intervention encompasses techniques and equipment used to access, maintain, and restore production from subsea wells without removing the subsea tree or drilling riser, typically operating at water depths exceeding 1,000 meters with pressure ratings above 10,000 psi to perform diagnostics, stimulation, or recompletion. Wireline services dominate routine logging and perforation work, while coiled tubing commands premium margins in live-well intervention where wellbore dynamics demand continuous circulation. Remote operated vehicles represent the fastest-growing technology segment as operators eliminate diver exposure in deeper, more hostile environments.
BSEE in the US Gulf of Mexico mandates subsea containment capabilities and well control equipment certification, while Norway's PSA enforces barrier management and facility integrity standards that directly shape intervention scope and frequency. Brazil's ANP local content requirements constrain foreign vessel deployment, redirecting procurement toward domestically registered service contractors. Stakeholders must monitor regulatory divergence across producing basins when configuring intervention asset fleets and compliance protocols.
Market Dynamics
Maturing subsea fields in the North Sea and US Gulf of Mexico are forcing operators to prioritize intervention over greenfield development, compressing payback timelines for specialized vessel and equipment investments.
Growth Catalysts
- Plug-and-abandonment obligations:Norway's PSA mandates accelerated decommissioning schedules for aging subsea infrastructure, expanding service procurement for riserless light well intervention systems.
- BSEE well control certification:The US regulator's subsea containment requirements tighten equipment standards, extending replacement cycles and aftermarket service demand for blowout preventers.
- Wireline logging advances:High-pressure rated logging tools now access reservoirs previously unreachable without full workover rigs, opening subsea intervention to marginal field economics.
Market Restraints
- Specialized vessel scarcity:Purpose-built monohull intervention vessels concentrate ownership among Nordic and Singapore-based fleet operators, creating capacity bottlenecks during seasonal demand surges.
- High-grade alloy input costs:Chromium-molybdenum steel price volatility directly pressures pressure control system margins, with limited substitution options for 15,000 psi-rated components.
- Brazil ANP local content thresholds:Foreign-flagged intervention vessels face deployment restrictions unless partnered with domestically registered contractors, fragmenting procurement options.
Strategic Opportunities
- Remote operated vehicle convergence:Integration of autonomous inspection drones with intervention vessels is automating seabed survey work, reducing pre-intervention site assessment timelines by half.
- West Africa underpenetration:Nigeria and Angola hold substantial subsea well counts with minimal intervention history, presenting first-mover advantages for established North Sea contractors.
- Digital twin adoption:Real-time wellbore simulation platforms enable predictive intervention scheduling, converting reactive maintenance into planned campaigns with higher equipment utilization.
Industry Challenges
- Subsea systems engineering talent gap:Experienced intervention supervisors with dual competency in coiled tubing operations and dynamic positioning command premium compensation, constraining crew scalability.
- API 17D certification timelines:Extended third-party validation periods for subsea intervention pressure control equipment delay new product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Well Intervention Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wireline Services, Coiled Tubing, Pumping Services, Subsea Tree Installation End User: Oil & Gas Companies, Offshore Operators, Engineering Firms, Service Providers Technology: Remote Operated Vehicles, Divers, Acoustic Tools, Intervention Systems Application: Maintenance, Repair, Upgrades, Decommissioning |
| Companies Covered | Weatherford International, Oceaneering International, Schlumberger Limited, Expro Group, TechnipFMC, Halliburton Company, Aker Solutions, Helix Energy Solutions, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Well Intervention Market Strategic Shifts
Digitalization and remote operations are compressing the traditional intervention value chain, eliminating diver exposure while extending operational reach into deeper, higher-pressure reservoirs previously deemed inaccessible.
Artificial intelligence-driven predictive maintenance platforms are automating equipment health monitoring across subsea intervention fleets. Major North Sea operators now mandate AI-enabled condition monitoring for all chartered vessels. The technology is automating failure-mode detection weeks before critical component degradation, shifting maintenance from calendar-based to condition-triggered protocols.
Norway's PSA barrier management regulations now require real-time verification of all well barriers during live-well interventions, not merely pre-job certification. This industrial consequence demands continuous pressure monitoring and automated shutdown triggers integrated into intervention control systems. Deepwater Gulf of Mexico operators are adopting identical protocols voluntarily to preempt BSEE rulemaking.
Integrated service contracting is displacing discrete vessel and equipment procurement as the dominant commercial model. National oil companies in Brazil and West Africa now bundle wireline, coiled tubing, and remote vehicle services under single-source agreements with penalty clauses for non-productive time. This consolidation is most visible in Petrobras's pre-salt development contracts, where integrated providers assume full well intervention risk.
Subsea Well Intervention Market Segmentation
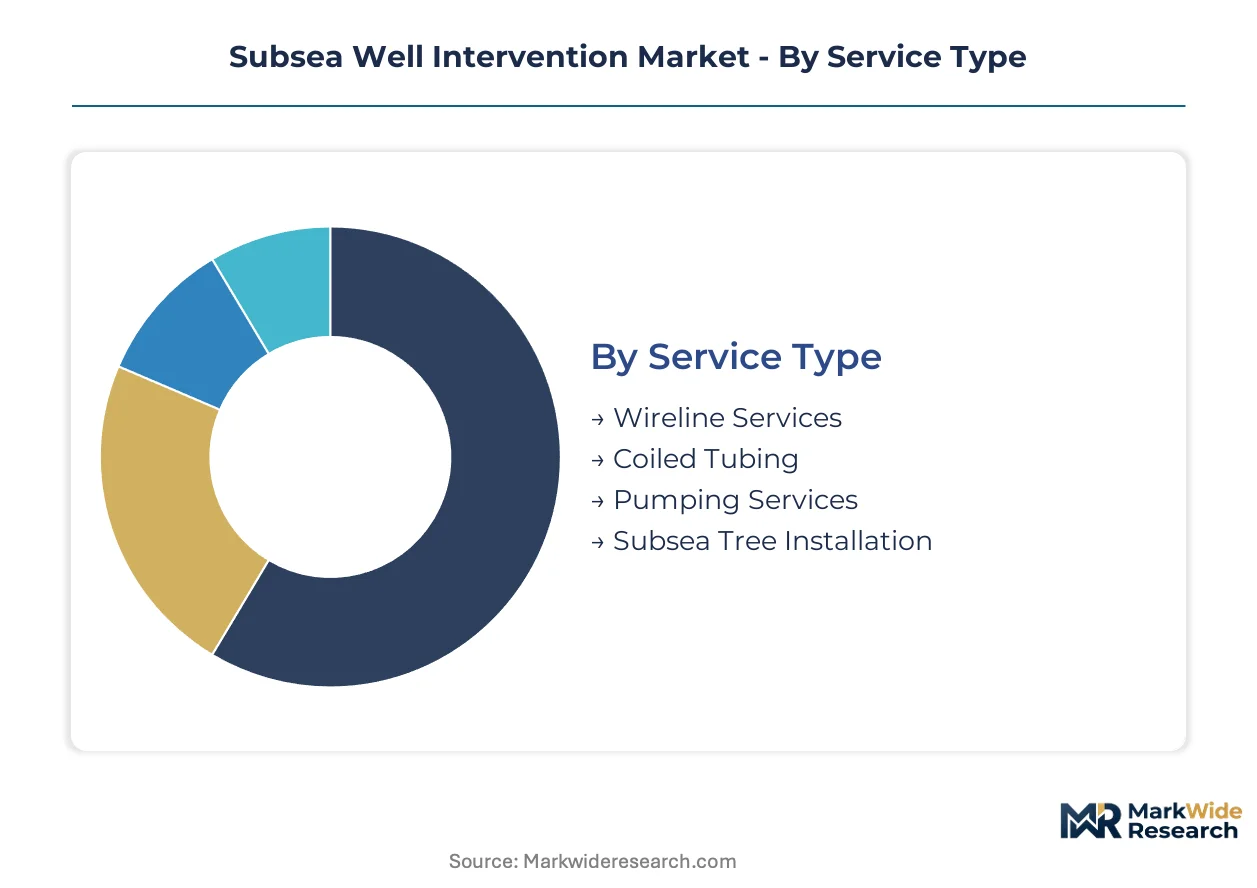
Service configuration in subsea well intervention follows a clear volume-versus-premium logic. Routine logging and perforation work generates high transaction counts at compressed margins, while live-well interventions with continuous circulation command substantial price premiums due to operational complexity and equipment intensity.
Service Type:
Wireline services anchor volume throughput across intervention fleets, yet coiled tubing captures disproportionate value through technical differentiation.
- Wireline Services:Electric cable-conveyed tools perform logging, perforating, and mechanical intervention in shut-in or live wells at pressures exceeding 10,000 psi. North Sea operators deploy these services for routine diagnostics on aging subsea trees, with demand intensifying around statutory decommissioning timelines.
- Coiled Tubing:Continuous steel tubing enables live-well intervention with uninterrupted circulation, essential for wellbore stability in high-pressure formations. Deepwater Gulf of Mexico campaigns favor this method for stimulation and sand control, where non-productive time penalties justify premium day rates.
- Pumping Services:Cementing, acidizing, and nitrogen pumping operations support zonal isolation and formation treatment.
- Subsea Tree Installation:Full tree replacement and retrofit work addresses integrity failures or production optimization requirements.
Today's leader: Wireline Services. Tomorrow's challenger: Coiled Tubing.
End User:
Contracting authority concentrates with asset owners holding balance-sheet responsibility for well integrity compliance.
- Oil & Gas Companies:Integrated majors and national oil companies directly charter intervention vessels and assume regulatory liability for barrier verification. Brazil's Petrobras bundles services under integrated contracts with full risk transfer to providers.
- Offshore Operators:Independent producers and field-specific joint venture partners procure discrete intervention campaigns without long-term fleet commitments. These entities concentrate procurement in the North Sea and US Gulf of Mexico around plug-and-abandonment obligations.
- Engineering Firms:Design contractors specify intervention system requirements during front-end engineering for new developments.
- Service Providers:Tier-2 and specialized contractors subcontract vessel and equipment capacity from fleet owners.
Contracting power pools with Oil & Gas Companies. Procurement flexibility favors Offshore Operators.
Technology:
Human exposure elimination drives capital allocation toward unmanned systems capable of operating at extreme depth and pressure.
- Remote Operated Vehicles:Tethered subsea robots perform inspection, intervention, and construction tasks without diver deployment. Norwegian operators now mandate ROV-based barrier verification during live-well interventions to satisfy PSA real-time monitoring requirements.
- Divers:Saturation diving remains necessary for complex mechanical intervention in shallower water depths where ROV dexterity proves insufficient.
- Acoustic Tools:Non-invasive diagnostic systems assess wellbore and flowline integrity through seabed-deployed sensors.
- Intervention Systems:Riserless light well intervention packages enable subsea tree access without drilling riser installation.
ROV platforms are expanding most quickly. Diver-based methods face regulatory headwinds.
Application:
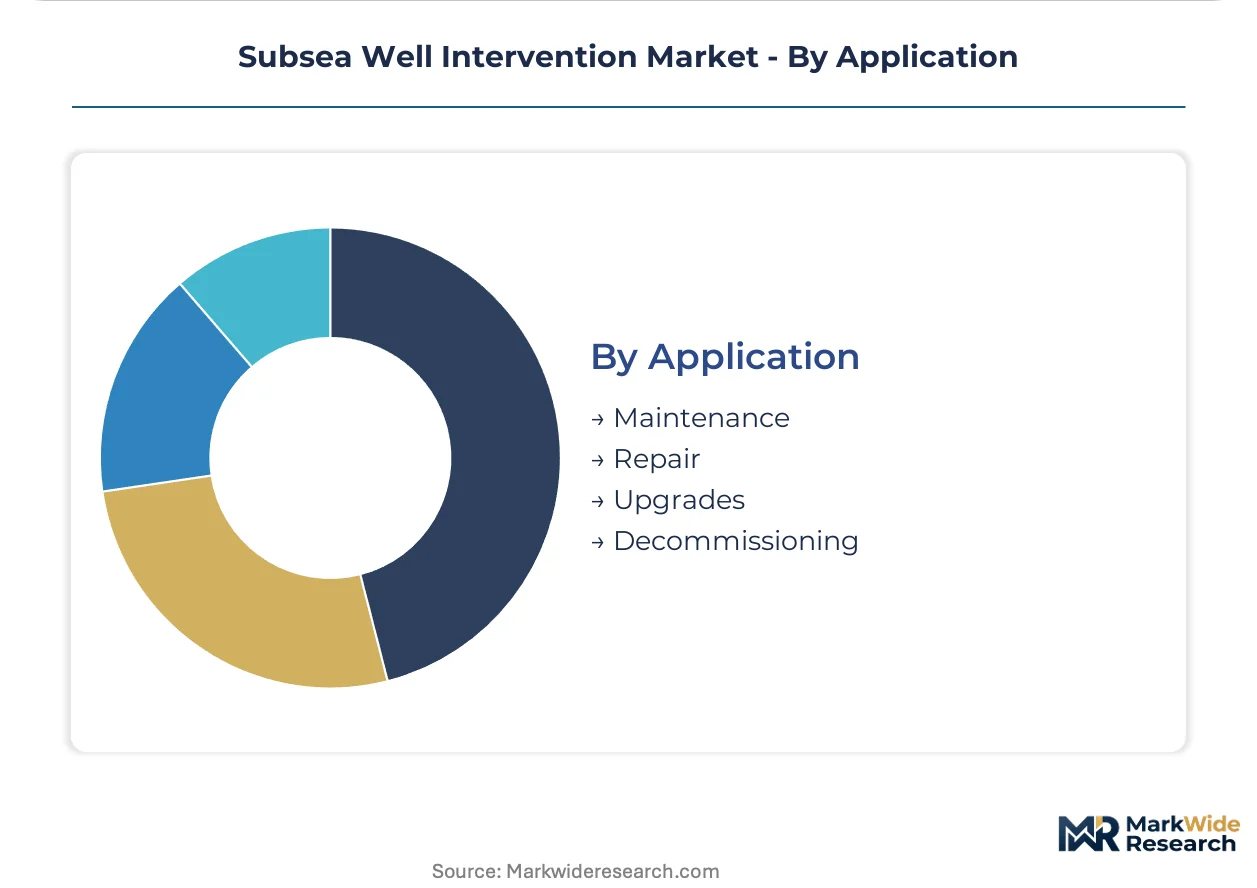
Field lifecycle position determines intervention scope, with late-life assets generating structurally different service demand than producing fields.
- Maintenance:Scheduled diagnostics and barrier testing sustain production from mature subsea wells. Norway's PSA mandates accelerated maintenance cycles for infrastructure exceeding design life, directly expanding service procurement.
- Repair:Unplanned intervention addresses integrity failures, sand production, or corrosion damage requiring immediate remediation.
- Upgrades:Subsea tree retrofit and artificial lift installation enhance recovery from marginal reservoirs.
- Decommissioning:Plug-and-abandonment campaigns permanently seal wells and remove subsea infrastructure. UK and Norwegian regulatory deadlines compress execution timelines for this application.
Maintenance commands current spend. Decommissioning offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands the highest intervention intensity per producing well, while Brazil's pre-salt development drives the steepest fleet expansion. Basin maturity and regulatory pressure create divergent procurement patterns across deepwater provinces.
Norway
Plug-and-abandonment obligations and aging subsea infrastructure dominate service demand. The PSA enforces accelerated decommissioning schedules and real-time barrier verification during live-well interventions. Stavanger anchors the Nordic contractor cluster, where riserless light well intervention vessels concentrate around North Sea marginal field campaigns.
United States
Deepwater Gulf of Mexico tightens vessel availability as drillship deployment competes for intervention assets. BSEE mandates subsea containment capabilities and well control equipment certification for all chartered units. Houston hosts the primary contractor coordination hub, with service procurement intensifying around high-pressure high-temperature well campaigns.
Brazil
Pre-salt field development sustains demand for integrated intervention packages with full risk transfer to providers. ANP local content thresholds redirect procurement toward domestically registered contractors, constraining foreign-flagged vessel deployment. Rio de Janeiro concentrates Petrobras contracting authority and specialized vessel registration.
United Kingdom
Statutory decommissioning deadlines compress execution timelines for plug-and-abandonment campaigns across mature North Sea assets. The North Sea Transition Authority enforces well integrity standards that accelerate maintenance cycles for infrastructure exceeding design life. Aberdeen maintains its position as the primary service procurement center for UK continental shelf operations.
Subsea Well Intervention Market Competitive Environment
Nordic producers anchor one tier of specialized vessel and riserless intervention systems; US Gulf specialists hold integrated wireline and coiled tubing portfolios. Market structure concentrates around three strategic archetypes: integrated oilfield service conglomerates with bundled contracting capabilities, pure-play subsea contractors with purpose-built vessel fleets, and engineering-heavy specialists in pressure control systems. Dominant competitive moves include vertical integration into vessel ownership and strategic partnerships to satisfy Brazil's local content requirements.
Among US-based integrated service providers, Schlumberger Limited and Baker Hughes Company exemplify the bundled contracting archetype, while Aker Solutions anchors the Nordic engineering-specialist position. These entities occupy differentiated competitive terrain: the integrated providers assume full well intervention risk under Petrobras-style single-source agreements, while the Nordic specialist concentrates riserless light well intervention vessel deployment around North Sea decommissioning obligations.
| Leading Market Players |
|---|
| Weatherford International |
| Oceaneering International |
| Schlumberger Limited |
| Expro Group |
| TechnipFMC |
| Halliburton Company |
| Aker Solutions |
| Helix Energy Solutions |
| Baker Hughes Company |
| Others |
Value Chain & Pricing Dynamics
Chromium-molybdenum steel price volatility cascades through pressure control system manufacturing, compressing margins at the 15,000 psi component tier while forcing buyers toward longer-term vessel charter contracts to lock in day-rate stability.
Pricing Analysis
Direct-to-operator contracting discounts dominate the commercial structure, with national oil companies capturing 15-20% day-rate reductions through bundled wireline-coiled tubing-ROV packages. Price differentiation hinges on BSEE well control certification tier and dynamic positioning vessel class, with DP-3 rated units commanding substantial premiums over DP-2 alternatives. Cost compression in standard wireline logging is intensifying as Nordic fleet operators add capacity, while live-well intervention with continuous circulation maintains pricing power due to equipment scarcity. Independent North Sea operators exhibit highest price sensitivity around plug-and-abandonment campaigns, whereas Petrobras-style integrated contracts show lowest sensitivity due to full risk-transfer structures.
Supply Chain Analysis
High-grade alloy feedstock rests on Norwegian specialty steel producers, South Korean heavy forging houses, and Japanese precision component manufacturers for subsea pressure control systems. Critical inputs include chromium-molybdenum billet, high-pressure seals rated beyond 10,000 psi, and dynamic positioning thruster assemblies. Single-source vulnerability concentrates in 15,000 psi blowout preventer forging capacity, where two Nordic facilities control global output. Distribution runs through Stavanger and Houston contractor coordination hubs, with vessel mobilization logistics determining effective regional supply boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as decommissioning obligations and real-time barrier verification requirements shift procurement toward certified, integrated service providers with proven track records in high-pressure environments.
For Market Incumbents: Deploy backward integration into specialized monohull vessel ownership to secure capacity access against emerging pure-play fleet operators. Consolidate pressure control engineering talent through targeted acquisition of Nordic specialist firms. Certification investment in API 17D and BSEE dual-tier approval creates switching costs that defend position against integrated oilfield service conglomerates expanding from wireline bases.
For New Entrants and Emerging Players: The premium-to-economy day-rate gap in West Africa offers entry space for ROV-led intervention packages without full coiled tubing capability. Target Nigeria and Angola marginal field campaigns where established North Sea contractors lack local registration. Partner with domestically registered vessel operators to satisfy ANP content thresholds without capital-heavy fleet ownership.
For Investors and Strategic Acquirers: Consolidation pressure builds where API 17D certification timelines stretch 18-24 months and engineering talent scarcity constrains crew scalability. Mid-cycle viability favors engineering-heavy specialists with captive pressure control technology over vessel-dependent pure-plays. Watch BSEE rulemaking on autonomous barrier verification as signal for ROV-convergence investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Ownership Integration | Captive monohull capacity secures day-rate stability against seasonal Nordic fleet bottlenecks. |
| API 17D Certification Investment | Accelerated approval timelines compress commercialization delays for high-pressure BOP systems. |
| West Africa Market Entry | First-mover positioning in Nigeria and Angola leverages underpenetrated subsea well counts. |
| AI-Enabled Condition Monitoring | Predictive maintenance platforms satisfy North Sea operator mandates for chartered vessel compliance. |
| Brazil Local Content Partnership | Domestic contractor alliances circumvent ANP vessel deployment restrictions for pre-salt campaigns. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with subsea intervention supervisors, offshore operator procurement leads, BSEE regulatory affairs specialists, and riserless vessel fleet managers with secondary validation through BSEE well control incident databases, Norwegian PSA barrier management audit reports, ANP local content compliance filings, and offshore vessel charter rate indices. Bottom-up service demand modeling and top-down basin-level expenditure triangulation anchored market size estimates.
Historical reference periods spanning pre-pandemic baseline, demand compression, and recovery phases informed projection anchor points across the analysis window. Segmentation dimensions modeled include service type, water depth tier, pressure rating class, and regulatory jurisdiction cluster. CAGRs derived from equipment replacement cycle analysis, decommissioning obligation schedules, and vessel fleet expansion plans. Forecast inputs incorporated PSA-mandated barrier verification frequency and BSEE containment capability requirements.
Caveats apply where chromium-molybdenum price spikes, extended API 17D validation delays, or abrupt regulatory divergence across the US Gulf, Norway, and Brazil could materially shift the outlook. A small set of named triggers—BSEE autonomous intervention rulemaking, PSA real-time monitoring enforcement intensity, and ANP local content threshold adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Drill Collar Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Well Test Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market