
 Flow Back Equipment Market | 2026-2036
Flow Back Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Back Equipment Market Analytics
Market Context
Petroleum engineering labor shortages across North American shale basins is bifurcating the competitive landscape between automated system providers and conventional equipment rental houses. Schlumberger Limited leverages digital twin integration across its flowback portfolio to reduce onsite crew requirements. Halliburton anchors its position through backward integration into proprietary valve and choke manufacturing. Baker Hughes Company differentiates via predictive maintenance algorithms embedded in pressure control skids.
Technical Definition and Segment Structure
Flow back equipment encompasses the surface-mounted separation, pressure regulation, and measurement systems used to control hydrocarbon and proppant returns during initial well production, typically handling pressures from 5,000 to 15,000 psi and multiphase fluid streams containing sand, formation fines, and chemical additives. The primary purpose centers on safe hydrocarbon recovery while protecting downstream infrastructure from erosion and plugging. Separators occupy the largest product category as operators extend well cleanup periods to optimize choke management and minimize sand production damage. Digital Technology represents the fastest-expanding segment, with remote monitoring and autonomous choke control commanding premium pricing against mechanical equivalents. Onshore Operations dominate application demand, though offshore specifications command substantially higher margin pools due to corrosion-resistant metallurgy and compact skid requirements.
Regulatory Environment
EPA New Source Performance Standards for methane and volatile organic compounds mandate closed-vent systems and flare minimization, directly expanding demand for vapor recovery units and enclosed separator designs. OSHA Process Safety Management requirements and DOT pipeline safety rules govern pressure equipment certification and worker exposure limits, elevating compliance costs for rental fleet operators. State regulators in Texas and Colorado impose additional venting and flaring restrictions that accelerate equipment replacement cycles. Stakeholders must monitor evolving federal methane fees and state-level emission intensity benchmarks that threaten to obsolete open-top tank configurations before the end of the forecast window.
Market Dynamics
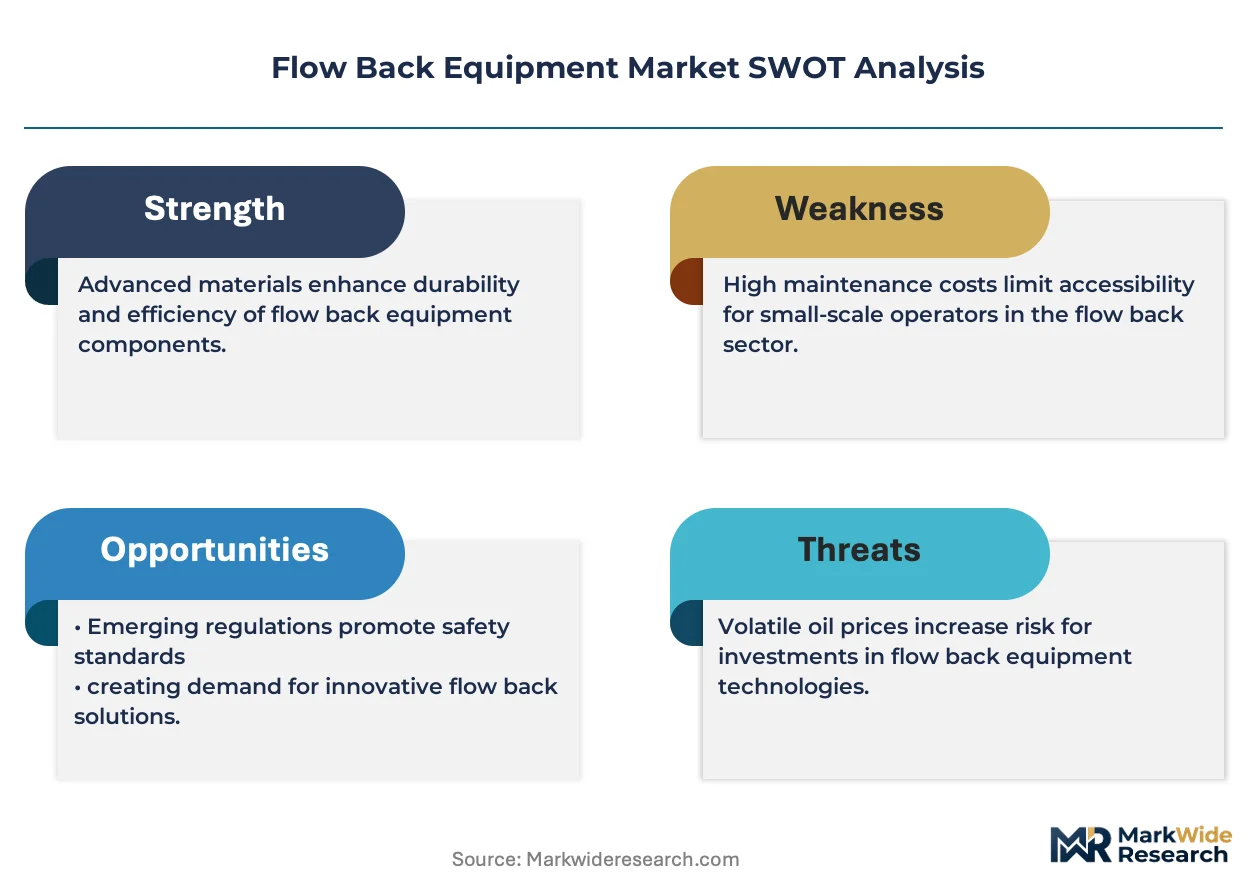
EPA methane emissions rules and state-level flaring restrictions in Texas and North Dakota are forcing rapid equipment replacement cycles, while pad drilling density in the Permian Basin strains conventional separation infrastructure beyond design capacity.
Growth Catalysts
- Hydraulic fracturing intensity:Longer laterals and higher proppant loads in unconventional shale formations multiply flowback complexity, requiring advanced separation and sand management systems.
- Closed-loop mandates:EPA New Source Performance Standards for methane and volatile organic compounds mandate enclosed separator designs and vapor recovery integration.
- Permian Basin concentration:Pad drilling density and produced water volumes in West Texas and southeastern New Mexico exceed legacy infrastructure capacity.
Market Restraints
- Specialized metallurgy costs:Corrosion-resistant alloys for sour service applications command 40-60% price premiums over standard carbon steel.
- Rental fleet obsolescence:Open-top tank configurations face premature retirement under evolving federal methane fees and state emission intensity benchmarks.
- Skilled technician scarcity:Petroleum engineering labor shortages across North American shale basins constrain deployment velocity for complex automated systems.
Strategic Opportunities
- Predictive maintenance convergence:Machine learning algorithms embedded in pressure control skids enable condition-based servicing and reduce unplanned downtime.
- Digital twin integration:Virtual commissioning and remote monitoring capabilities reduce onsite crew requirements and accelerate well cleanup optimization.
- Colorado regulatory tailwind:State-level venting restrictions and emission intensity benchmarks create first-mover advantage for enclosed separator providers.
Industry Challenges
- Automation integration complexity:Autonomous choke control systems require retrofitting legacy mechanical infrastructure with sensor networks and edge computing hardware.
- OSHA Process Safety Management compliance:Pressure equipment certification and worker exposure documentation elevate administrative burden for rental fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Back Equipment Market |
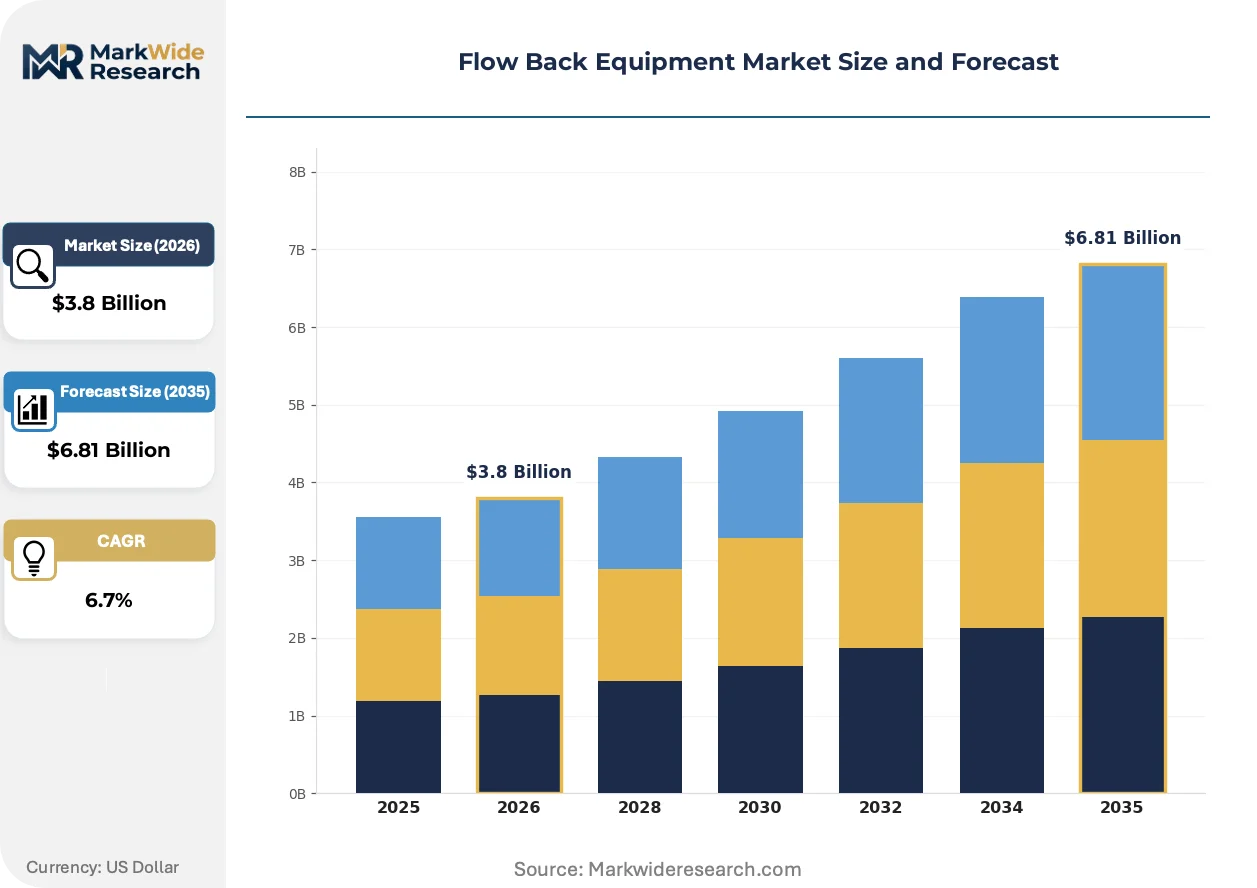
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Separators, Pressure Control Equipment, Filter Housings, Load Cells Application: Onshore Operations, Offshore Operations, Workover Operations, Production Testing Technology: Hydraulic Technology, Mechanical Technology, Pneumatic Technology, Digital Technology End User: Oil & Gas Companies, Service Providers, Equipment Manufacturers, Engineering Firms |
| Companies Covered | Schlumberger Limited, Halliburton, Baker Hughes Company, Weatherford International, NOV Inc., KLX Energy Services, TechnipFMC, Keane Group, NexTier Oilfield Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Back Equipment Market Evolving Landscape
Remote monitoring architectures and autonomous surface control systems are compressing the traditional separation equipment value chain, while metallurgical advances address corrosive multiphase streams.
Modular skid-mounted separation units with integrated sand detection and chemical injection capabilities are fragmenting the conventional equipment rental model. Unconventional shale operators in the Permian and Bakken formations now specify these systems for 70-80% of new pad developments. The technology is fragmenting procurement patterns away from standalone component leasing toward bundled service contracts with performance guarantees.
EPA New Source Performance Standards for methane and volatile organic compounds mandate closed-vent systems and flare minimization across greenfield well completions. The rule expands demand for vapor recovery units and enclosed separator designs while threatening open-top tank configurations with regulatory obsolescence. Equipment fabricators in Texas and North Dakota are accelerating R&D spending on zero-emission surface systems to maintain fleet eligibility.
Service contract unbundling is separating hardware rental from technical advisory and optimization services. Large independents in the Delaware Basin now procure separation equipment through equipment-as-a-service models while retaining choke management expertise in-house. This pattern is most visible among Permian operators with centralized production engineering teams and proprietary well performance databases.
Flow Back Equipment Market Segmentation
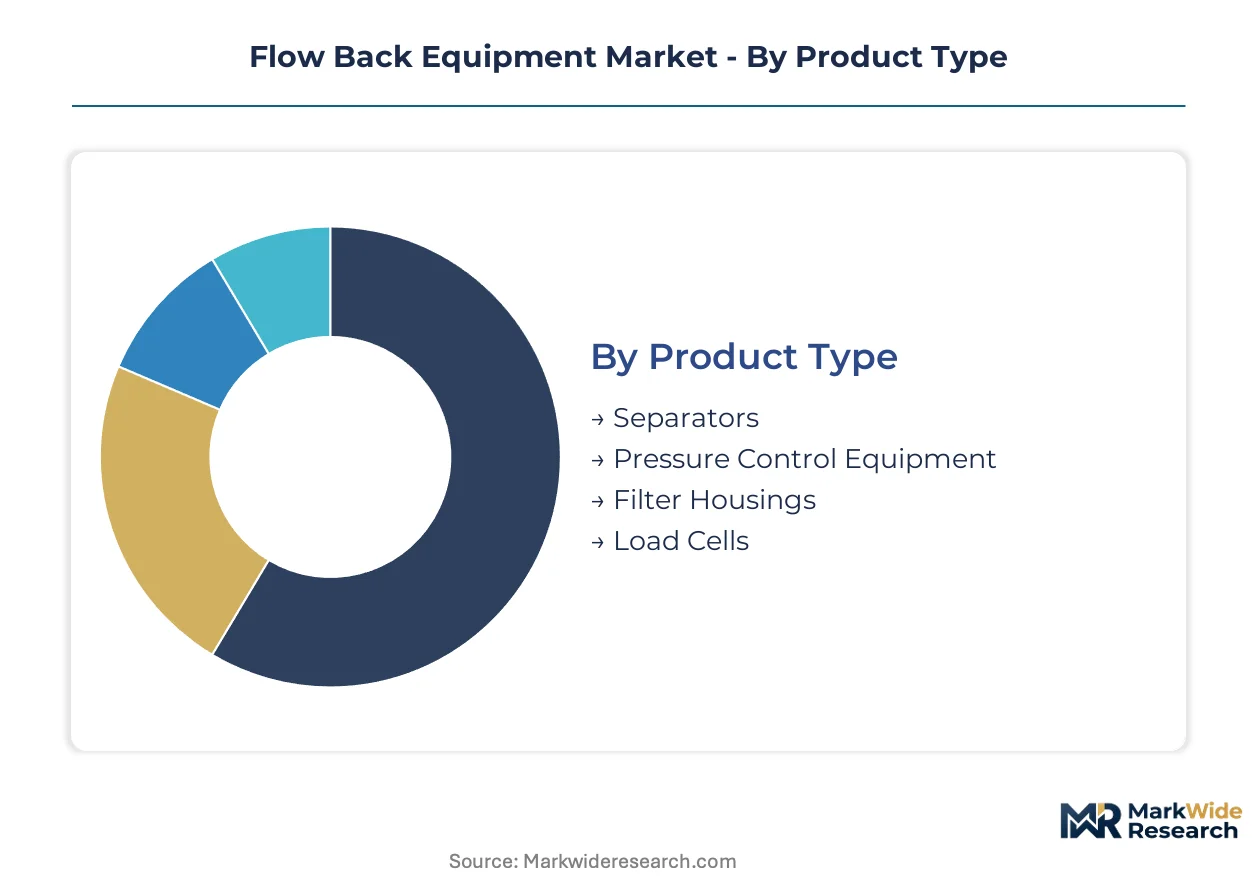
Flow back equipment segmentation reflects divergent technical requirements across well completion intensity, environmental compliance tiers, and automation maturity levels. Equipment specifications vary dramatically between Permian Basin pad drilling and Gulf of Mexico deepwater applications.
Product Type:
Separators face the strongest substitution pressure from integrated modular skids that bundle separation with sand management and vapor recovery, while standalone pressure control equipment maintains durable demand due to specialized choke precision requirements.
- Separators:These vessels handle multiphase fluid streams at 5,000 to 15,000 psi, separating hydrocarbons, produced water, and solids through gravity settling and cyclonic action. Demand concentrates in the Permian Basin where extended well cleanup periods and higher proppant loads strain conventional vessel capacity. EPA closed-vent mandates accelerate replacement of open-top configurations with enclosed separator designs.
- Pressure Control Equipment:Chokes, valves, and manifold systems regulate surface pressure during initial production to prevent formation damage and protect downstream infrastructure. Operators in the Delaware Basin specify these components for 70-80% of new pad developments where autonomous choke control commands premium pricing against mechanical equivalents.
- Filter Housings:Cartridge and bag filtration systems remove formation fines and residual proppant from produced fluids before pipeline injection.
- Load Cells:Weighing sensors integrated into sand management systems quantify proppant returns and optimize choke management strategies.
Separators anchor the volume base while Digital Technology gains share at the steepest rate.
Application:
Cost tier differentiation separates high-specification offshore systems from standardized onshore rentals, with margin pools diverging by metallurgy complexity and regulatory certification requirements.
- Onshore Operations:Surface-mounted separation and pressure control systems dominate equipment deployment across unconventional shale basins. Texas and North Dakota operators drive specification changes as state flaring restrictions and pad drilling density strain legacy infrastructure beyond design capacity.
- Offshore Operations:Compact skid-mounted systems with corrosion-resistant alloys address space constraints and sour service conditions on production platforms. These specifications command substantially higher margin pools due to duplex and super-duplex stainless steel requirements.
- Workover Operations:Temporary flow back equipment deployed during well intervention and recompletion activities.
- Production Testing:Portable separation and measurement systems evaluate well performance during initial completion and diagnostic operations.
Onshore Operations generate the highest absolute equipment demand while Offshore Operations deliver the steepest margin expansion trajectory.
Technology:
Customer type fragmentation splits procurement between automated system adopters seeking crew reduction and conventional rental houses serving price-sensitive independents.
- Digital Technology:Remote monitoring architectures, autonomous choke control, and predictive maintenance algorithms embedded in pressure control skids. Large independents in the Delaware Basin now procure these systems through equipment-as-a-service models while retaining optimization expertise in-house.
- Hydraulic Technology:Fluid-powered actuation systems for choke and valve control in high-pressure surface applications. These systems maintain installed base across the Bakken formation where extreme winter conditions challenge electronic component reliability.
- Mechanical Technology:Manual choke and valve adjustment systems with lowest capital cost but highest crew dependency.
- Pneumatic Technology:Compressed air-driven actuation for surface pressure control in standard service environments.
Hydraulic Technology retains the largest installed base while Digital Technology climbs the fastest.
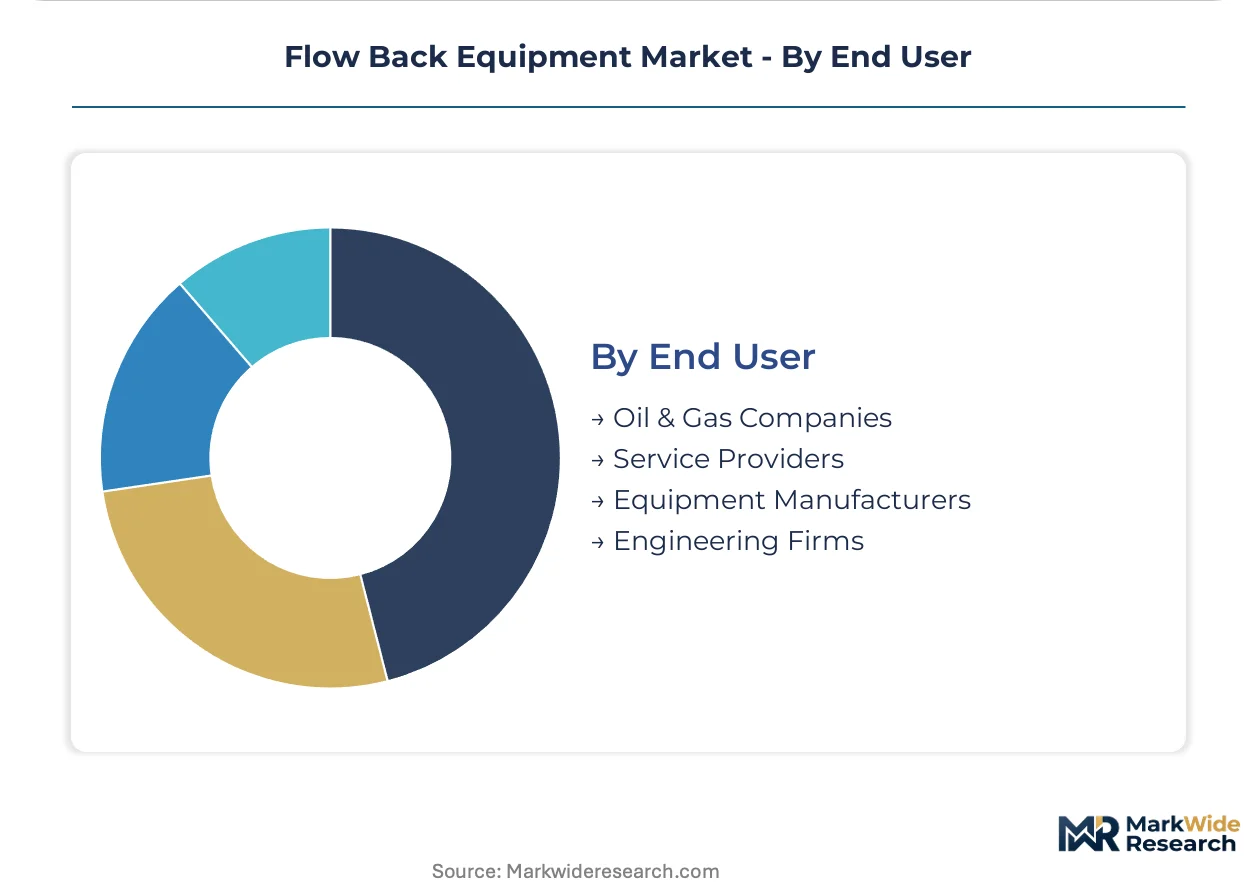
End User:
Supply concentration among integrated service providers shapes procurement leverage, with oil and gas operators fragmenting spend across multiple equipment rental and technology vendors.
- Oil & Gas Companies:Exploration and production firms that own flow back equipment for proprietary pad developments or lease systems for well completion campaigns. Permian Basin independents with centralized production engineering teams drive unbundling of hardware rental from technical advisory services.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes anchor equipment rental and bundled service delivery. These firms differentiate through backward integration into proprietary valve manufacturing and predictive maintenance algorithm development.
- Equipment Manufacturers:Fabricators producing separators, pressure control skids, and filtration systems for direct sale or rental fleet supply.
- Engineering Firms:Technical advisors specifying equipment configurations and optimizing well cleanup procedures.
Service Providers control the dominant revenue share while Oil & Gas Companies expand fastest through in-house equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA New Source Performance Standards for methane and volatile organic compounds anchor regulatory pressure in the United States, forcing equipment replacement cycles across unconventional shale basins while state-level restrictions in Texas and North Dakota compound compliance complexity.
United States
Unconventional shale operators in the Permian Basin drive equipment adoption as longer laterals and higher proppant loads intensify flowback complexity. State regulators in Texas and Colorado impose additional venting and flaring restrictions that accelerate equipment replacement cycles. Pad drilling density in West Texas and southeastern New Mexico strains conventional separation infrastructure beyond design capacity.
Canada
Alberta oil sands operators and Montney shale developers require specialized pressure control systems for cold-climate operations and sour gas service. Health Canada and provincial regulators enforce methane reduction mandates aligned with federal emissions intensity benchmarks. Calgary-based equipment fabricators concentrate on modular skid designs for remote northern deployments.
Saudi Arabia
Aramco's tight gas and unconventional development programs generate demand for high-specification separation systems capable of handling corrosive sour service conditions. The country's national oil company imposes stringent local content requirements and technology transfer obligations on foreign equipment suppliers. Eastern Province industrial cities host fabrication clusters serving both domestic and regional export markets.
China
Sinopec and PetroChina shale gas developments in Sichuan-Chongqing and Ordos basins require domestic-manufactured flowback equipment under import substitution policies. MEE methane control regulations and GB standards for pressure equipment certification reshape procurement specifications. Yangtze River Delta fabrication hubs supply standardized skids for onshore unconventional completions.
Brazil
Pre-salt layer development and onshore unconventional pilots in the Recôncavo Basin create demand for compact offshore-specification systems. ANP local content rules and Petrobras technical standards govern equipment qualification and supplier selection. Rio de Janeiro industrial corridors concentrate pressure vessel manufacturing for deepwater production platforms.
Flow Back Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure where scale advantages in manufacturing and service networks separate dominant players from regional fabricators. Integrated oilfield service conglomerates control the premium segment through captive supply chains and bundled service contracts. Specialist equipment manufacturers occupy mid-market positions with standardized skid configurations. Competitive moves concentrate on backward integration into proprietary component manufacturing and predictive maintenance algorithm development.
Among integrated service providers, Schlumberger Limited, Halliburton, and Baker Hughes Company exemplify the dominant archetype, each representing different strategic approaches to technology integration and service bundling. Schlumberger Limited anchors the digital convergence vector through virtual commissioning capabilities. Halliburton occupies a position emphasizing in-house production of pressure control components. Baker Hughes Company exemplifies predictive maintenance embedding within surface equipment portfolios.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton |
| Baker Hughes Company |
| Weatherford International |
| NOV Inc. |
| KLX Energy Services |
| TechnipFMC |
| Keane Group |
| NexTier Oilfield Solutions |
| Others |
Value Network & Pricing Analysis
EPA New Source Performance Standards for methane and volatile organic compounds simultaneously gate supplier qualification and stratify price tiers, as closed-vent certification requirements filter out uncertified fabricators while commanding 40-60% premiums for compliant metallurgy. Buyers in the Permian Basin face bifurcated procurement options between premium enclosed separator systems and depreciating open-top tank inventories facing regulatory obsolescence.
Pricing Analysis
Offshore-specification systems in the Gulf of Mexico command substantially higher price points than standardized onshore rentals due to duplex stainless steel requirements and compact skid engineering. Three-tier pricing structure across premium, standard, and economy levels segments by automation maturity and metallurgy grade, with digital-integrated pressure control skids extracting premium positioning against mechanical equivalents. Cost compression in the standard tier is intensifying because rental fleet operators liquidate non-compliant open-top configurations ahead of federal methane fee implementation. Independent operators in the Delaware Basin exhibit highest price sensitivity, while Aramco and Petrobras specifications tolerate premium positioning for sour-service corrosion resistance.
Supply Chain Analysis
Inventory cycles for corrosion-resistant alloys extend lead times beyond standard carbon steel procurement, compressing deployment velocity for urgent pad completions in West Texas. Manufacturing concentrates in the United States, China, and Saudi Arabia, with Houston fabrication clusters serving North American shale basins and Yangtze River Delta hubs supplying Sinopec's Sichuan-Chongqing developments. Supply chains draw from nickel, chromium, and molybdenum feedstocks for super-duplex grades, with single-source vulnerability concentrated in South African chromite ore. Distribution runs through integrated service provider rental fleets and direct OEM sales to national oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow back equipment procurement is shifting toward platform-based service contracts where predictive maintenance algorithms and remote monitoring capabilities create interoperability lock-in, mirroring the broader oilfield services ecosystem convergence around digital twin integration.
For Market Incumbents: Fortify captive supply chains through backward integration into proprietary valve and choke manufacturing, insulating margin pools from commodity metallurgy volatility. Prioritize EPA-compliant enclosed separator R&D to accelerate fleet turnover ahead of state-level emission intensity benchmarks in Colorado and North Dakota. Defensive consolidation around predictive maintenance algorithm development counters emerging equipment-as-a-service entrants unbundling hardware from optimization services. For New Entrants and Emerging Players: Lead with modular skid configurations targeting Colorado's regulatory tailwind, where state venting restrictions create first-mover advantage for zero-emission surface system providers. White-space concentrates in autonomous choke control retrofit kits for legacy mechanical infrastructure across the Bakken formation, where extreme winter conditions challenge electronic reliability gaps. Go-to-market through direct procurement relationships with Permian independents possessing centralized production engineering teams bypassing integrated service providers. For Investors and Strategic Acquirers: EPA methane fee implementation reshapes the acquisition landscape toward enclosed separator specialists with certified fabrication capacity and vapor recovery unit integration expertise. Long-term viability centers on digital-technology-enabled service contracts with recurring revenue streams displacing transactional equipment rental. Target acquisition archetype: mid-cap fabricators with API certification and established relationships with Delaware Basin operators. Signal to monitor: state-level emission intensity benchmark acceleration in Texas threatening open-top tank residual value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Valve Manufacturing | Halliburton's choke production captive supply secures margin control against component price volatility. |
| Predictive Maintenance Algorithm Development | Baker Hughes embeds machine learning in pressure control skids enabling condition-based servicing contracts. |
| Zero-Emission Surface System R&D Acceleration | Texas fabricators invest to maintain fleet eligibility under EPA closed-vent mandates. |
| Equipment-as-a-Service Model Deployment | Permian independents unbundle hardware rental from retained in-house choke management expertise. |
| Digital Twin Integration for Virtual Commissioning | Schlumberger reduces onsite crew requirements through remote monitoring architecture deployment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with petroleum engineering directors, flowback service managers, and equipment procurement leads at Permian Basin operators, and secondary validation through EPA regulatory filings, state environmental agency rulemakings, and API equipment certification databases. Bottom-up triangulation against customs data for corrosion-resistant alloy imports and top-down reconciliation with EIA drilling productivity reports anchored volume estimates. Primary fieldwork captured deployment velocity constraints from skilled technician scarcity across North Dakota and West Texas.
Across the modeling period, analytical frameworks segmented by product type, application intensity, automation maturity, and end-user procurement pattern. CAGRs derived from well completion count projections, lateral length trajectories, and proppant intensity curves specific to unconventional shale formations. Forecast inputs incorporated pad drilling density saturation in the Permian Basin and state regulatory adoption timelines for methane emission intensity benchmarks.
The analysis sits within stated boundaries; outcomes outside sustained unconventional shale investment cycles or accelerated federal methane regulation would require recalibration. Forecasts reflect documented assumptions regarding equipment replacement rates and technology adoption curves. Commodity price volatility, trade policy shifts affecting alloy sourcing, and regulatory enforcement variance across state jurisdictions constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Air Compressor Controller Market