
 Low Calorie Flour Market | 2026-2036
Low Calorie Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Flour Market Analytics
Commercial bakeries is collapsing as the dominant buyer archetype while direct-to-consumer home baking segments gain share. Ingredion leverages its ingredient technology portfolio to supply modified starch solutions that reduce caloric density in refined flour alternatives. Tate & Lyle sustains competitive positioning through its specialty sweetener and fiber integration capabilities that complement low-calorie flour formulations. Cargill anchors significant North American supply capacity for pulse-based and alternative grain flours.
Low calorie flour encompasses milled products formulated with reduced caloric content per serving through fiber enrichment, fat mimetic incorporation, or substitution of traditional high-starch grains with lower-glycemic alternatives such as almond meal or resistant starch blends. These formulations typically achieve caloric reductions of 15-40% compared to standard wheat flour while maintaining functional properties for leavening, binding, and moisture retention in baked goods. Almond flour occupies the premium tier within product type segmentation due to its keto-alignment and established consumer recognition, while oat flour captures mainstream expansion through its familiarity and soluble fiber content. Chickpea flour leads growth velocity among alternative proteins as manufacturers seek dual functionality across gluten-free and plant-protein positioning. Margin pools concentrate in specialty retail and online channels where health-claim differentiation commands price premiums.
FDA nutrition labeling requirements and the USDA organic certification framework shape product formulation standards and market access conditions for domestic manufacturers. EFSA health claim authorization processes in Europe determine which fiber-related and glycemic-response claims may appear on packaging, directly influencing consumer communication strategies. Stakeholders must monitor evolving front-of-package warning label regimes and emerging whole-grain certification standards to anticipate reformulation cycles and channel eligibility shifts.
Market Dynamics
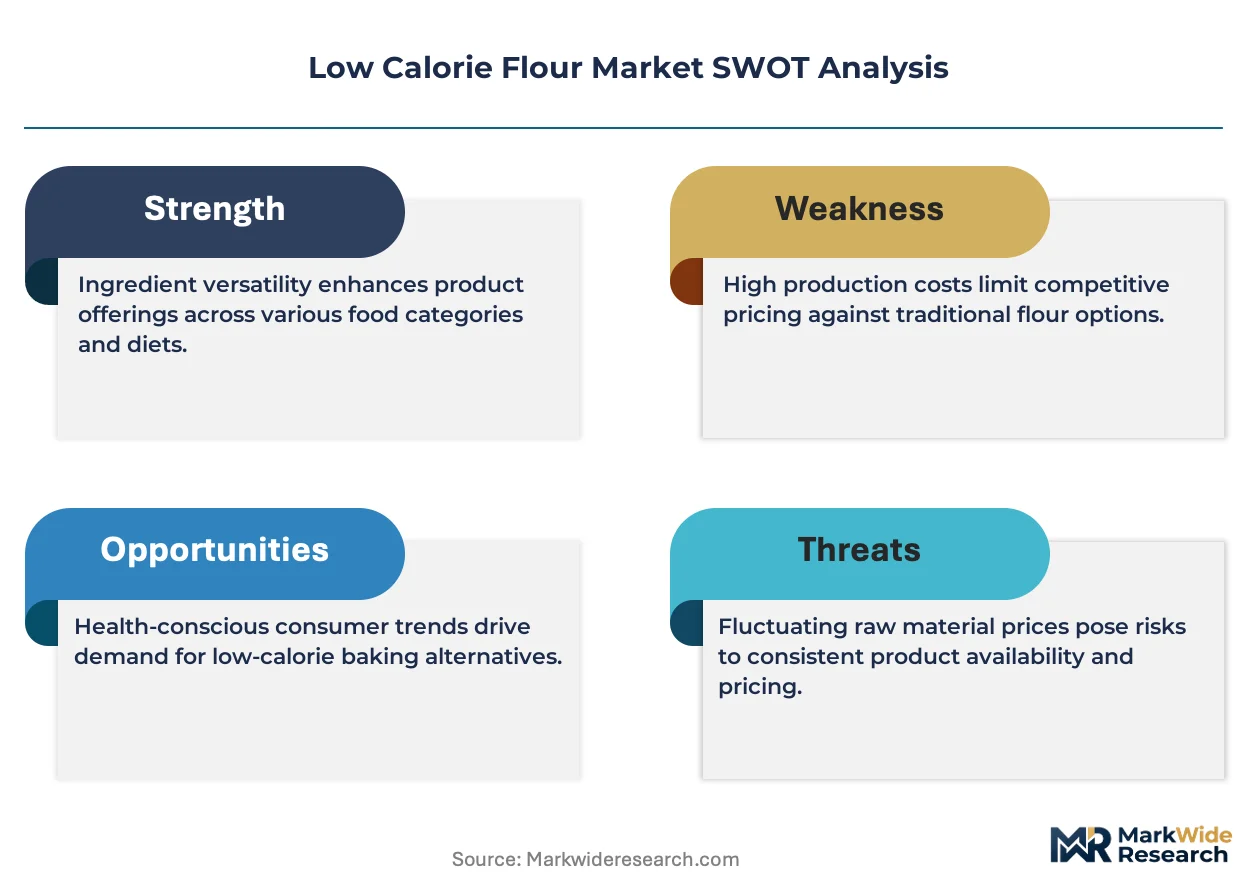
FDA's updated Nutrition Facts labeling requirements are forcing reformulation cycles across commercial bakeries as glycemic-index claims become central to packaging strategies and channel eligibility.
Growth Catalysts
- EFSA Health Claim Authorization:European fiber-related and glycemic-response claims on packaging are accelerating consumer pull for oat and resistant starch formulations in Germany and France.
- Home Baking Segment Expansion:Direct-to-consumer channels are capturing procurement share from commercial bakeries as health-conscious cooks prioritize almond and chickpea flour varieties.
- USDA Organic Certification:The framework is opening premium retail placement for fiber-enriched and alternative grain products in United States specialty grocers.
Market Restraints
- Almond Supply Concentration:California drought cycles are creating input cost volatility for premium-tier almond flour production.
- Modified Starch Technical Limitations:Fat mimetic incorporation struggles to replicate wheat flour's extensibility in high-hydration dough systems.
- Front-of-Package Warning Regimes:Emerging label requirements in select jurisdictions are compressing permissible health claim language and reformulation timelines.
Strategic Opportunities
- India Market Underpenetration:Rising diabetes prevalence and FSSAI regulatory clarity are creating white space for low-glycemic chickpea and millet flour positioning.
- Pulse-Flour Protein Convergence:Chickpea flour's dual functionality across gluten-free and plant-protein categories is enabling new bakery and snack applications.
- Online Channel Expansion:Direct subscription models for specialty flour blends are bypassing traditional grocery distribution markups.
Industry Challenges
- Resistant Starch Integration Complexity:Commercial bakeries face capex requirements for modified mixing and proofing equipment to handle fiber-heavy formulations.
- Whole-Grain Certification Timelines:Multiple third-party standards are creating compliance fragmentation and slowing product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Flour Market |
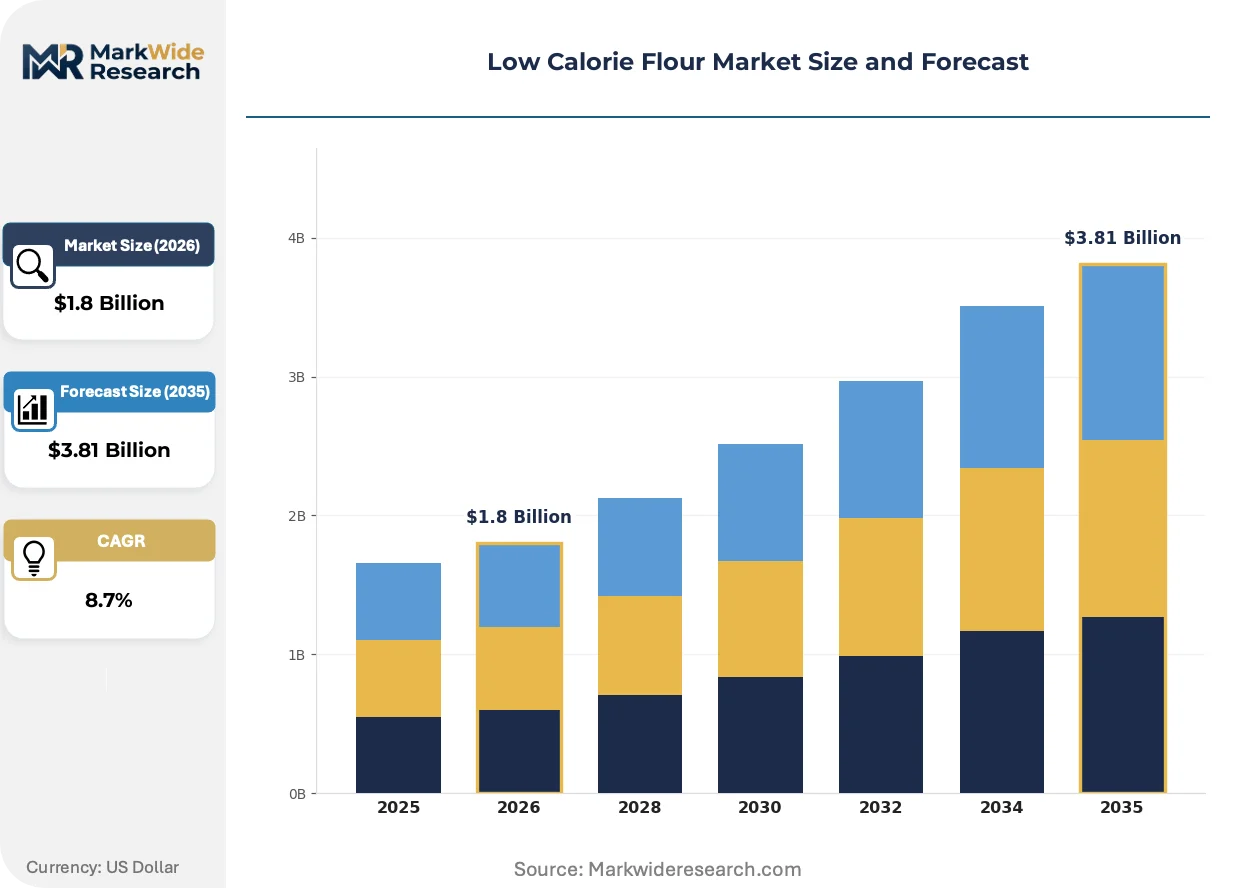
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Coconut Flour, Oat Flour, Chickpea Flour End Use: Baking, Cooking, Snack Foods, Meal Replacement Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Bags, Boxes, Tubs, Bulk Packaging |
| Companies Covered | Ingredion, Tate & Lyle, Cargill, Archer Daniels Midland Company, BENEO, General Mills, Bob's Red Mill Natural Foods, Nutiva, Ardent Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Flour Market Evolving Landscape
Active reshaping of the low calorie flour market centers on equipment downsizing for precision milling, regulatory acceleration of clean-label claims, and the collapse of traditional bakery procurement hierarchies.
Precision roller milling technology is miniaturizing. Small-batch almond and oat flour processors are adopting compact, continuous-flow systems previously limited to industrial-scale wheat operations. This equipment compression is enabling regional micro-mills to achieve particle-size consistency that rivals centralized production, fragmenting supply concentration.
REACH chemical safety assessments in Europe are tightening scrutiny of processing aids and fortification additives used in fiber-enriched flours. Manufacturers are reformulating to eliminate contested substances ahead of authorization sunsets. German and Dutch specialty millers are accelerating clean-label certifications to preempt compliance disruptions.
Home cooks are consolidating purchase authority previously held by commercial bakery procurement departments. Subscription flour services and direct-from-mill e-commerce are displacing traditional foodservice distribution for premium low-calorie varieties. This channel inversion is most visible in United States metropolitan markets where health-claim literacy drives repeat purchase behavior.
Low Calorie Flour Market Segmentation
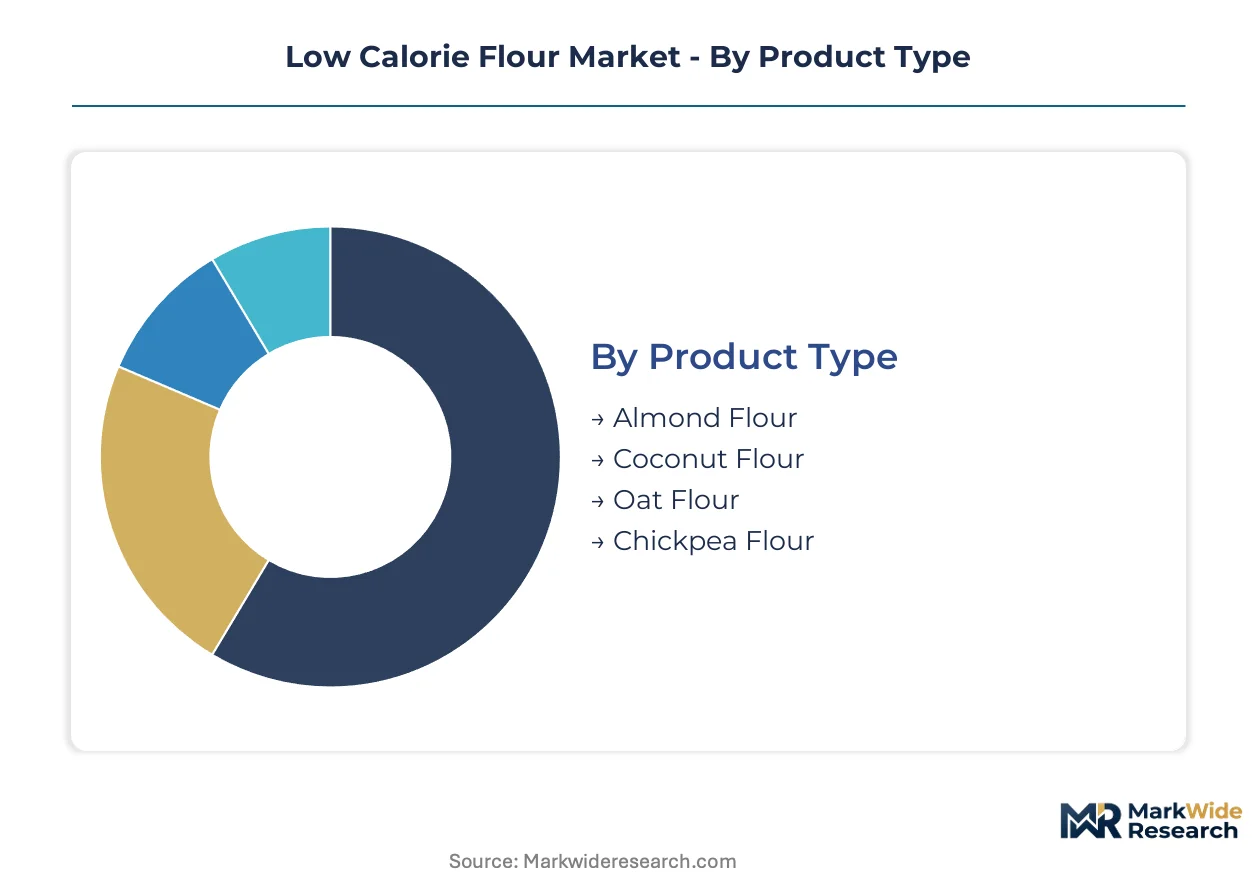
Segmentation in low calorie flour markets determines regulatory compliance pathways, margin capture potential, and equipment investment requirements. Product type and end-use splits reveal where FDA nutrition labeling and EFSA health claim authorization create competitive moats. Distribution channel fragmentation directly shapes procurement authority shifts between commercial bakeries and home baking segments.
Product Type:
FDA's updated Nutrition Facts labeling requirements and EFSA fiber-related claim authorization processes create divergent formulation standards across milled alternatives, concentrating margin pools in segments that satisfy both glycemic-index positioning and clean-label certification.
- Almond Flour:Finely ground blanched almond meal delivering 15-40% caloric reduction against wheat flour through high fat, low carbohydrate composition. Keto-aligned demand concentrates in United States metropolitan markets where health-claim literacy drives subscription flour services and direct-from-mill e-commerce. California drought cycles inject input cost volatility that compresses margin stability for premium-tier positioning.
- Oat Flour:Milled whole oat groats with soluble beta-glucan fiber enabling glycemic-response claims under EFSA authorization frameworks. German and French commercial bakeries are accelerating procurement for resistant starch blend formulations as front-of-package labeling regimes elevate fiber visibility. Familiarity among mainstream consumers sustains volume leadership despite lower price realization than nut-based alternatives.
- Coconut Flour:Defatted coconut meat flour with high fiber density requiring modified hydration protocols in baking applications. Southeast Asian supply chains serve specialty health food stores in United States coastal cities.
- Chickpea Flour:Stone-milled garbanzo bean flour delivering dual functionality across gluten-free and plant-protein positioning. Indian FSSAI regulatory clarity and rising diabetes prevalence are opening white space for low-glycemic formulations in Mumbai and Delhi retail channels.
Established volume favors oat flour; emerging adoption favors chickpea flour.
End Use:
Application-driven cost tiers separate equipment-intensive commercial production from precision-milling home baking segments, with capex requirements for modified mixing and proofing equipment determining procurement authority concentration.
- Baking:Bread, pastry, and confectionery applications requiring leavening compatibility and moisture retention in fiber-heavy formulations. Commercial bakeries face resistant starch integration complexity demanding proofing equipment upgrades, while home cooks bypass traditional foodservice distribution through direct subscription models. United States bakery chains are collapsing as dominant buyer archetypes.
- Cooking:Sauce thickening, coating, and binding applications where fat mimetic incorporation replaces wheat flour extensibility. German specialty millers are accelerating clean-label certifications to preempt REACH chemical safety assessment disruptions for processing aids.
- Snack Foods:Extruded and baked snack matrices where pulse-flour protein convergence enables new texture positioning. Indian manufacturers leverage chickpea flour for gluten-free cracker and chip applications.
- Meal Replacement:Powdered beverage and bar formulations requiring complete amino acid profiles and controlled glycemic response. Online retail channels capture procurement share through health-claim differentiation.
Commercial scale anchors baking; direct-to-consumer velocity is climbing fastest in meal replacement.
Distribution Channel:
Customer type fragmentation between institutional procurement and individual purchase authority is reshaping channel economics, with margin pools concentrating where health-claim differentiation commands price premiums.
- Online Retail:Direct subscription models and e-commerce platforms bypassing traditional grocery distribution markups. United States metropolitan markets exhibit highest repeat purchase behavior for almond and oat flour blends.
- Supermarkets:Mass retail placement requiring USDA organic certification for premium positioning in United States specialty grocer sections.
- Health Food Stores:Curated assortment emphasizing EFSA-authorized fiber claims and glycemic-index labeling for educated consumers in Germany and France.
- Specialty Shops:Regional micro-mills leveraging precision roller milling miniaturization to achieve particle-size consistency rivaling centralized production.
Volume concentration remains in supermarkets; steepest expansion trajectory sits with online retail.
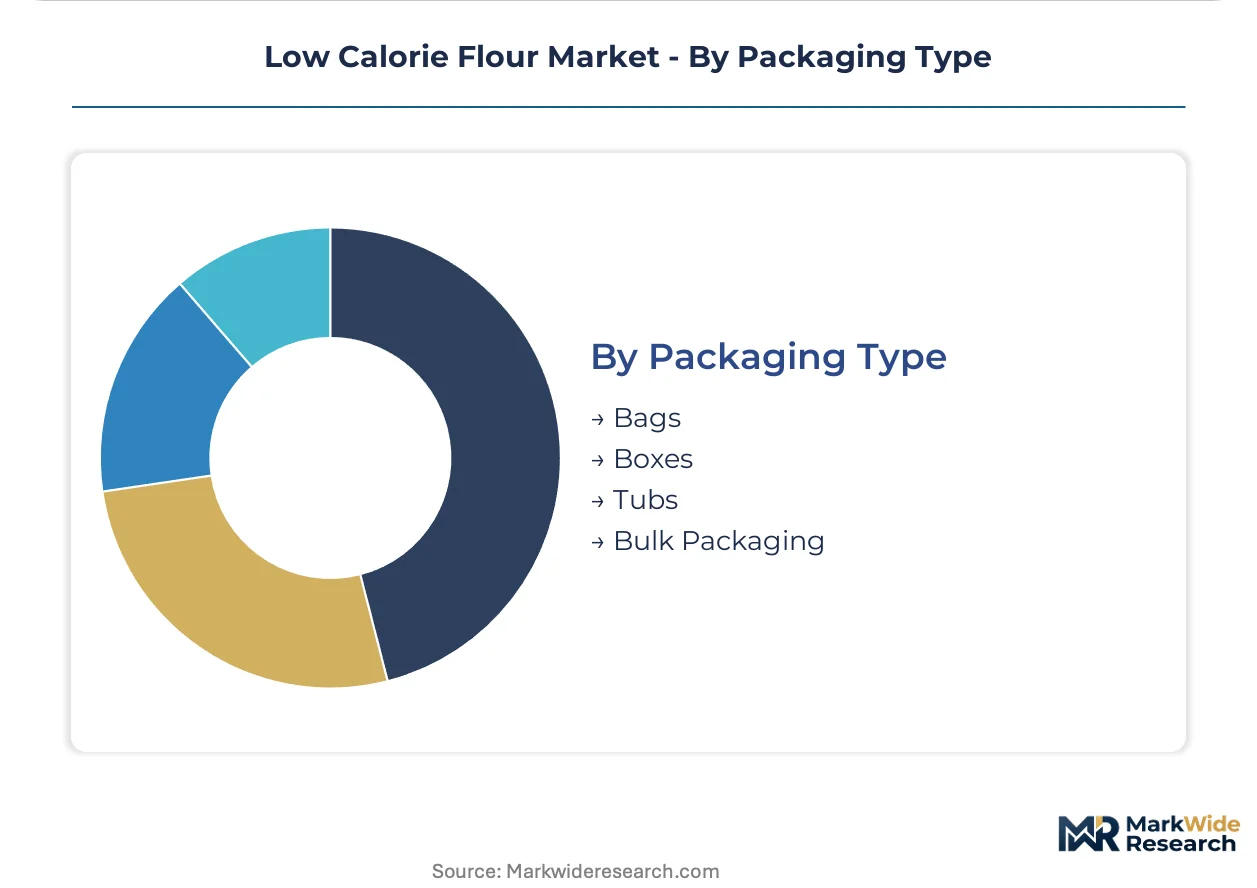
Packaging Type:
Supply concentration in California almond processing and Midwest oat milling dictates packaging format economics, with bulk configurations serving commercial bakeries and unitized formats capturing home baking premiums.
- Bags:Flexible packaging for retail unit sizes dominating oat flour distribution in German and French supermarkets.
- Boxes:Rigid secondary packaging for premium almond flour varieties in United States specialty retail.
- Tubs:Reclosable rigid containers for high-humidity environments preserving coconut flour shelf stability.
- Bulk Packaging:Industrial totes and supersacks serving commercial bakery procurement with modified starch solution integration.
Operational scale favors bulk packaging; premium positioning favors bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland anchors North American almond flour distribution, connecting California Central Valley processing to Pacific Rim markets. German rail corridors link EFSA-regulated millers to pan-European distribution. Mumbai's Nhava Sheva port enables Indian pulse flour exports.
United States
Bakery chain procurement collapse and home baking subscription growth drive almond and oat flour velocity. FDA updated Nutrition Facts labeling forces glycemic-index claim integration into packaging strategies. California Central Valley processing clusters face drought-induced input cost volatility.
Germany
Commercial bakeries accelerate resistant starch blend procurement for EFSA-authorized fiber claims. REACH chemical safety assessments tighten scrutiny of processing aids in fiber-enriched formulations. Cologne-Düsseldorf millers preempt compliance disruptions through clean-label certification acceleration.
India
Rising diabetes prevalence and FSSAI regulatory clarity open white space for low-glycemic chickpea and millet positioning. Mumbai and Delhi retail channels capture emerging demand for gluten-free plant-protein formulations. Gujarat pulse processing clusters supply domestic and export markets.
France
EFSA health claim authorization processes determine fiber-related packaging language for educated consumers. Front-of-package labeling regimes elevate fiber visibility in supermarket placement. Lyon and Paris specialty grocers curate glycemic-index differentiated assortments.
United Kingdom
Direct-to-consumer e-commerce channels bypass traditional grocery distribution for premium varieties. Subscription flour services consolidate purchase authority from commercial procurement departments. London metropolitan markets exhibit highest health-claim literacy and repeat purchase behavior.
Low Calorie Flour Market Competitive Landscape
Listed leaders compete with private specialists across ingredient technology portfolios, creating a tiered structure where scale-driven multinationals anchor supply capacity and regional millers capture premium positioning. Strategic archetypes include modified starch solution providers, specialty sweetener integrators, and pulse-based alternative grain suppliers. Dominant competitive moves center on strategic partnerships for fiber enrichment capabilities and geographic expansion into underpenetrated diabetes-prevalent markets.
Within the ingredient technology tier, Ingredion and Tate & Lyle exemplify multinational specialists leveraging formulation science to reduce caloric density. Cargill occupies a position among North American supply anchors with pulse-based and alternative grain flour capacity. These three represent distinct archetypes: modified starch innovation, specialty sweetener integration, and agricultural commodity processing scale.
| Leading Market Players |
|---|
| Ingredion |
| Tate & Lyle |
| Cargill |
| Archer Daniels Midland Company |
| BENEO |
| General Mills |
| Bob's Red Mill Natural Foods |
| Nutiva |
| Ardent Mills |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for almond flour processors in California's Central Valley concentrate pricing power with handlers who weather drought-induced supply squeezes. This lead-time exposure tightens margin capture for premium-tier positioning while oat flour's Midwest sourcing sustains more stable contract structures.
Pricing Analysis
Volume-discount tiering separates commercial bakery procurement from direct-to-consumer subscription models. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel control. Price erosion runs through almond flour's premium tier as California water restrictions compress supply reliability. Home baking segments exhibit lowest price sensitivity due to health-claim literacy, while commercial bakeries negotiate aggressively on resistant starch blend contracts.
Supply Chain Analysis
Just-in-time inventory strategies dominate commercial bakery procurement, while strategic stockpiling characterizes almond flour handlers facing climatic volatility. Supply concentrates in the United States, Germany, and India, with raw material dependencies on California almonds, Midwest oats, and Gujarat chickpeas. Single-source vulnerability in California almond processing creates structural risk for premium-tier formulations. Distribution runs through Port of Oakland for Pacific Rim markets, German rail corridors for EFSA-regulated millers, and Mumbai's Nhava Sheva for pulse flour exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision-milled micro-mills and direct-to-consumer subscription services that bypass traditional foodservice distribution hierarchies.
For Market Incumbents: Consolidate procurement relationships with California almond processors through long-term offtake agreements that lock in supply priority during drought cycles. Deepen backward integration into resistant starch blending capabilities to capture margin pools in EFSA-authorized fiber claim formulations. Channel control through direct subscription platforms defends against micro-mill fragmentation. For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps in United States metropolitan markets offer white-space entry where incumbents under-serve health-claim-literate home bakers. Target India's Mumbai and Delhi retail channels with chickpea flour positioning leveraging FSSAI regulatory clarity. Go-to-market through direct-from-mill e-commerce bypasses traditional grocery distribution markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision roller milling miniaturization, enabling regional micro-mill scalability without industrial-scale capex. Long-term viability favors acquisition targets with dual gluten-free and plant-protein certification capabilities. Watch EFSA health claim authorization timelines as inflection indicators for fiber-enriched formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond Processing | Captive supply from California Central Valley clusters insulates margin from drought volatility. |
| EFSA Health Claim Authorization Investment | Fiber-related packaging claims in Germany and France accelerate oat flour procurement velocity. |
| Direct-to-Consumer Subscription Launch | Online retail channels bypass supermarket distribution markups in United States metropolitan markets. |
| Precision Milling Equipment Miniaturization | Compact continuous-flow systems enable regional micro-mills to rival centralized particle consistency. |
| India Market Entry with Chickpea Positioning | FSSAI regulatory clarity and diabetes prevalence create white space for low-glycemic formulations. |
Research Methodology
A spread of perspectives from commercial bakery procurement directors, specialty miller operations heads, foodservice distribution channel managers, and regulatory affairs leads converged on the working assumptions. Primary interviews combined with secondary validation from FDA nutrition labeling guidance documents, EFSA health claim authorization registers, USDA organic certification databases, and customs trade flow records. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include product type, end-use application, distribution channel, and packaging format across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments. Industry-specific forecast inputs incorporated almond supply volatility indices and EFSA authorization pipeline timelines.
Forecasts assume regulatory continuity in FDA nutrition labeling and EFSA health claim regimes; material policy shifts would require re-modeling. Revision becomes warranted when California drought severity indices or front-of-package warning label adoptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Yeastless Dough Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Soft Biscuit Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Specula Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Baked Foods Market
Bakery Products
Teaseed Cake Market
Bakery Products
Bread Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Low Calorie Bread Market