
 APMEA Frozen Bakery Products Market | 2026-2036
APMEA Frozen Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
APMEA Frozen Bakery Products Market Insights
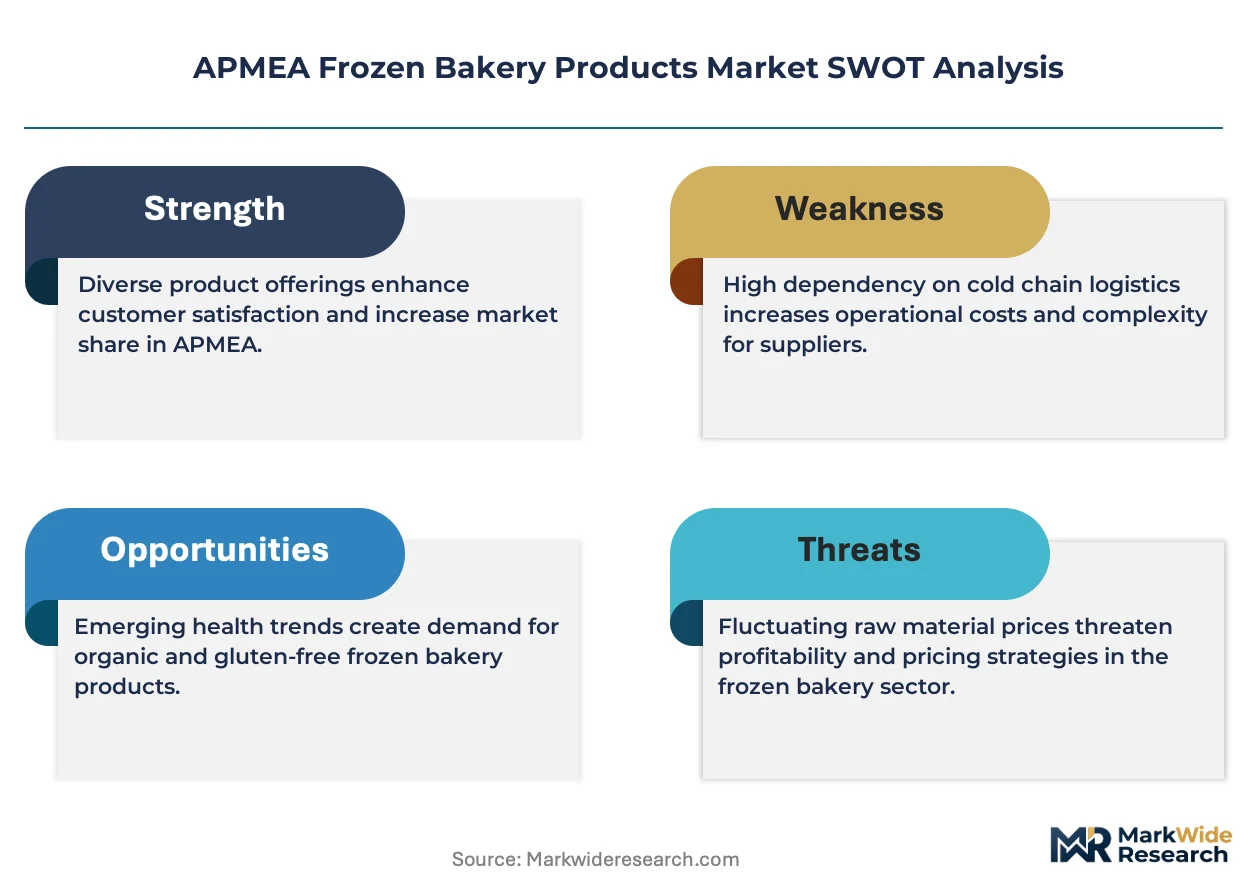
The gap between premium artisan frozen pastries and commodity bread rolls is shifting from a price divide into a supply-chain separation. Europastry anchors the premium tier through specialized laminated dough capacity in Southern Europe that feeds APMEA luxury hotel channels. Grupo Bimbo dominates mass-market bread across Latin American-origin operations that extend into Asian retail. Associated British Foods competes on brand strength in ready-to-bake formats through its Twinings-adjacent retail presence.
APMEA frozen bakery products comprise dough, partially baked, and fully baked items preserved at sub-zero temperatures to arrest staling and microbial activity, typically formulated with modified starches and emulsifiers to survive freeze-thaw cycles. Their primary purpose is to deliver consistent, scalable baked output to foodservice and retail channels without on-site mixing or skilled labor. Bread remains the volume backbone across supermarket and wholesaler channels, while pastries capture disproportionate margin in foodservice and catering. Ready-to-bake formats are expanding fastest among cloud kitchens and QSR chains seeking minimal-prep flexibility, whereas frozen dough still occupies a niche among traditional bakeries with in-house ovens.
FSSAI in India mandates specific additive disclosures and cold-chain integrity documentation for frozen imports, while China's SAMR enforces GB standards on microbial limits and net-content labeling that reshape exporter compliance costs. Australia's FSANZ and New Zealand's MPI jointly govern trans-Tasman trade rules that affect APMEA supply routing and shelf-life claims. Stakeholders must monitor how divergent national labeling regimes and emerging carbon-accounting rules for refrigeration will reshape sourcing decisions and plant-location strategy.
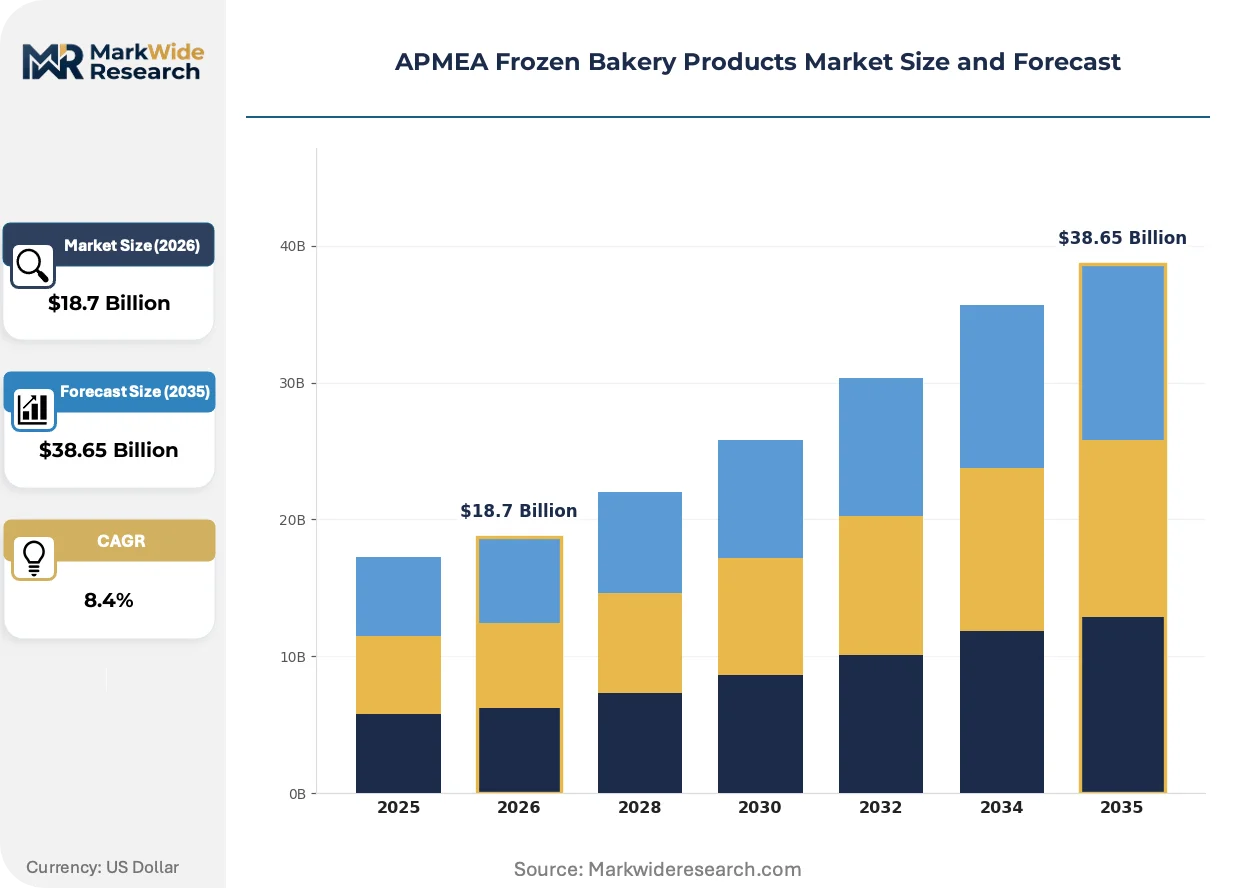
Market Dynamics
Foodservice chains across Southeast Asia are expanding freezer-to-oven programs to cut labor costs and standardize output, compressing the traditional bakery supply chain into centralized frozen distribution hubs.
Growth Catalysts
- Cloud kitchen proliferation:Quick-service restaurants and cloud kitchens in India's urban corridors are scaling frozen paratha and croissant procurement, creating pull for ready-to-bake formats.
- China's SAMR labeling rules:Tightened frozen food labeling requirements are pushing exporters toward reformulation and cleaner ingredient decks, elevating product quality benchmarks across the trade.
- Modified starch advances:New emulsifier blends that survive multiple freeze-thaw cycles are extending shelf stability, enabling longer distribution radii from central production.
Market Restraints
- Wheat price volatility:Input cost swings for the primary flour feedstock compress margins for frozen dough producers operating on fixed-price foodservice contracts.
- Cold-chain infrastructure gaps:Inconsistent refrigeration integrity across last-mile distributors in South Asia creates spoilage risk and limits market penetration.
- Fresh bakery substitution:Traditional wet markets and artisan bakeries in Southeast Asian cities retain consumer preference for same-day baked goods.
Strategic Opportunities
- Vietnam foodservice expansion:Underpenetrated relative to Thailand, Vietnam's growing cafe culture and hotel construction pipeline offer white space for premium frozen pastry supply.
- Australia-New Zealand trans-Tasman routing:FSANZ-MPI joint standards create a harmonized regulatory zone for shelf-life claims, simplifying multi-market product registration.
- Carbon accounting alignment:Emerging refrigeration emissions tracking requirements favor producers with renewable-powered cold storage, creating differentiation for early adopters.
Industry Challenges
- Laminated dough technician scarcity:Skilled labor capable of managing industrial croissant and puff pastry production lines remains concentrated in Southern Europe, constraining local capacity buildout.
- FSSAI import documentation:India's additive disclosure and cold-chain integrity requirements extend certification timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APMEA Frozen Bakery Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Pies End User: Retail, Foodservice, Catering, Bakeries Distribution Channel: Supermarkets, Online, Convenience Stores, Wholesalers Form: Pre-baked, Ready-to-bake, Frozen Dough, Fully Baked |
| Companies Covered | Associated British Foods, Europastry, Nestlé, Unilever, Kellogg Company, Grupo Bimbo, Aryzta AG, Mondelēz International, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APMEA Frozen Bakery Products Market Trends and Innovations
Refrigeration technology and regulatory disclosure requirements are converging to reshape how frozen bakery products are formulated, labeled, and distributed across APMEA trade corridors.
Blast-freezing systems with integrated humidity control are rewriting the economics of laminated dough production. Luxury hotel chains and premium foodservice distributors are adopting these systems at scale in Singapore and Dubai. The technology is compressing the quality gap between centrally produced frozen croissants and artisan same-day alternatives.
China's SAMR enforcement of GB standards on microbial limits and net-content labeling is forcing exporters to redesign packaging and reformulate preservative systems. The industrial consequence is a bifurcation between compliant premium suppliers and commodity players exiting the market. Frozen bread rolls and paratha targeting China's retail channels are most affected, with reformulation timelines stretching 12-18 months.
Foodservice procurement is consolidating around single-source frozen bakery contracts with outcome-based quality guarantees. Hotel chains and airline caterers are displacing fragmented multi-supplier arrangements with centralized national agreements. This pattern is most visible in India's metropolitan corridors, where cloud kitchen operators negotiate direct supply relationships bypassing traditional wholesale bakery distributors.
APMEA Frozen Bakery Products Market Segmentation
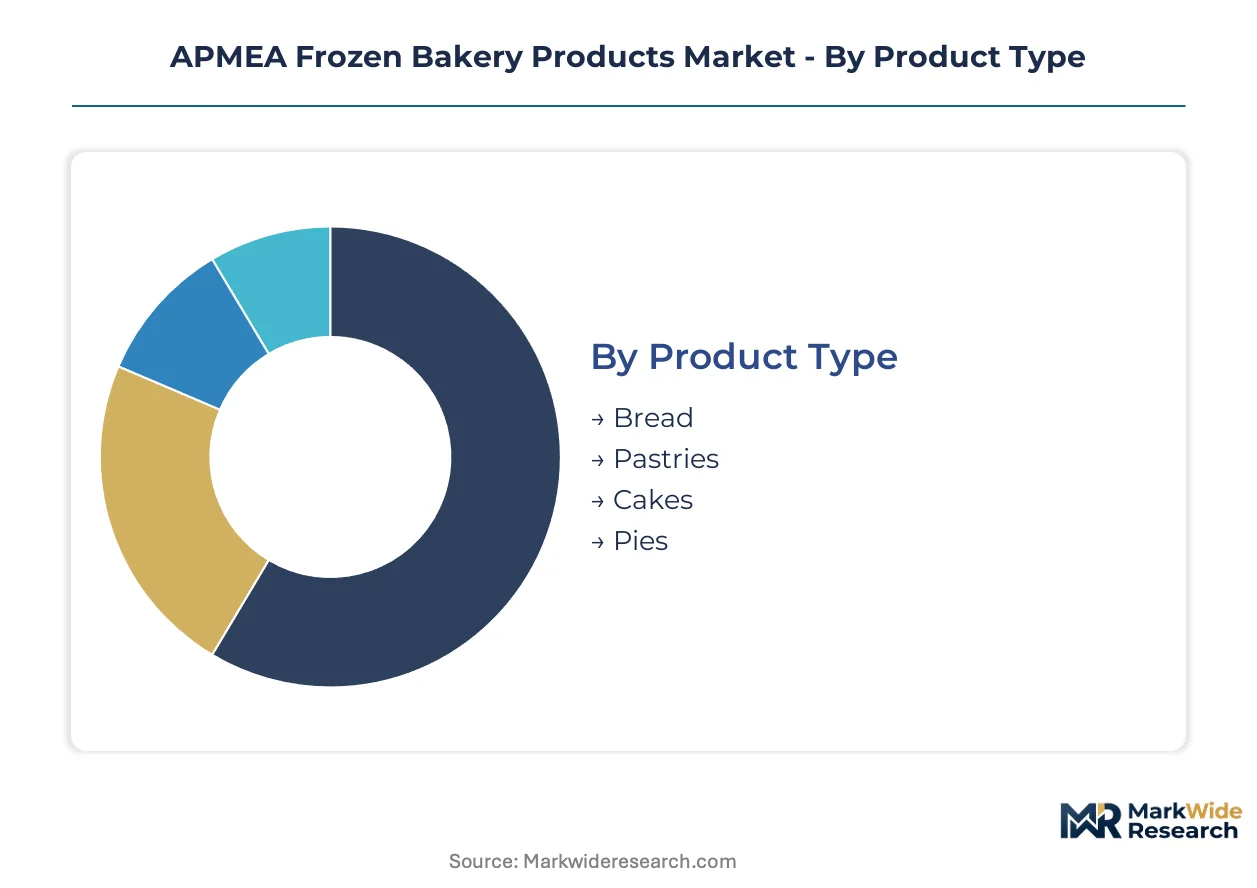
Frozen bakery supply chains in APMEA diverge sharply by product physics and customer operational constraints. Each segmentation axis reveals distinct margin profiles, cold-chain requirements, and regulatory exposure that shape supplier strategy.
Product Type:
Formulation complexity and freeze-thaw tolerance separate commodity volumes from premium positioning.
- Bread:High-volume frozen loaves and rolls rely on modified starch systems to maintain crumb structure through distribution. Demand clusters in India's supermarket retail and Southeast Asian QSR bun procurement, where labor cost reduction drives freezer-to-oven adoption.
- Pastries:Laminated dough products—croissants, danishes, puff pastry—command disproportionate margin through luxury hotel and cafe channels in Singapore, Dubai, and Vietnam. Blast-freezing technology with humidity control is compressing quality gaps with artisan alternatives.
- Cakes:Frozen layer cakes and sheet cakes serve institutional catering and airline foodservice with extended shelf-life formulations.
- Pies:Savory and dessert pies occupy niche positions in Australian retail and New Zealand foodservice, constrained by regional taste preferences.
Mature deployment sits with Bread. Newer deployment is concentrated in Pastries.
End User:
Operational sophistication and volume scale determine procurement patterns and contract structures.
- Foodservice:Hotel chains, airline caterers, and cafe operators are consolidating around single-source national contracts with outcome-based quality guarantees. This channel captures the steepest expansion trajectory as cloud kitchens proliferate across Indian metropolitan corridors.
- Retail:Supermarkets and hypermarkets stock frozen bread rolls and paratha for home baking, with China's SAMR labeling rules forcing reformulation and cleaner ingredient decks.
- Catering:Event and institutional catering relies on fully baked frozen formats for operational simplicity.
- Bakeries:Traditional bakeries with in-house ovens represent a shrinking niche for frozen dough inputs.
Volume leadership rests with Retail. Margin expansion is concentrated in Foodservice.
Distribution Channel:
Cold-chain integrity requirements and last-mile economics shape channel viability across APMEA's fragmented infrastructure.
- Supermarkets:Temperature-controlled retail cabinets in urban India and Southeast Asian capitals anchor frozen bread and pastry volumes. FSSAI cold-chain documentation requirements extend certification timelines for new entrants.
- Wholesalers:Broadline distributors serve foodservice accounts with pallet-scale frozen bakery procurement, consolidating fragmented bakery supply into centralized hubs.
- Online:Direct-to-consumer frozen pastry delivery is emerging in tier-1 Indian cities and Australian metropolitan areas, constrained by last-mile refrigeration gaps.
- Convenience Stores:Limited frozen cabinet space restricts assortment to high-velocity bread rolls in Japan and South Korea.
Established volume flows through Supermarkets. Emerging penetration is concentrated in Online.
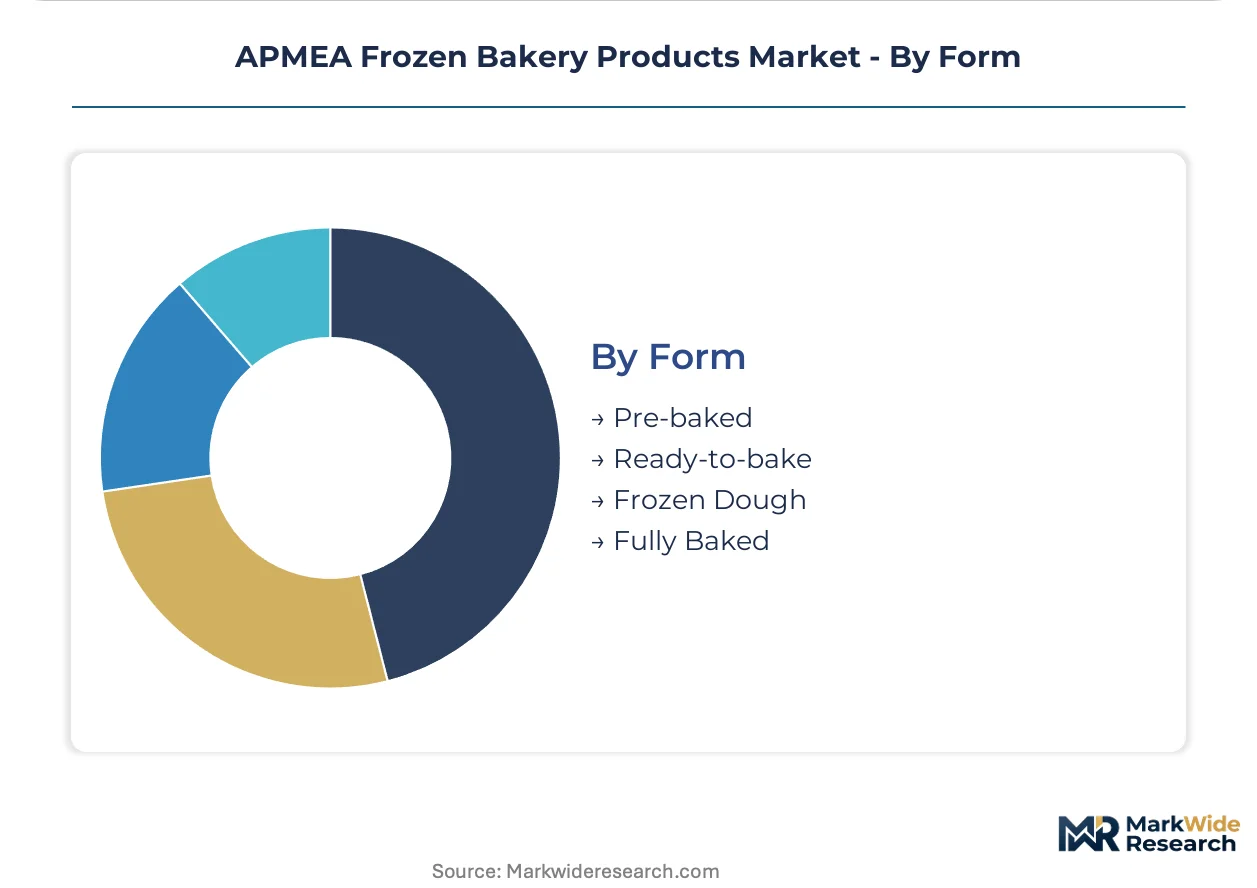
Form:
Processing stage at freezing determines labor substitution potential and end-user capital requirements.
- Ready-to-bake:Par-cooked croissants, paratha, and rolls requiring only oven finish are gaining share fastest among cloud kitchens and QSR chains seeking minimal-prep flexibility. India's urban corridors show particular pull for this format.
- Frozen Dough:Unbaked laminated and yeasted dough blocks serve traditional bakeries with skilled labor and in-house ovens, a contracting segment as central production displaces artisan operations.
- Pre-baked:Partially baked products for final oven crisping occupy middle ground between convenience and quality perception.
- Fully Baked:Thaw-and-serve cakes and bread dominate catering and institutional channels where on-site baking capacity is absent.
Operational simplicity favors Fully Baked. Growth investment is concentrating in Ready-to-bake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali Free Zone anchors frozen bakery distribution across the Middle East, with blast-freezing infrastructure serving luxury hotel chains from centralized hubs.
China
Shanghai's cloud kitchen corridor drives ready-to-bake paratha and croissant procurement at scale. SAMR enforces GB standards on microbial limits and net-content labeling that force 12-18 month reformulation timelines for frozen bread exporters. Yangtze River Delta cold-chain hubs are consolidating national distribution away from fragmented provincial wholesalers.
India
Mumbai and Delhi-NCR cloud kitchens are displacing traditional wholesale bakery distributors through direct frozen pastry contracts. FSSAI mandates additive disclosures and cold-chain integrity documentation that extend import certification timelines for new entrants. Gujarat's industrial belt is attracting domestic frozen dough manufacturing investment to bypass import complexity.
Vietnam
Ho Chi Minh City's cafe culture and hotel construction pipeline create underpenetrated white space for premium frozen pastry supply. The country's national food safety regulator enforces evolving cold-chain standards that favor compliant international suppliers over informal traders. Da Nang's central logistics position is emerging as a transshipment node for frozen bakery products serving Indochina.
Australia
Sydney and Melbourne foodservice chains are consolidating procurement around single-source frozen bakery contracts with outcome-based quality guarantees. FSANZ joint standards with New Zealand's MPI create a harmonized regulatory zone simplifying multi-market product registration. Queensland's renewable-powered cold storage facilities are capturing early-mover advantage under emerging carbon-accounting rules for refrigeration.
United Arab Emirates
Dubai's luxury hotel and airline catering sectors demand laminated dough products with quality benchmarks approaching artisan same-day alternatives. MOHAP enforces strict cold-chain documentation for frozen food imports that filters out non-compliant suppliers. Jebel Ali's free zone infrastructure enables re-export routing to Saudi Arabia and African markets with minimal regulatory friction.
APMEA Frozen Bakery Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and distribution radius capabilities. Europastry anchors the premium tier through specialized laminated dough capacity feeding luxury hotel channels, while Grupo Bimbo dominates mass-market bread across retail and QSR procurement. Three archetypes populate the competitive set: Southern European laminated dough specialists, Latin American-origin mass-market bakers with Asian retail extension, and diversified FMCG conglomerates leveraging brand equity in ready-to-bake formats. Consolidation is accelerating through foodservice contract centralization and cold-chain infrastructure partnerships.
Among diversified conglomerates, Associated British Foods and Nestlé occupy positions exemplifying brand-strength competition in retail-facing ready-to-bake segments. Unilever sits within the same tier, representing FMCG distribution leverage rather than bakery-specific technical capability. These three anchors demonstrate how non-specialist players compete through channel access and marketing scale rather than laminated dough expertise.
| Leading Market Players |
|---|
| Associated British Foods |
| Europastry |
| Nestlé |
| Unilever |
| Kellogg Company |
| Grupo Bimbo |
| Aryzta AG |
| Mondelēz International |
| General Mills |
| Others |
Pricing and Supply Chain Analysis
Blast-freezing systems with integrated humidity control are compressing the quality-cost tradeoff in laminated dough production, simultaneously raising capital barriers for new entrants and concentrating margin capture among Southern European specialists with installed capacity. This technology shift feeds directly into pricing power asymmetries between premium hotel-channel suppliers and commodity bread-roll producers serving India's retail corridors.
Pricing Analysis
Outcome-based pricing tied to finished-product yield and consistency metrics anchors contract structures for luxury hotel and airline catering accounts. Pricing stratifies across premium artisan, standard industrial, and economy private-label tiers, with differentiation driven by laminated dough complexity and cold-chain certification grade. Cost compression in the economy tier is intensifying because wheat flour volatility and fixed-price QSR contracts squeeze processor margins. Cloud kitchen operators in India show highest price sensitivity, while Dubai's luxury hotel procurement teams prioritize quality guarantees over unit cost.
Supply Chain Analysis
India's FSSAI additive disclosure mandates and cold-chain integrity documentation are reshaping sourcing patterns for frozen imports, pushing exporters toward local production partnerships. Supply concentration rests on Southern Europe for laminated dough expertise, China for modified starch and emulsifier inputs, and India's Gujarat industrial belt for emerging domestic capacity. Wheat flour and specialized freezing equipment draw from geographically dispersed sources, creating tariff exposure on European machinery imports. Distribution runs through Jebel Ali's free-zone hubs for Middle East re-export and Yangtze River Delta cold-chain nodes for China national coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APMEA frozen bakery market is becoming a vertical-integration race, with players pursuing captive supply of laminated dough capacity to lock in hotel-channel margins and escape commodity bread pricing traps.
For Market Incumbents: Anticipate margin compression in India's retail bread segment as domestic processors expand Gujarat-based capacity and bypass import documentation delays. Secure backward integration into modified starch and emulsifier formulation to reduce input cost volatility exposure. Defend premium positioning through exclusive blast-freezing technology partnerships with Singapore and Dubai hotel chains, creating switching costs that commodity competitors cannot replicate.
For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated cafe and hotel construction pipeline, where premium frozen pastry supply remains concentrated among informal traders lacking cold-chain compliance. Target Da Nang's emerging logistics position for Indochina transshipment rather than competing directly in saturated Bangkok channels. Lead with ready-to-bake croissant and paratha formats tailored to cloud kitchen operational constraints, bypassing the frozen dough niche where traditional bakeries are contracting.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Latin American-origin mass-market bakers seeking Asian retail extension, or FMCG conglomerates building ready-to-bake brand portfolios. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than formulation capability alone. Watch for India's FSSAI enforcement intensity as the inflection signal separating compliant premium suppliers from commodity players facing extended certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Capacity Expansion | Captures premium hotel-channel contracts in Dubai and Singapore through quality parity with artisan alternatives. |
| Backward Integration into Emulsifier Supply | Reduces reformulation cost exposure under China's SAMR microbial limit enforcement. |
| Direct Cloud Kitchen Supply Agreements | Bypasses fragmented wholesale distributors in India's Mumbai and Delhi-NCR corridors. |
| Renewable-Powered Cold Storage Certification | Creates differentiation under emerging carbon-accounting rules for refrigeration emissions tracking. |
| Local Production Partnership in Gujarat | Shortens FSSAI certification timelines and shields against import documentation delays. |
Research Methodology
Document review covered frozen food trade databases, FSSAI and SAMR regulatory filings, and hotel foodservice procurement records, complemented by interviews with plant managers at laminated dough processors, procurement leads at Dubai luxury hotel chains, cold-chain logistics operators across South Asia, and technical R&D directors at emulsifier suppliers. Secondary validation drew from customs import records, airline catering contract announcements, and cloud kitchen operator expansion disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-user channel, and regional demand clusters.
Segment-level projections incorporate formulation complexity tiers, freeze-thaw stability requirements, and regulatory compliance cost differentials across the analysis window. The analytical framework models bread, pastry, cake, and pie categories against foodservice, retail, catering, and bakery end-use channels, with distribution channel and form-factor cross-segmentation. CAGRs derive from trend extrapolation of cloud kitchen proliferation rates, SAMR enforcement intensity, and cold-chain infrastructure investment pipelines, with scenario weighting for wheat price volatility and carbon-accounting rule adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FSSAI documentation requirement changes or sustained wheat price spikes beyond historical bands. The analysis reflects documented assumptions regarding technology adoption curves and regulatory enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Pastries Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Baked Foods Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Bakery Premixes Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Healthy Biscuits Market