
 Dredging Market | 2026-2036
Dredging Market Size, Share, and Industry Trends Forecast 2026-2036
Dredging Market Intelligence
The EU Green Deal's sediment quality directives is repositioning contractor priorities across European waterways, requiring advanced environmental dredging capabilities that limit turbidity and contaminant release. Royal Boskalis Westminster leverages its fleet scale to anchor large-scale port deepening contracts across multiple continents. DEME Group specializes in integrated dredging and land reclamation solutions that compete for complex coastal infrastructure packages. Jan De Nul Group extends its positioning through technology leadership in precision dredging systems for sensitive marine environments.
Dredging encompasses the underwater excavation of sediments, soils, and rock from harbors, rivers, and seabeds using specialized vessels equipped with cutter heads, suction pumps, or mechanical grabs, typically operating at depths ranging from several meters to over 50 meters depending on project scope. The primary industrial purpose centers on maintaining navigable waterways, expanding port capacity, reclaiming land for coastal development, and remediating contaminated sediments to restore aquatic ecosystems. Cutter suction dredgers dominate capital-intensive new-build projects where hard-packed soils demand high-powered cutting forces, while trailing suction hopper dredgers capture expanding share in maintenance dredging cycles that require efficient sediment transport over longer distances. Environmental dredging represents the fastest-growing method segment as regulatory thresholds for contaminant release tighten across jurisdictions, concentrating margin pools with contractors possessing advanced treatment and disposal capabilities.
The US Army Corps of Engineers maintains stringent dredged material management protocols under EPA oversight, shaping project specifications and disposal site access across American waterways. China's Ministry of Ecology and Environment enforces marine environmental impact assessments that filter market entry for foreign dredging contractors operating in domestic waters. The International Maritime Organization's conventions on ballast water and anti-fouling systems further constrain vessel equipment standards for cross-border project deployment. Stakeholders must monitor how evolving carbon accounting frameworks for marine construction equipment reshape fleet investment priorities and contract bidding strategies.
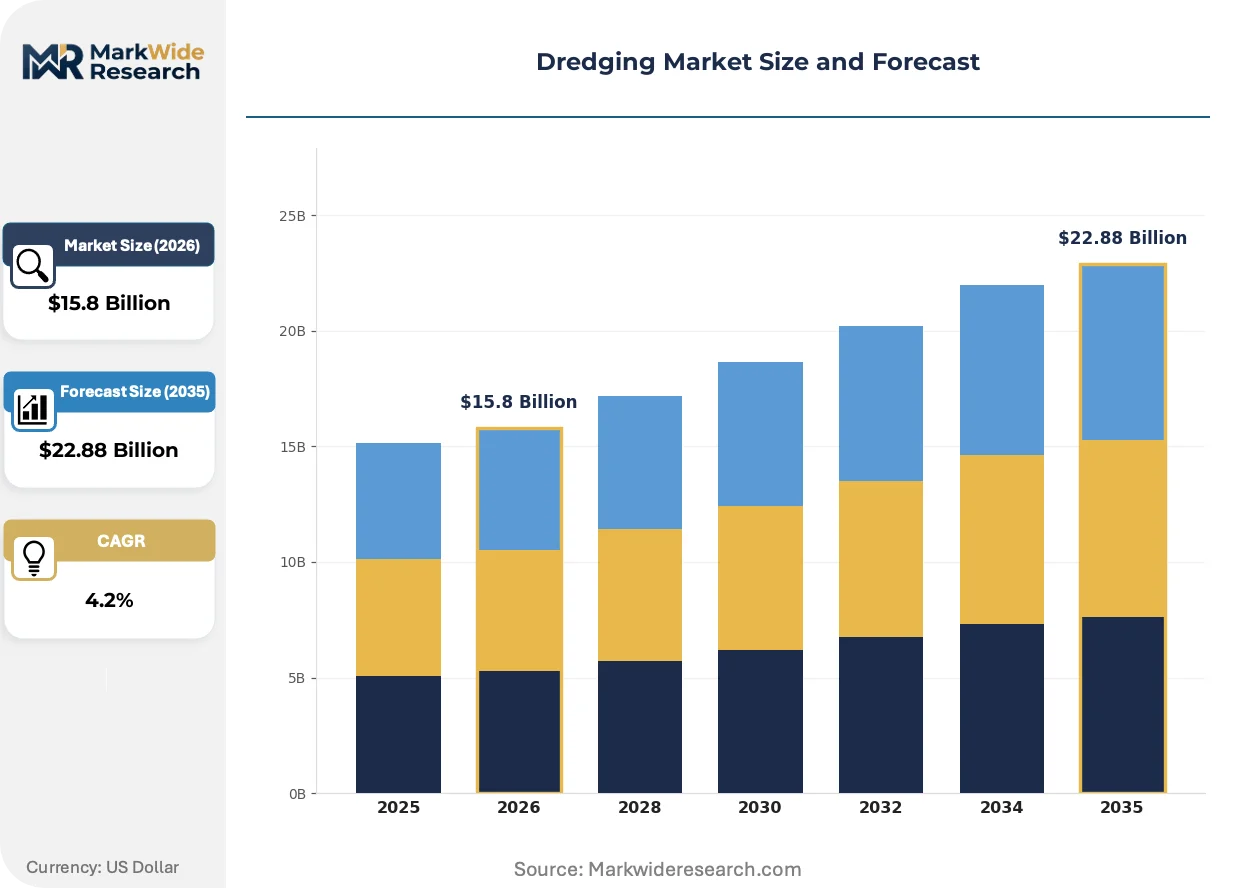
Market Dynamics
Environmental compliance mandates are restructuring contractor capabilities across all major dredging jurisdictions, forcing capital redeployment toward precision turbidity control and real-time sediment monitoring systems that satisfy tightening discharge thresholds.
Growth Catalysts
- EU Green Deal sediment directives:Contractors must deploy low-turbidity dredging methods and onboard treatment systems to meet contaminant release limits, creating specialized equipment demand across European waterways.
- Southeast Asian port deepening:Maritime trade volume expansion through Singapore, Indonesia, and Vietnam is absorbing larger cutter suction dredger fleets for channel maintenance and capacity upgrades.
- Autonomous dredge positioning:Dynamic positioning systems with sub-meter accuracy are reducing operational downtime and enabling work in restricted shipping lanes previously deemed inaccessible.
Market Restraints
- Specialized steel and high-grade alloys:Cutter head fabrication and hull construction depend on alloy inputs subject to volatile commodity pricing and concentrated supplier bases in East Asian foundries.
- Ballast water treatment mandates:International Maritime Organization conventions require expensive retrofits to existing fleets, extending vessel dry-dock periods and compressing available operating days.
- Disposal site scarcity:Contaminated sediment placement faces community opposition and regulatory denial across densely populated coastal corridors in Japan and Western Europe.
Strategic Opportunities
- Carbon-neutral dredging propulsion:Battery-electric and hydrogen fuel cell powertrains offer compliance pathway with emerging maritime decarbonization frameworks in the European Union and California.
- Subsea cable route preparation:Offshore wind interconnectors and transoceanic data cables require precision seabed conditioning in markets with limited established contractor presence.
- Beneficial use certification:EPA and state-level environmental agencies are streamlining approval pathways for dredged material in coastal restoration and engineered fill applications.
Industry Challenges
- Marine hydrographic survey expertise:Precision bathymetric mapping and sediment characterization require specialized sonar technicians whose training pipelines lag fleet expansion schedules.
- Multi-jurisdictional permitting:Cross-border projects spanning international waters and overlapping exclusive economic zones confront conflicting national environmental assessment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dredging Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $22.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Cutter Suction Dredger, Trailing Suction Hopper, Backhoe Dredger, Clamshell Dredger, Water Injection Dredger Application: Port Construction, Land Reclamation, Waterway Maintenance, Shoreline Protection, Environmental Remediation Dredging Method: Mechanical Dredging, Hydraulic Dredging, Pneumatic Dredging, Environmental Dredging, Suction Dredging End User: Marine Contractors, Government Agencies, Infrastructure Developers, Environmental Consultants |
| Companies Covered | CCCC Shanghai Dredging, Royal Boskalis Westminster, Great Lakes Dredge & Dock Corporation, The Dutra Group, National Marine Dredging Company, Van Oord, Jan De Nul Group, Penta-Ocean Construction, DEME Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dredging Market Strategic Shifts & Innovations
Digital twin integration and real-time environmental monitoring are compressing project timelines while expanding the feasible operating envelope for sensitive marine construction. These capabilities are becoming baseline requirements rather than competitive differentiators.
Automated cutter suction control systems are unifying hydraulic power management with sediment density feedback loops to optimize production rates. Port authorities in the Netherlands and Belgium are mandating these installations for contracts in ecologically sensitive estuaries. The technology is compressing the performance gap between experienced operator crews and newer market entrants.
The EPA's dredged material management protocols under the Marine Protection, Research and Sanctuaries Act are tightening disposal site monitoring requirements. Contractors must now demonstrate long-term containment integrity through decades-long institutional controls. Maintenance dredging cycles in US harbors are extending as disposal alternatives face community opposition and regulatory scrutiny.
Performance-based contracting is displacing traditional unit-rate agreements in European port maintenance programs. Authorities in Rotterdam and Hamburg now compensate contractors based on achieved channel depth retention over multi-year periods rather than cubic meters removed. This shift concentrates contract awards with operators possessing predictive maintenance algorithms and fleet reliability data.
Dredging Market Segmentation
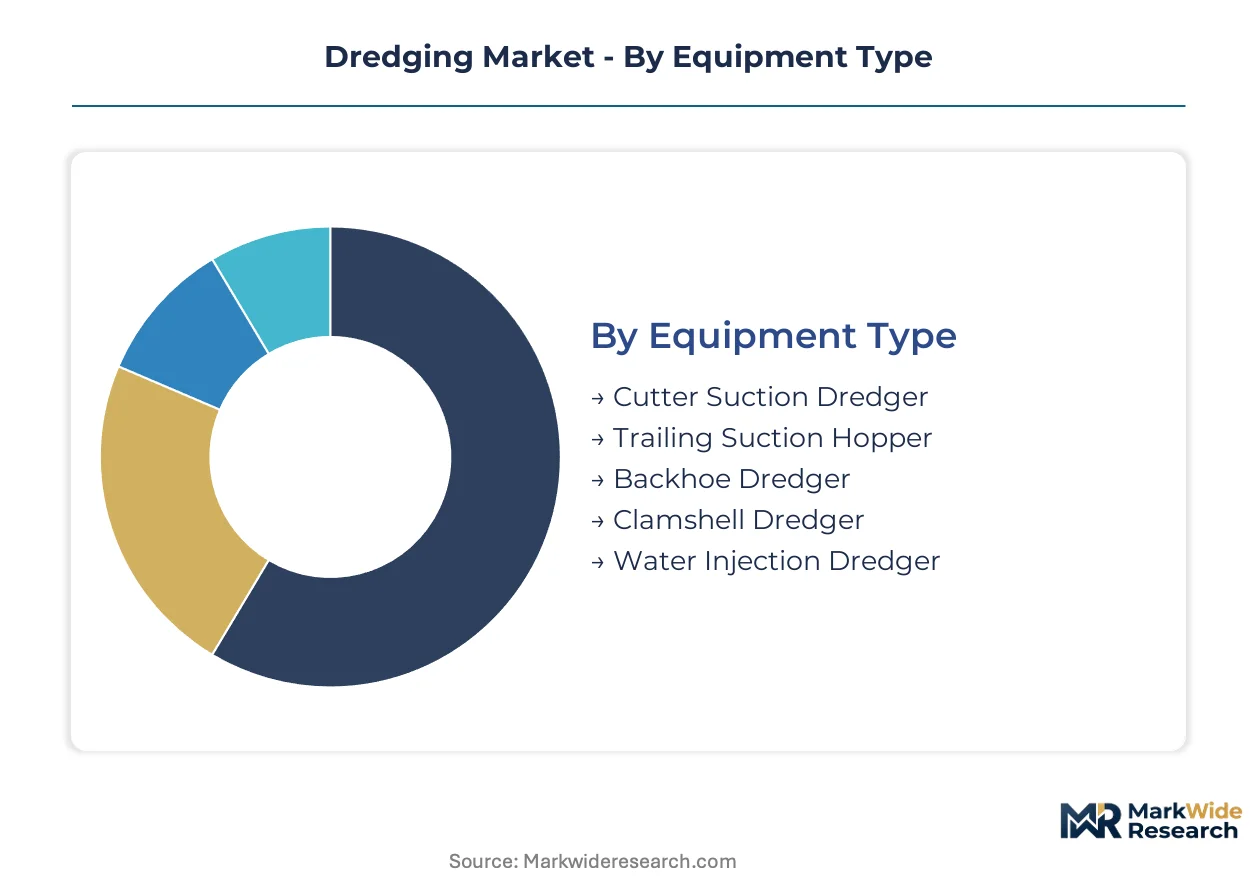
Dredging equipment and service configurations fragment sharply across project scale, sediment hardness, and regulatory stringency. Contractors configure fleet composition to match specific contract profiles rather than deploying universal platforms. Understanding these segment boundaries clarifies where capital investment concentrates and which capability gaps create competitive vulnerability.
Equipment Type:
Volume-driven port maintenance contracts favor hopper vessels with long-distance transport economics, while premium new-build infrastructure demands cutter suction platforms with high-powered cutting forces for compacted soils.
- Cutter Suction Dredger:Rotating cutter heads disaggregate rock and hard-packed sediments before hydraulic suction transport through floating pipelines. China's state-backed land reclamation programs sustain multi-year deployment contracts for these capital-intensive units. EU Green Deal turbidity mandates are forcing precision control retrofits that elevate operating costs.
- Trailing Suction Hopper Dredger:Self-propelled vessels with drag arms extract loose sediments into onboard hoppers for offshore disposal or beach nourishment. Southeast Asian port deepening cycles absorb expanding fleet capacity as maritime trade volumes rise through Singapore and Vietnam. Autonomous positioning systems are reducing crew requirements for repetitive maintenance channels.
- Backhoe Dredger:Excavator-based platforms operate from anchored barges for confined waterway work.
- Clamshell Dredger:Mechanical grab systems handle discrete debris removal and wharf foundation excavation.
- Water Injection Dredger:Fluidized sediment dispersal suits shallow maintenance without material removal.
Today's leader: Trailing Suction Hopper Dredger. Tomorrow's challenger: Cutter Suction Dredger.
Application:
Land reclamation commands premium day-rates due to multi-year project horizons and integrated engineering requirements, while waterway maintenance operates on compressed margins and cyclical demand.
- Port Construction:Channel deepening and berth excavation demand heavy-duty cutter suction fleets operating at depths exceeding 25 meters. Indonesia's new capital development and Vietnam's container terminal expansion sustain equipment utilization. Environmental impact assessments under China's MEE filter contractor eligibility for sensitive marine zones.
- Land Reclamation:Integrated dredging-fill operations convert marine sediments into industrial zones and coastal infrastructure. Rotterdam and Hamburg authorities now specify performance-based contracts tied to achieved fill density rather than cubic meters pumped. Precision placement requirements concentrate awards with contractors possessing real-time density monitoring.
- Waterway Maintenance:Recurrent sediment removal preserves navigable depths in rivers and harbors.
- Shoreline Protection:Beach nourishment and coastal defense structures utilize hopper-dredged sand.
- Environmental Remediation:Contaminated sediment extraction requires onboard treatment and secure disposal.
Land reclamation captures the steepest expansion trajectory as coastal urbanization accelerates. Waterway maintenance faces margin compression from extended disposal timelines.
Dredging Method:
Mechanical and hydraulic approaches dominate mature markets, while environmental methods gain regulatory-mandated share in jurisdictions with strict contaminant release protocols.
- Mechanical Dredging:Clamshell buckets and backhoes extract discrete material loads for precise placement control. Japan's densely populated coastal corridors rely on mechanical methods where turbidity restrictions prohibit hydraulic dispersion. Disposal site scarcity extends project timelines and elevates transport costs.
- Hydraulic Dredging:Pump-driven sediment slurry transport enables continuous high-volume production rates. Cutter suction and trailing suction hopper platforms dominate capital project deployment. EU Green Deal sediment quality directives are forcing closed-loop systems that recirculate process water.
- Pneumatic Dredging:Compressed air fluidization suits specialized salvage and archaeological recovery.
- Environmental Dredging:Precision extraction with real-time contaminant monitoring and onboard treatment. EPA dredged material management protocols under the Marine Protection, Research and Sanctuaries Act mandate long-term containment verification.
- Suction Dredging:Vacuum-based systems handle loose sediments in shallow water maintenance.
Hydraulic methods anchor current fleet investment. Environmental dredging is gaining share fastest as regulatory thresholds tighten across North American and European waterways.
End User:
Marine contractors internalize equipment risk and crew expertise, while government agencies outsource project execution through design-build and maintenance concession structures.
- Marine Contractors:Royal Boskalis Westminster and DEME Group deploy owned fleets across multi-continent project portfolios. Capital intensity creates barriers to entry that concentrate market share with established operators. Carbon accounting frameworks are reshaping fleet renewal priorities toward alternative propulsion.
- Government Agencies:The US Army Corps of Engineers maintains federal waterway specifications under EPA oversight. China's Ministry of Transport directs state-owned contractors for strategic infrastructure. Procurement patterns favor long-term framework agreements over discrete tender competitions.
- Infrastructure Developers:Private port operators and coastal real estate developers contract specialized reclamation services.
- Environmental Consultants:Remediation specialists subcontract precision extraction for contaminated site restoration.
Marine contractors dominate capital deployment. Government agencies are consolidating procurement into fewer, larger framework contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern dredging operations trace their industrial lineage to Dutch hydraulic engineering innovations of the 19th century, when steam-powered suction systems first enabled systematic seabed excavation for port development. Contemporary demand concentrates in coastal economies where maritime trade expansion and land scarcity converge.
China
State-backed land reclamation for industrial zones and coastal infrastructure sustains multi-year vessel deployment contracts through the Ministry of Transport's strategic procurement frameworks. The Ministry of Ecology and Environment enforces marine environmental impact assessments that filter market entry for foreign contractors operating in domestic waters. Yangtze River Delta port clusters absorb the largest cutter suction dredger fleets for channel deepening and berth construction.
United States
The US Army Corps of Engineers maintains federal waterway maintenance cycles that preserve navigable depths across commercial harbors and inland river systems. EPA oversight under the Marine Protection, Research and Sanctuaries Act shapes dredged material management protocols and disposal site access. Gulf Coast petrochemical corridor expansion drives demand for precision dredging in restricted shipping lanes.
Netherlands
Rotterdam and Amsterdam port authorities pioneered performance-based contracting structures that compensate operators based on achieved channel depth retention rather than cubic meters removed. EU Green Deal sediment quality directives mandate low-turbidity methods and onboard treatment systems across European waterways. Dutch contractors anchor large-scale port deepening contracts across multiple continents through integrated engineering capabilities.
Belgium
Antwerp port maintenance programs now require automated cutter suction control systems for contracts in ecologically sensitive estuaries. The country's national environmental regulator enforces turbidity thresholds that elevate operating costs for precision dredging deployments. Flemish coastal defense and beach nourishment cycles sustain trailing suction hopper dredger utilization.
Japan
Densely populated coastal corridors rely on mechanical dredging methods where turbidity restrictions prohibit hydraulic dispersion in confined waterways. METI coordinates industrial port expansion with stringent sediment quality protocols. Tokyo Bay and Osaka Bay industrial zones face disposal site scarcity that extends project timelines and elevates transport costs.
Dredging Market Key Industry Players
Capital-heavy fleet owners compete with specialized engineering consortia that charter equipment rather than owning vessels outright. The market structure concentrates around a tier of integrated marine contractors possessing owned dredging assets, supported by regional operators serving discrete geographic markets. Three archetypes dominate: scale-driven global fleet operators, precision specialists in environmentally sensitive marine construction, and national champions aligned with state-backed infrastructure programs. Competitive dynamics center on long-term framework contract capture and carbon-neutral propulsion retrofits that satisfy emerging maritime decarbonization mandates.
Among European-integrated contractors, Royal Boskalis Westminster and DEME Group exemplify the scale-driven archetype through multi-continent project portfolios. Van Oord occupies a position within the precision specialist tier. Chinese state-linked operators including CCCC Shanghai Dredging anchor the national champion segment. US-based Great Lakes Dredge & Dock Corporation represents the regional fleet operator model serving federal waterway programs. Jan De Nul Group sits within the technology-forward tier emphasizing environmental compliance capabilities.
| Leading Market Players |
|---|
| CCCC Shanghai Dredging |
| Royal Boskalis Westminster |
| Great Lakes Dredge & Dock Corporation |
| The Dutra Group |
| National Marine Dredging Company |
| Van Oord |
| Jan De Nul Group |
| Penta-Ocean Construction |
| DEME Group |
| Others |
Cost & Logistics Intelligence
Specialized steel and high-grade alloys for cutter head fabrication flow from East Asian foundries through three distinct pricing tiers downstream. Premium cutter suction dredger contracts absorb elevated alloy costs through multi-year deployment agreements with state-backed land reclamation programs, while maintenance dredging operators face compressed margins when volatile commodity pricing coincides with cyclical demand troughs.
Pricing Analysis
Project-based day-rate contracting dominates fleet deployment, with pricing stratifying across premium, standard, and economy tiers based on vessel capability and environmental compliance certification. Premium tier operators command rates anchored by EU Green Deal turbidity compliance and precision dredging technology, while economy tier competitors compete on unit-rate maintenance contracts with minimal environmental controls. Cost compression in standard-tier maintenance dredging is intensifying as disposal site scarcity extends project timelines and elevates transport costs. Government agencies exhibit lowest price sensitivity due to federal waterway mandates, while private infrastructure developers negotiate aggressively on land reclamation packages.
Supply Chain Analysis
Regional equipment distribution centers in the Netherlands, China, and South Korea anchor hub-and-spoke patterns for cutter head components and dredging pumps. Manufacturing concentrates in China for hull fabrication, Germany for precision hydraulic systems, and Japan for specialized marine alloys. Raw material dependencies draw from nickel-chromium-molybdenum alloys for cutter teeth, high-tensile steel for hull construction, and marine-grade coatings for corrosion protection. Single-source vulnerability runs through concentrated East Asian foundry capacity for specialized alloys. Distribution runs through manufacturer-direct channels for capital equipment and regional service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contractors can arbitrage regulatory stringency gaps between EU Green Deal jurisdictions and Southeast Asian enforcement regimes, capturing margin premiums where environmental compliance capabilities transfer across geographies with differential sediment quality mandates.
For Market Incumbents: Acquire autonomous dredge positioning technology assets to defend against emerging technology specialists threatening premium channel contracts. Royal Boskalis Westminster and DEME Group should deepen backward integration into precision cutter head manufacturing to secure alloy supply continuity against East Asian foundry concentration risk. Incumbents must secure long-term framework agreements with Rotterdam and Hamburg port authorities before performance-based contracting spreads to Asian markets. For New Entrants and Emerging Players: The premium-economy pricing gap in environmental dredging services creates entry opportunity for specialized treatment technology providers. New entrants should target US Gulf Coast petrochemical corridor expansion where EPA oversight creates compliance capability shortages and limited established contractor presence. A go-to-market angle emphasizing carbon-neutral propulsion retrofits addresses emerging maritime decarbonization mandates in California and European Union jurisdictions. For Investors and Strategic Acquirers: Consolidation pressure builds where environmental compliance capital requirements exceed standalone operator balance sheet capacity. The five-to-ten year viability window favors acquisition targets possessing integrated land reclamation engineering capabilities and established disposal site access. Watch carbon accounting framework implementation timelines as the inflection indicator for fleet renewal investment cycles and contract bidding strategy shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Propulsion Retrofit | Battery-electric and hydrogen fuel cell powertrains satisfy EU maritime decarbonization frameworks and California emissions mandates. |
| Precision Turbidity Control System Deployment | Real-time sediment monitoring capabilities secure contracts under Rotterdam and Hamburg performance-based channel depth retention programs. |
| Beneficial Use Certification Investment | EPA streamlined approval pathways for dredged material in coastal restoration expand addressable project scopes beyond disposal-limited maintenance cycles. |
| Subsea Cable Route Preparation Capability | Offshore wind interconnector and transoceanic data cable seabed conditioning accesses markets with limited established contractor presence. |
| Multi-Jurisdictional Permitting Expertise | Cross-border project execution capabilities spanning international waters and overlapping exclusive economic zones differentiate bid competitiveness. |
Research Approach
Coverage spans China, the United States, the Netherlands, Belgium, and Japan, with primary inputs from each market's dredging contractors and port authorities. The study combines structured interviews with fleet operations managers, port authority procurement officers, marine environmental regulators, and hydrographic survey technicians with secondary validation from customs trade data, SEC filings for publicly traded contractors, US Army Corps of Engineers dredging schedules, and EU Green Deal implementation documentation. Bottom-up vessel deployment tallies triangulate against top-down infrastructure investment forecasts.
Granularity-level modeling distinguishes equipment type deployment by project scale and sediment hardness, application segments by contract duration and regulatory stringency, and end-user categories by procurement structure and risk allocation. CAGRs derive from equipment utilization rates, fleet renewal schedules, and port expansion timelines across the projection horizon. Industry-specific forecast inputs include maritime trade volume projections through Singapore and Vietnam, and EU sediment quality directive implementation phases.
The model assumes a particular technology adoption path for autonomous dredge positioning and environmental monitoring systems; alternative pathways for battery-electric propulsion commercialization would alter the outlook for carbon-neutral fleet investment cycles. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, alloy price volatility bands, and disposal site approval timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market