
 Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market | 2026-2036
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market Insights
High-recovery membrane specifications are redrawing competitive benchmarks for mobile SWRO systems in Saudi Arabia. Veolia Environnement SA leverages its global desalination engineering base to anchor large-scale containerized projects across the Kingdom's coastal zones. Metito Saudi Arabia competes through localized manufacturing and after-sales service networks. Energy Recovery specializes in energy-efficient pressure exchanger technology that differentiates its offerings for power-constrained remote installations.
Mobile sea water reverse osmosis treatment plants are self-contained desalination systems engineered around semi-permeable polyamide thin-film composite membranes operating at pressures typically between 55 and 85 bar, designed to produce potable or industrial-grade water from saline feed sources without permanent civil infrastructure. Containerized systems dominate current procurement volumes due to their plug-and-deploy architecture suited to Saudi Arabia's remote oilfield and construction camp requirements. Skid-mounted systems capture expanding interest from industrial manufacturers seeking flexible capacity additions without long-term capital commitment. The oil and gas end-user segment leads absolute demand, though municipalities represent the fastest-growing category as the Kingdom decentralizes water supply resilience.
SFDA drinking water quality standards, SASO technical regulations for electrical safety, and MEWA environmental discharge permits collectively shape product certification requirements and operational compliance burdens for mobile SWRO suppliers. These frameworks elevate barriers for non-compliant imports while creating preferential market access for vendors with established Saudi testing and certification relationships. Stakeholders must monitor regulatory alignment between national water security strategies and evolving membrane efficiency standards to anticipate procurement specification shifts.
Market Dynamics
Saudi Vision 2030 water security mandates are compressing deployment timelines for modular desalination assets, forcing suppliers to accelerate factory acceptance testing and on-site commissioning protocols. The structural pressure from national self-sufficiency targets is reshaping how mobile SWRO systems are procured, financed, and operated across the Kingdom's coastal industrial zones.
Growth Catalysts
- Saudi Vision 2030 Water Security Mandates:National targets for desalination capacity expansion are accelerating procurement cycles for containerized SWRO units across Eastern Province oilfields.
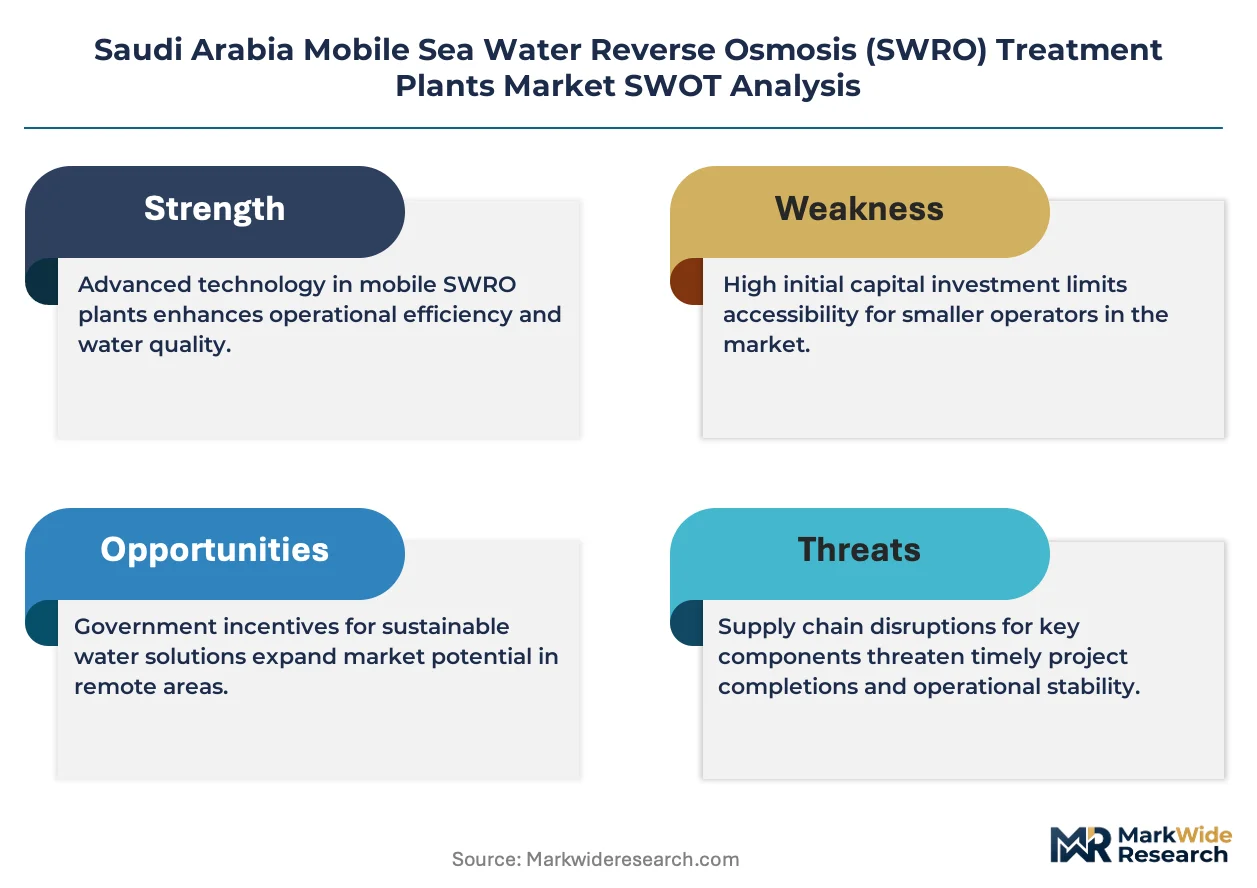
- High-Recovery Membrane Specifications:Advances in polyamide thin-film composite membranes operating above 60 bar are reducing energy intensity for remote installations.
- Eastern Province Industrial Corridor Concentration:Dense clustering of Aramco operations from Jubail to Dhahran generates concentrated demand for rapid-deployment water treatment.
Market Restraints
- Specialized Alloy Input Volatility:Duplex stainless steel and super-duplex piping costs fluctuate with nickel and molybdenum commodity markets, squeezing fabrication margins.
- SFDA Certification Complexity:Saudi Food and Drug Authority drinking water quality standards require extensive local testing protocols that extend market entry timelines for non-established suppliers.
- Skid-Mounted System Substitution:Permanent skid-mounted installations with lower lifecycle costs threaten mobile containerized units in semi-permanent camp applications.
Strategic Opportunities
- Red Sea Coastal Development:NEOM and Amaala megaprojects are generating demand for modular desalination at construction sites lacking grid infrastructure.
- Pressure Exchanger-Energy Recovery Convergence:Integration of isobaric energy recovery devices with high-pressure pumps is opening power-constrained remote markets previously inaccessible to conventional SWRO.
- SASO Electrical Safety Fast-Track:Pre-certified containerized systems meeting Saudi Standards, Metrology and Quality Organization technical regulations gain preferential access to municipal procurement channels.
Industry Challenges
- Commissioning Engineer Scarcity:Shortage of technicians certified for high-pressure membrane operation and saline corrosion management delays field deployment.
- MEWA Discharge Permit Timelines:Ministry of Environment, Water and Agriculture environmental discharge approvals create operational uncertainty for brine management planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market |
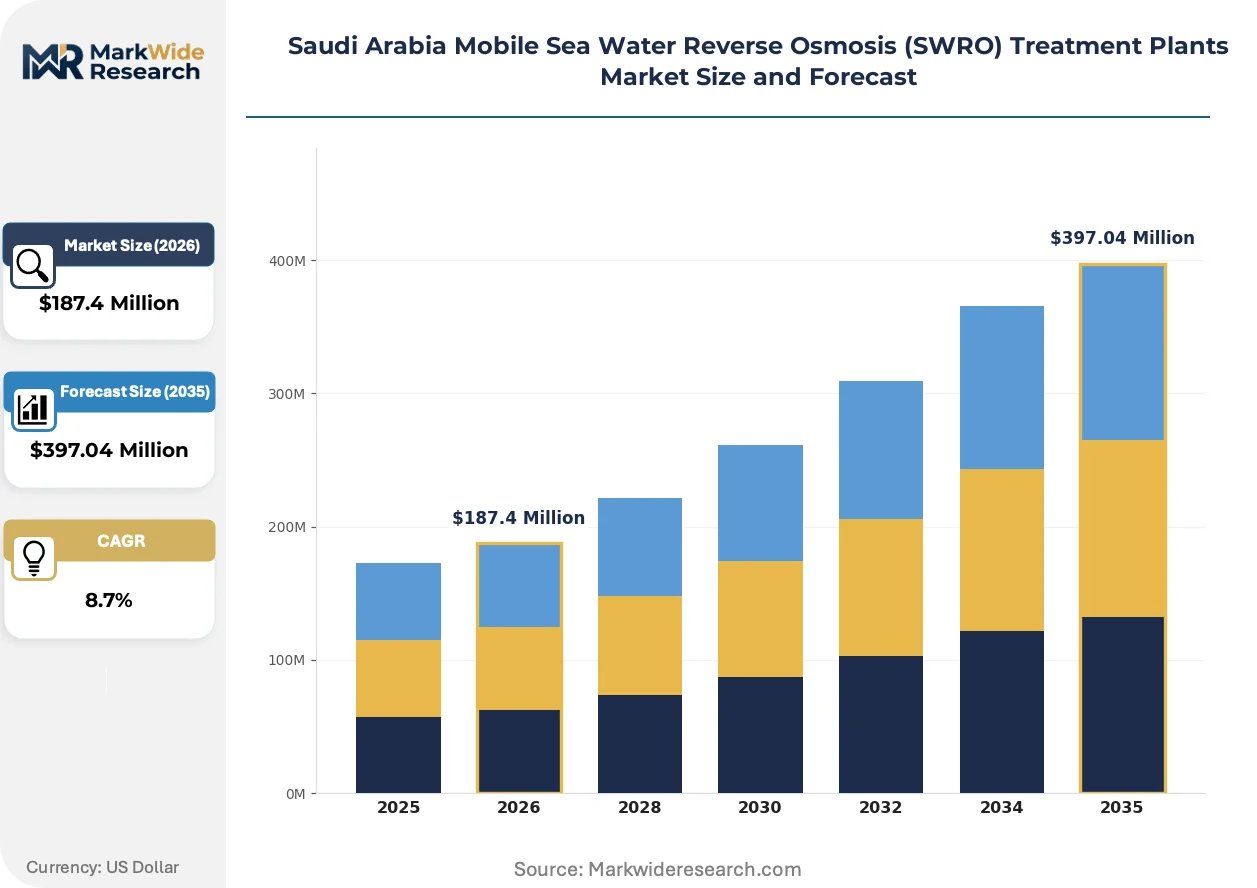
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containerized Systems, Skid-Mounted Systems, Modular Units, Portable Desalination End User: Municipalities, Industrial Manufacturers, Oil & Gas Sector, Agriculture Installation Type: Onshore, Offshore, Mobile Units, Stationary Systems Technology: Reverse Osmosis, Ultra-Filtration, Nano-Filtration, Electrodialysis |
| Companies Covered | National Shipping Company of Saudi Arabia SJSC (Bahri), Veolia Environnement SA, Get Water Co Ltd, Meft International Company, Al Kafaah LLC, Metito Saudi Arabia, Saudi Arabian Amiantit Company, ACCIONA Agua, Energy Recovery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market Trends and Innovations
Containerized architecture is decomposing traditional civil-works-bound desalination economics, enabling water production at points previously unreachable by permanent infrastructure. Three intersecting forces are compressing deployment cycles and reshaping supplier capabilities.
Isobaric energy recovery technology is decomposing the capital cost barrier for off-grid SWRO installations. Oil and gas operators across the Arabian Gulf coast are specifying pressure-exchanger-integrated containerized units for wellpad and flare-gas recovery sites. The technology is decomposing the historical trade-off between mobility and energy efficiency that constrained remote deployment.
SFDA membrane certification requirements are tightening feedwater quality monitoring and finished water testing protocols for mobile systems. Suppliers must now demonstrate continuous compliance with Saudi drinking water standards across variable saline feed conditions. Industrial end-users in the Eastern Province are responding by demanding factory-integrated instrumentation packages that streamline regulatory submission.
Lease-to-own financing structures are displacing outright purchase models for municipal and industrial buyers seeking operational expenditure treatment. Equipment lessors are capturing share from traditional EPC contractors by bundling maintenance and membrane replacement into per-cubic-meter water supply agreements. This shift concentrates most visibly around Dhahran and Jubail industrial zones where capital budget constraints intersect with urgent water security timelines.
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market Segmentation
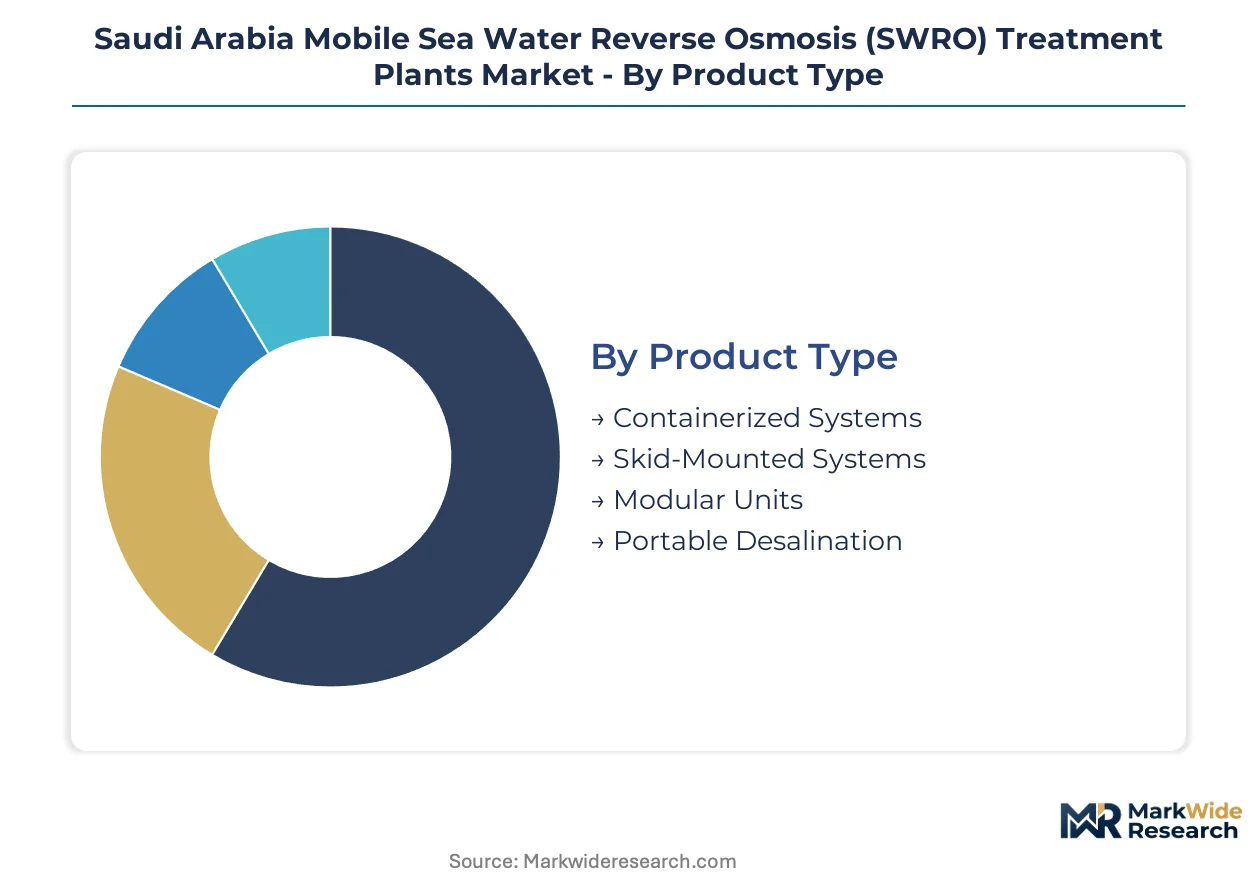
Segmentation in Saudi Arabia's mobile SWRO market reveals how procurement specifications diverge across regulatory environments, operational constraints, and financing structures. Understanding these divisions exposes where suppliers must adapt certification, deployment speed, and commercial terms to capture share.
Product Type:
SFDA membrane certification requirements and SASO electrical safety standards create divergent compliance burdens across product architectures, reshaping vendor specialization and factory location decisions.
- Containerized Systems:Self-contained 20-foot or 40-foot ISO shipping enclosures housing high-pressure pumps, membrane arrays, and energy recovery devices in plug-and-deploy configuration. Aramco wellpad operations across the Eastern Province from Jubail to Dhahran specify these for rapid commissioning without civil works. Lease-to-own financing structures concentrate heavily around this format.
- Skid-Mounted Systems:Steel-frame assemblies designed for semi-permanent installation with lower lifecycle costs than containerized alternatives. Industrial manufacturers in Jubail Industrial City favor these for capacity additions where five-plus year operational horizons justify reduced mobility.
- Modular Units:Scalable membrane blocks enabling phased capacity expansion. NEOM construction camps specify these for progressive water supply scaling as workforce populations grow.
- Portable Desalination:Trailer-mounted or towable systems below 100 cubic meters per day output. Remote agricultural cooperatives in Al-Ahsa Oasis deploy these for seasonal irrigation supplementation.
Containerized systems handle the majority of throughput; portable desalination is climbing the fastest as agricultural water security initiatives expand.
End User:
Customer procurement authority and financing capacity segment the market into fundamentally different sales cycles, from municipal tender boards to oilfield operational expenditure approvals.
- Municipalities:Local government water departments procuring under MEWA water security mandates with strict SFDA drinking water quality enforcement. Dammam and Al-Khobar municipal utilities are accelerating decentralized resilience investments.
- Industrial Manufacturers:Petrochemical and steel producers requiring process water without grid dependency. SABIC affiliates across Jubail Industrial City represent concentrated demand for redundant supply.
- Oil & Gas Sector:Upstream operators managing wellpad water needs across remote Arabian Gulf and Rub' al Khali concessions. Aramco Unconventional Resources deployments from Manifa to Shaybah drive specification standards.
- Agriculture:Date palm cooperatives and dairy operations seeking brackish water treatment for irrigation and livestock. Al-Ahsa and Qatif farming clusters are expanding mobile SWRO adoption under food security programs.
Oil and gas commands the largest absolute procurement volumes; agriculture is expanding most quickly as rural water subsidy reforms take hold.
Installation Type:
Physical siting constraints determine corrosion protection specifications, foundation requirements, and brine discharge permitting complexity under MEWA environmental frameworks.
- Onshore:Coastal or inland fixed-position deployments with direct grid or generator power access. Eastern Province industrial corridor concentrations dominate this category.
- Offshore:Platform-mounted or floating systems serving artificial islands and marine construction. Red Sea coastal development projects at Amaala are generating novel demand.
- Mobile Units:Rapidly relocatable assets deployed sequentially across multiple sites. Aramco drilling camp rotations require 30-day redeployment cycles.
- Stationary Systems:Permanent or semi-permanent installations with multi-year operational horizons. Industrial zone anchor tenants favor these for cost amortization.
Onshore installations absorb the dominant share of capital deployment; mobile units are gaining share fastest as exploration activity intensifies in frontier basins.
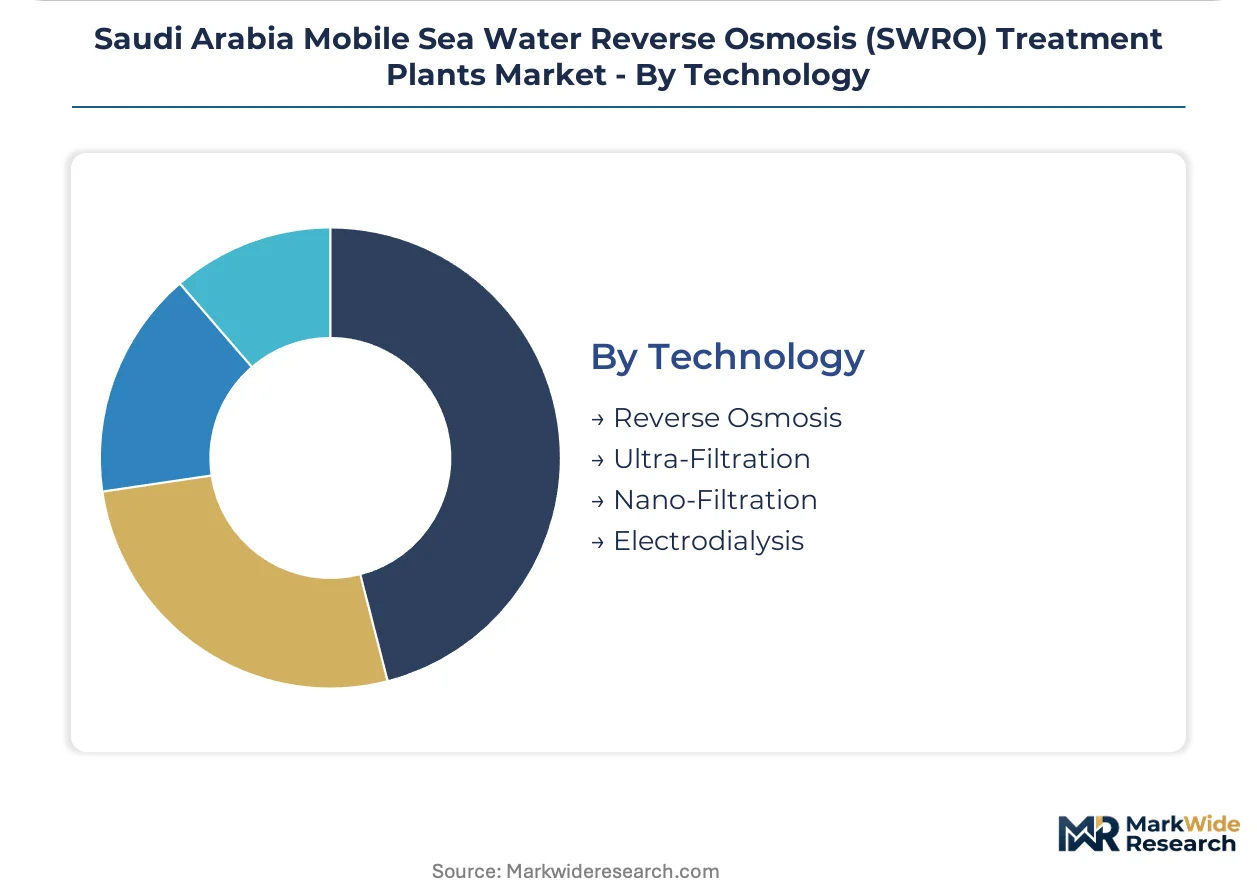
Technology:
Membrane chemistry and energy recovery integration separate performance tiers, with Saudi procurement specifications increasingly favoring high-recovery configurations that reduce specific energy consumption.
- Reverse Osmosis:Polyamide thin-film composite membranes operating at 55-85 bar with semi-permeable salt rejection above 99.2 percent. This is the baseline technology for all Saudi mobile SWRO procurement.
- Ultra-Filtration:Hollow-fiber membranes serving as pre-treatment or standalone particulate removal. NEOM construction water recycling specifications are incorporating these for suspended solids management.
- Nano-Filtration:Looser membrane pore structures targeting divalent ion removal rather than full desalination. Limited adoption in Saudi mobile applications due to incomplete salinity reduction.
- Electrodialysis:Electric potential-driven ion transport for brackish water conditions. Agricultural users in moderate-salinity zones are piloting these for reduced energy consumption.
Reverse osmosis underpins virtually all installed capacity; ultra-filtration is expanding most quickly as pre-treatment bundling becomes standard in municipal tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's mobile SWRO market operates as a net importer of specialized membrane components and energy recovery devices, with domestic fabrication concentrated in the Eastern Province industrial corridor. The Kingdom's water security strategy is compressing deployment timelines across coastal and inland sub-regions, creating divergent procurement patterns.
Eastern Province
Aramco wellpad operations from Jubail to Dhahran drive concentrated demand for rapid-deployment containerized systems. MEWA environmental discharge permits for brine management create operational planning complexity for suppliers serving this corridor. Lease-to-own financing structures cluster heavily around Dhahran industrial zones where capital budget constraints intersect with urgent water security mandates.
Riyadh
Municipal utilities under MEWA decentralization directives are procuring mobile SWRO for emergency resilience and distributed supply redundancy. SFDA drinking water quality standards enforce rigorous membrane certification protocols that extend supplier qualification timelines. Industrial manufacturers in the Second Industrial City specify skid-mounted systems for process water independence from grid infrastructure.
Western Region
Jeddah and Makkah municipal authorities face Red Sea salinity conditions that favor high-recovery membrane specifications above 60 bar operating pressure. SASO electrical safety technical regulations for containerized systems create compliance entry barriers for non-established vendors. King Abdullah Economic City construction camps are piloting modular unit architectures for phased workforce scaling.
NEOM Northwest
The linear city megaproject generates novel demand for off-grid mobile desalination at construction sites lacking permanent infrastructure. Saudi Vision 2030 water self-sufficiency targets are accelerating procurement cycles for pressure-exchanger-integrated systems in this zone. Amaala and Sindalah island developments specify offshore-capable containerized units for marine construction phases.
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market Competitive Landscape
Concentration sits with diversified environmental engineering conglomerates and specialized membrane technology providers. The supplier base organizes around three functional tiers: global desalination engineering houses with turnkey EPC capabilities, regional fabricators leveraging localized manufacturing and service networks, and component specialists focused on energy recovery and high-pressure pumping subsystems. Strategic moves center on lease-to-own financing bundling and SASO pre-certification fast-tracking to capture municipal procurement channels.
Among French-headquartered environmental services groups, Veolia Environnement SA exemplifies the global engineering archetype with turnkey containerized project capabilities. Metito Saudi Arabia occupies a position within the regional fabricator tier, leveraging localized manufacturing presence and aftermarket service infrastructure. Energy Recovery represents the component specialist archetype, anchoring the energy recovery device segment with isobaric pressure exchanger technology for power-constrained remote installations.
| Leading Market Players |
|---|
| National Shipping Company of Saudi Arabia SJSC (Bahri) |
| Veolia Environnement SA |
| Get Water Co Ltd |
| Meft International Company |
| Al Kafaah LLC |
| Metito Saudi Arabia |
| Saudi Arabian Amiantit Company |
| ACCIONA Agua |
| Energy Recovery |
| Others |
Pricing and Supply Chain Analysis
Pressure-exchanger substitution for conventional energy-recovery devices is redrawing procurement economics, shifting supplier geography toward California-based component specialists while compressing margins for European system integrators serving Saudi Arabia's Eastern Province oilfields.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SASO electrical safety certification tier and bundled membrane replacement schedules. Cost compression in economy-tier containerized units is intensifying because nickel-molybdenum alloy volatility squeezes fabrication margins. Municipal procurement boards exhibit highest price sensitivity; Aramco operational expenditure approvals show lowest.
Supply Chain Analysis
Extended lead times for polyamide thin-film composite membranes stretch factory acceptance testing schedules by 8-14 weeks. Manufacturing concentrates in the United States, Japan, and Germany for membrane elements; China and South Korea for high-pressure pump castings; Italy and France for energy recovery device machining. The chain rests on duplex stainless steel sheet and super-duplex piping feedstock. Single-source vulnerability permeates isobaric pressure exchanger sourcing. Distribution runs through Jubail Industrial City fabrication hubs to Dhahran operational sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's mobile SWRO market sits in early-cycle recovery, with exploration activity intensification in Rub' al Khali frontier basins driving sequential equipment redeployment demand.
For Market Incumbents: Fortify lease-to-own financing capabilities to match municipal procurement shifts toward operational expenditure treatment. Deepen backward integration into membrane warehousing at Dammam logistics hubs to offset SFDA certification timeline risks. Anchor aftermarket service density in Jubail-Dhahran corridor to defend against regional fabricator encroachment. For New Entrants and Emerging Players: After-sales service underinvestment by global engineering houses creates entry space for localized maintenance networks. Target agricultural cooperatives in Al-Ahsa Oasis as the most penetrable buyer segment, where portable desalination adoption accelerates under food security programs. Pursue SASO pre-certification fast-track as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional water treatment specialists holding Eastern Province service contracts. Five-to-ten year viability hinges on Saudi Vision 2030 water security mandate durability. Watch Aramco unconventional resources drilling camp rotation frequency as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Lease-to-Own Financing Bundling | Captures municipal procurement channels where capital budget constraints intersect with urgent MEWA water security timelines. |
| SASO Pre-Certification Investment | Accelerates market entry timelines for containerized systems against SFDA drinking water quality enforcement complexity. |
| Pressure Exchanger Technology Licensing | Opens power-constrained Red Sea coastal development markets previously inaccessible to conventional SWRO configurations. |
| Localized Membrane Warehousing | Compresses factory acceptance testing schedules vulnerable to polyamide thin-film composite supply bottlenecks. |
| Aftermarket Service Network Expansion | Defends recurring revenue streams against Metito Saudi Arabia and regional fabricator aftermarket encroachment. |
Research Methodology
The analysis maps containerized systems, skid-mounted assemblies, modular units, and portable desalination configurations, each validated through desalination engineering directors, Aramco procurement officers, MEWA regulatory affairs leads, and Jubail Industrial City plant managers. Primary fieldwork combined with secondary validation from customs trade records, SEC filings of listed environmental engineering groups, MEWA water security policy documents, and SASO technical regulation databases. Bottom-up unit deployment tallies triangulated against top-down national desalination capacity targets.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product architecture, end-user procurement authority, installation siting constraints, and membrane chemistry integration as core segmentation dimensions. CAGRs derived from deployment cycle compression rates and Saudi Vision 2030 mandate acceleration effects. Forecast inputs incorporated lease-to-own financing penetration curves and pressure-exchanger technology adoption thresholds.
Forecasts assume regulatory continuity in SFDA drinking water quality enforcement and SASO electrical safety regimes; material policy shifts would require re-modeling. Specific energy consumption improvements in membrane chemistry and energy recovery integration represent unmodeled upside. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Global Seismic Vessels Market