
 Offshore Mooring Line Fatigue Monitoring and Test Equipment Market | 2026-2036
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market Insights
Aftermarket service revenue is reconfiguring competitive economics in offshore asset integrity. Fugro leverages its global survey vessel network to bundle monitoring hardware with long-term inspection contracts. DNV sustains authority through classification rules that mandate fatigue testing protocols for floating production installations. Bureau Veritas anchors its position by certifying both equipment manufacturers and end-user inspection procedures across major hydrocarbon basins.
Offshore mooring line fatigue monitoring and test equipment encompasses sensor systems, data acquisition hardware, and analytical software designed to measure cyclic stress accumulation in steel chain, wire rope, and synthetic fiber mooring components operating in wave-dominated environments. These systems typically resolve microstrain variations and detect crack initiation at load thresholds critical to preventing sudden mooring failure in floating production systems. Fiber optic sensors now lead equipment type adoption where electromagnetic interference from subsea power cables corrupts conventional strain gauge signals. Dynamic load monitoring applications are growing fastest among deployment categories, driven by real-time digital twin integration on tension leg platforms. Oilfield operators represent the most concentrated end-user margin pool, though marine contractors compete aggressively for installation and commissioning scope.
DNV standards, API RP 2SK guidelines from the American Petroleum Institute, and ISO 19901-7 collectively shape equipment certification requirements and inspection intervals for floating offshore structures. Norway's Petroleum Safety Authority enforces these frameworks through mandatory fatigue life verification before life-extension approvals, directly stimulating replacement sensor demand. Stakeholders must track how evolving classification rules for synthetic rope monitoring will redistribute equipment procurement between platform operators and specialized testing laboratories.
Market Dynamics
Real-time digital twin integration on tension leg platforms is compressing inspection cycles and forcing sensor hardware refresh rates from annual to continuous monitoring, fundamentally altering procurement economics for floating production operators.
Growth Catalysts
- Regulatory Mandates:Norway's Petroleum Safety Authority enforces mandatory fatigue life verification before approving platform life-extension projects, creating replacement sensor demand for aging North Sea assets.
- Synthetic Rope Adoption:Polyester mooring systems in deepwater pre-salt fields require specialized fiber optic monitoring where electromagnetic interference corrupts conventional strain gauge signals.
- Platform Life-Extension:North Sea basin operators face concentrated investment in continuous fatigue assessment for chain and wire rope systems on assets exceeding original design life.
Market Restraints
- Input Cost Volatility:Specialized fiber optic sensor assemblies depend on rare-earth-doped fiber supplies concentrated in Asian manufacturing clusters, exposing procurement to price swings.
- Technical Limitation:Subsea data transmission through steel-armored umbilicals experiences signal attenuation below 1,500 meters, restricting real-time monitoring on ultra-deepwater installations.
- Regulatory Friction:Divergent certification timelines between DNV classification rules and API RP 2SK guidelines create duplicate testing burdens for equipment manufacturers serving multiple basins.
Strategic Opportunities
- Brazil Pre-Salt Expansion:Floating production unit deployments in the Santos Basin lack established local fatigue testing infrastructure, creating first-mover advantage for integrated monitoring service providers.
- Technology Convergence:Machine learning algorithms trained on historical mooring failure databases are hybridizing with physics-based fatigue models to predict remaining useful life.
- Channel Innovation:Marine contractors are unbundling installation scope from long-term sensor maintenance contracts, opening direct equipment sales to platform operators previously captive to integrated service agreements.
Industry Challenges
- Skill Scarcity:Subsea fiber optic splicing technicians with combined offshore certification and photonics expertise command premium wages, constraining deployment velocity.
- Certification Timeline:ISO 19901-7 compliance testing for new sensor configurations requires 18-24 months of wave basin validation, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Mooring Line Fatigue Monitoring and Test Equipment Market |
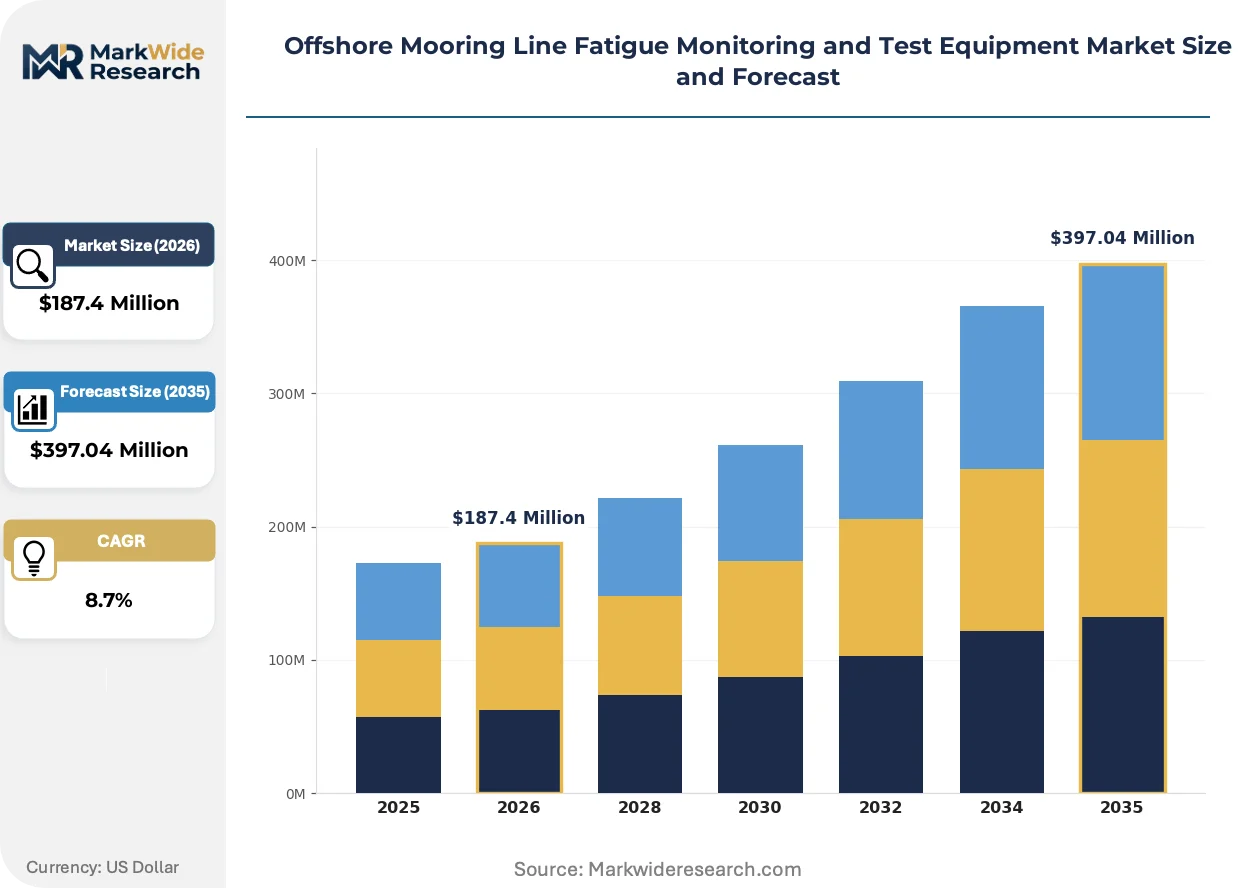
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Strain Gauges, Fiber Optic Sensors, Accelerometers, Load Cells, Magnetic Sensors Application: Fatigue Analysis, Dynamic Load Monitoring, Structural Health Assessment, Predictive Maintenance, Failure Prevention Deployment: Fixed Platforms, Floating Production Systems, Subsea Installations, Tension Leg Platforms, Spar Platforms End User: Oilfield Operators, Marine Contractors, Testing Laboratories, Research Institutes |
| Companies Covered | Oceaneering International, Acteon Group, DeepOcean, DOF Group, Fugro, Bureau Veritas, DNV, Ashtead Technology, InterMoor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market Trends and Innovations
Sensor architecture is fragmenting between distributed fiber optic sensing and discrete accelerometer arrays, with platform operators arbitrating between capital cost and data granularity trade-offs. This divergence is reshaping supplier specialization and aftermarket service bundling.
Fiber Bragg grating sensor networks are hybridizing with conventional electrical strain gauges on hybrid mooring configurations. Major tension leg platform operators in the Gulf of Mexico are piloting these dual-modality systems to validate synthetic rope behavior against steel reference measurements. The technology is hybridizing equipment procurement decisions by forcing operators to specify interoperable data acquisition hardware rather than single-vendor lock-in.
API RP 2SK guideline revisions now mandate annual fatigue damage accumulation reporting for all floating production systems in US federal waters. The US Bureau of Safety and Environmental Enforcement enforces these frameworks through inspection penalty structures, compelling operators to upgrade legacy manual inspection protocols. Deepwater tension leg platforms in the Gulf of Mexico represent the most affected segment, with operators accelerating sensor retrofit programs to avoid operational downtime.
Aftermarket service unbundling is fragmenting traditional integrated procurement contracts. Platform operators in the North Sea now separate hardware acquisition from long-term data interpretation services, compressing supplier margins on installation scope while expanding recurring software subscription revenue. This pattern is most visible among UK continental shelf operators managing multiple aging floating production assets under life-extension regimes.
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market Segmentation
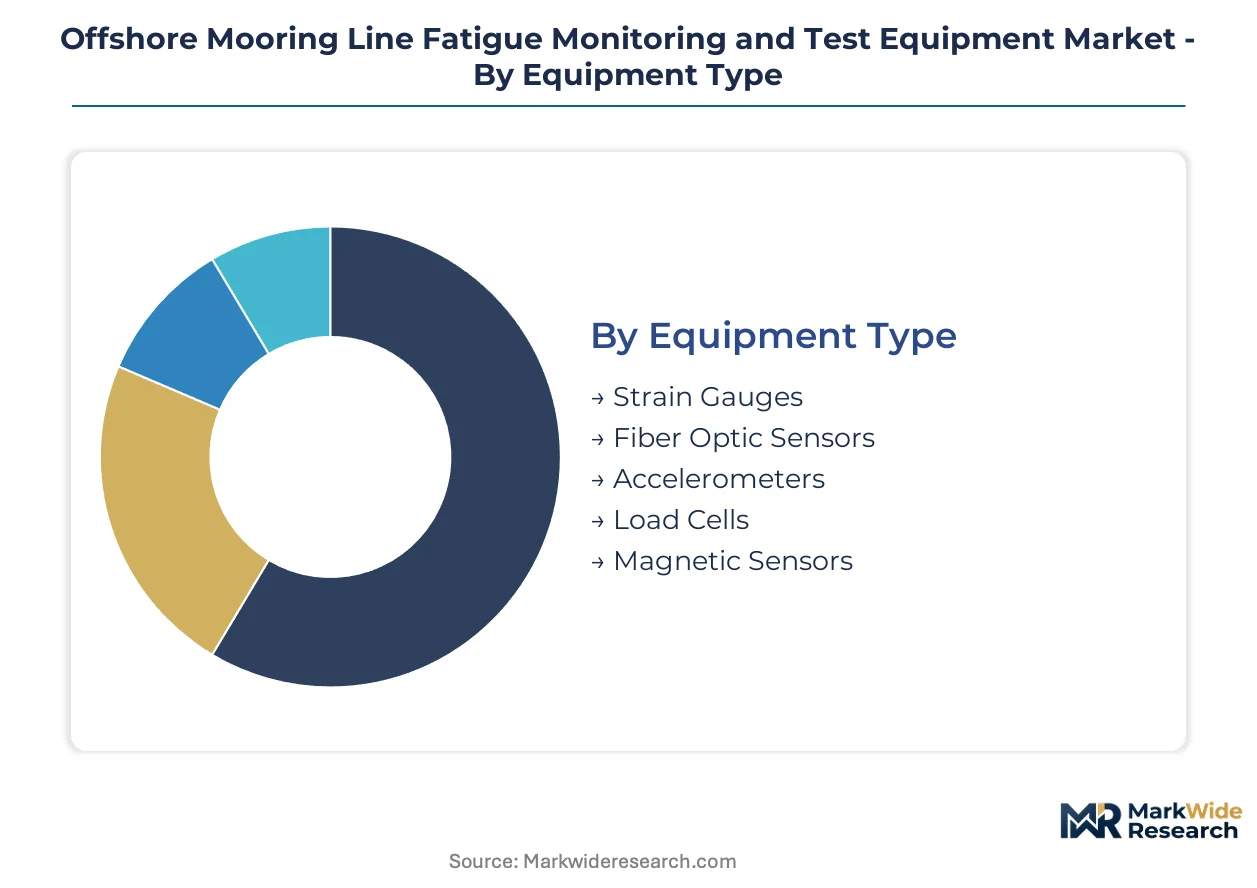
Equipment specification choices in offshore mooring fatigue monitoring cascade directly into service contract structures and sensor replacement cycles. Platform operators arbitrating between fiber optic and electromechanical architectures lock in fundamentally different aftermarket revenue profiles for equipment vendors.
Equipment Type:
After-sales service intensity varies dramatically across sensor technologies, with fiber optic systems demanding specialized subsea splicing expertise that electromechanical alternatives avoid.
- Fiber Optic Sensors:Distributed sensing cables with Bragg grating arrays resolve microstrain variations along continuous mooring lengths without electromagnetic interference. Norwegian North Sea operators specify these exclusively for polyester rope monitoring on floating production units where steel-armored umbilicals corrupt conventional signals.
- Strain Gauges:Conventional foil and semiconductor gauges bonded directly to chain links and wire rope terminations provide discrete point measurements at lower capital cost. Gulf of Mexico tension leg platform operators favor these for steel component monitoring where signal transmission distances remain short.
- Accelerometers:MEMS and piezoelectric devices capture vibration signatures indicative of fretting fatigue and out-of-plane motion.
- Load Cells:In-line tension measurement devices installed at fairlead connections quantify mean and cyclic load components.
- Magnetic Sensors:Eddy current and flux leakage instruments detect surface-breaking cracks in magnetizable steel mooring chains.
Fiber optic sensors hold the largest share; momentum sits with integrated multi-modality packages combining optical and electromechanical elements.
Application:
Procurement patterns diverge sharply between continuous monitoring mandates and periodic inspection regimes, with regulatory classification rules determining which applications command premium pricing.
- Dynamic Load Monitoring:Real-time acquisition of tension time histories enables immediate operational response to extreme weather events. Santos Basin pre-salt floating production units deploy these systems to validate polyester rope behavior against digital twin predictions before regulatory submission to Brazil's national petroleum regulator.
- Fatigue Analysis:Cumulative damage calculation using rainflow counting and Palmgren-Miner rules determines remaining service life. UK continental shelf operators commission these studies annually for life-extension approvals from the country's offshore safety regulator.
- Structural Health Assessment:Comprehensive evaluation of mooring system integrity combining multiple sensor modalities.
- Predictive Maintenance:Algorithm-driven scheduling of intervention activities based on measured degradation rates.
- Failure Prevention:Threshold-based alarm systems triggering emergency disconnect or production shutdown.
Fatigue analysis commands the dominant revenue pool; predictive maintenance is expanding most quickly as machine learning tools mature.
Deployment:
Water depth and platform architecture dictate sensor packaging requirements, with ultra-deepwater installations demanding pressure-compensated housings that multiply hardware costs.
- Floating Production Systems:Spread-moored vessels including FPSOs, FSOs, and drillships require distributed sensing across multiple mooring lines. West African developments favor these configurations for their storage capacity and weathervaning ability.
- Tension Leg Platforms:Vertical tendon systems experience high-frequency axial vibration demanding specialized accelerometer arrays. US federal waters installations face mandatory annual fatigue reporting to the Bureau of Safety and Environmental Enforcement.
- Fixed Platforms:Jacket structures with conventional catenary moorings use simpler monitoring architectures.
- Subsea Installations:Seabed-to-surface production risers and flowlines require pressure-resistant sensor packaging.
- Spar Platforms:Deep-draft single-point moorings with composite riser systems.
Floating production systems anchor volume demand; tension leg platforms show the steepest expansion trajectory as Gulf of Mexico retrofit cycles accelerate.
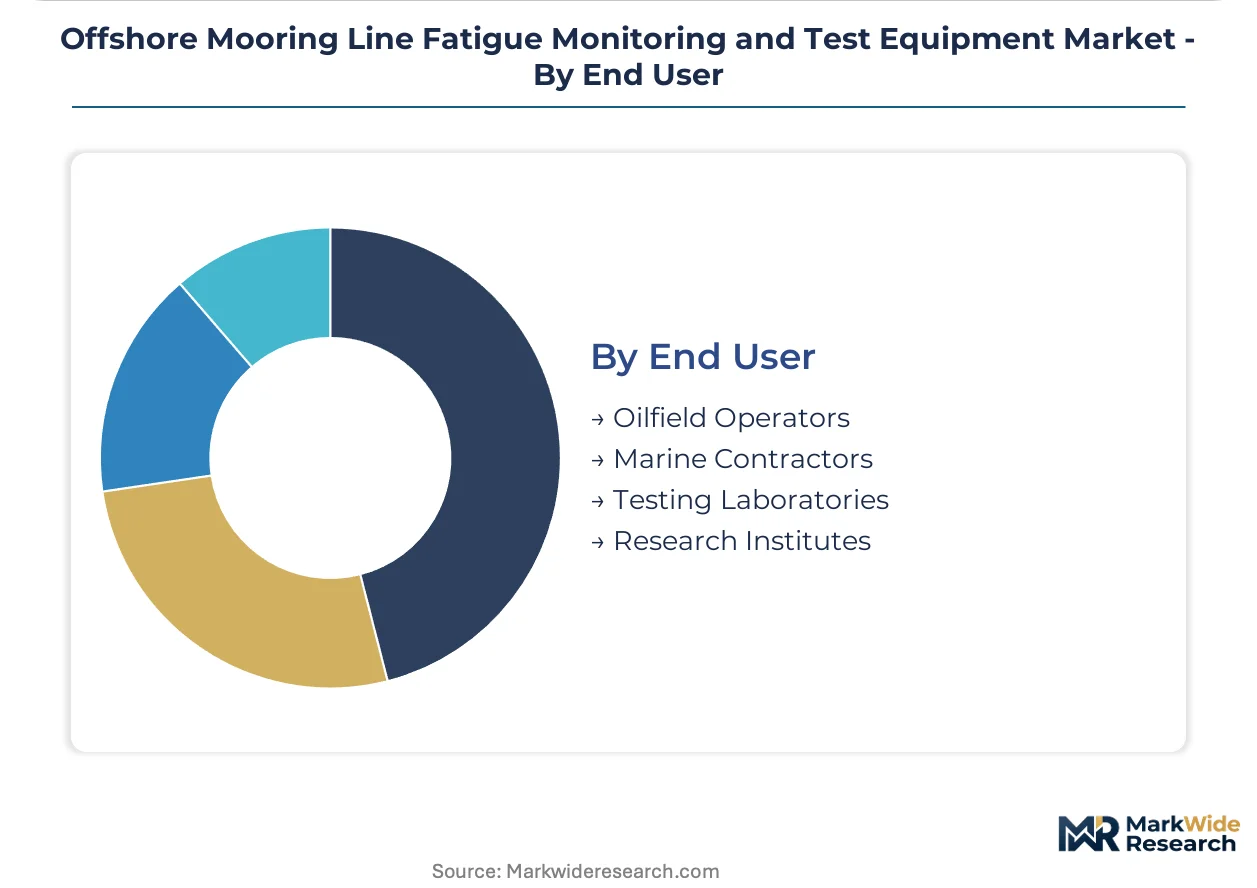
End User:
Customer sophistication and procurement authority determine whether equipment sales proceed through direct channels or marine contractor intermediaries.
- Oilfield Operators:Supermajors and national oil companies with captive engineering teams specify sensor configurations directly and retain data interpretation capability. Norwegian operators maintain the most stringent internal standards, often exceeding Petroleum Safety Authority minima.
- Marine Contractors:Installation and construction specialists bundle monitoring hardware within integrated mooring installation contracts. These intermediaries dominate early-phase project procurement before handover to field operators.
- Testing Laboratories:Independent facilities providing third-party fatigue validation and certification services.
- Research Institutes:Academic and government laboratories developing next-generation sensing methodologies.
Oilfield operators capture the largest procurement value; testing laboratories are gaining share fastest as classification societies expand outsourced validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Norway and Brazil demonstrate the least price elasticity, absorbing premium sensor costs under strict regulatory mandates. Gulf of Mexico operators exhibit moderate sensitivity, balancing hardware refresh cycles against Bureau of Safety and Environmental Enforcement penalty structures. Asian procurement remains most cost-conscious, with Chinese and South Korean yards driving standardization around lower-cost electromechanical alternatives.
Norway
North Sea platform life-extension projects dominate sensor procurement as operators retrofit aging floating production assets. The Petroleum Safety Authority enforces mandatory fatigue life verification before approving operational extensions beyond original design limits. Stavanger anchors the regional supply chain, with engineering clusters specializing in fiber optic integration for polyester mooring systems on deepwater units.
United States
Gulf of Mexico tension leg platform operators face accelerated sensor retrofit cycles driven by API RP 2SK guideline revisions. The Bureau of Safety and Environmental Enforcement mandates annual fatigue damage accumulation reporting, compelling hardware upgrades on legacy installations. Houston concentrates procurement authority, with supermajor engineering teams specifying configurations for federal waters developments.
Brazil
Pre-salt floating production unit deployments in the Santos Basin lack established local fatigue testing infrastructure. Brazil's national petroleum regulator requires validation of polyester rope behavior against digital twin predictions before operational approval. Rio de Janeiro hosts the engineering coordination centers, though sensor installation scope flows through international marine contractors.
United Kingdom
UK continental shelf operators unbundle hardware acquisition from long-term data interpretation services under life-extension regimes. The country's offshore safety regulator commissions annual fatigue studies for aging asset approvals. Aberdeen maintains specialist engineering density, though procurement decisions increasingly centralize in London-based operator headquarters.
China
State-owned oil companies specify cost-optimized electromechanical sensor packages for domestic shallow-water developments. The country's national offshore safety regulator adapts ISO 19901-7 frameworks with simplified inspection intervals. Tianjin and Qingdao anchor manufacturing clusters, with yards integrating monitoring hardware into newbuild floating production system packages.
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market Competitive Landscape
Capability concentration sits with classification societies and specialized survey contractors; scale advantage sits with integrated oilfield service conglomerates. The market structures around three tiers: certifying authorities mandating protocol standards, hardware-software integrators bundling sensor systems with data analytics, and installation specialists capturing marine construction scope. Strategic moves center on unbundling service contracts to access direct equipment sales, and hybridizing fiber optic with electromechanical modalities to reduce customer lock-in.
Among certifying authorities, Bureau Veritas and DNV exemplify the standards-setting tier, anchoring market access through protocol mandates. Fugro occupies a position bridging hardware provision with long-term inspection contracts, representing the integrated service archetype. Oceaneering International sits within the installation-specialist segment, though marine contractor intermediaries face margin compression as platform operators separate procurement channels.
| Leading Market Players |
|---|
| Oceaneering International |
| Acteon Group |
| DeepOcean |
| DOF Group |
| Fugro |
| Bureau Veritas |
| DNV |
| Ashtead Technology |
| InterMoor |
| Others |
Pricing and Supply Chain Analysis
Rare-earth-doped fiber supply concentration in Asian manufacturing clusters determines both the premium tier spread for fiber optic sensor assemblies and the geographic shape of procurement networks. Equipment vendors face compressed margins on electromechanical alternatives while capturing service attach value through subsea splicing expertise.
Pricing Analysis
After-sales service contracts and long-term data interpretation subscriptions drive lifetime value beyond initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels separates fiber optic systems with continuous monitoring capabilities from periodic electromechanical inspections and manual survey alternatives. Price differentiation rests on certification grade from DNV and Bureau Veritas plus the geographic delivery cost to offshore installations. Cost compression in standard-tier electromechanical packages is intensifying because Chinese yards are driving commoditization of strain gauge assemblies. Marine contractors exhibit the highest price sensitivity, while Norwegian oilfield operators absorb premium sensor costs under Petroleum Safety Authority mandates.
Supply Chain Analysis
Tariff exposure between Chinese rare-earth processing facilities and European sensor assembly plants dominates supply chain risk planning for equipment vendors. Specialized fiber optic cable manufacturing draws from China, Japan, and Germany, with subsea connector assemblies anchored in Norway and the United Kingdom. Rare-earth-doped fiber, pressure-compensated housings, and photonics-grade splices constitute critical input dependencies. Single-source vulnerability persists for deepwater-qualified fiber grades qualified to ISO 19901-7 standards. Distribution runs through marine contractor intermediaries for newbuild installations and direct operator channels for retrofit sensor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription revenue for fatigue data interpretation is expanding faster than hardware replacement cycles, transforming this market into a service-attach opportunity where recurring revenue multiples exceed capital equipment valuations.
For Market Incumbents: Entrench position by deepening captive supply of rare-earth-doped fiber through backward integration into Asian photonics suppliers, insulating against input cost volatility that threatens margin stability. Accelerate certification investment for multi-modality sensor packages combining fiber optic and electromechanical elements to defend against emerging entrants offering unbundled hardware sales. Channel control through long-term inspection vessel charters locks out competitors from North Sea life-extension projects where the Petroleum Safety Authority mandates continuous monitoring. For New Entrants and Emerging Players: Establish a beachhead in Brazil's Santos Basin pre-salt developments where local fatigue testing infrastructure remains undeveloped and international marine contractors dominate procurement. Target direct equipment sales to UK continental shelf operators who have unbundled hardware acquisition from integrated service agreements, bypassing incumbent contractor relationships. A machine learning-powered predictive maintenance software layer offers the most penetrable go-to-market angle, as platform operators seek algorithmic remaining-life calculations independent of incumbent hardware vendors. For Investors and Strategic Acquirers: The market sits at a platform life-extension acceleration phase that favors vertically integrated service providers with captive vessel and sensor manufacturing capabilities. Long-term viability centers on recurring revenue attachment rates rather than hardware shipment volumes, positioning data analytics specialists with offshore domain expertise as attractive acquisition targets. The signal to watch is unbundling velocity in the North Sea, where operator procurement centralization away from marine contractors indicates willingness to separate hardware and service purchasing decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modality Sensor Integration | Hybrid fiber optic-electromechanical packages reduce customer lock-in and expand addressable platform retrofit scope. |
| Software-Defined Analytics Layer | Machine learning fatigue prediction algorithms create recurring subscription revenue independent of hardware refresh cycles. |
| Backward Integration into Fiber Supply | Captive rare-earth-doped fiber sourcing insulates margin pressure from Asian supply concentration volatility. |
| Direct Channel Development | Bypassing marine contractor intermediaries captures hardware margin previously allocated to installation bundling. |
| Brazil Pre-Salt Infrastructure Buildout | First-mover positioning in Santos Basin fatigue testing addresses regulatory validation gaps before local capability develops. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform integrity engineers, subsea sensor procurement leads, marine contractor project managers, and classification society surveyors. Secondary validation drew from DNV classification rule filings, API RP 2SK guideline documentation, Petroleum Safety Authority inspection reports, Bureau of Safety and Environmental Enforcement enforcement data, and ISO 19901-7 compliance records. Bottom-up equipment shipment tracking and top-down floating production system installation forecasts were triangulated to anchor market sizing.
Calibration against historical sensor replacement cycles and platform life-extension approval timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, application category, deployment architecture, and end-user procurement authority, with water depth tiers and regulatory jurisdiction clusters as industry-specific overlays. CAGRs were derived from regression analysis of sensor adoption intensity against platform age distributions and inspection mandate evolution. Forecast inputs incorporated digital twin integration penetration rates and synthetic rope adoption curves in deepwater basins.
Sensitivities concentrate around regulatory enforcement intensity variations, rare-earth supply disruption scenarios, and subsea data transmission technology breakthroughs that could extend real-time monitoring below current depth limitations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market