
 North America Agricultural Enzymes Market | 2026-2036
North America Agricultural Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Enzymes Market Analytics
Specialty crop growers and organic farming operations are reorganizing procurement priorities toward biological inputs, pulling enzyme demand away from conventional commodity producers. Novonesis leverages its fermentation scale to supply bulk cellulase formulations across Midwest distribution networks. BASF SE anchors its position through integrated seed-treatment-to-soil-health portfolios that bundle enzymes with nutrient management systems. Elemental Enzymes differentiates via custom protease blends tailored to regional soil microbiome profiles.
Agricultural enzymes are protein-based biocatalysts, typically derived from microbial fermentation of bacteria or fungi, that accelerate biochemical reactions in soil and plant systems at concentrations measured in active units per gram. These molecules function primarily to degrade organic matter, mobilize bound nutrients, and enhance root-zone metabolic activity for yield improvement. Cellulase dominates volume demand due to its role in residue decomposition across corn-soy rotations, while lipase formulations command premium positioning in specialty crop segments where lipid metabolism enhancement drives fruit quality metrics. Amylase applications in biofuel production represent a mature, price-competitive channel with thinner margins compared to direct agricultural uses.
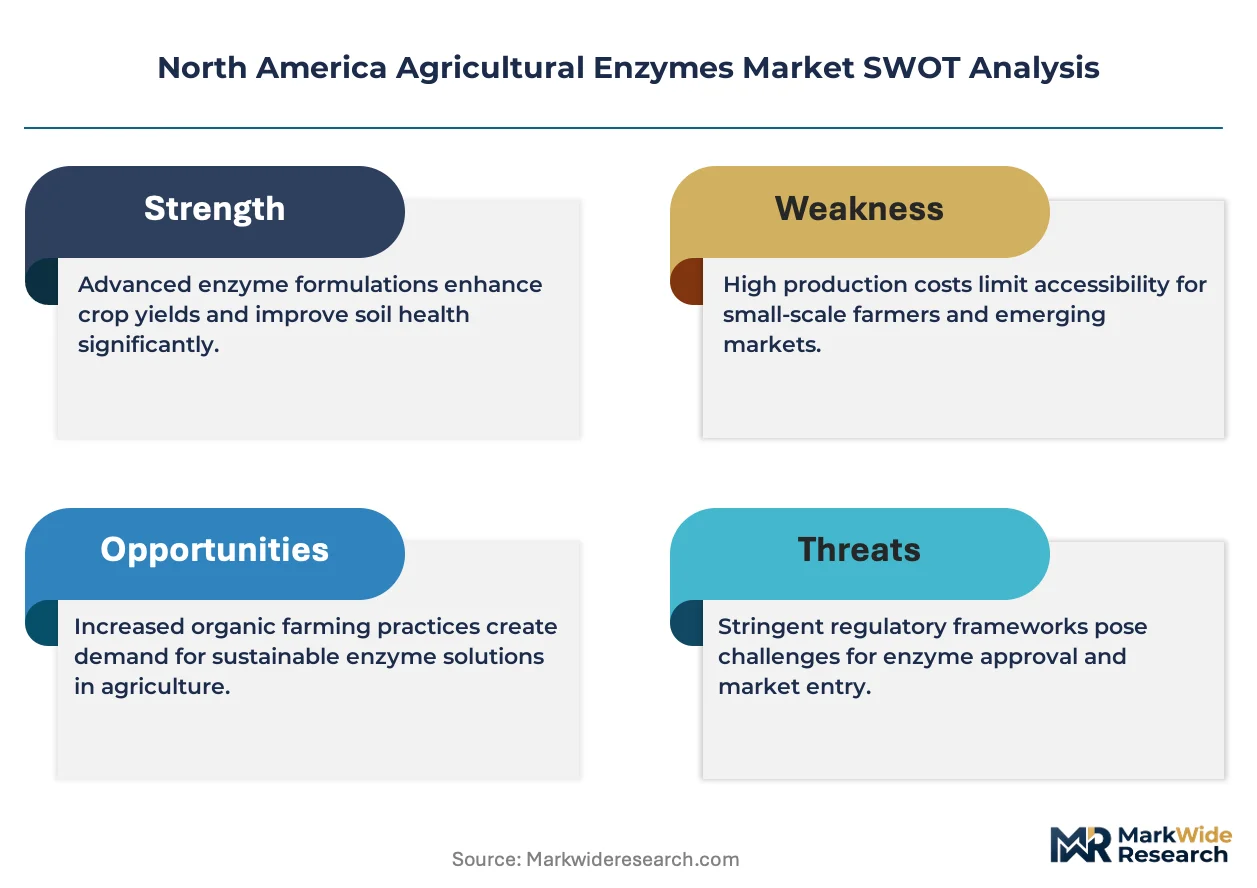
The U.S. EPA regulates agricultural enzymes under biopesticide and plant-incorporated protectant frameworks, requiring submission of toxicity and non-target organism data prior to interstate commerce. Canada's PMRA enforces parallel efficacy standards through the Pest Control Products Act, creating a dual-compliance burden for suppliers operating cross-border. The USDA National Organic Program certifies enzyme products for organic system plans, directly shaping label claims and farmer eligibility. Stakeholders must monitor evolving state-level neonicotinoid restrictions that indirectly expand biological input budgets across the Great Plains and Prairie provinces.
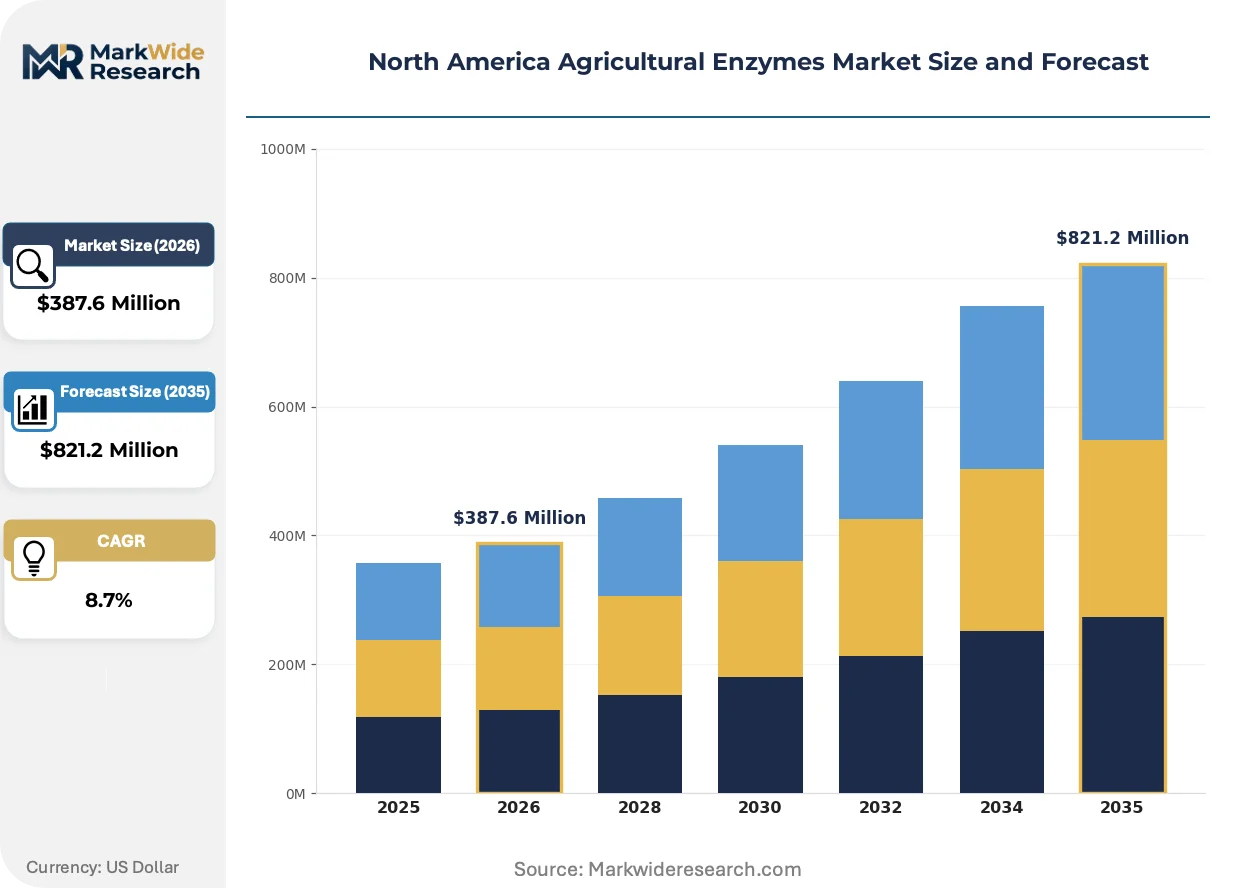
Market Dynamics
Biological input procurement reorganization is pulling enzyme demand away from conventional commodity producers toward specialty crop and organic operations, restructuring competitive positioning across the Corn Belt and Prairie provinces.
Growth Catalysts
- EPA Biopesticide Pathways:Streamlined registration under the Federal Insecticide, Fungicide, and Rodenticide Act reduces commercialization timelines for microbial-derived enzyme formulations entering interstate commerce.
- USDA Organic Certification:National Organic Program approval enables label claims that unlock procurement budgets across certified operations in California's Central Valley and Florida's citrus belt.
- Residue Management Mandates:Corn-soy rotation intensification across Iowa, Illinois, and Indiana creates sustained pull for cellulase products targeting stover decomposition and soil carbon retention.
Market Restraints
- Fermentation Feedstock Volatility:Corn steep liquor and soybean meal price swings directly compress margins for bulk cellulase manufacturers operating at scale.
- Dual-Compliance Burden:Cross-border suppliers face parallel EPA and PMRA data requirements, extending registration costs and timeline uncertainty for products targeting both U.S. and Canadian markets.
- Synthetic Fertilizer Substitution:Low-cost urea and anhydrous ammonia remain economically dominant in commodity row-crop budgets, limiting enzyme penetration in price-sensitive segments.
Strategic Opportunities
- Prairie Province Expansion:Saskatchewan and Manitoba pulse-crop operations represent underpenetrated demand for nitrogen-fixation-enhancing enzyme formulations.
- Seed Treatment Convergence:Integration of enzymes with biological inoculants creates bundled value propositions for precision planting equipment deployed across the U.S. Midwest.
- State Neonicotinoid Restrictions:New York and Minnesota pesticide limitations indirectly expand biological input budgets, opening procurement channels for soil-health-focused enzyme portfolios.
Industry Challenges
- Microbiome Characterization Expertise:Custom protease development requires specialized soil metagenomics capabilities that remain scarce among regional distributors serving specialty crop growers.
- Organic Certification Timeline:USDA National Organic Program review cycles create 12-18 month label approval delays that mismatch with seasonal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Enzymes Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulase, Amylase, Protease, Lipase Application: Crop Protection, Soil Fertility, Plant Growth, Biofuel Production End User: Farmers, Agricultural Cooperatives, Research Institutions, Biotechnology Firms Service Type: Consultancy, Technical Support, Custom Formulation, Training |
| Companies Covered | Novonesis, Corteva Agriscience, BASF SE, Syngenta AG, Elemental Enzymes, Bayer AG, FMC Corporation, Bioworks Inc., Stoller USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Enzymes Market Evolving Landscape
Enzyme formulation science is converging with digital agriculture platforms, creating precision-application capabilities that tie biological efficacy to variable-rate equipment and real-time soil sensing networks.
Cell-free enzyme systems derived from extremophile microorganisms are displacing traditional fermentation-based production for high-value specialty crop applications. These thermostable formulations tolerate broader pH ranges and temperature fluctuations during field application. California almond and grape producers are adopting these products at accelerating rates, compressing the performance premium historically commanded by live microbial inoculants.
Canada's PMRA has tightened efficacy data requirements under revised Pest Control Products Act guidance, mandating field trial documentation across multiple agro-climatic zones. This regulatory shift elevates registration costs for entrants lacking established North American trial networks. Suppliers with existing Prairie province datasets are consolidating advisory relationships with provincial extension services to defend compliance positioning.
Buyer concentration among large-scale Midwest cooperatives is compressing traditional distribution margins and forcing reformulation of channel economics. Direct procurement relationships between 10,000-plus acre operations and enzyme manufacturers are displacing independent retail agronomists as the primary technical advisory interface. This pattern is most visible across Iowa and Illinois, where cooperative buying groups now specify performance guarantees and application support in volume contracts.
North America Agricultural Enzymes Market Segmentation
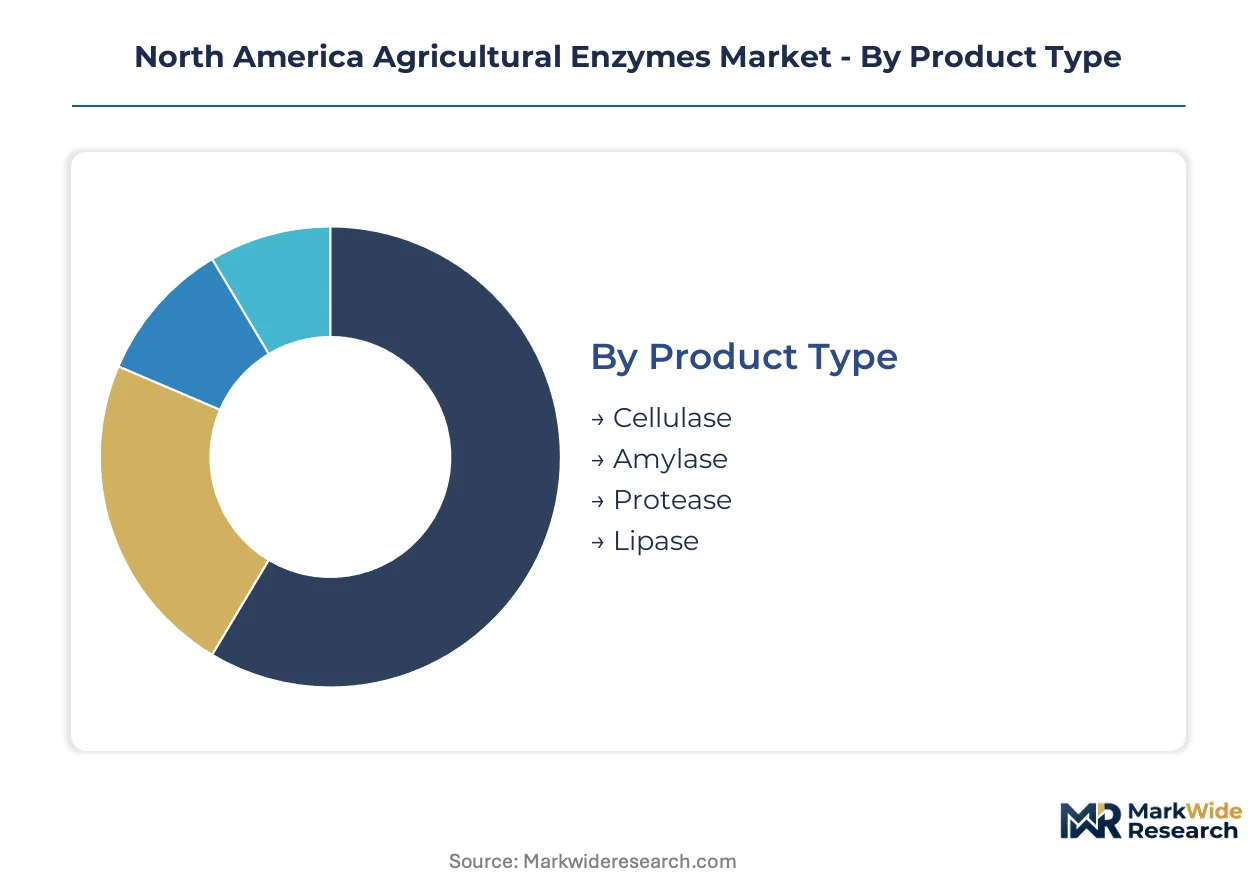
Enzyme procurement patterns across North America diverge sharply between commodity row-crop operations and specialty producers, with each segment demanding distinct formulation specifications and service intensities. Understanding these fault lines reveals where margin pools concentrate and which technical capabilities defend supplier positioning.
Product Type:
Domestic fermentation capacity in the U.S. Midwest supplies cellulase and amylase at scale, while protease and lipase formulations draw more heavily on specialized production networks serving export-oriented specialty crop regions.
- Cellulase:Multi-enzyme complexes targeting β-1,4-glycosidic bonds in crop residue dominate volume procurement across Iowa and Illinois corn-soy rotations. Demand concentrates in residue management programs where tillage reduction mandates accelerate stover decomposition requirements.
- Amylase:Starch-hydrolyzing enzymes catalyze polysaccharide breakdown in soil organic matter and biofuel feedstock processing. Corn Belt ethanol plants represent the anchor demand channel, though thinner margins pressure agricultural-grade pricing relative to industrial applications.
- Protease:Protein-cleaving biocatalysts enhance nitrogen mineralization in organic systems across California's Central Valley.
- Lipase:Ester-hydrolyzing formulations command premium positioning in Florida citrus and Pacific Northwest tree fruit quality optimization.
Cellulase commands the established base. The steepest expansion runs through protease as organic acreage climbs fastest.
Application:
Cost tier stratification separates commodity-priced soil fertility applications from premium crop protection and plant growth segments where performance guarantees justify higher per-acre expenditures.
- Crop Protection:Enzyme-based biopesticide formulations disrupt pathogen cell walls and insect digestive systems, qualifying for streamlined EPA biopesticide registration. California almond and grape producers drive adoption as neonicotinoid restrictions tighten.
- Soil Fertility:Nutrient-mobilizing enzymes unlock bound phosphorus and accelerate organic nitrogen mineralization. Prairie province pulse growers in Saskatchewan and Manitoba represent underpenetrated demand for nitrogen-fixation-enhancing blends.
- Plant Growth:Root-zone metabolic activators improve seedling vigor in precision-planted corn and soybean systems.
- Biofuel Production:Cellulase and amylase deployments in ethanol pre-treatment constitute a mature, price-competitive channel with standardized specifications.
Soil fertility anchors volume procurement. Crop protection is climbing the fastest as regulatory pressure redirects chemical budgets.
End User:
Customer type determines service intensity and contract structure, with cooperatives consolidating purchasing power while biotechnology firms demand specialized R&D partnerships.
- Farmers:Individual operators below 2,000 acres rely on retail agronomist recommendations and seasonal procurement cycles. Direct manufacturer relationships are displacing traditional distribution in larger operations.
- Agricultural Cooperatives:Consolidated buying groups across Iowa, Illinois, and Indiana now specify performance guarantees and application support in volume contracts exceeding 10,000-acre coverage.
- Research Institutions:University extension services and USDA ARS facilities generate field trial data supporting PMRA and EPA registration submissions.
- Biotechnology Firms:Seed and trait developers integrate enzymes into biological inoculant portfolios for bundled precision agriculture offerings.
Agricultural cooperatives concentrate purchasing volume. Biotechnology firms are gaining share fastest through seed treatment convergence.
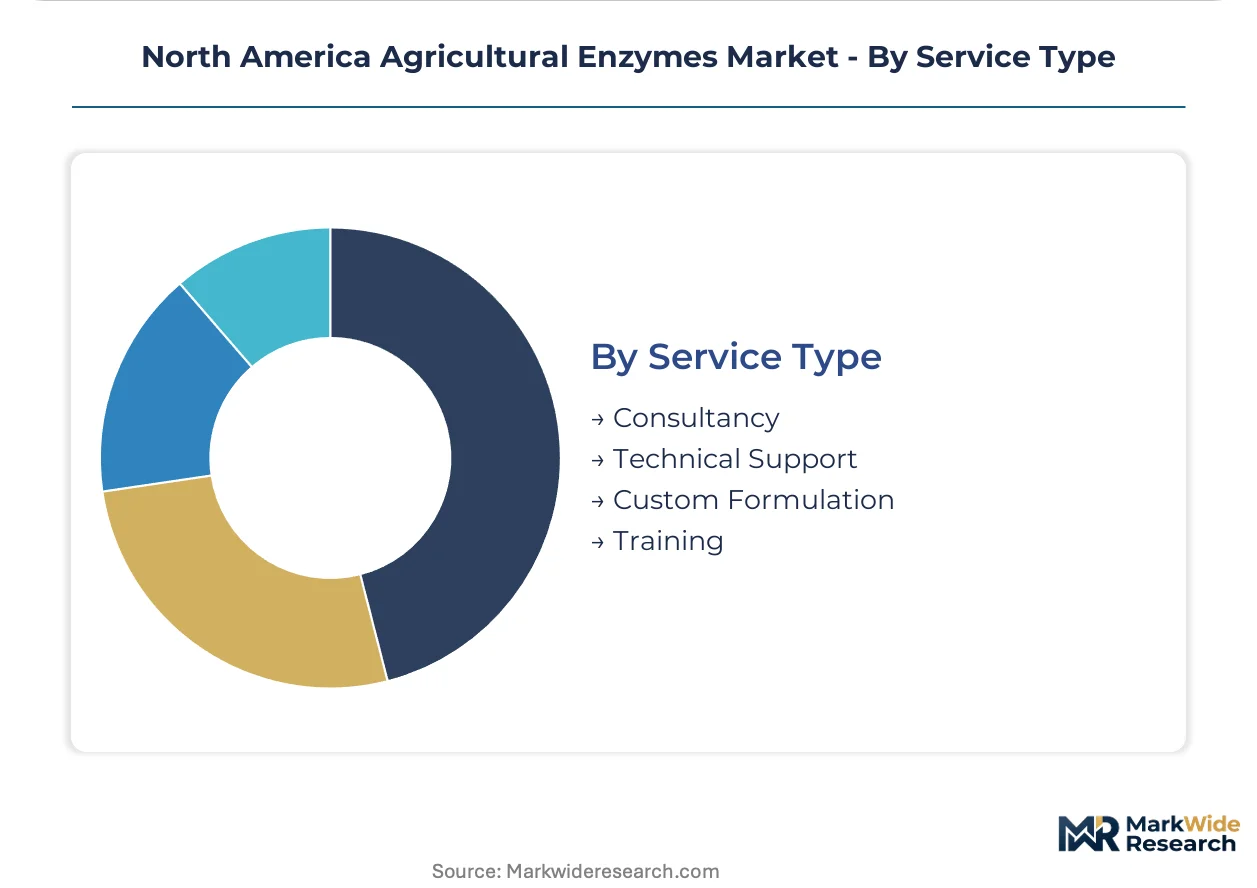
Service Type:
Margin structure separates standardized technical support from high-value custom formulation services requiring specialized soil metagenomics capabilities.
- Consultancy:Soil health advisory services tie enzyme recommendations to cover crop selection and carbon credit eligibility verification.
- Technical Support:Application rate optimization and tank-mix compatibility guidance defend customer retention in commodity segments.
- Custom Formulation:Protease blends tailored to regional soil microbiome profiles command premium pricing from specialty crop growers. Elemental Enzymes and similar specialists leverage Prairie province datasets to defend compliance positioning.
- Training:Operator certification programs for precision application equipment reduce liability exposure and improve field efficacy.
Technical support commands the established base. Custom formulation is expanding most quickly as microbiome characterization differentiates supplier positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration among large-scale agricultural cooperatives and biotechnology firms shapes demand distribution across the region, with procurement power consolidating in the U.S. Corn Belt and Canadian Prairie provinces.
United States
Cellulase demand concentrates in Iowa, Illinois, and Indiana corn-soy rotations where residue management mandates accelerate stover decomposition requirements. The EPA's streamlined biopesticide registration under FIFRA reduces commercialization timelines for microbial-derived enzyme formulations. California's Central Valley anchors specialty crop adoption, with almond and grape producers driving protease and lipase procurement as neonicotinoid restrictions tighten.
Canada
Saskatchewan and Manitoba pulse-crop operations generate underpenetrated demand for nitrogen-fixation-enhancing enzyme formulations. Health Canada's PMRA enforces parallel efficacy standards through the Pest Control Products Act, creating compliance requirements for cross-border suppliers. Prairie province extension services consolidate advisory relationships with enzyme manufacturers possessing established regional field trial datasets.
Mexico
Sinaloa and Baja California vegetable export operations pull biological input procurement toward residue-degrading enzyme formulations meeting international organic certification standards. Mexico's national agricultural regulator, SENASICA, coordinates phytosanitary protocols affecting biological input importation. Guanajuato's intensive horticulture belt concentrates precision agriculture adoption, linking enzyme applications to variable-rate equipment networks.
North America Agricultural Enzymes Market Competitive Landscape
Player mix skews toward diversified agrochemical conglomerates with biological input portfolios, creating a tiered structure where fermentation scale and regulatory data assets determine positioning. Strategic archetypes separate bulk cellulase suppliers serving commodity row-crop cooperatives from custom protease specialists targeting organic specialty crop operations. Dominant competitive moves include seed treatment convergence bundling enzymes with biological inoculants, and direct procurement relationships displacing traditional retail distribution channels.
Within the diversified agrochemical tier, Novonesis and BASF SE exemplify scale-driven positioning through Midwest distribution networks and integrated seed-treatment-to-soil-health portfolios respectively. Elemental Enzymes occupies a specialist position, representing the custom formulation archetype through regional soil microbiome profiling capabilities.
| Leading Market Players |
|---|
| Novonesis |
| Corteva Agriscience |
| BASF SE |
| Syngenta AG |
| Elemental Enzymes |
| Bayer AG |
| FMC Corporation |
| Bioworks Inc. |
| Stoller USA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Corn Belt cooperatives and Midwest fermentation facilities lock in cellulase supply access while anchoring price visibility against corn steep liquor indexation. These agreements insulate bulk buyers from spot volatility in agricultural feedstock markets, though renegotiation windows expose both parties to margin compression when fermentation input costs spike.
Pricing Analysis
Cost-plus contracts with corn steep liquor and soybean meal indexation dominate bulk cellulase procurement across Iowa and Illinois cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates custom protease blends for California organic operations from commodity formulations. Pricing pressure stems from synthetic fertilizer price floors that cap biological input budgets in commodity row-crop segments. Large-scale cooperatives exhibit lowest price sensitivity due to volume-anchored contract terms, while individual operators below 2,000 acres face acute budget constraints.
Supply Chain Analysis
Fermentation capacity chokepoints in the U.S. Midwest and Denmark underwrite supply security for cellulase and amylase volume production. Production draws from corn steep liquor, soybean meal, and molasses feedstocks sourced through captive agricultural processing networks. Single-source vulnerability concentrates in specialized protease and lipase fermentation lines serving California and Florida specialty crop markets. Distribution runs through cooperative buying groups and direct manufacturer relationships that displace independent retail agronomists across the Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against low-cost synthetic fertilizers that retain economic dominance in commodity row-crop budgets. Incumbents must demonstrate yield equivalence or superior soil health outcomes to justify per-acre premiums.
For Market Incumbents: Secure fermentation feedstock supply through backward integration into corn processing facilities or long-term offtake agreements with ethanol producers. Deepen Prairie province field trial datasets to preempt PMRA compliance elevation that would disadvantage entrants lacking established Canadian agro-climatic documentation. For New Entrants and Emerging Players: Anchor in Saskatchewan and Manitoba pulse-crop operations where nitrogen-fixation-enhancing enzyme formulations remain underpenetrated relative to Corn Belt saturation. Pursue seed treatment convergence partnerships with precision planting equipment manufacturers to bypass cooperative buying group gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom formulation specialists serving organic specialty crop operations with annual soil microbiome retesting requirements. Acquisition targets should demonstrate established EPA biopesticide registration pathways and existing USDA National Organic Program certifications. Watch state-level neonicotinoid restriction expansion as the signal indicating biological input budget inflection across the Great Plains.| Strategic Initiative | Industry Significance |
|---|---|
| Seed Treatment Convergence | Bundles enzymes with biological inoculants for precision planting equipment deployed across Iowa and Illinois. |
| Prairie Province Field Trial Expansion | Generates PMRA-compliant efficacy data across Saskatchewan and Manitoba agro-climatic zones. |
| USDA Organic Certification Investment | Unlocks procurement budgets across California Central Valley certified operations. |
| Direct Procurement Relationship Development | Displaces independent retail agronomists as technical advisory interface for 10,000-plus acre operations. |
| Cell-Free Enzyme System Production Scale-Up | Captures premium positioning among California almond and grape producers adopting thermostable formulations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with cooperative procurement managers, specialty crop agronomists, fermentation facility operations directors, and EPA regulatory affairs specialists. Secondary validation drew from EPA biopesticide registration databases, USDA National Organic Program certified product listings, PMRA Pest Control Products Act guidance documents, and provincial extension service trial reports. Bottom-up volume estimates from county-level enzyme application rates were triangulated against top-down fermentation capacity assessments.
Across the analysis window, forecasts model enzyme demand by product type, application segment, end user category, and service intensity tier. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory approval timelines and seasonal procurement patterns. Key inputs include corn-soy rotation intensification rates, state-level neonicotinoid restriction adoption schedules, and organic acreage expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of stable EPA biopesticide pathway efficiency and continued organic certification growth; material deviation in fermentation feedstock costs or PMRA data requirements would warrant model refresh. Practitioners should keep alternative scenarios live as synthetic fertilizer price volatility and state pesticide restriction momentum evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Brazil Lime Market
Others
Surgical Simulation Market
Others
Prunes Market
Others
Thermoformed Plastics Market
Others
Deflectometer Market
Others
US Cat Food Market
Others
Couscous Market
Others
Digital Thermal Plates Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Bimodal Identity Management Solutions Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Asia-Pacific Medical Simulation Market
Others
Tunnel Lighting Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Global Crowdsourced Testing Market