
 Sprockets Market | 2026-2036
Sprockets Market Size, Share, and Industry Trends Forecast 2026-2036
Sprockets Market Analytics
Modular sprocket-and-hub assemblies is repositioning buyer preference away from one-piece cast designs by cutting inventory carrying costs and simplifying field replacement. Martin Sprocket & Gear, Inc. dominates the North American replacement channel through extensive stock-and-ship distribution. Tsubakimoto Chain Co., Ltd. leverages integrated chain-and-sprocket engineering to capture bundled specification wins in precision conveyor applications. SKF AB extends its bearing-service network into mounted sprocket solutions, blurring traditional category boundaries.
A sprocket is a toothed mechanical wheel engineered to mesh with a roller chain, transmitting rotary motion between shafts with pitch diameters typically ranging from 25 mm to over 1,200 mm for heavy industrial units. Hardened steel variants undergo induction or flame hardening to achieve 45-55 HRC tooth surfaces, ensuring wear resistance in continuous-operation environments such as mining conveyors and automotive engine timing systems. Single strand and double strand configurations remain the volume core, though specialty sprockets for robotics and high-speed automation command disproportionate margin pools due to tight tolerances and low-volume production economics. Steel retains absolute material dominance in load-bearing applications, while aluminum and composite alternatives gain traction in weight-sensitive robotics and food-grade conveyor systems where corrosion resistance and cleanability matter.
ISO 606 and ANSI B29.1 standards govern roller chain and sprocket dimensional interchangeability, with REACH and RoHS compliance in Europe restricting certain surface coatings and alloy compositions. The US EPA and OSHA frameworks influence foundry emissions controls and workplace exposure limits that affect domestic casting economics. Buyers and suppliers must track evolving machinery safety directives and carbon-border adjustment mechanisms that will reshape sourcing geography and material qualification requirements.
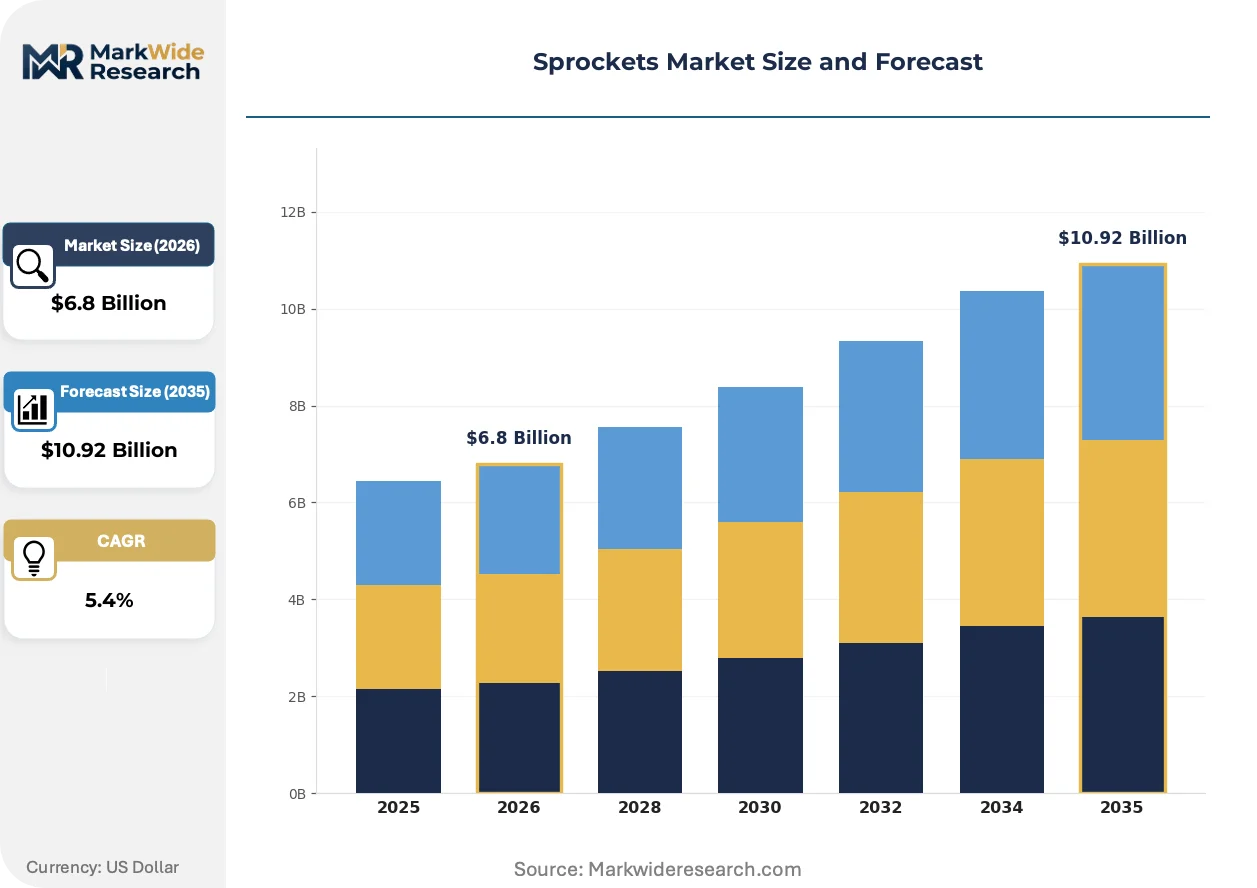
Market Dynamics
Modular sprocket-and-hub assemblies are compressing replacement cycles and reshaping inventory economics across industrial distribution channels. Heat treatment automation in German and Japanese forging operations is raising performance benchmarks that tier-two foundries struggle to match.
Growth Catalysts
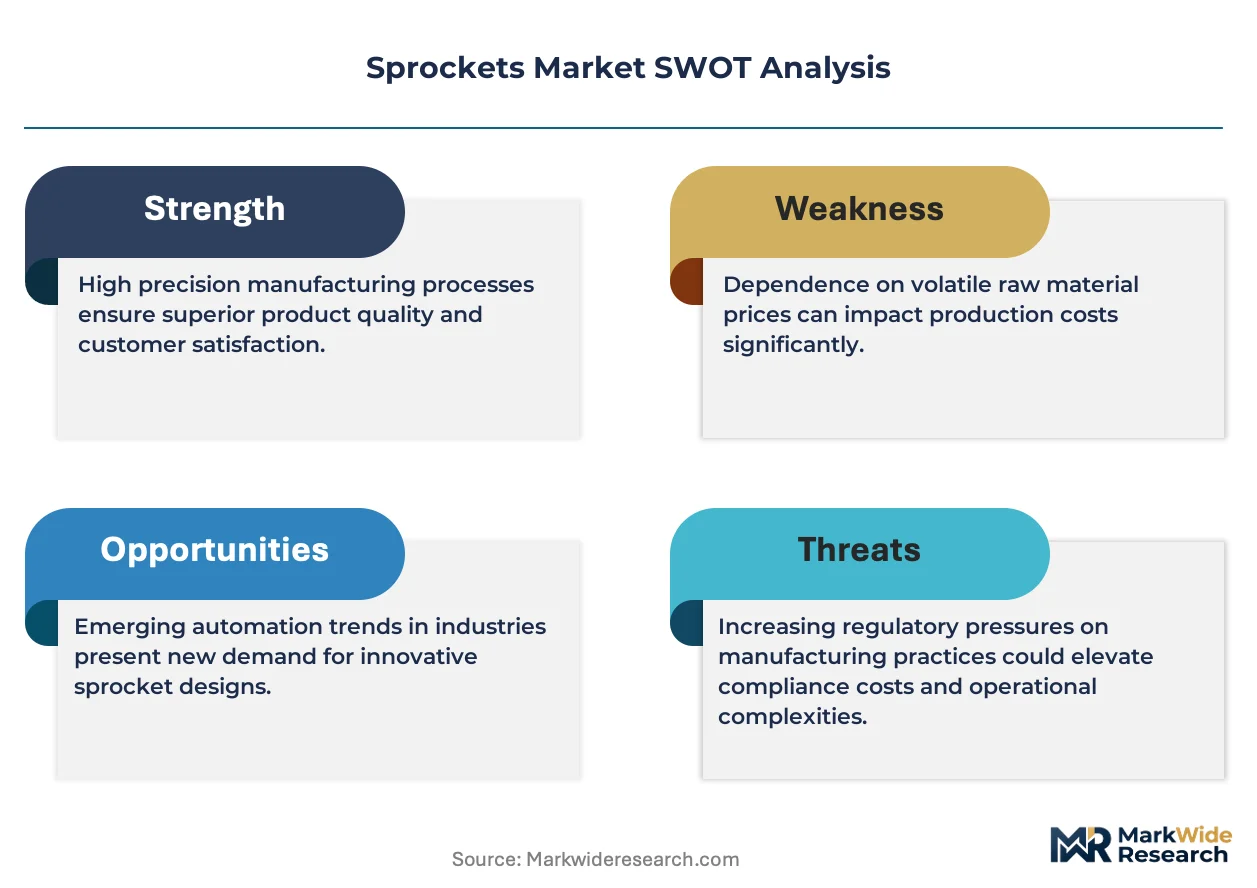
- REACH and RoHS compliance:European surface coating restrictions are accelerating migration from hexavalent chromium to trivalent and composite alternatives, opening specification windows for qualified suppliers.
- E-commerce fulfillment infrastructure:Amazon, Alibaba, and regional logistics operators are commissioning precision conveyor systems requiring 45-55 HRC hardened sprockets in 25-200 mm pitch ranges.
- Induction hardening process automation:Japanese and German equipment OEMs are deploying in-line heat treatment systems that reduce tooth surface variability below 2 HRC deviation.
Market Restraints
- Scrap steel price volatility:Input cost swings of 15-40% within single quarters compress margin predictability for gray iron and carbon steel casting operations.
- Supply concentration in East Asian forging:Taiwan, South Korea, and mainland China control 60-70% of precision-cut sprocket blank capacity, creating single-source vulnerability.
- Polymer belt substitution in light-load automation:Timing belts and synchronous drive systems are capturing sub-5 kW power transmission applications previously served by roller chain.
Strategic Opportunities
- India PLI scheme for capital goods:Production-linked incentives for machinery manufacturing are drawing sprocket forging investments to Pune and Chennai industrial corridors.
- Food-grade stainless sprockets:USDA and 3-A Sanitary Standards compliance is creating premium positioning for 316L and 17-4 PH variants in dairy and protein processing.
- Additive manufacturing convergence with CNC hardening:Hybrid production workflows are enabling low-volume custom tooth profiles without dedicated forging dies.
Industry Challenges
- Metallurgical technician scarcity:Induction coil design and pyrometric control expertise is retiring faster than vocational programs in Germany, Japan, and the US can replenish.
- ISO 606 revision alignment:Pending tolerance updates for high-speed automation sprockets are forcing recertification investments before demand materializes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sprockets Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Strand, Double Strand, Triple Strand, Specialty Sprockets Material: Steel, Aluminum, Plastic, Composite Application: Automotive, Industrial Machinery, Conveyor Systems, Robotics Size: Small, Medium, Large, Custom |
| Companies Covered | The Timken Company, Martin Sprocket & Gear, Inc., Tsubakimoto Chain Co., Ltd., KMC Chain Industrial Co., Ltd., Diamond Chain & Manufacturing Co., Renold plc, Rexnord Corporation, Regina S.p.A., SKF AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sprockets Market Evolving Landscape
Digital thread integration from CAD tooth profile to CNC hobbing is collapsing design-to-delivery timelines. Surface engineering advances and procurement model evolution are simultaneously reshaping technical specifications and commercial relationships.
Split-type sprocket hubs with interchangeable tooth rings are modularizing field maintenance protocols in mining and aggregate processing. Caterpillar and Komatsu fleet operators are specifying these configurations for conveyor drive stations where downtime costs exceed $50,000 per hour. The technology is modularizing supplier relationships, allowing end-users to hold hub inventory while sourcing tooth rings from competing machine shops.
EPA foundry emissions standards under MACT regulations are forcing US-based gray iron casting operations to install baghouse and thermal oxidizer systems. Compliance capital requirements of $2-8 million per facility are accelerating consolidation toward Ohio and Alabama operations with scale economics. Automotive timing chain suppliers are responding by qualifying Mexican and Canadian forging sources to maintain NAFTA-origin content ratios.
Buyer consolidation among industrial distributors is compressing supplier negotiation cycles from quarterly to monthly intervals. Motion Industries and Applied Industrial Technologies are unbundling technical specification-setting from procurement execution, deploying metallurgical engineers at regional hubs while centralizing purchasing. This pattern is most visible in Germany's Ruhr industrial belt, where family-owned Mittelstand distributors are selling to private equity platforms seeking procurement leverage.
Sprockets Market Segmentation
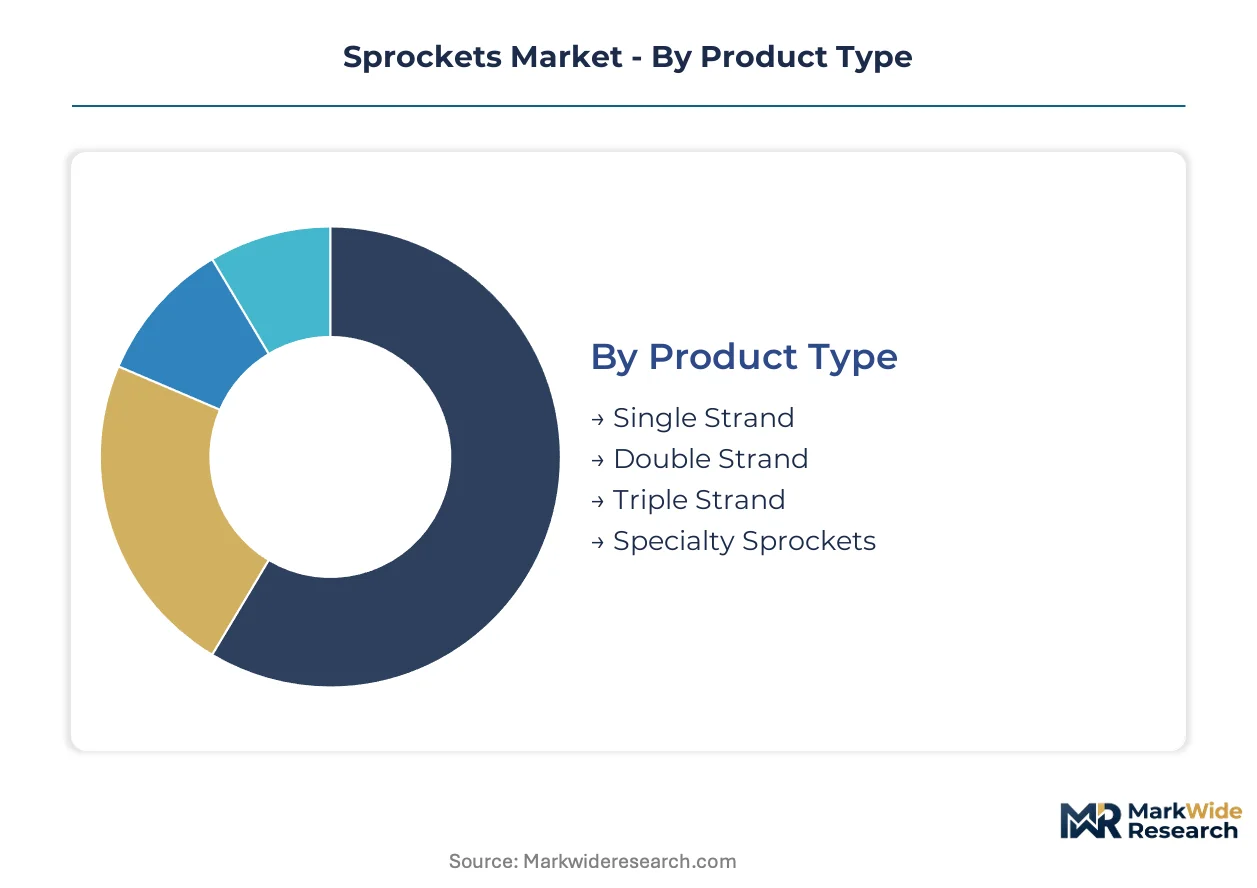
Sprocket specification varies sharply by integration depth. Standalone replacement units dominate aftermarket volume, while embedded precision assemblies command OEM specification authority and longer contract cycles.
Product Type:
Single strand configurations anchor standalone conveyor drives, while double and triple strand variants embed into integrated power transmission systems requiring synchronized shaft operation.
- Single Strand:Standard tooth profiles with 25-200 mm pitch diameters serve bulk material handling and light industrial drives. Amazon fulfillment centers in Germany specify induction-hardened variants for 24/7 conveyor operation.
- Double Strand:Paired tooth rows transmit higher torque loads through balanced chain engagement. Automotive timing system suppliers in Stuttgart and Munich require 45-55 HRC surface hardness with sub-2 HRC deviation tolerances.
- Triple Strand:Heavy mining and aggregate processing equipment deploy these for extreme load distribution.
- Specialty Sprockets:Custom tooth geometries for robotics and high-speed automation command premium positioning due to tight tolerances.
Volume placements concentrate in Single Strand; the faster expansion belongs to Specialty Sprockets.
Material:
Cost tier stratification separates load-bearing specifications from weight-sensitive and corrosion-resistant applications.
- Steel:Carbon and alloy grades undergo induction or flame hardening to achieve 45-55 HRC tooth surfaces. German forging operations automate heat treatment to reduce surface variability below 2 HRC deviation.
- Aluminum:6061-T6 and 7075 variants serve robotics and aerospace linkages where mass reduction offsets lower wear resistance.
- Plastic:Nylon and acetal formulations gain traction in food-grade conveyors requiring USDA compliance and cleanability.
- Composite:Carbon-fiber reinforced polymers target prototype automation and specialized lightweight drives.
Steel retains absolute volume dominance; Aluminum is climbing the fastest among alternative materials.
Application:
Customer type segmentation separates OEM specification-setting from aftermarket replacement procurement patterns.
- Automotive:Engine timing systems and transmission drives require precision tooth profiles with ISO 606 tolerance compliance.
- Industrial Machinery:Machine tools and packaging equipment specify modular hub-and-tooth-ring assemblies to compress maintenance downtime.
- Conveyor Systems:E-commerce fulfillment infrastructure in Germany, the US, and Japan drives procurement of hardened precision units in 25-200 mm pitch ranges.
- Robotics:High-speed automation and collaborative robot joints demand specialty tooth geometries with tight tolerances and low backlash.
Industrial Machinery captures the largest installed base; Robotics shows the steepest expansion trajectory.
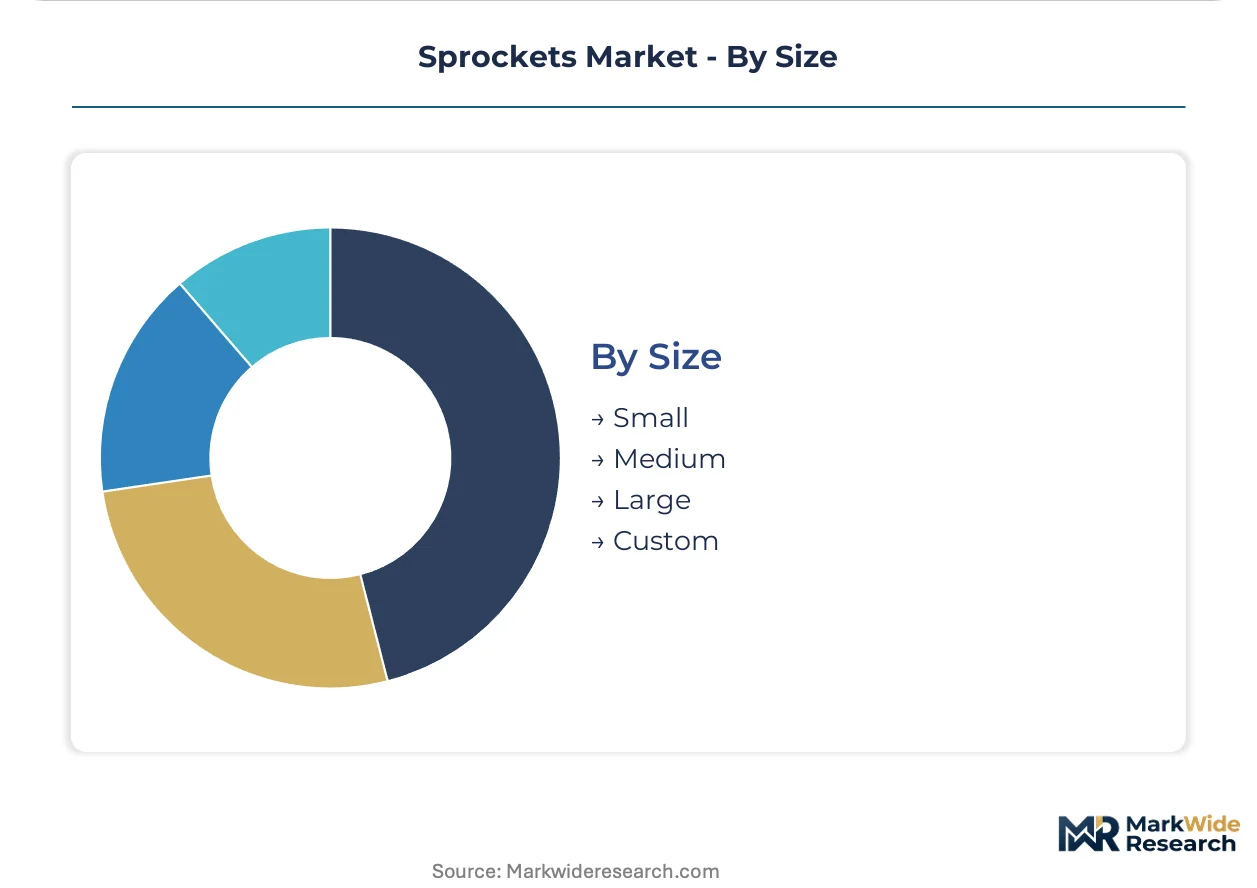
Size:
Supply concentration varies by manufacturing process scalability across dimensional ranges.
- Small:Precision-cut blanks under 100 mm pitch diameter dominate robotics and light automation.
- Medium:100-400 mm units serve standard industrial drives and automotive auxiliary systems.
- Large:Heavy industrial units exceeding 400 mm pitch diameter require dedicated forging capacity concentrated in German and Japanese operations.
- Custom:Non-standard tooth profiles and bore configurations address specialized mining and marine applications.
Medium sizes hold the deepest volume penetration; Custom specifications are gaining share fastest in premium industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Pune and Chennai under India's PLI scheme for capital goods are drawing sprocket forging investments away from traditional East Asian supply bases. Germany's Ruhr industrial belt and Japan's Chubu region maintain premium specification authority through automated heat treatment clusters.
Germany
Automotive OEMs in Stuttgart and Munich anchor demand for 45-55 HRC hardened sprockets with sub-2 HRC deviation tolerances. REACH and RoHS compliance restricts hexavalent chromium surface coatings, accelerating migration to trivalent alternatives. The Ruhr industrial belt concentrates precision forging operations with in-line induction hardening automation.
United States
Amazon fulfillment centers and logistics operators commission precision conveyor systems requiring hardened sprockets in 25-200 mm pitch ranges. EPA foundry emissions standards under MACT regulations force gray iron casting operations to install baghouse systems. Ohio and Alabama operations consolidate as compliance capital requirements of $2-8 million per facility accelerate regional concentration.
Japan
High-speed automation and robotics manufacturers in the Chubu region demand specialty tooth geometries with tight tolerances. METI industrial standards govern precision chain-and-sprocket dimensional interchangeability. Japanese equipment OEMs deploy in-line heat treatment systems that reduce tooth surface variability below 2 HRC deviation.
India
Production-linked incentives for machinery manufacturing under the PLI scheme attract forging investments to Pune and Chennai industrial corridors. BIS standards alignment with ISO 606 governs roller chain and sprocket dimensional specifications. Domestic automotive and conveyor system assemblers are qualifying local forging sources to reduce import dependency.
China
Dual carbon goals and MEE emissions frameworks reshape foundry economics in Shandong and Jiangsu provinces. GB standards for mechanical power transmission components govern domestic specification requirements. Precision-cut sprocket blank capacity concentrates in Taiwan-linked supply chains facing single-source vulnerability pressures.
Sprockets Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered specification bands. The vendor base separates into three strategic archetypes: integrated chain-and-sprocket engineering houses, bearing-service network extenders, and stock-and-ship distribution dominators. Competitive moves concentrate on modular hub-and-tooth-ring portfolio expansion and automated heat treatment capability acquisition.
Among North American stock-and-ship distributors, Martin Sprocket & Gear, Inc. occupies a position exemplifying replacement channel dominance through extensive distribution networks. Tsubakimoto Chain Co., Ltd. represents the integrated engineering archetype, while SKF AB sits within the bearing-service extension tier. These three anchors illustrate how category boundaries blur as technical specification-setting unbundles from procurement execution.
| Leading Market Players |
|---|
| The Timken Company |
| Martin Sprocket & Gear, Inc. |
| Tsubakimoto Chain Co., Ltd. |
| KMC Chain Industrial Co., Ltd. |
| Diamond Chain & Manufacturing Co. |
| Renold plc |
| Rexnord Corporation |
| Regina S.p.A. |
| SKF AB |
| Others |
Value Network & Pricing Analysis
Modular sprocket-and-hub assembly procurement from Amazon and Alibaba fulfillment networks is compressing supplier lead time tolerances and forcing distributors to hold finished goods inventory closer to end-use points, elevating working capital costs that transmit into premium pricing for same-day and next-day availability tiers.
Pricing Analysis
Expedited lead time premiums of 15-30 percent above standard contract pricing apply to induction-hardened precision units required within 48-72 hours, while spot inventory liquidation from distributor overstock channels commands 10-20 percent discounts below catalog list. Three-tier pricing structure across premium, standard, and economy levels separates ISO 606-certified automotive timing system grades from general industrial conveyor specifications and uncertified gray iron replacement units. Pricing pressure stems from scrap steel input volatility and buyer consolidation among Motion Industries and Applied Industrial Technologies, which compresses negotiation cycles and squeezes margin predictability. Aftermarket maintenance procurement teams exhibit highest price sensitivity, while OEM specification engineers prioritize hardness consistency and sub-2 HRC deviation tolerances over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive timing system suppliers in Stuttgart and Munich, while stock-and-ship distributors serve fragmented aftermarket replacement procurement across North American industrial corridors. Geographic supply concentration centers on Taiwan, South Korea, and mainland China for precision-cut sprocket blank capacity, with German and Japanese operations controlling automated heat treatment and surface hardening. Raw material dependencies rest on scrap steel and alloy steel bar stock, with induction coil equipment and pyrometric control systems feeding from Japanese and German equipment OEMs. Single-source vulnerability pervades the East Asian forging base, where 60-70 percent of precision blank capacity concentrates in Taiwan-linked supply chains exposed to geopolitical disruption. Distribution runs through regional industrial distributors holding hub inventory while sourcing tooth rings from competing machine shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive heat treatment capability and precision forging capacity represents the decisive competitive race in this market, as automated induction hardening expertise retires faster than vocational programs in Germany, Japan, and the US can replenish technical talent pipelines.
For Market Incumbents: To counter metallurgical technician scarcity and tier-two foundry automation gaps, Martin Sprocket & Gear and Tsubakimoto Chain should acquire automated induction hardening equipment OEMs or exclusive coil design partnerships in Germany and Japan. Securing captive supply of precision-cut blanks through backward integration into Taiwanese or South Korean forging operations mitigates single-source vulnerability. For New Entrants and Emerging Players: Regional industrial distributors in India's Pune and Chennai corridors offer the most penetrable channel partner type for qualification under PLI scheme incentives, with local automotive and conveyor system assemblers actively seeking to reduce import dependency from East Asian sources. Specialty sprockets for robotics and high-speed automation command disproportionate margin pools due to tight tolerances and low-volume production economics. For Investors and Strategic Acquirers: The window for entry favors mid-cap forging operations with automated heat treatment clusters in Germany's Ruhr belt or Japan's Chubu region, where specification authority and OEM relationships concentrate. Automated induction hardening capability with sub-2 HRC deviation consistency serves as the primary acquisition target archetype. Watch for ISO 606 revision recertification deadlines as inflection indicators forcing consolidation among unprepared tier-two suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Heat Treatment Acquisition | Captures sub-2 HRC deviation capability that automotive OEMs in Stuttgart mandate. |
| Modular Hub-and-Tooth-Ring Portfolio Expansion | Aligns with Caterpillar and Komatsu fleet specifications for sub-50,000 dollar downtime costs. |
| India PLI Scheme Qualification | Positions forging investments in Pune and Chennai to serve domestic automotive assemblers. |
| REACH-Compliant Surface Coating Migration | Opens specification windows as hexavalent chromium restrictions accelerate trivalent adoption. |
| Additive Manufacturing Convergence | Enables low-volume custom tooth profiles without dedicated forging die capital. |
Research Methodology
Multi-period observation of procurement cycle compression, heat treatment automation deployment, and distributor consolidation patterns anchored the trend analysis, supplemented by interviews with maintenance directors at mining and aggregate processing operations, OEM procurement teams at automotive timing system suppliers, aftermarket service heads at industrial distributors, and plant engineers at e-commerce fulfillment centers. Secondary validation drew from SEC 10-K filings of listed power transmission component manufacturers, German KBA machinery registration data, Japanese METI industrial production indices, US EPA MACT compliance disclosures, and ISO 606 standard revision documentation. Bottom-up segment sizing triangulated against top-down macroeconomic industrial production indices.
Input-output matrices modeled demand drivers across product type, material grade, application sector, and dimensional size tier, with cross-elasticities estimated between roller chain and synchronous belt substitution threats. Volume and value outputs across the analysis window derived from installed base depreciation schedules, replacement cycle compression factors, and OEM specification win rates. Industry-specific forecast inputs included e-commerce fulfillment center capex pipelines from Amazon and Alibaba, automotive timing system platform standardization roadmaps, and robotics automation deployment trajectories in the Chubu region.
Caveats apply where scrap steel price volatility, REACH and RoHS regulatory expansion, or polymer belt substitution acceleration could materially shift the outlook beyond modeled scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Enabled Healthcare Services Market
Others
Space Power Supply Market
Others
Storage Dewars Market
Others
South Asia Geosynthetics Market
Others
Inflight Entertainment Solutions Market
Others
North America Agricultural Enzymes Market
Others
Video Encoder Market
Others
UAE Location-Based Services Market
Others
India Home Automation Market
Others
Digital Signage Media Player Market
Others
Idaas Market
Others
Global Computer Peripherals Market
Others
Nuclear Power Cables Market
Others
Advertising Intelligence Solution Market
Others
Software Synthesizers Market
Others
Global Surface Analysis Market