
 Global Flexible PVC Films Market | 2026-2036
Global Flexible PVC Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible PVC Films Market Foresight
The EU F-Gas Regulation and downstream buyer mandates from European automotive OEMs is consolidating demand toward lower-emission, recyclable film formulations. RENOLIT SE leverages its integrated calendering and extrusion footprint across Germany and Spain to sustain supply continuity for medical and construction grades. Teknor Apex Company anchors North American specialty compounding with customized flexible PVC alloys for healthcare and consumer applications. Mondorevive S.p.a. competes through post-industrial recycling loops that differentiate its Italian-produced films in premium packaging channels.
Flexible PVC films are thermoplastic sheets manufactured by calendering or extrusion of polyvinyl chloride resin blended with plasticizers, stabilizers, and additives, typically ranging from 0.05 mm to 1.0 mm in thickness, engineered for conformability, chemical resistance, and weldability across packaging, protective covering, and decorative surfacing applications. Transparent Films dominate pharmaceutical blister and food visibility packaging due to established clarity standards and thermoforming compatibility, while Printed Films represent the fastest-growing category as brand owners convert from rigid to flexible decorated formats for shelf differentiation. Metallized Films command margin concentration in barrier-sensitive segments such as pharmaceutical desiccant pouches and extended-shelf-life food wraps where oxygen and moisture transmission rates determine specification compliance.
The US FDA enforces extractables and leachables testing for films contacting pharmaceuticals and food, pushing converters toward compliant additive packages and documented supply chain traceability. ECHA's REACH restrictions on phthalate plasticizers and the EU MDR's heightened scrutiny of medical device materials are forcing reformulation investments across European supply chains. China's SAMR and GB standards for food-contact plastics create parallel compliance architectures for exporters serving Asian manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation specialization or unified global product platforms deliver superior returns.
Market Dynamics
Phthalate migration bans across multiple jurisdictions are forcing simultaneous reformulation of plasticizer packages while converters scramble to qualify alternative chemistries without disrupting existing supply contracts.
Growth Catalysts
- Healthcare packaging sterilization demand:Hospitals and medical device manufacturers in Germany, India, and the United States are expanding orders for sterilizable barrier films to meet surgical kit and pharmaceutical packaging specifications.
- REACH phthalate restrictions:ECHA's accelerating timeline for restricted substance lists is pulling converters toward citrate-based and bio-plasticizer alternatives ahead of compliance deadlines.
- Calendering technology advancement:Modern multi-roll calendering lines achieve tighter thickness tolerances, enabling thinner gauge films that reduce resin consumption per square meter.
Market Restraints
- Plasticizer cost volatility:Epoxidized soybean oil and citrate ester prices fluctuate with agricultural commodity cycles, compressing converter margins during feedstock spikes.
- Supply concentration in German calendering:A disproportionate share of European medical-grade capacity sits within 200 kilometers of Cologne, creating geographic risk concentration.
- Technical limitations of bio-alternatives:Current non-phthalate plasticizers exhibit inferior low-temperature flexibility compared to DINCH formulations, restricting cold-chain applications.
Strategic Opportunities
- Underpenetrated Indian domestic market:Per-capita flexible film consumption in Maharashtra and Gujarat remains below Southeast Asian benchmarks, offering volume expansion potential as local packaging converters scale.
- EU F-Gas Regulation tailwind:Automotive OEM mandates for lower-emission interior materials are opening specification windows for specialized low-VOC film grades in seating and dashboard applications.
- Post-industrial recycling convergence:Integration of mechanical recycling loops with virgin calendering lines enables margin capture from sustainability premiums in Italian and French premium packaging channels.
Industry Challenges
- Extractables testing timeline compression:US FDA documentation requirements for pharmaceutical contact applications extend qualification cycles to 18-24 months, freezing formulation changes.
- Multi-jurisdiction compliance complexity:Simultaneous adherence to REACH, FDA, and SAMR additive restrictions demands parallel testing protocols that strain technical service resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible PVC Films Market |
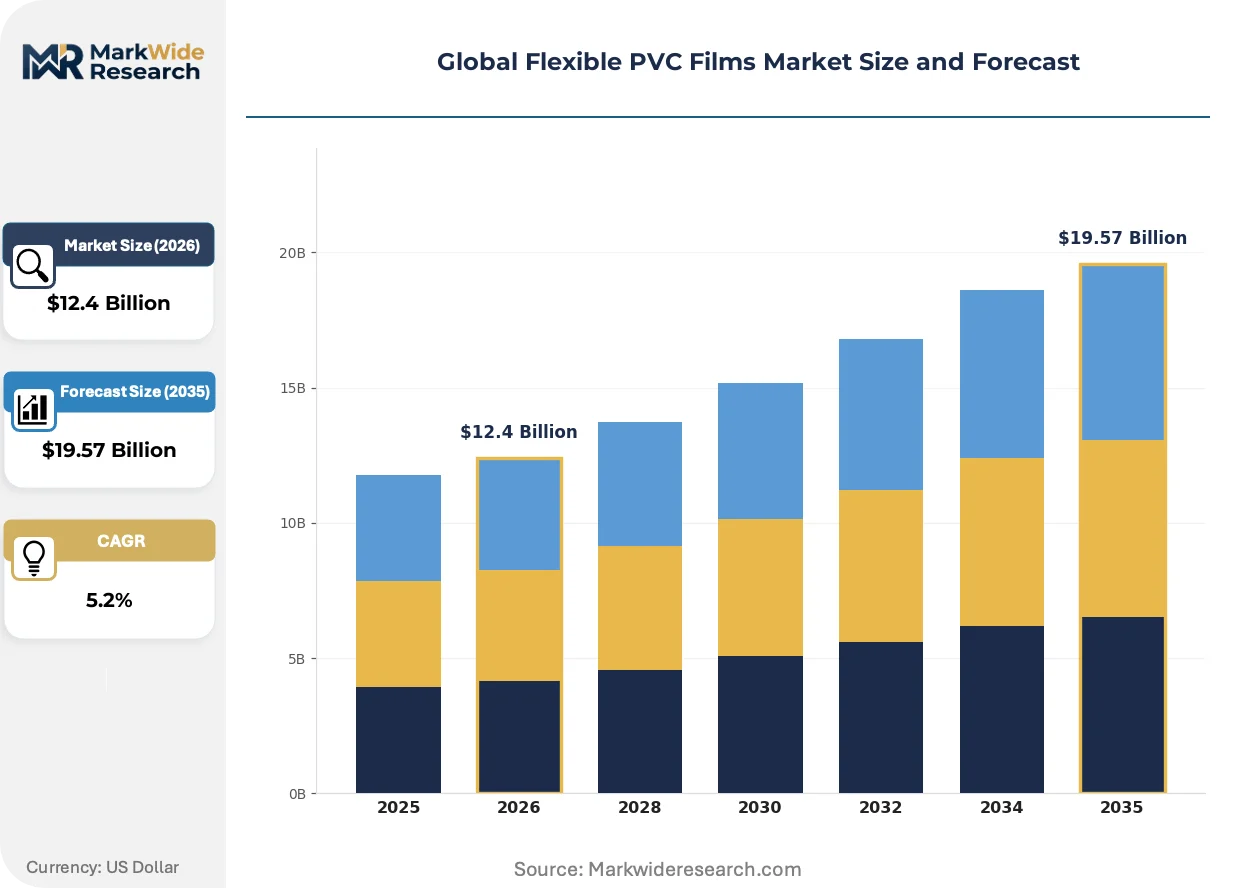
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $19.57 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Colored Films, Printed Films, Textured Films, Metallized Films Application: Packaging, Building Envelope, Automotive Interiors, Healthcare Packaging, Consumer Goods Wrapping End User Industry: Food & Beverage, Construction, Transportation, Pharmaceutical, Personal Care Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Exporters |
| Companies Covered | RENOLIT SE, Teknor Apex Company, Mississippi Polymers, Caprihans India Limited, ACG, Canadian Speciality Vinyls, South Asia Plastics Group, ZHONGSHAN LIN-YANG PLASTIC CO.LTD., Mondorevive S.p.a., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible PVC Films Market Shifts & Advancements
Reformulation chemistry and processing automation are converging to address regulatory pressure while opening new specification windows in medical and automotive segments.
Non-phthalate plasticizer systems based on cyclohexane dicarboxylates and bio-derived esters are rewriting the technical baseline for flexible PVC films in pharmaceutical blister packs. Medical packaging converters in Switzerland and Germany are qualifying these alternatives at accelerated pace to preempt REACH enforcement. The shift is compressing demand for legacy DINP and DEHP formulations while creating specification divergence between European and export-oriented product lines.
ECHA's REACH Annex XVII restrictions on four phthalate plasticizers are forcing compounders to maintain dual formulation portfolios. Medical device manufacturers face heightened scrutiny under the EU MDR's materials documentation requirements, extending supplier qualification timelines. Pharmaceutical packaging segments in France and the Netherlands are responding by consolidating purchases with converters holding pre-validated non-phthalate certificates.
Hospital procurement departments are consolidating flexible film purchasing through centralized tendering platforms that unbundle converter relationships from distributor networks. This behavior concentrates volume with large-scale calendering operations capable of multi-site supply guarantees. The pattern is most visible in German hospital purchasing cooperatives and is spreading to National Health Service supply frameworks in the United Kingdom.
Global Flexible PVC Films Market Segmentation
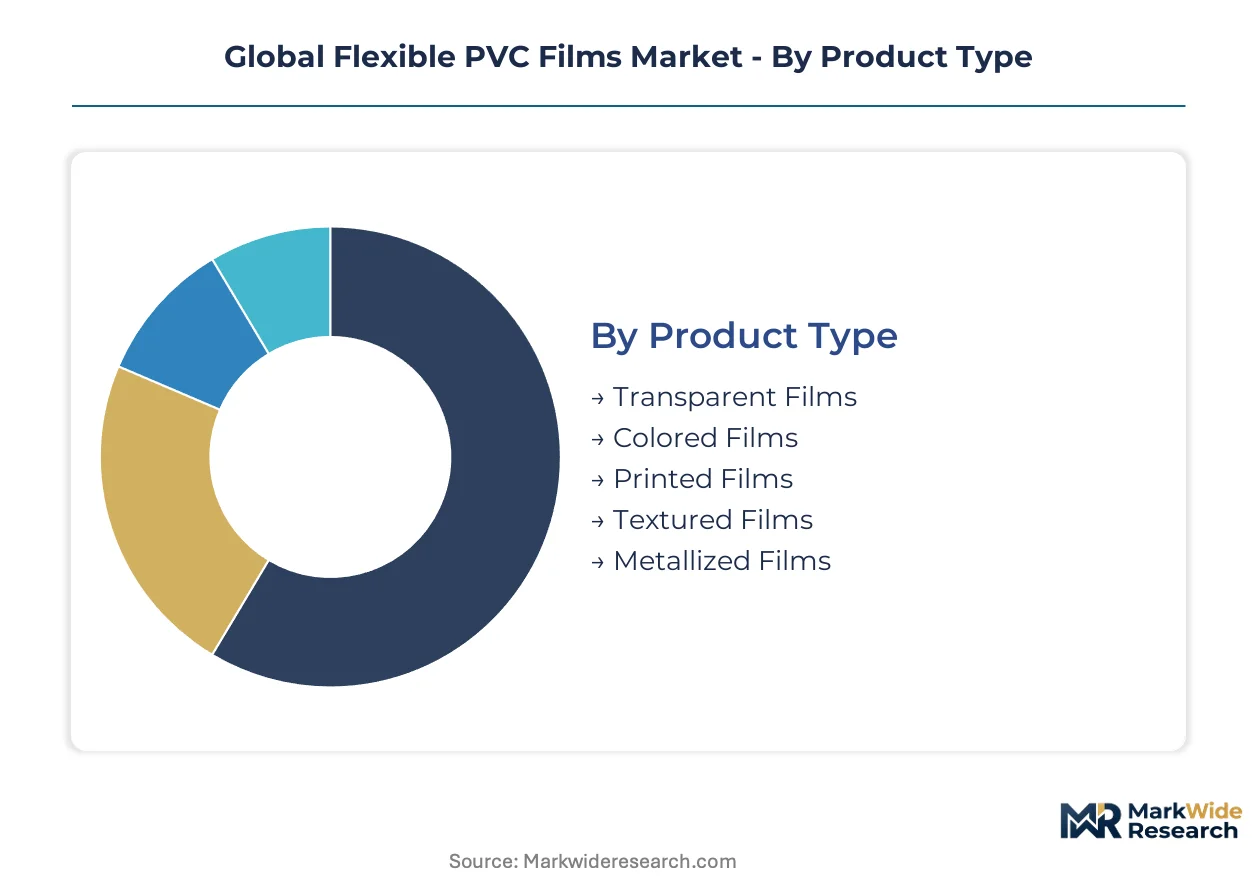
Flexible PVC film specifications diverge sharply across end-use requirements, with calendering tolerances, plasticizer loadings, and surface treatments determining qualification for medical, food-contact, or automotive applications. Segmentation reveals how converters align product portfolios against regulatory thresholds and buyer consolidation patterns.
Product Type:
Calendering and extrusion technologies produce distinct film architectures optimized for clarity, decoration, or barrier performance.
- Transparent Films:Unpigmented formulations with tight thickness control (0.05–0.25 mm) serve pharmaceutical blister packs and fresh food visibility packaging where thermoforming compatibility and optical clarity meet FDA and EFSA extractables standards. German and Swiss medical packaging converters concentrate specification authority here.
- Printed Films:Surface-treated substrates accepting solvent-based or UV-cured inks enable brand differentiation in flexible decorated formats, with French and Italian premium food brands driving specification shifts from rigid to flexible decorated packaging. This segment climbs fastest as shelf differentiation demands intensify.
- Colored Films:Pigmented calendered sheets serve decorative surfacing and identification coding in construction and consumer goods applications.
- Textured Films:Embossed surface finishes provide slip resistance and tactile differentiation in automotive interior laminates and specialty packaging.
- Metallized Films:Vacuum-deposited aluminum layers create oxygen and moisture barriers for pharmaceutical desiccant pouches and extended-shelf-life food wraps where transmission rate compliance commands margin premiums.
Transparent Films lead on scale; Printed Films lead on momentum.
Application:
Demand concentration tracks regulatory intensity and buyer procurement consolidation across medical, automotive, and construction verticals.
- Packaging:General-purpose flexible wrapping spans food, industrial, and retail formats with specifications varying by contact sensitivity and shelf-life requirements.
- Building Envelope:Weather-resistant membranes and vapor barriers in roofing and cladding applications demand UV-stabilized formulations with 10+ year durability ratings.
- Automotive Interiors:Low-VOC film grades for seating, dashboard surfacing, and door panels face EU F-Gas Regulation and OEM mandates for reduced emissions and recyclability, with German and Spanish supply chains capturing specification windows.
- Healthcare Packaging:Sterilizable barrier films for surgical kits, pharmaceutical blisters, and medical device pouches require documented extractables testing and REACH-compliant plasticizer packages; hospital purchasing cooperatives in Germany and NHS frameworks in the United Kingdom concentrate volume with qualified converters.
- Consumer Goods Wrapping:Decorative and protective films for electronics, cosmetics, and household products compete on printability and tactile surface quality.
Healthcare Packaging commands the steepest expansion trajectory; Building Envelope maintains the most stable volume base.
End User Industry:
Industry-specific compliance architectures shape formulation investments and supplier qualification timelines.
- Food & Beverage:Films contacting edibles face FDA, EFSA, and FSSAI additive restrictions with parallel testing protocols for exporters serving multiple jurisdictions.
- Construction:Roofing membranes and interior surfacing prioritize weathering resistance and fire performance over migration testing, with demand clustering in German and Spanish building material distribution.
- Transportation:Automotive and mass transit interior specifications emphasize low-fogging, abrasion resistance, and OEM sustainability scorecards.
- Pharmaceutical:Blister packs, desiccant pouches, and sterile barriers demand the most intensive documentation, with 18–24 month qualification cycles freezing formulation changes and consolidating purchases with pre-validated converters.
- Personal Care:Cosmetic and hygiene product wrapping balances decoration with chemical resistance to fragrances and oils.
Pharmaceutical extracts the highest margins; Food & Beverage generates the broadest volume.
Distribution Channel:
Channel structure reflects buyer scale, technical service requirements, and geographic reach needs.
- Direct Sales:Large-scale converters and brand owners with dedicated technical service requirements purchase directly from calendering operations, particularly in German hospital purchasing cooperatives and NHS supply frameworks.
- Distributors:Regional stocking intermediaries serve mid-tier converters requiring smaller minimum order quantities and local inventory availability.
- Online Retailers:E-commerce platforms capture spot purchases and specialty grades for small converters and job shops.
- Wholesalers:Bulk aggregation channels serve construction and industrial applications with standardized specifications and price-sensitive procurement.
- Exporters:Cross-border traders bridge supply from Indian and Chinese manufacturing clusters to Southeast Asian, Middle Eastern, and African buyers.
Direct Sales captures the highest value concentration; Exporters gain share fastest in emerging demand centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible PVC film manufacturing originated in German industrial centers during the mid-20th century, with calendering technology spreading subsequently to North American and Asian production clusters. Today the industry maintains distinct regional specializations shaped by regulatory frameworks and end-use demand concentration.
Germany
Medical-grade film specifications from hospital purchasing cooperatives and automotive OEM low-VOC mandates drive demand concentration. ECHA REACH Annex XVII phthalate restrictions force compounders toward cyclohexane dicarboxylate alternatives. The Cologne-Düsseldorf corridor hosts disproportionate European calendering capacity for healthcare and construction grades.
United States
FDA extractables testing requirements for pharmaceutical contact applications extend supplier qualification timelines to 18-24 months. Hospital procurement consolidation through centralized tendering platforms concentrates volume with large-scale converters. The Ohio River Valley and Gulf Coast regions maintain specialty compounding operations for healthcare and consumer film alloys.
India
Domestic packaging converters in Maharashtra and Gujarat scale capacity to serve Southeast Asian and Middle Eastern export markets. BIS standards for food-contact plastics create compliance architecture parallel to FDA and REACH regimes. Per-capita flexible film consumption remains below regional benchmarks, offering volume expansion potential as local demand matures.
China
SAMR and GB standards for food-contact plastics establish testing protocols for exporters serving Asian manufacturing clusters. Yangtze River Delta and Pearl River Delta production bases supply regional converters with standardized and specialty grades. Domestic automotive interior specifications increasingly incorporate low-emission requirements aligned with EU F-Gas Regulation precedents.
Italy
Premium packaging channels in France and the Netherlands source films with documented post-industrial recycling content. EU MDR materials documentation requirements extend medical device supplier qualification timelines. Northern Italian calendering operations integrate mechanical recycling loops with virgin production lines to capture sustainability premiums.
Global Flexible PVC Films Market Competitive Landscape
Capital-heavy calendering operations compete with asset-light converters and specialty compounders across differentiated specification tiers. The vendor base organizes around three strategic archetypes: integrated resin-to-film producers with captive plasticizer supply, independent calendering specialists serving medical and automotive qualification channels, and regional converters leveraging distributed extrusion assets for packaging volume. Dominant competitive moves include backward integration into plasticizer compounding to secure non-phthalate formulation supply, and geographic expansion into Indian and Southeast Asian demand centers to bypass European regulatory cost structures.
Among European integrated producers, RENOLIT SE exemplifies the calendering-specialist archetype with cross-border manufacturing footprint. Teknor Apex Company anchors North American specialty compounding capabilities for customized flexible PVC alloys. Mondorevive S.p.a. represents the sustainability-differentiated tier through Italian-based post-industrial recycling integration.
| Leading Market Players |
|---|
| RENOLIT SE |
| Teknor Apex Company |
| Mississippi Polymers |
| Caprihans India Limited |
| ACG |
| Canadian Speciality Vinyls |
| South Asia Plastics Group |
| ZHONGSHAN LIN-YANG PLASTIC CO.LTD. |
| Mondorevive S.p.a. |
| Others |
Supply & Pricing Matrix
Hospital purchasing cooperatives in Germany and NHS supply frameworks in the United Kingdom concentrate procurement volume with large-scale calendering operations, locking in contract-based long-term offtake agreements that compress spot-market liquidity and anchor pricing power with qualified converters holding REACH-compliant certificates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade films with FDA extractables documentation from general-purpose packaging grades and commodity construction sheeting. Certification grade and volume scale drive price differentiation, with pharmaceutical blister specifications commanding substantial premiums over food-contact films. Pricing pressure stems from agricultural commodity volatility in bio-plasticizer feedstocks, squeezing converter margins on non-phthalate formulations. Construction and industrial wrapping segments exhibit highest price sensitivity, while pharmaceutical and medical device packaging buyers prioritize qualification security over unit cost.
Supply Chain Analysis
REACH Annex XVII compliance certificates and FDA extractables documentation function as gating mechanisms that restrict supply base participation in premium tiers. Manufacturing concentrates in Germany, the United States, and India, with the Cologne-Düsseldorf corridor hosting disproportionate European medical-grade capacity. Raw material sourcing draws from petrochemical resin producers, epoxidized soybean oil suppliers, and specialty stabilizer compounders. Single-source vulnerability concentrates around German calendering operations serving hospital purchasing cooperatives. Distribution runs through direct sales relationships with large converters, supplemented by regional distributors for mid-tier packaging volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory cost divergence between REACH-compliant European supply chains and Indian manufacturing clusters creates geographic-arbitrage opportunities for converters repositioning capacity to serve Southeast Asian and Middle Eastern export markets.
For Market Incumbents: Anchor medical-grade qualification advantages by accelerating backward integration into non-phthalate plasticizer compounding to secure formulation supply against REACH enforcement timelines. Expand calendering footprint in Maharashtra and Gujarat to capture volume growth in underpenetrated domestic Indian packaging demand while defending margin position against emerging Asian converters. For New Entrants and Emerging Players: Begin with post-industrial recycling integration in Italian and French premium packaging channels, where sustainability premiums offset capital intensity barriers. Target printed films for premium food brands seeking shelf differentiation, leveraging surface treatment capabilities as entry wedge against established transparent film specialists. Pursue distributor partnerships rather than direct sales to bypass 18-24 month hospital qualification cycles. For Investors and Strategic Acquirers: Specialty chemical compounders with captive plasticizer technology represent the most active acquirer category in this space, seeking calendering assets to complete resin-to-film integration. Target mid-scale converters holding pre-validated non-phthalate certificates in pharmaceutical packaging tiers. Watch for inflection signals in ECHA enforcement intensity against legacy phthalate formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasticizer Compounding | Captive supply of cyclohexane dicarboxylate alternatives insulates against REACH-driven feedstock shortages. |
| Capacity Expansion in Indian Manufacturing Clusters | Maharashtra and Gujarat positioning captures per-capita consumption growth in domestic packaging demand. |
| Post-Industrial Recycling Loop Integration | Mechanical recycling convergence with virgin calendering lines captures sustainability premiums in French and Italian channels. |
| Long-term Supply Agreement with Hospital Purchasing Cooperatives | German and NHS framework contracts lock in volume concentration and compress competitor access. |
| Joint Venture for Bio-Plasticizer Feedstock Security | Epoxidized soybean oil supply partnerships hedge agricultural commodity volatility compressing converter margins. |
Research Methodology
Bottom-up healthcare packaging and automotive interior modeling reconciled against top-down calendering capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and Indian calendering operations, procurement leads at pharmaceutical packaging converters, hospital purchasing committee members, and technical R&D directors at specialty compounders informed demand and qualification dynamics. Secondary validation drew from ECHA REACH substance restriction updates, FDA extractables guidance documentation, BIS food-contact standards, customs trade data for PVC resin and film shipments, and SEC filings from listed chemical producers. Triangulation across these sources reconciled volume estimates with supply-side capacity assessments.
Input-output matrices mapped resin consumption, plasticizer loading rates, and calendering yield factors against end-use demand across the projection horizon. Segmentation dimensions modeled include film type architecture, application vertical, end-use industry compliance tier, and regional production hub. CAGRs were derived from regression analysis of historical volume trends against regulatory enforcement timelines and buyer consolidation patterns. Forecast inputs incorporated REACH Annex XVII implementation schedules, hospital procurement platform adoption rates, and automotive OEM low-VOC mandate penetration.
Several conditions sit outside the modeled scope, including sudden phthalate regulatory acceleration beyond published ECHA timelines, disruptive substitution by polyolefin barrier films in pharmaceutical applications, and extreme agricultural commodity price spikes in soybean oil feedstocks. Forecasts reflect documented assumptions about qualification cycle stability and buyer consolidation continuity. A model refresh is warranted upon material change in ECHA enforcement intensity or FDA extractables testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Military Sensors Software Market
Others
Programmatic Display Market
Others
Middle East Location-Based Services Market
Others
Wind and Solar Hybrid Street Light Market
Others
Asia-Pacific Military 4D Printing Market
Others
Asia-Pacific Telecom Transformers Market
Others
Hybrid Switchgear Market
Others
Global Personal Care Packaging Market
Others
PC As a Service Market
Others
Foldable Smartphone Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Brazil Lime Market
Others
Global Human Augmentation Market
Others
Powder Coating Equipment Market
Others
Molybdenum-99 Market