
 United Kingdom Co-Working Office Spaces Market | 2026-2036
United Kingdom Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Co-Working Office Spaces Market Analytics
Market Context
Premium-grade workspace specifications is reorganizing competitive dynamics across the United Kingdom co-working landscape. International Workplace Group plc leverages its extensive suburban portfolio to sustain occupancy rates outside London's core. The Office Group differentiates through design-led environments targeting professional services tenants. Huckletree specializes in sector-specific communities for technology and creative founders.
Technical Definition and Structural Segments
Co-working office spaces constitute commercial real estate facilities offering shared workstations, private suites, and collaborative areas through flexible membership agreements rather than traditional multi-year leases, typically incorporating high-speed connectivity, meeting infrastructure, and hospitality services as core functional parameters. Private Office deployments command superior yields per square metre compared to Hot Desk arrangements, reflecting enterprise demand for branded, secure environments within flexible portfolios. Freelancers and Startups anchor volume throughput in Membership-based plans, while Corporates increasingly migrate toward Monthly Plan structures for satellite team deployment.
Regulatory Framework
UK Health and Safety Executive guidelines govern workplace density and ventilation standards, directly influencing fit-out specifications and capacity calculations across operators. The Flexible Working Bill and local authority planning frameworks shape permissible use-class conversions and licensing requirements for shared workspace providers. Stakeholders must monitor evolving building safety regulations and permitted development rights that could accelerate or constrain supply expansion in key metropolitan zones.
Market Dynamics
The UK Flexible Working Bill is fundamentally restructuring lease economics across commercial real estate, compressing traditional ten-year commitments into rolling monthly agreements while forcing landlords to compete with amenity-rich co-working operators on speed-to-occupancy and service flexibility.
Growth Catalysts
- Hybrid Work Mandates:Enterprise technology and professional services firms now require satellite locations for distributed teams, directly expanding monthly plan subscriptions across Greater Manchester and Birmingham innovation corridors.
- Local Authority Planning Flexibility:Permitted development rights for office-to-coworking conversions in England's metropolitan zones accelerate supply expansion without full planning applications.
- SME Technology Clustering:Sector-specific demand from fintech and AI startups concentrates in London's Tech City, generating premium yields for operators offering high-performance connectivity infrastructure.
Market Restraints
- Commercial Mortgage Rate Exposure:Floating-rate debt structures across landlord portfolios compress operator margins as base rates reset quarterly.
- Prime Real Estate Concentration:Grade-A stock in London's core districts commands rents that absorb 35-45% of operator revenue, limiting expansion beyond established zones.
- Building Safety Compliance Burden:Post-Grenfell fire safety regulations impose extended remediation timelines on conversions of older commercial stock.
Strategic Opportunities
- Suburban Satellite Networks:Underpenetrated commuter belts surrounding Leeds, Bristol and Edinburgh present first-mover advantages for transit-adjacent locations.
- Net-Zero Retrofit Incentives:The UK Green Finance Strategy and local authority sustainability grants subsidize energy-efficient fit-outs that attract ESG-mandated corporate tenants.
- AI-Enabled Space Optimization:Convergence of occupancy sensors and predictive analytics enables dynamic pricing models that maximize yield per square metre across fluctuating demand patterns.
Industry Challenges
- Facilities Management Talent Scarcity:Qualified building operations managers with hospitality-hybrid skill sets command premium compensation in tight labour markets.
- Legacy Lease Integration Complexity:Operators acquiring distressed commercial assets face protracted negotiations with existing tenants holding below-market rents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Co-Working Office Spaces Market |
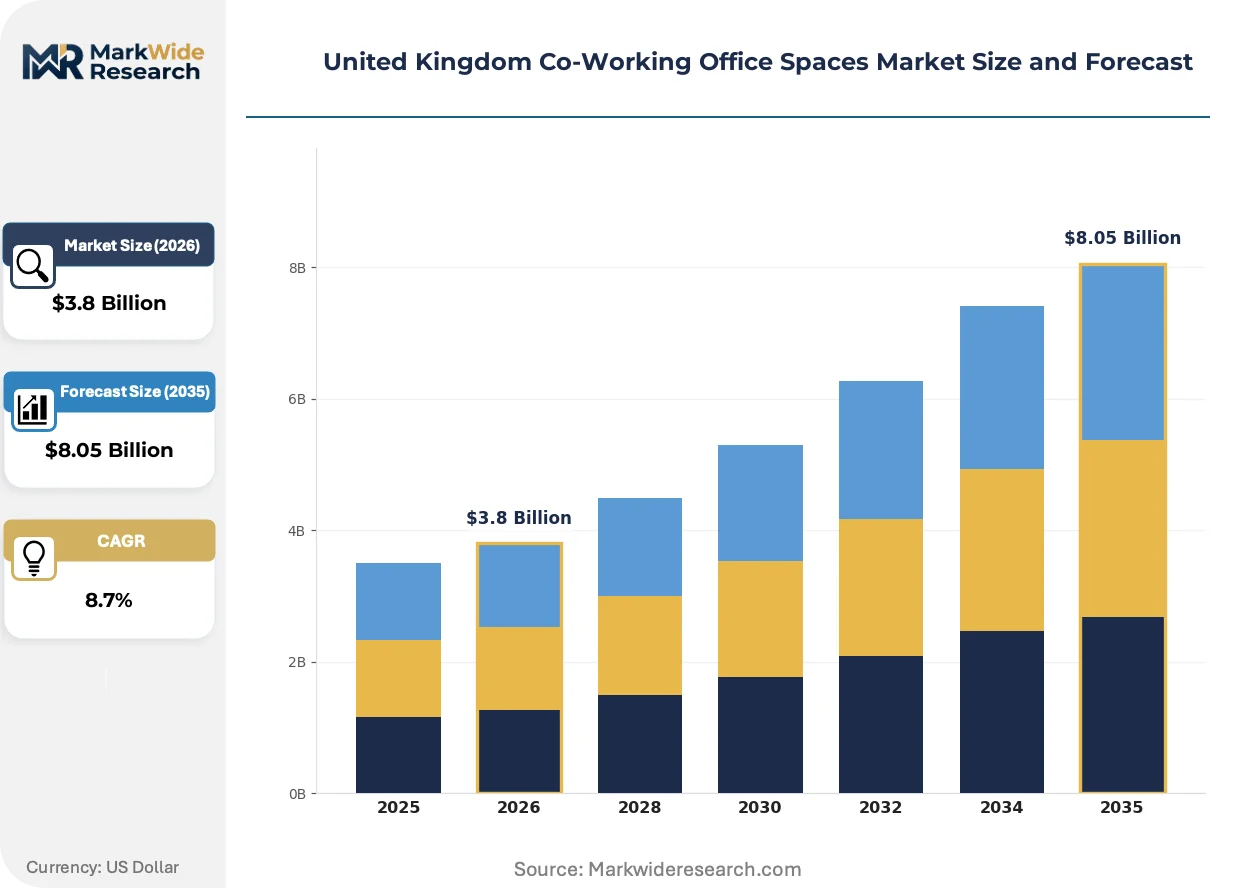
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated Desk, Hot Desk, Private Office, Meeting Room End User: Freelancers, Startups, SMEs, Corporates Service Type: Membership, Pay-as-you-go, Virtual Office, Events Pricing Model: Fixed Rate, Flexi Rate, Daily Rate, Monthly Plan |
| Companies Covered | International Workplace Group plc, WeWork, The Office Group, Landmark, Huckletree, Fora, Workspace Group PLC, Bizspace, Servcorp Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Co-Working Office Spaces Market Evolving Landscape
Workspace technology stacks are fragmenting traditional bundled service models, enabling modular procurement of connectivity, hospitality and meeting infrastructure as separate subscription tiers rather than fixed amenity packages.
Embedded IoT sensor networks is decomposing the conventional fixed-desk allocation model across UK operators. These systems capture real-time occupancy patterns and environmental conditions. Technology sector tenants in Manchester and Cambridge clusters adopt sensor-enabled hot-desking at accelerated rates. The data infrastructure is decomposing long-term space planning into weekly reconfiguration cycles that compress wasted square footage.
The Flexible Working Bill creates statutory obligations for employers to accommodate remote and hybrid arrangements upon request. This legislative shift fragments enterprise real estate strategies into distributed portfolios rather than consolidated headquarters. Professional services and financial services verticals in London and Birmingham respond by migrating satellite team deployment to monthly coworking subscriptions.
Enterprise procurement departments now unbundle workspace services from bundled facility management contracts, negotiating direct relationships with coworking operators for specific team functions. Channel disintermediation displaces traditional corporate real estate brokers from transaction flow. This pattern concentrates among technology and consulting firms with 50-200 employee satellite offices in regional UK cities.
United Kingdom Co-Working Office Spaces Market Segmentation
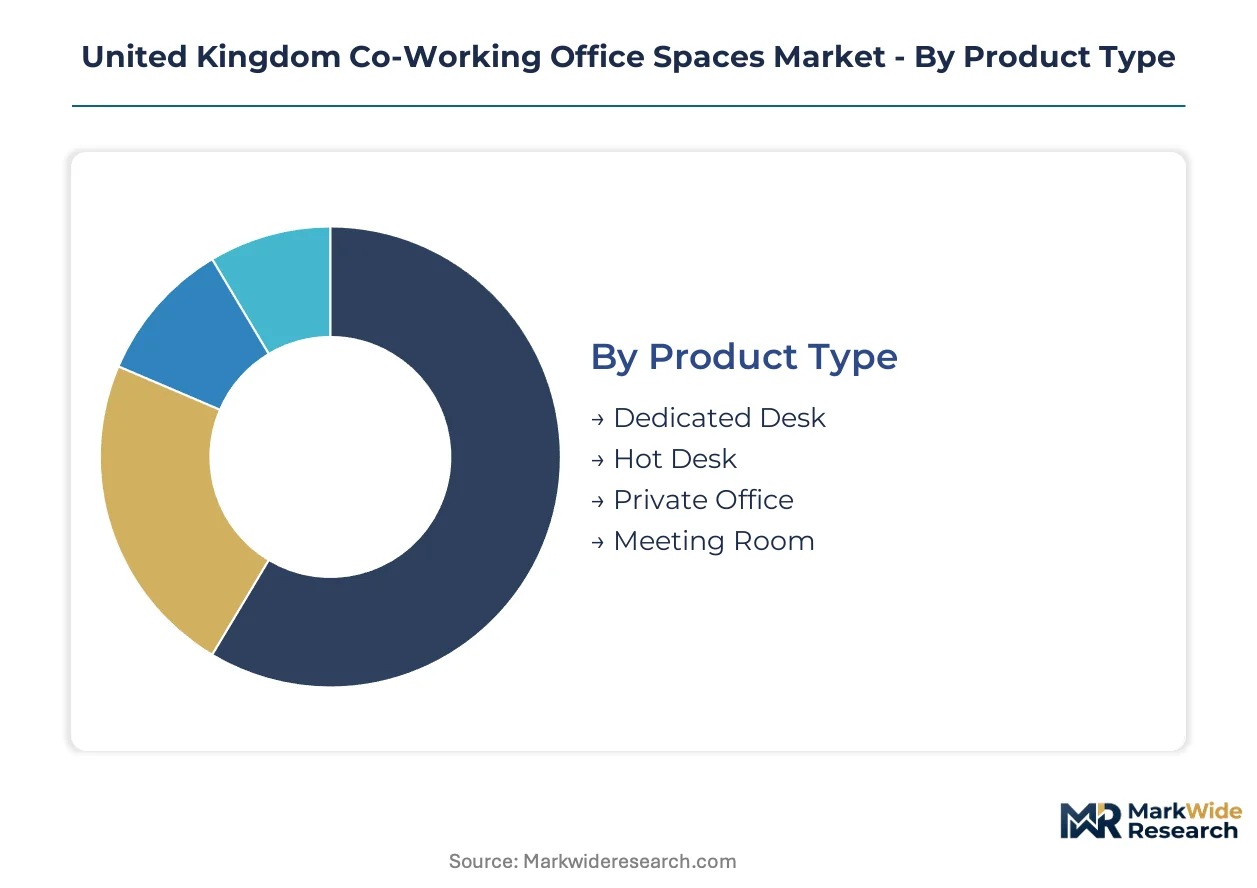
Segmentation in UK co-working markets determines how operators configure space economics, compliance exposure, and service bundling. Each dimension carries distinct regulatory, margin, and demand concentration profiles that shape competitive positioning across Greater London, Birmingham, and Manchester corridors.
Product Type:
UK Health and Safety Executive density guidelines and fire safety regulations apply differentially across product configurations, with enclosed Private Office deployments triggering stricter ventilation and egress requirements than open-plan Hot Desk arrangements.
- Private Office:Enclosed suites with dedicated access control and branded interiors. Demand concentrates among financial services and legal sector satellite teams in London's Tech City, where enterprise tenants require secure environments for client-confidential work and regulatory data handling.
- Hot Desk:Unassigned workstations in shared open-floor configurations with first-come allocation. Technology freelancers and early-stage founders in Manchester's innovation district drive volume, prioritizing cost flexibility over permanence as venture funding cycles compress.
- Dedicated Desk:Permanently reserved individual workstations within communal areas.
- Meeting Room:Bookable enclosed spaces for presentations, interviews, and client sessions.
Established volume favors Hot Desk; emerging adoption favors Private Office.
End User:
Customer type determines contract structure, with Freelancers and Startups anchoring membership throughput while Corporates negotiate bespoke enterprise agreements with service-level guarantees.
- Corporates:Established enterprises with 50-200 employee satellite deployments. Professional services firms in Birmingham's innovation corridor are expanding fastest, driven by Flexible Working Bill mandates for distributed team accommodation and reduced headquarters consolidation.
- SMEs:Growth-stage technology and creative sector businesses with 10-50 employees. Fintech and AI clusters in Cambridge and Bristol generate premium yield concentration, requiring high-performance connectivity infrastructure and sector-specific community programming.
- Freelancers:Independent contractors and solo practitioners purchasing individual memberships.
- Startups:Pre-revenue and seed-stage ventures seeking network effects and investor proximity.
Revenue concentration sits with Corporates; volume throughput depends on SMEs.
Service Type:
Service bundling intensity varies by customer lifecycle stage, with Membership and Virtual Office offerings commanding recurring revenue streams against transactional Pay-as-you-go and Events revenue.
- Membership:Recurring subscription access to workspace infrastructure with tiered entitlement levels. Startups and scale-ups in Edinburgh's technology cluster are climbing the fastest, seeking community integration and investor network access over pure cost minimization.
- Virtual Office:Registered business address and mail handling without physical occupancy. Professional services sole practitioners across Leeds commuter belts are expanding most quickly, leveraging prestige addressing for client credibility while maintaining home-based operations.
- Pay-as-you-go:Single-session access purchased without ongoing commitment.
- Events:Space rental for workshops, product launches, and corporate functions.
Margin stability favors Membership; growth velocity favors Virtual Office.
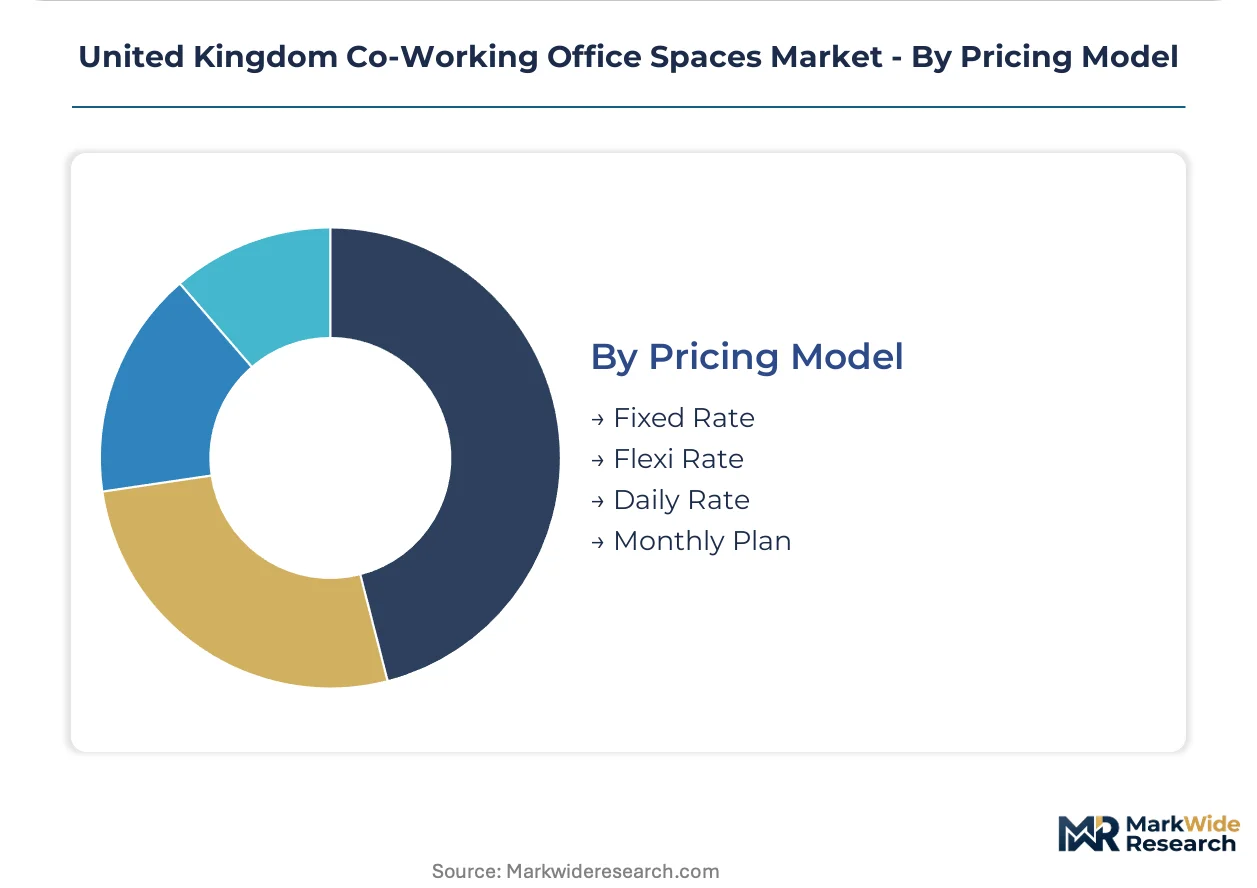
Pricing Model:
Payment structure determines cash flow predictability and customer acquisition friction, with Monthly Plan and Fixed Rate arrangements reducing administrative overhead against variable Flexi Rate and Daily Rate alternatives.
- Monthly Plan:Rolling 30-day commitments with automatic renewal. Enterprise procurement departments in London and Birmingham are gaining share fastest, unbundling workspace from legacy facility management contracts and negotiating direct operator relationships for satellite functions.
- Fixed Rate:Predetermined pricing for defined service bundles over specified durations. SMEs across Greater Manchester are expanding most quickly, prioritizing budget certainty over flexibility as interest rate volatility compresses working capital buffers.
- Flexi Rate:Usage-adjusted pricing with variable components tied to consumption.
- Daily Rate:Single-day access purchased on demand without ongoing obligation.
Recurring revenue favors Monthly Plan; customer acquisition favors Fixed Rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grade-A stock in London's core districts absorbs 35-45% of operator revenue, forcing expansion into underpenetrated commuter belts. The Flexible Working Bill accelerates satellite office deployment across regional innovation corridors.
London and Southeast
Enterprise technology and professional services firms drive Private Office uptake in Tech City and Canary Wharf. The UK Health and Safety Executive workplace density guidelines constrain fit-out specifications in high-rise conversions. Fintech and AI clusters concentrate in Shoreditch and King's Cross, generating premium yields for operators with high-performance connectivity infrastructure.
Midlands
Birmingham's innovation district anchors SME demand from professional services satellite teams. Local authority permitted development rights accelerate office-to-coworking conversions without full planning applications. The West Midlands Combined Authority's regeneration funding supports transit-adjacent workspace development around New Street and Snow Hill stations.
North England
Greater Manchester's technology corridor expands fastest for Hot Desk volume among freelancers and seed-stage ventures. The Greater Manchester Combined Authority's spatial framework prioritizes city center densification over greenfield expansion. Spin-out demand from University of Manchester and Manchester Metropolitan University concentrates in Oxford Road corridor incubators.
Scotland
Edinburgh's technology cluster climbs fastest for Membership subscriptions among scale-ups seeking investor network access. Scottish Government net-zero retrofit incentives subsidize energy-efficient fit-outs in historic commercial stock. The Edinburgh City Region Deal funds innovation infrastructure around Haymarket and Quartermile districts.
Wales
Cardiff's professional services sole practitioners expand Virtual Office adoption fastest for prestige addressing. Welsh Government property development grants support conversion of underutilized office buildings in the capital. The Cardiff Central Enterprise Zone targets creative and digital sector clustering around Central Square.
United Kingdom Co-Working Office Spaces Market Competitive Landscape
Concentration sits with international platform operators holding suburban portfolios outside London's core. The vendor base spans three tiers: global workspace networks with multi-city coverage, design-focused regional specialists, and sector-specific community builders. Dominant competitive moves include portfolio diversification into satellite locations and strategic partnerships with local authorities for regeneration-linked developments.
Within the international platform tier, International Workplace Group plc occupies a position exemplifying extensive suburban coverage. The Office Group and Huckletree represent contrasting archetypes: the former anchors design-led environments targeting professional services tenants, while the latter exemplifies sector-specific community models for technology and creative founders. These three operators collectively illustrate the strategic segmentation driving competitive differentiation across UK metropolitan zones.
| Leading Market Players |
|---|
| International Workplace Group plc |
| WeWork |
| The Office Group |
| Landmark |
| Huckletree |
| Fora |
| Workspace Group PLC |
| Bizspace |
| Servcorp Limited |
| Others |
Value Network & Pricing Analysis
Ninety-day fit-out lead times for Grade-A conversions in London's core districts compress operator pricing power against suburban competitors with faster speed-to-market. This temporal asymmetry between prime real estate procurement and peripheral supply availability fragments margin structures across the United Kingdom co-working landscape.
Pricing Analysis
The UK Health and Safety Executive workplace density guidelines dictate the pricing tier structure across Private Office, Dedicated Desk, and Hot Desk configurations, with ventilation-compliant enclosed suites commanding premium positioning. Price differentiation rests on connectivity infrastructure grade and branded interior specification, with enterprise tenants in Tech City showing lowest sensitivity and Manchester freelancers highest. Pricing pressure intensifies in suburban corridors as permitted development rights accelerate competing supply. Monthly Plan subscriptions dominate enterprise procurement, while Fixed Rate arrangements anchor SME budget certainty.
Supply Chain Analysis
Just-in-time procurement of modular furniture and IoT sensor networks dominates operator fit-out strategy, minimizing capital lock-up in volatile demand environments. Supply concentration centers on China for smart building components, Germany for HVAC systems, and domestic UK sources for fire safety materials. Raw material dependencies span steel framing, low-emissivity glazing, and fiber-optic cabling. Single-source vulnerability concentrates in enterprise-grade connectivity hardware. Distribution runs through regional contractor networks with direct-to-site logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in underpenetrated commuter belts as the Flexible Working Bill fragments enterprise real estate into distributed satellite portfolios rather than consolidated headquarters.
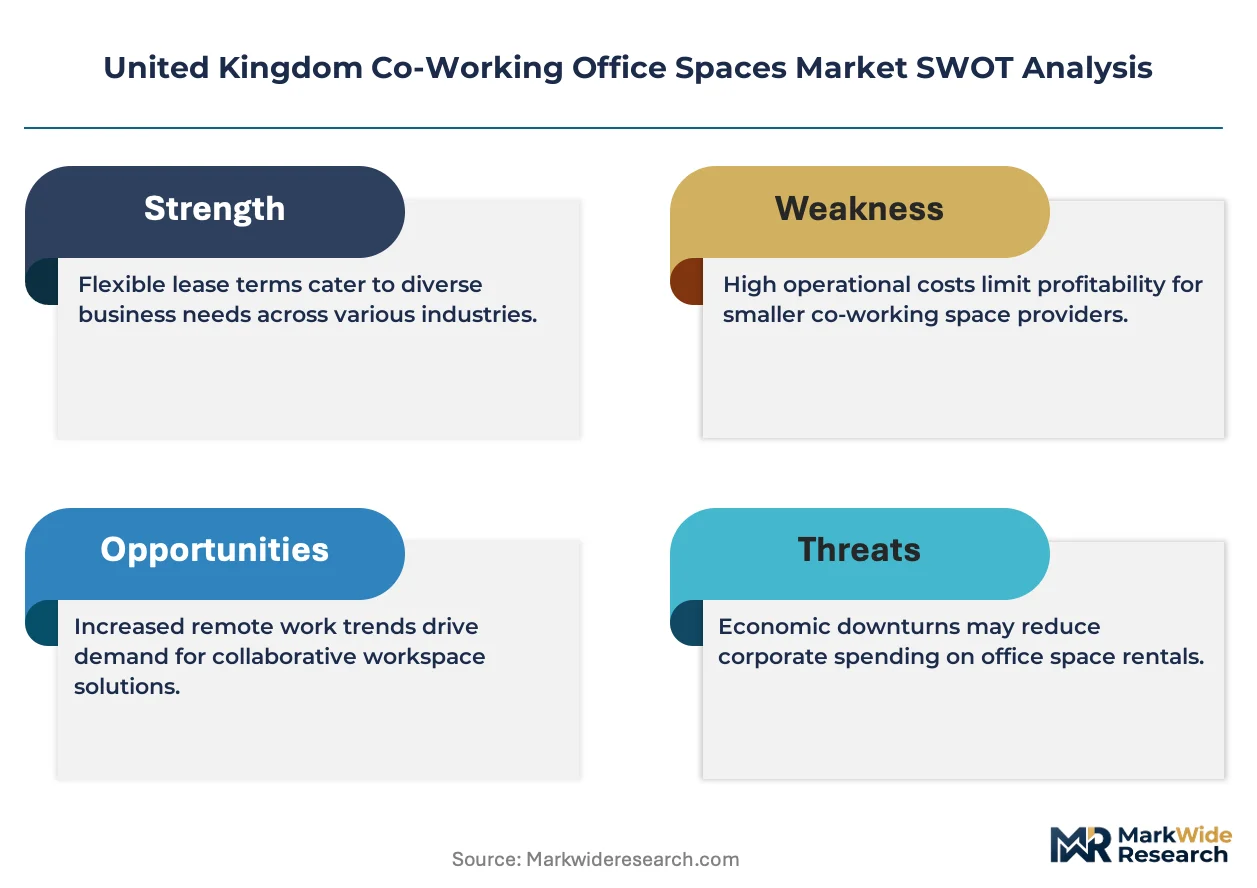
For Market Incumbents: Fortify suburban network density around Leeds, Bristol, and Edinburgh transit nodes before competitor saturation. Defend margin position by accelerating net-zero retrofit certification to capture ESG-mandated corporate tenants. Threat concentration sits with AI-enabled space optimization platforms that could displace traditional yield management. Vertical integration into facilities management talent pipelines offers defensive moat construction. For New Entrants and Emerging Players: Anchor in Virtual Office services across Welsh and Scottish professional services corridors where prestige addressing demand outpaces physical workspace supply. White-space concentration favors Cardiff and Edinburgh scale-up communities seeking investor network proximity without London cost structures. Sector-specific community programming for fintech and AI clusters offers differentiated go-to-market positioning against generic operators. For Investors and Strategic Acquirers: Carve-out targets emerge from distressed commercial real estate portfolios with below-market legacy leases and conversion-permitted development rights. Long-term viability hinges on operator capability to transition from volume-based Hot Desk models toward enterprise Private Office yield optimization. Signal to watch: monthly plan subscription renewal rates among professional services satellite teams as inflection indicator for sector-wide demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Suburban Satellite Network Expansion | Captures Flexible Working Bill-driven distributed team demand in underpenetrated commuter belts around Leeds and Bristol. |
| Net-Zero Retrofit Certification | Unlocks UK Green Finance Strategy subsidies and attracts ESG-mandated corporate tenants with sustainability reporting obligations. |
| AI-Enabled Space Optimization | Deploys occupancy sensors and predictive analytics to maximize yield per square metre across fluctuating demand patterns. |
| Sector-Specific Community Programming | Builds differentiated positioning for fintech and AI clusters in Manchester and Cambridge innovation corridors. |
| Facilities Management Talent Pipeline | Addresses hospitality-hybrid skill scarcity constraining operational scalability across multi-site portfolios. |
Research Methodology
A standing panel of workspace operators, commercial real estate asset managers, enterprise procurement officers, and local authority planning leads provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against UK Health and Safety Executive guidance documents, Greater Manchester Combined Authority spatial frameworks, and West Midlands regeneration funding disclosures. Bottom-up demand modeling triangulated against top-down commercial real estate transaction flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including permitted development rights utilization rates and flexible workspace occupancy surveys. The analytical framework segmented across product type, end user, service type, and pricing model dimensions throughout the projection horizon. CAGRs derived from fitted growth curves incorporating hybrid work mandate penetration, SME technology clustering intensity, and local authority planning flexibility as core inputs.
Decision-makers should treat outputs as directional under sustained base rate environments and Flexible Working Bill implementation timelines; material deviation would warrant model refresh. Revision becomes warranted when commercial mortgage rate resets or building safety compliance timelines cross thresholds that alter supply expansion economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Flexible Office Market
Office Real Estate
Bahrain Co-Working Office Space Market