
 Flexible Letterpress Printing Ink Market | 2026-2036
Flexible Letterpress Printing Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Letterpress Printing Ink Market Analysis
Flexible packaging converters are redrawing procurement priorities for letterpress ink formulations as food-grade compliance requirements intensify. Sun Chemical Corporation leverages backward integration into pigment synthesis to secure supply continuity for high-performance nitrocellulose systems. DIC Corporation anchors its position through dedicated R&D centers in Osaka and sustained patent activity around low-migration UV oligomers. Flint Group competes on manufacturing scale, operating integrated resin production that controls cost structures across European and North American label markets.
Flexible letterpress printing ink comprises pigmented fluid systems formulated with binders, solvents or photoinitiators, and additives, designed for transfer from raised photopolymer or rubber plates to flexible substrates at viscosities typically between 30 and 80 Pa·s. These inks serve primary industrial purposes in high-speed rotary letterpress equipment where substrate compatibility and drying speed determine run economics. UV-curable inks capture expanding margin pools in label and food packaging segments where instant polymerization eliminates solvent retention risks. Water-based formulations lead volume in corrugated and decorative printing applications where porous substrates absorb aqueous vehicles efficiently. Solvent-based systems retain structural importance in textile printing and certain flexible packaging lanes where substrate adhesion demands aggressive surface wetting.
EPA volatile organic compound rules under the Clean Air Act shape formulation chemistry for US-based ink manufacturing, while REACH registration requirements and RoHS substance restrictions govern material composition across European supply chains. FDA indirect food additive regulations under 21 CFR 175.105 and 175.300 constrain resin and photoinitiator selection for food packaging applications, creating compliance-driven segmentation between packaging-grade and non-contact formulations. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that will recast ink procurement specifications through recycled content mandates and chemical disclosure requirements.
Market Dynamics
UV-curable ink chemistry is compressing drying times from minutes to milliseconds, forcing solvent-based formulation investments into obsolescence cycles while converters recalculate run economics around instant polymerization throughput.
Growth Catalysts
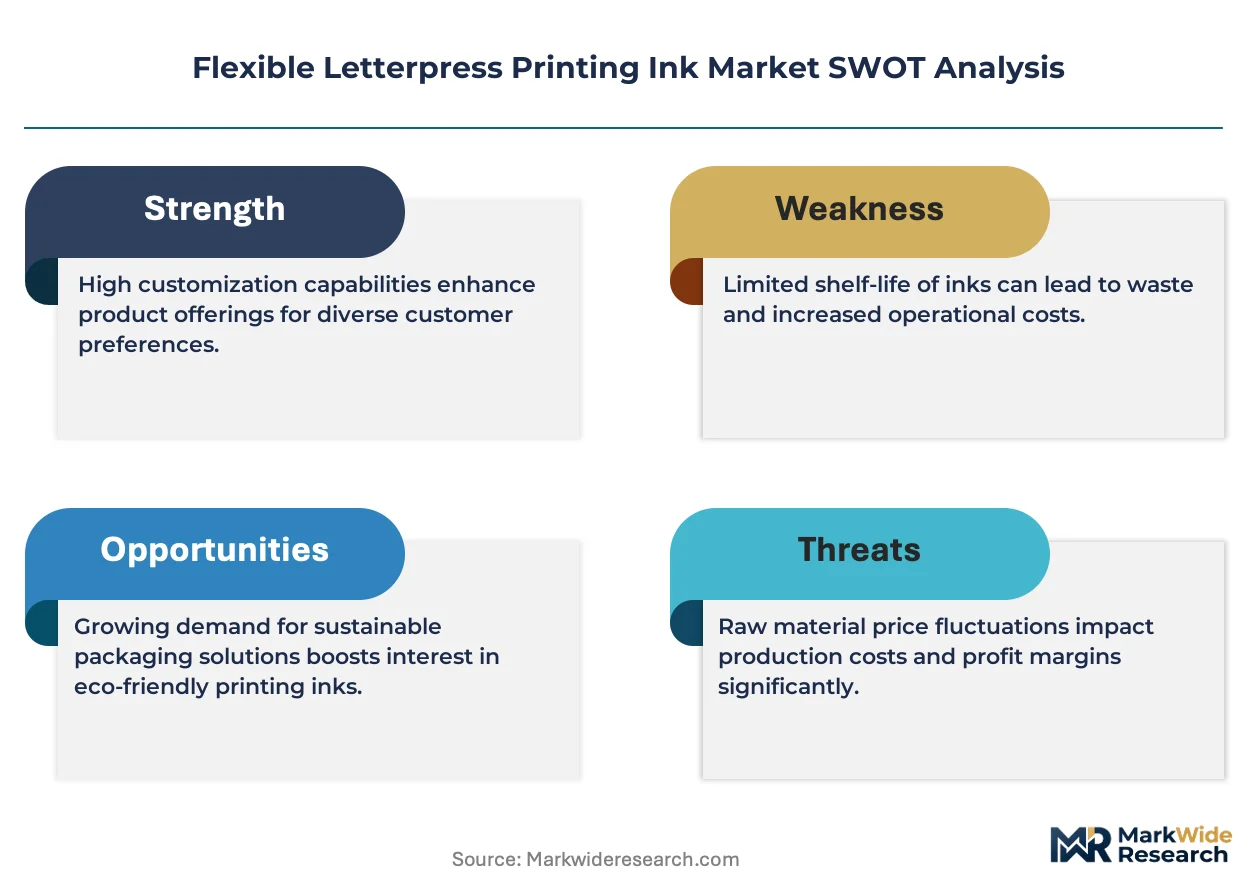
- REACH substance restrictions:European converters face phased volatile organic compound limits that accelerate water-based and UV-curable ink procurement timelines across food packaging label operations.
- Photopolymer plate advances:Digital plate imaging systems reduce makeready waste by 60% in high-volume rotary letterpress environments, sustaining capital deployment against flexographic alternatives.
- Poland:Central European flexible packaging clusters attract German and Italian equipment relocations, concentrating demand for nitrocellulose-compatible ink systems in Warsaw and Kraków industrial zones.
Market Restraints
- Photoinitiator supply concentration:Specialty photoinitiator manufacturing concentrates in Chinese and Indian chemical clusters, exposing European ink compounders to freight cost volatility and customs processing delays.
- Substrate adhesion limits:Water-based formulations fail to achieve required bond strength on oriented polypropylene films without corona treatment capital expenditure, constraining adoption in premium snack packaging lanes.
- RoHS substance restrictions:Heavy metal pigment prohibitions under EU directive 2011/65/EU force reformulation of certain color index pigments, extending R&D cycles by 12-18 months for compliant replacements.
Strategic Opportunities
- Pharmaceutical serialization mandates:EU Falsified Medicines Directive enforcement creates demand for low-migration UV inks in secondary packaging applications where traceability codes require pharmaceutical-grade compliance.
- Italy:Northern Italian label converters maintain letterpress capacity for wine and spirits applications where tactile varnish effects resist digital reproduction, preserving premium ink margin pools.
- LED-UV convergence:Mercury lamp replacement with LED curing arrays reduces energy consumption 40% and enables heat-sensitive substrate processing, opening bio-based film markets previously excluded from UV workflows.
Industry Challenges
- Formulation chemist scarcity:Retirement waves among nitrocellulose dispersion specialists constrain R&D throughput at mid-sized ink compounders competing with pharmaceutical sector salary benchmarks.
- FDA 21 CFR 175.300 compliance timelines:Food contact notification pathways for novel photoinitiator chemistries require 18-24 month pre-market review, delaying commercialization of next-generation low-odor formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Letterpress Printing Ink Market |
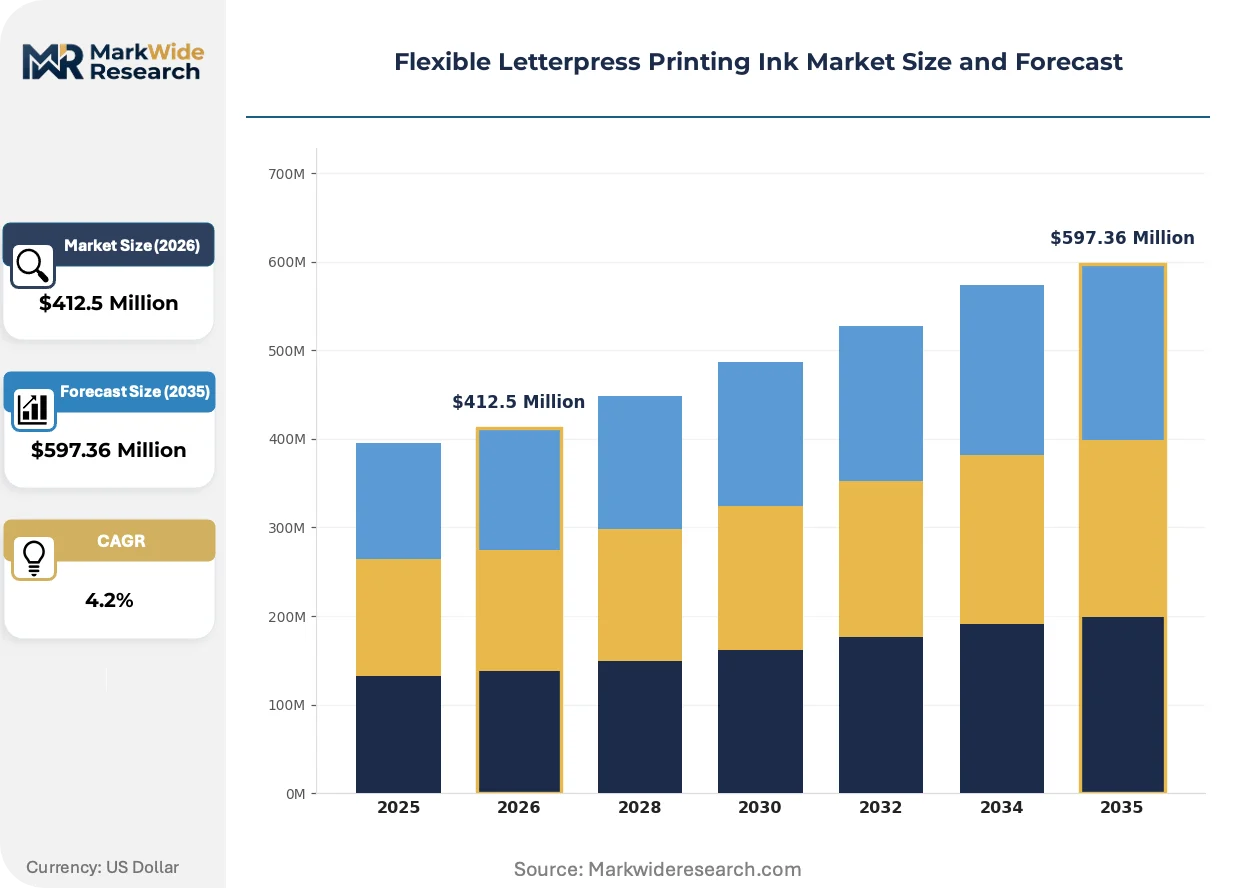
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Inks, Solvent-Based Inks, UV-Curable Inks, Oil-Based Inks End User: Packaging, Publishing, Labels, Commercial Printing Application: Food Packaging, Textile Printing, Decorative Printing, Stationery Formulation: Conventional Inks, Sustainable Inks, Specialty Inks, Performance Inks |
| Companies Covered | Sun Chemical Corporation, DIC Corporation, Flint Group, Siegwerk, Toyo Ink SC Holdings, Sakata INX Corporation, Huber Group, Nazdar Ink Technologies, Zeller+Gmelin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Letterpress Printing Ink Market Emerging Trajectories
Formulation chemistry is fragmenting into parallel development tracks as regulatory divergence between jurisdictions forces region-specific product architectures rather than universal platforms.
LED-UV curing technology is bifurcating the installed equipment base. Narrow-wavelength LED arrays at 395nm and 365nm enable instant polymerization without thermal substrate damage. Premium label converters in Germany and Switzerland are retrofitting existing letterpress decks with hybrid mercury-LED configurations. This technology is bifurcating equipment supplier strategies between full LED-native press designs and modular retrofit kits for legacy assets.
EU Green Deal chemical sustainability requirements are tightening substance disclosure obligations across packaging supply chains. The Corporate Sustainability Reporting Directive mandates scope 3 emissions documentation that captures ink formulation carbon intensity. Flexible packaging buyers in France and the Netherlands now require full material safety data sheet transparency extending to photoinitiator decomposition byproducts, forcing compounders to requalify supplier networks.
Specification authority is migrating from brand marketing departments to procurement sustainability officers who weight lifecycle assessment scores alongside unit cost. Centralized buying consortia in German retail chains now mandate cradle-to-gate carbon thresholds for all packaging inputs including inks. This behavioral pivot concentrates volume with compounders holding third-party verified environmental product declarations, compressing spot-market purchasing for non-certified formulations.
Flexible Letterpress Printing Ink Market Segmentation
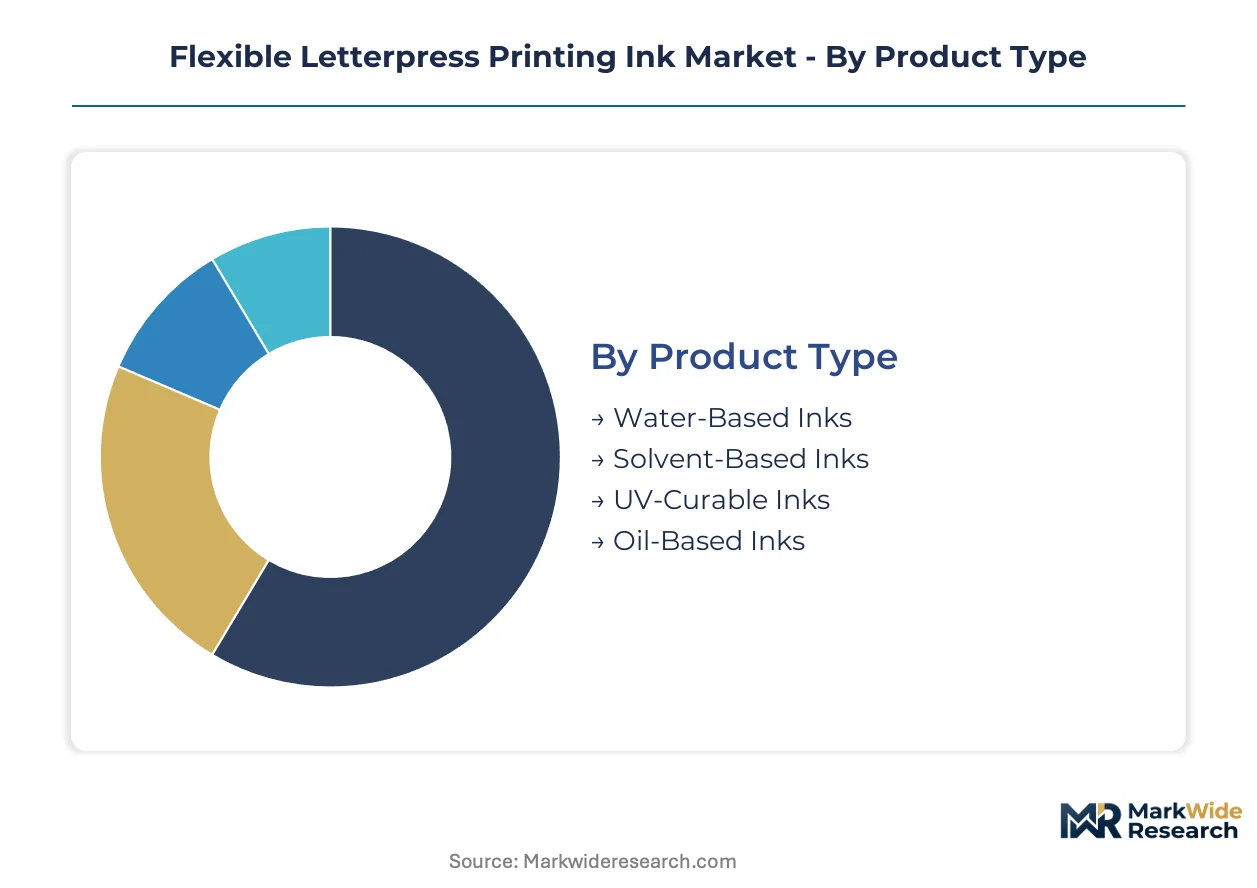
Segmentation in flexible letterpress printing ink reveals how formulation chemistry, end-use requirements, and regulatory pressure fragment procurement patterns across converter operations. Each dimension carries distinct margin structures and compliance burdens that reshape supplier relationships.
Product Type:
Channel mix varies sharply by curing mechanism, with UV-curable formulations flowing through specialized distributors serving label converters while water-based systems move through corrugated supply houses in higher volumes.
- Water-Based Inks:Aqueous pigment dispersions employing acrylic or styrene-acrylic binders at 20-40% solids content. Demand clusters in corrugated packaging operations across Poland and Germany where absorbent kraft substrates eliminate drying infrastructure requirements. REACH volatile organic compound limits accelerate procurement timelines for food-contact corrugated applications.
- Solvent-Based Inks:Nitrocellulose or polyurethane-bonded systems dissolved in ester-ketone blends, delivering aggressive surface wetting on non-porous films. Italian textile printers and flexible packaging converters in Warsaw industrial zones sustain procurement despite regulatory pressure, driven by adhesion performance on oriented polypropylene that water-based alternatives cannot match without corona treatment investment.
- UV-Curable Inks:Photoinitiator-activated oligomer systems polymerizing instantly under mercury or LED lamps.
- Oil-Based Inks:Mineral oil or vegetable oil vehicles with high molecular weight resins, historically dominant in newspaper and publication gravure now residual in letterpress.
Solvent-based formulations dominate installed base in textile and premium flexible packaging. UV-curable systems are where expansion concentrates, climbing fastest in German and Swiss label operations retrofitting LED curing arrays.
End User:
Cost tier segmentation separates pharmaceutical serialization compliance investments from commodity corrugated procurement, with label converters occupying the premium middle ground.
- Packaging:Food-contact formulations governed by FDA 21 CFR 175.105 and EU 10/2011 migration limits. German retail chain buying consortia now mandate cradle-to-gate carbon thresholds that favor compounders with third-party verified environmental product declarations.
- Labels:Wine and spirits applications in Northern Italy preserve letterpress capacity for tactile varnish effects that digital reproduction cannot replicate. Low-migration UV oligomer demand intensifies under EU Falsified Medicines Directive enforcement for pharmaceutical traceability codes.
- Publishing:Periodical and directory printing with declining letterpress relevance.
- Commercial Printing:General job shop applications migrating to digital or offset technologies.
Packaging commands the largest volume share across European converter operations. Labels represent the steepest expansion trajectory as pharmaceutical serialization mandates and premium beverage branding sustain margin pools.
Application:
Geography drives application concentration, with Central European flexible packaging clusters anchoring food-grade demand and Italian industrial districts preserving decorative specialty volumes.
- Food Packaging:Low-odor, low-migration formulations for direct and indirect food contact. Polish converters in Warsaw and Kraków industrial zones drive nitrocellulose-compatible ink procurement as German and Italian equipment relocations concentrate capacity.
- Textile Printing:Solvent-based systems with high pigment loading for fabric penetration and wash fastness. Italian Como district printers sustain demand despite water-based substitution pressure in other segments.
- Decorative Printing:Specialty effect inks including metallic and pearlescent finishes for premium consumer goods.
- Stationery:Greeting card and envelope applications with modest technical requirements and price-sensitive procurement.
Food packaging dominates installed base in volume terms. Textile printing is where specialty solvent-based margins concentrate despite regulatory headwinds.
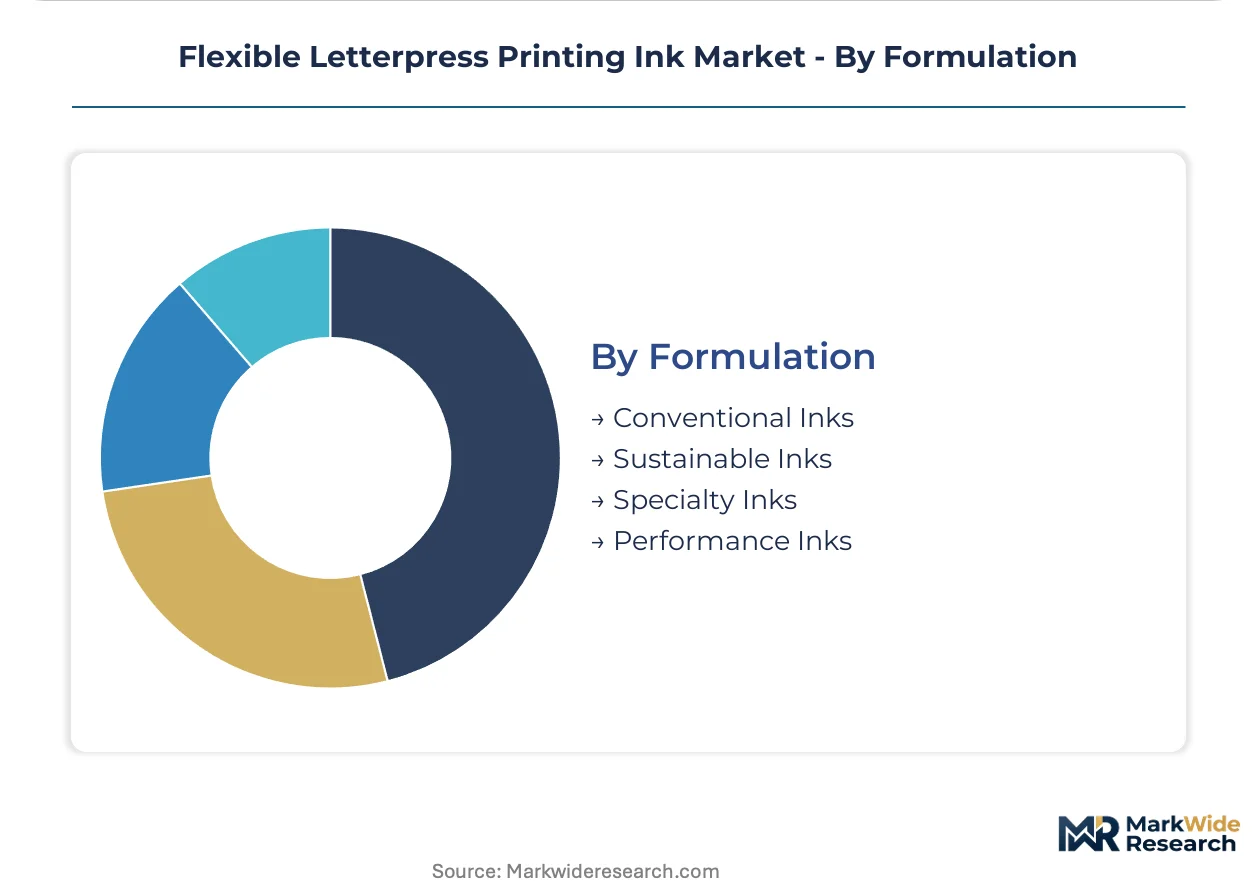
Formulation:
Customer type segmentation separates sustainability-officer-driven procurement in German retail chains from technical-performance-driven selection in pharmaceutical packaging operations.
- Sustainable Inks:Bio-based resin vehicles, renewable photoinitiators, and cradle-to-gate carbon documentation. EU Green Deal chemical sustainability requirements and Corporate Sustainability Reporting Directive scope 3 emissions documentation force requalification of supplier networks across French and Dutch flexible packaging buyers.
- Specialty Inks:Low-migration, low-odor, or sensory-effect formulations for pharmaceutical and premium food applications. FDA food contact notification pathways for novel chemistries require 18-24 month pre-market review, delaying commercialization.
- Conventional Inks:Standard nitrocellulose or acrylic systems without sustainability certification or specialty compliance features.
- Performance Inks:High-adhesion, high-speed, or extreme-environment formulations for technical applications.
Conventional formulations retain volume leadership across corrugated and general commercial applications. Sustainable inks are gaining share fastest as procurement authority migrates to sustainability officers weighting lifecycle assessment scores alongside unit cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in flexible packaging logistics, connecting German chemical feedstock hubs to Polish converter clusters and Italian specialty print districts.
Germany
REACH substance restrictions and EU Green Deal mandates accelerate procurement of UV-curable and water-based formulations across food packaging label operations. The Corporate Sustainability Reporting Directive forces cradle-to-gate carbon documentation from ink compounders serving German retail chain buying consortia. Frankfurt and Stuttgart industrial zones concentrate R&D investment in low-migration UV oligomers for pharmaceutical serialization compliance.
Poland
Central European flexible packaging clusters attract German and Italian equipment relocations, concentrating nitrocellulose-compatible ink demand. Warsaw and Kraków industrial zones host expanding converter capacity serving EU export markets with cost-competitive letterpress operations. Polish converters leverage proximity to German chemical supply chains while operating under REACH registration requirements.
Italy
Northern Italian label converters maintain letterpress capacity for wine and spirits applications where tactile varnish effects resist digital reproduction. The Como textile printing district sustains solvent-based ink procurement despite water-based substitution pressure in other segments. Italian operations navigate RoHS heavy metal pigment prohibitions while preserving premium specialty margins.
Switzerland
Swissmedic pharmaceutical packaging standards and proximity to German supply chains position Swiss converters for low-migration UV ink demand. Basel and Zurich industrial corridors specialize in pharmaceutical-grade compliance for EU Falsified Medicines Directive traceability codes. LED-UV curing retrofits advance fastest here due to premium substrate handling requirements.
United States
EPA volatile organic compound rules under the Clean Air Act shape formulation chemistry for domestic ink manufacturing. California and New York state-level extended producer responsibility frameworks recast procurement specifications through recycled content mandates. Midwest label converters and Southeast flexible packaging clusters drive water-based ink volume for corrugated applications.
Flexible Letterpress Printing Ink Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and geographic coverage. The vendor base separates into scale-driven integrated compounders, mid-sized regional specialists, and technology-focused niche operators. Three archetypes dominate: backward-integrated pigment manufacturers controlling raw material costs, R&D-intensive oligomer developers securing pharmaceutical compliance positions, and flexible regional blenders serving spot-market corrugated demand. Competitive moves concentrate on manufacturing scale expansion and sustainability certification acquisition.
Within the integrated compounder tier, Sun Chemical Corporation and DIC Corporation exemplify archetypes of pigment synthesis control and dedicated photopolymer research infrastructure respectively. Flint Group occupies a position among scale-driven manufacturers with integrated resin production. These three anchors represent distinct strategic postures: captive supply security, patent-protected specialty development, and cost-optimized regional manufacturing scale.
| Leading Market Players |
|---|
| Sun Chemical Corporation |
| DIC Corporation |
| Flint Group |
| Siegwerk |
| Toyo Ink SC Holdings |
| Sakata INX Corporation |
| Huber Group |
| Nazdar Ink Technologies |
| Zeller+Gmelin |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German resin synthesis facilities anchors pricing power across European letterpress ink supply, with integrated compounders leveraging captive pigment production to set price floors that spot-market blenders cannot match. REACH registration burdens and photoinitiator import dependencies concentrate margin control among backward-integrated manufacturers while corrugated converters absorb pass-through cost volatility through annual contract structures.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade low-migration UV formulations from commodity corrugated water-based systems, with three-tier pricing stratification across premium certified, standard industrial, and economy spot-market levels. Price differentiation hinges on FDA food-contact notification status and cradle-to-gate carbon documentation under EU Green Deal mandates. Pricing pressure stems from LED-UV equipment retrofit costs compressing converter capital budgets for ink premiumization. Pharmaceutical packaging operations show least price sensitivity due to serialization compliance requirements, while corrugated converters in Poland negotiate aggressively on per-kilogram solvent-based formulations.
Supply Chain Analysis
Inventory lead times for specialty photoinitiators stretch across 8-12 week ocean freight corridors from Chinese and Indian chemical clusters, exposing European compounders to customs processing volatility at Rotterdam and Hamburg port facilities. Geographic supply concentration centers on Germany for nitrocellulose resin synthesis, China for photoinitiator active ingredients, and India for pigment intermediate processing. Raw material dependencies include ester-ketone solvent blends, acrylic binder dispersions, and oligomer base resins. Single-source vulnerability concentrates in narrow-wavelength photoinitiator chemistries optimized for LED-UV arrays. Distribution runs through specialized chemical distributors serving label converters and corrugated supply houses moving water-based volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized procurement consortia at German retail chains, with sustainability officer authority consolidating specification decisions previously fragmented across plant-level technical managers.
For Market Incumbents: Secure captive supply of photoinitiator precursors through long-term offtake agreements with Chinese and Indian chemical manufacturers, insulating formulation costs from freight volatility. Defend pharmaceutical compliance positions by accelerating FDA food contact notification pathways for novel low-odor oligomers ahead of EU Falsified Medicines Directive enforcement waves. Capacity addition in Polish converter corridors captures equipment relocation demand from German and Italian packaging operations. For New Entrants and Emerging Players: Differentiate on bio-based resin vehicles with third-party verified environmental product declarations targeting French and Dutch flexible packaging buyers under Corporate Sustainability Reporting Directive scope 3 mandates. White-space opportunities concentrate in LED-UV compatible formulations for heat-sensitive bio-based films excluded from legacy mercury curing workflows. Target pharmaceutical serialization compliance as the most penetrable premium segment, leveraging regulatory burden as barrier against commodity competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors R&D-intensive oligomer developers over scale-driven commodity compounders as LED-UV convergence accelerates equipment replacement cycles. Long-term viability across the projection horizon rests on patent-protected low-migration chemistries rather than manufacturing scale alone. Acquisition target archetype: mid-sized European compounders with established pharmaceutical compliance dossiers and underutilized resin production capacity. Signal to watch: FDA pre-market review timeline compression for food-contact photoinitiator approvals indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Sun Chemical's captive supply of nitrocellulose dispersions insulates margin structures from raw material volatility. |
| LED-UV Curing Retrofit Partnerships | Equipment supplier alliances accelerate converter adoption of narrow-wavelength polymerization systems. |
| Pharmaceutical Compliance Certification | FDA 21 CFR 175.300 notification pathways secure premium positioning in serialization packaging. |
| Carbon Documentation Investment | Third-party verified environmental product declarations satisfy German retail chain procurement mandates. |
| Central European Capacity Expansion | Polish manufacturing footprints capture equipment relocation demand from German converter operations. |
Methodological Framework
Desk research of trade association publications, customs import records, and SEC regulatory filings preceded structured interviews with ink formulation chemists, flexible packaging procurement directors, and photopolymer plate equipment specialists. Primary fieldwork captured converter capital expenditure intentions and formulation substitution patterns across German, Italian, and Polish industrial zones. Secondary validation drew from European Chemicals Agency REACH registration databases, FDA food contact substance inventories, and EU Green Deal implementation guidance documents. Bottom-up demand modeling triangulated against top-down chemical feedstock consumption estimates.
Variance decomposition across curing mechanism, end-use compliance tier, and geographic production cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include formulation chemistry, substrate compatibility requirements, and regulatory jurisdiction clusters. CAGRs derived from installed equipment base replacement cycles and converter technology migration patterns. Industry-specific forecast inputs encompass LED-UV lamp retrofit penetration rates and pharmaceutical serialization mandate compliance timelines.
Forecasts assume regulatory continuity in REACH substance restrictions and FDA food contact notification pathways; material policy shifts including accelerated EU Green Deal chemical bans or extended producer responsibility framework expansion would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Food Marking Inks Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Printing Plate Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
North America Printing Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
United States Printing Inks Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Molecular Ink Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Thermal Inkjet Inks Market