
 Waterborne Ink Market | 2026-2036
Waterborne Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Waterborne Ink Market Analytics
ISO 14001 environmental management certification is unwinding competitive barriers for mid-tier suppliers seeking entry into branded packaging supply chains. Sun Chemical leverages captive resin manufacturing to control raw material variability across flexo and gravure product lines. Siegwerk Druckfarben AG & Co. KGaA anchors its position through specialized waterborne formulations for sensitive food-contact substrates. DIC Corporation dominates Asian supply channels with integrated pigment and ink production networks.
Waterborne ink comprises pigment or dye dispersions suspended in water-based resin vehicles with volatile organic compound content typically below five percent by weight, serving commercial printing and industrial coating applications where air quality compliance and worker safety standards apply. Flexo ink leads volume demand from corrugated and flexible packaging converters, while digital ink captures the fastest expansion as narrow-web label printers retrofit presses for shorter run lengths. Eco-friendly technology formulations command margin premiums where brand sustainability scorecards influence supplier selection.
EPA National Emission Standards for Hazardous Air Pollutants govern US printing facility solvent thresholds, while REACH registration requirements in Europe restrict specific co-solvent chemistries from waterborne formulations. FDA food-contact notification protocols determine which resin systems qualify for direct packaging applications. Stakeholders must monitor evolving state-level VOC regulations in California and pending amendments to the Industrial Emissions Directive that could tighten permissible emission limits for gravure operations.
Market Dynamics
Flexible packaging converters are accelerating solvent-to-water technology migrations as binding VOC emission thresholds under the EU Industrial Emissions Directive compress legacy formulation margins and reshape supplier qualification requirements.
Growth Catalysts
- REACH Registration Mandates:European restrictions on specific co-solvent chemistries are eliminating solvent-based alternatives from branded packaging supply chains, forcing converters toward compliant waterborne systems.
- Food-Contact Substrate Expansion:Sensitive direct-contact packaging applications in dairy and ready-to-eat segments are specifying waterborne resins to meet FDA food-contact notification protocols.
- Germany's Emission Threshold Enforcement:Print service providers in Baden-Württemberg and Bavaria face binding gravure operation limits that concentrate procurement of sub-five-percent VOC formulations.
Market Restraints
- Petrochemical Resin Volatility:Acrylic and polyurethane dispersion feedstock costs fluctuate with crude derivative pricing, compressing margin predictability for mid-tier ink suppliers.
- Asian Pigment Concentration:Integrated pigment production networks in China dominate intermediate supply, creating single-source vulnerability for European and North American formulators.
- Drying Speed Limitations:Waterborne systems require extended curing cycles versus solvent alternatives, constraining throughput velocity on high-speed corrugated lines.
Strategic Opportunities
- Narrow-Web Digital Retrofit:Label printers in Italy and Spain are converting legacy flexo presses to inkjet systems, opening formulation partnerships for waterborne digital ink suppliers.
- EU Green Deal Procurement Incentives:Public sector packaging tenders now weight lifecycle carbon metrics, advantaging waterborne suppliers with ISO 14001 certification.
- Hybrid UV-Water Convergence:Energy-curable waterborne hybrids are penetrating premium cosmetic folding carton applications where gloss and rub resistance specifications intersect with emission controls.
Industry Challenges
- Formulation Chemistry Expertise Gap:Experienced resin dispersion chemists are concentrated among legacy suppliers, constraining new entrant R&D velocity.
- Press Retrofit Capex Burden:Converting solvent-optimized drying systems to handle waterborne cure profiles requires substantial capital outlay for mid-size converters.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, EFSA, and national food-contact approvals extend product commercialization cycles by eighteen to thirty months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterborne Ink Market |
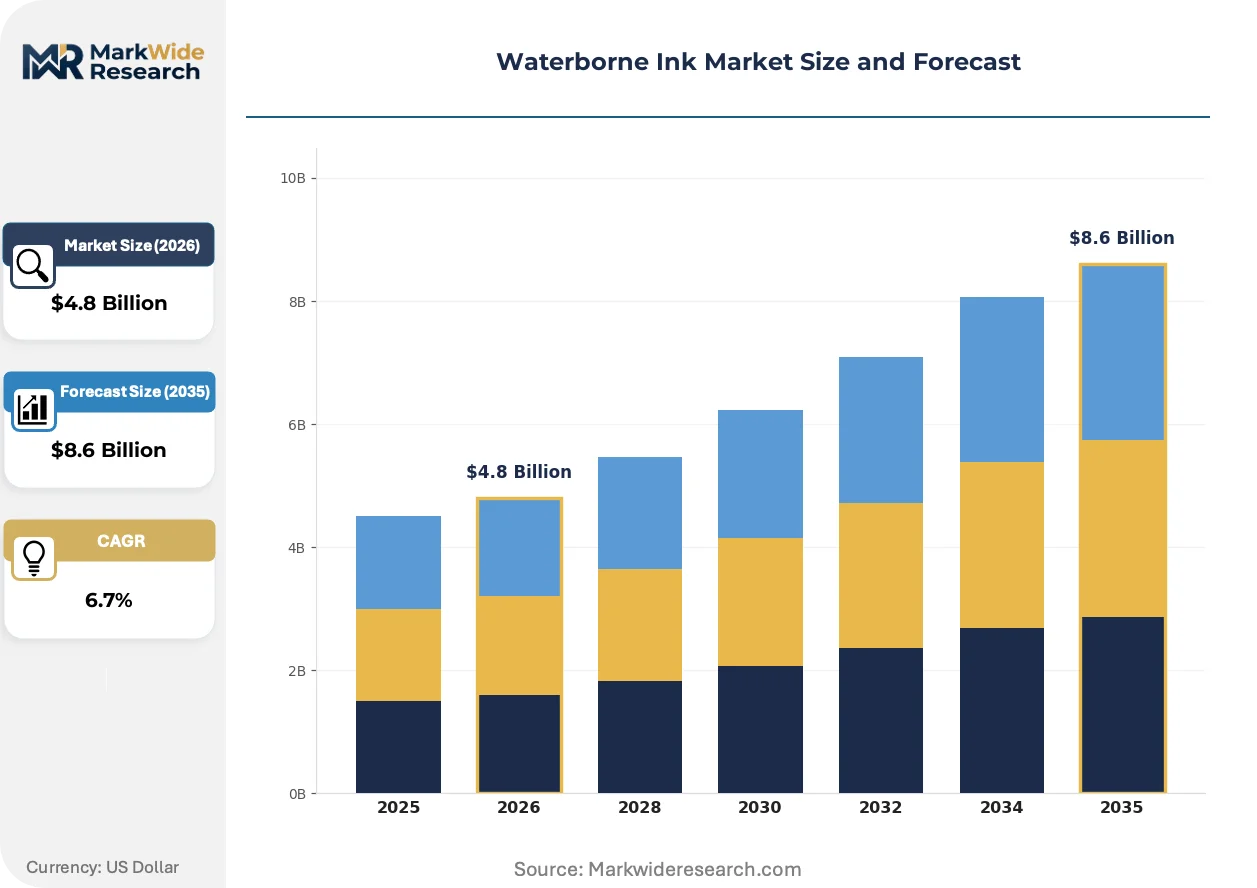
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexo Ink, Gravure Ink, Digital Ink, Screen Ink Application: Packaging, Coatings, Labeling, Publishing End User: Consumer Goods, Automotive, Electronics, Food & Beverage Technology: Low Viscosity, High Performance, Eco-Friendly, Fast Drying |
| Companies Covered | Sun Chemical, Flint Group, Siegwerk Druckfarben AG & Co. KGaA, Toyo Ink SC Holdings Co., Ltd., Sakata Inx Corporation, Hubergroup, DIC Corporation, INX International Ink Co., Wikoff Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterborne Ink Market Evolving Landscape
Formulation chemistry, regulatory architecture, and procurement logic are simultaneously restructuring competitive position in waterborne ink supply, compressing legacy solvent incumbents while elevating certified specialists.
Hybrid UV-curable waterborne ink is decomposing the traditional trade-off between emission compliance and surface performance in premium packaging segments. Cosmetic and pharmaceutical folding carton converters in Switzerland and France are specifying these systems for high-gloss, rub-resistant finishes previously requiring solvent platforms. The technology is decomposing incumbent solvent suppliers' grip on luxury packaging by delivering comparable aesthetics without VOC exposure liabilities.
REACH authorization requirements for specific co-solvent chemistries are eliminating formulation flexibility for European ink producers. The restriction of N-methyl-2-pyrrolidone and certain glycol ethers from waterborne vehicles is forcing resin system redesigns across flexo and gravure product lines. German print service providers are responding by consolidating procurement with suppliers maintaining captive resin manufacturing capabilities to ensure continuity.
Brand sustainability scorecards are restructuring supplier selection criteria in food and beverage packaging. Major retail chains in the Netherlands and Scandinavia now require documented VOC content thresholds and third-party environmental certification from their packaging converters. This behavioral shift is displacing price-only procurement models with multi-criteria evaluation frameworks where formulation compliance commands margin premiums.
Waterborne Ink Market Segmentation
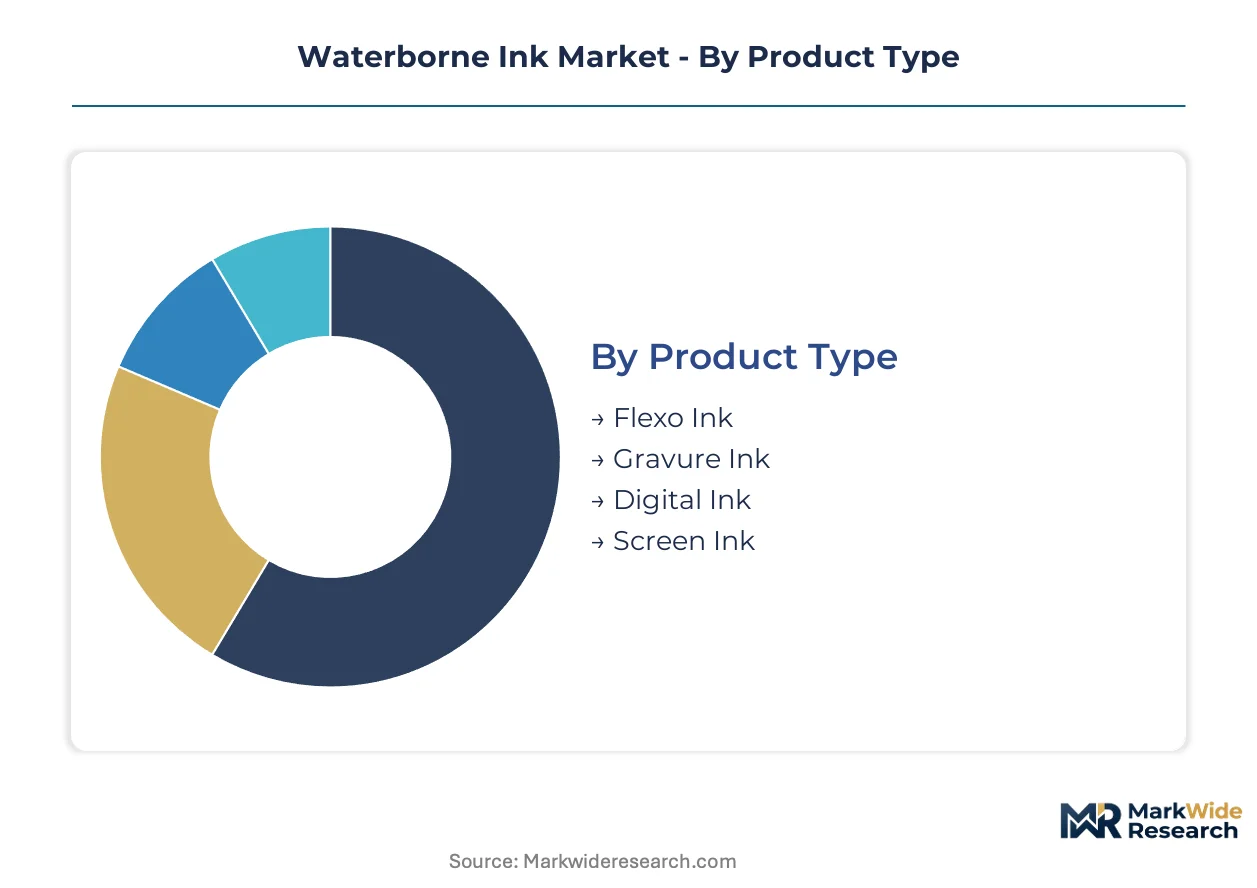
Waterborne ink segmentation reveals how formulation chemistry, substrate compatibility, and regulatory compliance intersect across distinct commercial channels. Understanding these divisions exposes where margin concentrates and which technology migrations are reshaping procurement patterns.
Product Type:
Domestic production dominates flexo and gravure supply in Germany and the US, while digital ink formulations flow through specialized export channels serving narrow-web retrofit markets in Italy and Spain.
- Flexo Ink:Pigment dispersions in acrylic or polyurethane resin vehicles formulated for corrugated and flexible packaging substrates. Demand concentrates with German converters facing binding VOC thresholds under the Industrial Emissions Directive, where sub-five-percent formulations command procurement preference.
- Digital Ink:Jettable waterborne formulations with controlled surface tension and viscosity profiles for piezoelectric printheads. Italian and Spanish label printers retrofitting legacy flexo presses are driving the steepest expansion trajectory as run lengths shorten and versioning requirements multiply.
- Gravure Ink:Low-viscosity resin systems optimized for high-speed cylinder engraving in publication and decorative applications.
- Screen Ink:Thixotropic formulations with extended open time for textile and industrial substrate printing.
Flexo ink holds the largest share; momentum sits with digital ink.
Application:
Cost tier stratification separates premium food-contact formulations from standard industrial coatings, with certification burden driving price differentiation.
- Packaging:Direct and indirect food-contact resin systems meeting FDA notification protocols and EFSA compliance requirements. Dairy and ready-to-eat segments in the Netherlands and Scandinavia specify documented VOC thresholds, displacing price-only procurement with sustainability scorecard evaluation.
- Labeling:Narrow-web and wide-web adhesive-compatible formulations for pressure-sensitive and shrink-sleeve applications. Swiss and French cosmetic converters specify hybrid UV-waterborne systems for gloss and rub resistance previously requiring solvent platforms.
- Coatings:Industrial decorative and protective finishes for wood, metal, and plastic substrates.
- Publishing:Heatset and coldset web offset replacements with reduced emission profiles.
Packaging commands the dominant revenue position; labeling climbs fastest on digital press conversion.
End User:
Volume concentration tracks branded goods manufacturers with plastic-reduction commitments and binding sustainability disclosure requirements.
- Food & Beverage:Sensitive direct-contact packaging for dairy, ready-to-eat, and beverage applications requiring FDA food-contact notification and EU framework regulation compliance. Major retail chains now mandate third-party environmental certification from converters.
- Consumer Goods:Personal care and household product folding cartons with premium aesthetic requirements.
- Automotive:Interior trim and component marking with durability and emission specifications.
- Electronics:Membrane switch and display component printing with precision registration demands.
Food & beverage anchors volume demand; consumer goods expands on premium cosmetic segment specification.
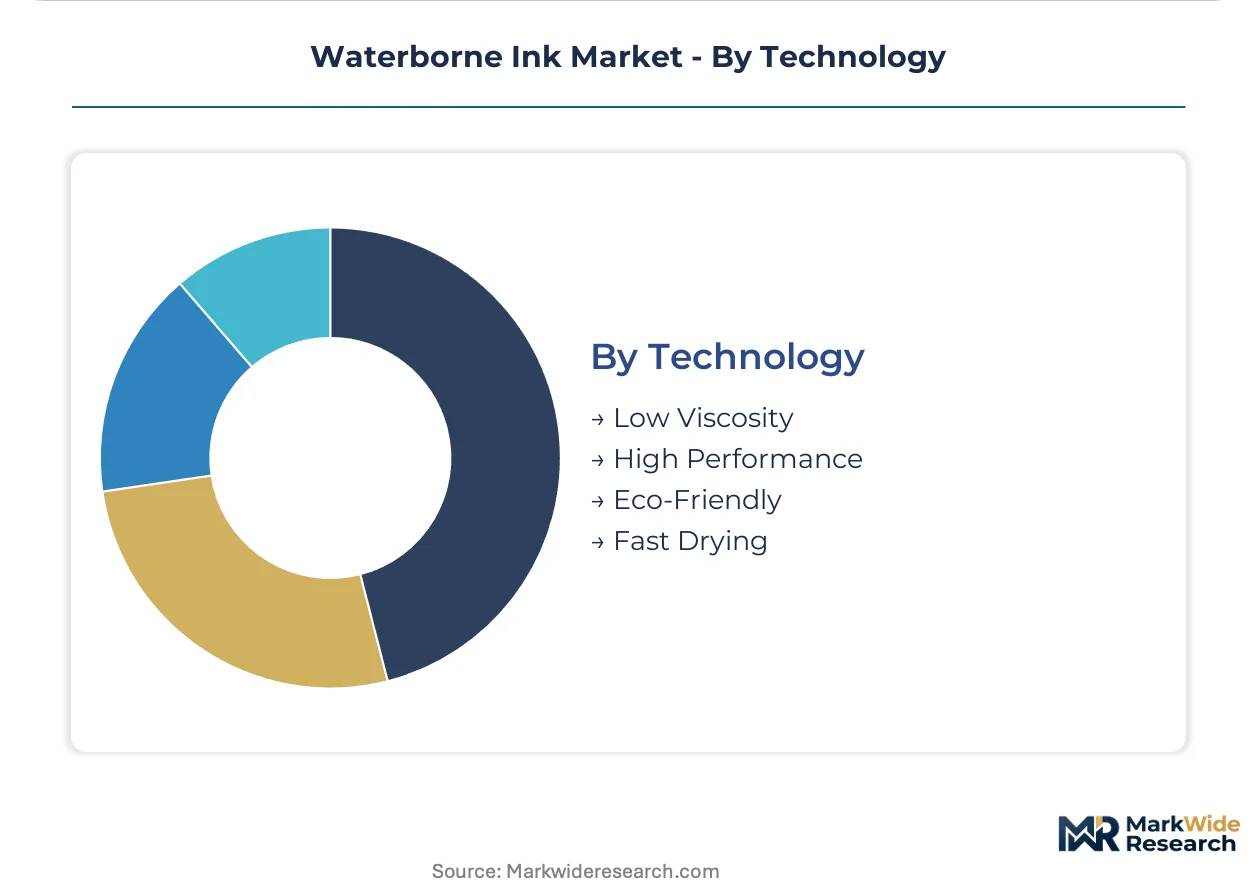
Technology:
Supply concentration sits with resin dispersion chemists capable of bridging performance and compliance in reformulated vehicle systems.
- Eco-Friendly:Bio-based resin vehicles and renewable pigment dispersions with cradle-to-grave carbon documentation. EU Green Deal procurement incentives in public sector tenders weight lifecycle metrics, advantaging ISO 14001-certified suppliers with margin premiums.
- Fast Drying:Modified acrylic and hybrid resin systems with accelerated water release profiles for high-speed corrugated lines. German and Bavarian converters prioritize throughput velocity to offset extended cure cycle constraints versus solvent alternatives.
- Low Viscosity:Reduced solids formulations for high-definition flexo and gravure transfer.
- High Performance:Enhanced rub resistance, gloss, and adhesion for demanding substrate combinations.
Eco-friendly formulations capture premium positioning; fast drying addresses the critical throughput bottleneck.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging converters in Germany, Italy, and the Netherlands are expanding procurement of waterborne formulations as brand owners pursue plastic-reduction commitments and binding VOC compliance deadlines compress legacy supplier margins.
Germany
Print service providers in Baden-Württemberg and Bavaria face binding gravure operation emission thresholds under the Industrial Emissions Directive. The EU Green Deal compliance deadlines are accelerating solvent-to-water technology migrations among corrugated and flexible packaging converters. Stuttgart and Munich industrial clusters concentrate demand for sub-five-percent VOC formulations as procurement qualification requirements tighten.
United States
Corrugated packaging converters in the Midwest and Southeast are retrofitting drying systems to handle waterborne cure profiles. EPA National Emission Standards for Hazardous Air Pollutants govern printing facility solvent thresholds in California, Ohio, and Wisconsin. Chicago and Atlanta metropolitan areas host label printers converting legacy flexo presses to inkjet systems for shorter run lengths.
Italy
Narrow-web label printers in Lombardy and Emilia-Romagna are driving digital ink expansion as versioning requirements multiply. REACH registration mandates are eliminating specific co-solvent chemistries from waterborne vehicles, forcing resin system redesigns. Milan and Bologna packaging districts specify hybrid UV-waterborne systems for premium cosmetic folding carton applications.
China
Integrated pigment and ink production networks in the Yangtze River Delta and Pearl River Delta dominate intermediate supply for Asian packaging converters. The country's dual carbon goals are pressuring domestic formulators toward emission-compliant resin vehicles. Shanghai and Shenzhen industrial corridors supply waterborne dispersions to food-contact substrate producers across Southeast Asia.
Netherlands
Major retail chains headquartered in Amsterdam and Rotterdam now mandate documented VOC content thresholds and third-party environmental certification from packaging converters. EFSA compliance requirements intersect with brand sustainability scorecards to displace price-only procurement models. Randstad logistics hubs distribute certified waterborne formulations to dairy and ready-to-eat segments across Northern Europe.
Waterborne Ink Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive resin manufacturing capabilities and specialized ink formulators with food-contact certification expertise. The supplier base concentrates among legacy European and Japanese manufacturers with established REACH compliance portfolios and ISO 14001 environmental management systems. Two strategic archetypes dominate: vertically integrated pigment-ink producers controlling raw material variability, and formulation specialists anchoring positions through sensitive substrate expertise. Competitive moves center on backward integration into resin dispersion chemistries and strategic partnerships with narrow-web digital press manufacturers.
Within the integrated chemical tier, DIC Corporation and Toyo Ink SC Holdings Co., Ltd. exemplify pigment-ink production network control across Asian supply channels. Among European formulation specialists, Siegwerk Druckfarben AG & Co. KGaA and Hubergroup occupy positions anchored through food-contact substrate certification and REACH-compliant vehicle systems. Sun Chemical represents the vertically integrated archetype with captive resin manufacturing spanning flexo and gravure product lines.
| Leading Market Players |
|---|
| Sun Chemical |
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| Toyo Ink SC Holdings Co., Ltd. |
| Sakata Inx Corporation |
| Hubergroup |
| DIC Corporation |
| INX International Ink Co. |
| Wikoff Color Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with acrylic and polyurethane dispersion suppliers lock in both raw material access and margin visibility for European ink formulators navigating REACH-driven resin system redesigns. These agreements insulate mid-tier suppliers from petrochemical feedstock volatility while securing priority allocation from integrated pigment producers in China.
Pricing Analysis
Cost-plus contracts indexed to crude derivative benchmarks dominate procurement between resin suppliers and ink formulators across Germany and the US. Three-tier pricing structure across premium food-contact certified, standard industrial, and economy-grade formulations differentiates based on FDA notification status and ISO 14001 certification. Pricing pressure stems from Asian pigment concentration compressing margins for non-integrated European formulators. Mid-tier corrugated converters exhibit highest price sensitivity, while cosmetic brand owners in Switzerland and France absorb premiums for hybrid UV-waterborne systems.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German and Italian flexible packaging converters with established supplier relationships, while strategic stockpiling of certified resin dispersions characterizes US converters preparing for EPA enforcement windows. Raw material sourcing draws from Chinese pigment networks, German acrylic dispersion plants, and Japanese polyurethane resin facilities. Single-source vulnerability concentrates in Yangtze River Delta pigment intermediates. Distribution runs through regional chemical distributors serving Baden-Württemberg and Bavaria industrial clusters, with direct mill-to-plant logistics for high-volume corrugated accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne ink incumbents face substitution defense against energy-curable UV systems penetrating premium cosmetic and pharmaceutical folding carton segments where gloss specifications previously demanded solvent platforms.
For Market Incumbents: Consolidate backward integration into captive resin dispersion manufacturing to control formulation variability across flexo and gravure lines. Deepen ISO 14001 certification moats to capture EU Green Deal procurement incentives displacing price-only tender evaluation. Anchor supply contracts with Baden-Württemberg converters facing binding Industrial Emissions Directive thresholds.
For New Entrants and Emerging Players: FDA food-contact notification fast-tracks open penetration paths into dairy and ready-to-eat packaging segments where incumbent certification backlogs extend commercialization cycles. Target narrow-web digital retrofit opportunities in Lombardy and Emilia-Romagna label markets with jettable waterborne formulations. Pursue partnership positioning with Italian inkjet press manufacturers rather than direct converter sales.
For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with established REACH-compliant resin vehicle portfolios and active FDA food-contact notification pipelines. The five-to-ten year viability window favors acquirers of mid-tier European suppliers with certification infrastructure rather than greenfield capacity builds. Watch hybrid UV-waterborne technology penetration rates in Swiss and French cosmetic folding carton segments as inflection signals for premium formulation margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Dispersion | Captive acrylic and polyurethane manufacturing insulates Sun Chemical and Siegwerk from feedstock volatility and REACH-driven reformulation cycles. |
| Hybrid UV-Waterborne Formulation Development | Energy-curable waterborne systems penetrate Swiss and French cosmetic folding carton markets previously reserved for solvent platforms. |
| Narrow-Web Digital Press Partnerships | Formulation alliances with Italian and Spanish inkjet equipment suppliers capture label printer retrofit demand from shortening run lengths. |
| ISO 14001 Certification Investment | Environmental management certification unlocks EU Green Deal public procurement tenders weighting lifecycle carbon metrics. |
| Food-Contact Notification Pipeline Expansion | FDA and EFSA approval accumulation anchors Siegwerk's position in sensitive dairy and ready-to-eat substrate applications. |
Research Methodology
Cross-validation between executive interviews with ink formulation chemists and secondary analysis of ECHA REACH registration databases anchors the qualitative findings in documented regulatory constraints. Primary fieldwork encompassed procurement directors at German flexible packaging converters, technical R&D leads at resin dispersion manufacturers, regulatory affairs managers navigating FDA food-contact protocols, and narrow-web label printers in Northern Italy. Secondary sources included SEC 10-K filings of listed chemical conglomerates, Cefic industry statistics, customs trade data on pigment intermediate flows, and EPA National Emission Standards compliance records. Bottom-up demand modeling from converter procurement patterns triangulates against top-down supply-side capacity assessments.
Sensitivity analysis around crude derivative price trajectories and REACH authorization timelines tests forecast robustness across the projection horizon. Segmentation dimensions span product type, application substrate, end-use industry, technology tier, and regional regulatory cluster. CAGRs derive from installed press base conversion rates, VOC threshold enforcement schedules, and brand sustainability scorecard adoption curves. Industry-specific inputs include gravure operation emission limit compliance costs in Bavaria and digital press retrofit velocity in Lombardy packaging districts.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and incremental REACH enforcement timelines; material deviation would warrant model refresh. Forecasts reflect assumptions regarding converter capex availability for drying system retrofits and continued EU Green Deal procurement incentive durability. Revision becomes warranted when hybrid UV-curable technology penetration in premium cosmetic segments crosses thresholds that structurally displace waterborne formulation margins.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Food Grade Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
North America Ink Market
Printing Inks
Lithography Inks Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Printing Inks Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
United States Printing Inks Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Functional Printing Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Molecular Ink Market