
 Global Water-Based Inks Market | 2026-2036
Global Water-Based Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water-Based Inks Market Foresight
Aftermarket technical service revenue is reshaping margin pools across the Global Water-Based Inks Market, pulling profitability from bulk formulation sales toward color-matching support and press-side troubleshooting. DIC Corporation leverages its integrated pigment and resin operations to control raw material quality for packaging ink customers. Siegwerk Druckfarben AG & Co. KGaA anchors its position through specialized polymer emulsion expertise for flexible food packaging applications. Huber Group competes via regional manufacturing density that shortens lead times for European print service providers.
Water-based inks are colloidal suspensions of pigments or dyes dispersed in water with acrylic, polyurethane, or styrene-acrylate binders, typically formulated at 30-50% solids content for viscosity stability during high-speed gravure or flexographic printing. Their primary purpose is to deliver colorfast, food-safe decoration onto absorbent and non-absorbent substrates while eliminating hydrocarbon solvent emissions from pressroom environments. Packaging Inks command the largest value share as beverage and food brands convert laminated structures to recyclable mono-material designs compatible with water-based chemistries. Nanoparticle Technology represents the fastest-expanding technology segment, enabling thinner ink films with enhanced opacity on oriented polypropylene films that resist water absorption.
EPA regulations under the Clean Air Act constrain solvent emissions from U.S. printing facilities, while REACH and the EU F-Gas Regulation restrict hazardous substance content in imported ink formulations. China's MEE enforces wastewater discharge standards that favor water-based systems with lower chemical oxygen demand in effluent streams. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union and state-level packaging laws in California reshape substrate compatibility requirements and reformulation cycles.
Market Dynamics
REACH restrictions on volatile organic compounds are compressing solvent-based ink margins across European print operations while accelerating converter migration to water-based chemistries. Brand-owner plastic-reduction pledges are pulling formulation demand toward recyclable mono-material substrates compatible with aqueous systems.
Growth Catalysts
- EU Green Deal VOC mandates:REACH Annex XVII limits on solvent emissions force flexible packaging converters in Germany and France to retool presses for water-based gravure and flexographic runs.
- Food-contact safety requirements:FDA and EFSA compliance for direct-contact applications favors water-based systems with lower extractable contaminants versus solvent alternatives.
- Nanoparticle dispersion advances:Thinner film deposition on oriented polypropylene enables opacity performance previously requiring solvent-borne coatings.
Market Restraints
- Acrylic resin price volatility:Crude oil derivative costs for styrene-acrylate binders create quarterly formulation cost instability for ink producers.
- Drying energy intensity:Water evaporation demands 40-60% more thermal input than solvent flash-off, elevating operating costs for high-speed packaging lines.
- Substrate compatibility limits:Non-absorbent films including untreated polyethylene resist water-based adhesion without corona or plasma pre-treatment capital expenditure.
Strategic Opportunities
- India flexible packaging conversion:FSSAI food-contact regulations and BIS standards alignment create first-mover advantage for technical service-capable suppliers establishing local blending capacity.
- Digital-inkjet hybrid integration:Convergence of flexographic base coats with inkjet variable data enables personalized packaging without separate print passes.
- Extended producer responsibility frameworks:EU packaging waste directives reward recyclable mono-material structures that water-based chemistries enable versus multi-layer solvent-laminated alternatives.
Industry Challenges
- Press-side colorimetry expertise gap:Shortage of technicians trained in delta-E matching for water-based systems on non-absorbent substrates extends startup waste cycles.
- Legacy solvent infrastructure stranded assets:Converters face write-down pressures on existing drying and recovery systems during aqueous transition decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water-Based Inks Market |
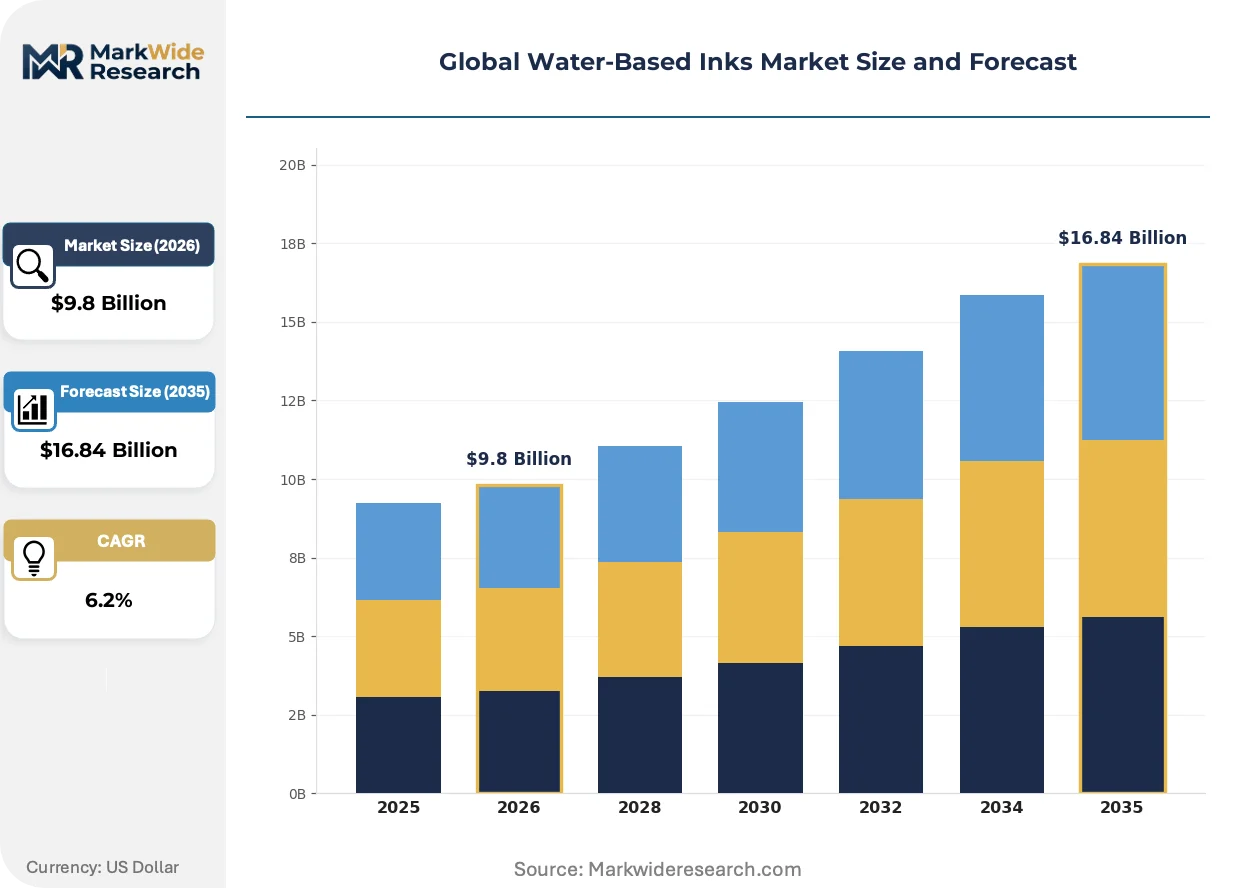
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printing Inks, Coating Inks, Textile Inks, Packaging Inks, Graphic Arts Inks Technology: Pigment Dispersion, Dye-Based, Polymer Emulsion, Resin-Based, Nanoparticle Technology Application: Labeling, Paperboard Printing, Textile Dyeing, Metal Packaging, Flexible Packaging End User: Publishing Houses, Textile Manufacturers, Packaging Companies, Advertising Agencies, Print Service Providers |
| Companies Covered | Toyo Ink SC Holdings Co. Ltd., Nazdar Ink Technologies, DIC Corporation, Huber Group, Fujifilm Sericol, Flint Group, Sun Chemical Group, Bauhinia Variegata Ink & Chemicals, Siegwerk Druckfarben AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water-Based Inks Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-based binders and energy-cured water hybrids that narrow the performance gap with solvent systems on demanding substrates. Technical service capabilities are becoming the primary competitive differentiator as converters prioritize press-side troubleshooting over commodity supply.
Photoinitiator-free UV-LED curable water-based hybrids are rendering obsolete conventional thermal drying tunnels on narrow-web label presses. Narrow-web converters in Italy and Spain are adopting these systems to eliminate natural gas dependency and reduce web handling distortion. The technology is rendering obsolete the 15-meter drying sections that previously constrained press floor layouts and elevated heat-set energy costs.
China's MEE wastewater discharge standards are tightening chemical oxygen demand thresholds for printing facility effluent. Water-based systems with lower COD burdens are gaining preference over solvent alternatives in Guangdong and Zhejiang packaging clusters facing enforcement escalation. Domestic converters are consolidating supplier relationships toward formulators with documented environmental compliance certification.
Brand-owner sustainability scorecards are reshaping procurement evaluation criteria for packaging converters. Unilever and Nestlé purchasing teams now weight carbon footprint and recyclability compatibility above unit ink pricing in annual supplier reviews. European flexible packaging procurement committees are requiring aqueous formulation compatibility certificates as mandatory bid qualifications.
Global Water-Based Inks Market Segmentation
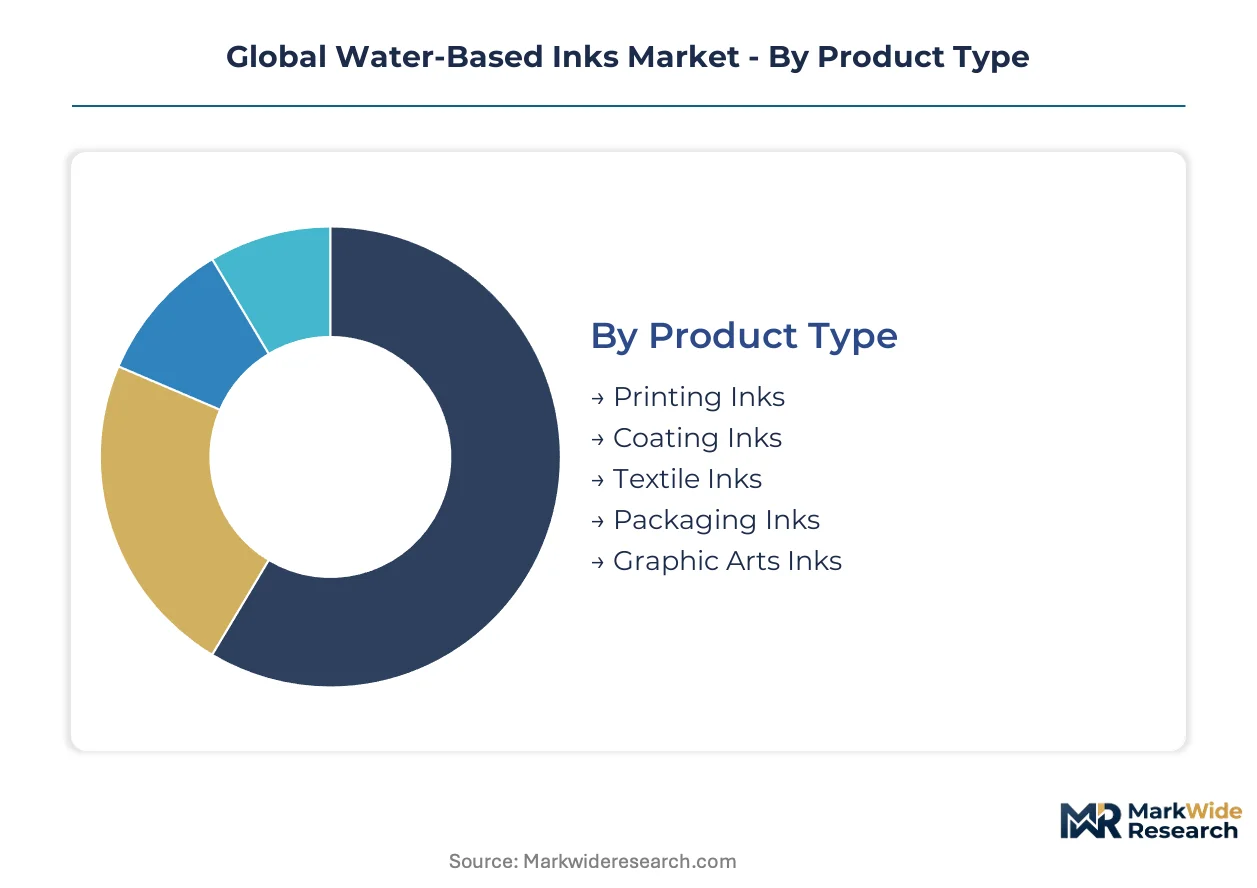
Water-based ink formulations diverge sharply across end-use requirements, with substrate compatibility and regulatory compliance driving portfolio specialization. Each segmentation dimension reveals distinct margin structures and technical service intensity that reshape supplier competitive positioning.
Product Type:
Mature gravure and flexographic formulations coexist with emerging nano-engineered variants across this spectrum.
- Printing Inks:Acrylic and polyurethane-binder suspensions formulated for high-speed gravure and flexographic presses on absorbent stocks. Demand concentrates in German and U.S. commercial print operations where EPA and REACH VOC enforcement accelerates solvent displacement.
- Packaging Inks:Food-contact compliant formulations with low extractable contaminants for direct substrate contact. Beverage and food brands in France and California are converting laminated structures to recyclable mono-material designs compatible with these aqueous chemistries.
- Coating Inks:Protective decorative layers for specialty paper and board applications requiring enhanced rub resistance.
- Textile Inks:Pigment dispersions for digital and screen printing on natural and synthetic fibers with soft-hand requirements.
- Graphic Arts Inks:High-fidelity color formulations for fine art reproduction and premium commercial work.
Packaging Inks handles the majority of throughput; Nanoparticle Technology is the fastest mover on share.
Technology:
Cost tier separation runs from commodity pigment grinding to precision-engineered nano-dispersions requiring specialized equipment.
- Nanoparticle Technology:Sub-100nm pigment dispersions enabling thinner film deposition with enhanced opacity on oriented polypropylene and other non-absorbent films. Flexible packaging converters in Italy and Spain adopt these systems to eliminate corona pre-treatment requirements and reduce coating weights.
- Polymer Emulsion:Styrene-acrylate and pure acrylic latex systems providing film-forming properties and adhesion across diverse substrates. Siegwerk Druckfarben anchors its market position through specialized emulsion expertise for flexible food packaging applications in Germany.
- Pigment Dispersion:Conventional wet-milling processes for standard color strength and stability requirements.
- Dye-Based:Soluble colorant systems offering transparency and brilliance for specific graphic applications.
- Resin-Based:Modified natural and synthetic resin vehicles for specialty adhesion and gloss properties.
Polymer Emulsion commands the largest installed base; Nanoparticle Technology is expanding most quickly as opacity performance gaps close.
Application:
Volume concentration tracks packaging sector procurement patterns with substrate-specific formulation requirements.
- Flexible Packaging:Multi-layer film and pouch decoration requiring adhesion to oriented polypropylene, polyethylene terephthalate, and bio-based alternatives. China's MEE wastewater standards favor these systems in Guangdong and Zhejiang printing clusters facing chemical oxygen demand enforcement.
- Labeling:Pressure-sensitive and wet-glue label stocks demanding rapid drying and rub resistance. Narrow-web converters adopt photoinitiator-free UV-LED curable hybrids to eliminate natural gas dependency in Italian and Spanish operations.
- Paperboard Printing:Folding carton and corrugated post-print applications with high absorbency permitting simpler formulation economics.
- Metal Packaging:Two-piece and three-piece can decoration requiring specialized adhesion and sterilization resistance.
- Textile Dyeing:Continuous and batch processes for fabric coloration with fastness and handle requirements.
Flexible Packaging generates the dominant volume share; Labeling is gaining share fastest through digital hybrid integration.
End User:
Customer type determines technical service intensity and procurement sophistication across the value chain.
- Packaging Companies:Integrated converters and independent flexible packaging specialists requiring press-side color matching and troubleshooting support. Unilever and Nestlé procurement teams now weight carbon footprint and recyclability compatibility above unit ink pricing in annual supplier reviews.
- Print Service Providers:Commercial and specialty printers with diverse equipment fleets needing formulation consistency across multiple press configurations. Huber Group competes through regional manufacturing density that shortens lead times for European PSP networks.
- Publishing Houses:Periodical and book printers with high-volume, price-sensitive requirements for heat-set and coldset applications.
- Textile Manufacturers:Vertical apparel and home goods producers with digital and conventional printing integration needs.
- Advertising Agencies:Specifiers of premium promotional and display graphics with color fidelity demands.
Packaging Companies represent the deepest technical service engagement; Print Service Providers show the steepest expansion trajectory in aftermarket revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany and France absorb formulation premiums without volume elasticity, while Indian and Chinese buyers prioritize unit cost compression over technical service intensity. This demand-elasticity divide shapes supplier margin architecture across geographies.
United States
Flexible packaging converters in Wisconsin and Ohio are retooling gravure presses for water-based runs as brand owners enforce plastic-reduction timelines. EPA Clean Air Act enforcement constrains solvent emissions from Ohio and Illinois printing facilities. Chicago-area technical service laboratories co-located with major ink producers support real-time color matching for high-speed packaging lines.
Germany
REACH Annex XVII VOC limits force flexible packaging specialists in Baden-Württemberg and Bavaria to accelerate solvent-to-water transitions. EU Green Deal mandates compress solvent-based ink margins across German print operations. The Stuttgart and Munich industrial corridors concentrate co-development partnerships between ink formulators and automotive packaging suppliers.
China
Guangdong and Zhejiang packaging clusters favor water-based systems as MEE wastewater discharge standards tighten chemical oxygen demand thresholds. Domestic converters consolidate supplier relationships toward formulators with documented environmental compliance certification. Shenzhen and Dongguan printing facilities face enforcement escalation on effluent quality.
India
FSSAI food-contact regulations and BIS standards alignment create first-mover advantage for technical service-capable suppliers establishing local blending capacity. Flexible packaging conversion accelerates in Maharashtra and Gujarat as multinational brands localize supply chains. Mumbai and Ahmedabad industrial zones attract ink producers building regional formulation plants.
Italy
Narrow-web converters in Lombardy and Emilia-Romagna adopt photoinitiator-free UV-LED curable hybrids to eliminate natural gas dependency. Italian label printers prioritize energy-cured water systems that reduce web handling distortion. Bologna and Milan packaging districts lead European adoption of hybrid inkjet-flexographic integration.
Global Water-Based Inks Market Competitive Landscape
Capability concentration sits with integrated pigment-resin operations; scale advantage sits with regional manufacturing networks. The market structures around three tiers: multinational chemical conglomerates with captive raw material supply, specialized ink formulators with polymer emulsion expertise, and regional blenders competing on logistics proximity. Dominant competitive moves include technical service co-location with packaging customers and backward integration into acrylic resin production.
Within the integrated chemical tier, DIC Corporation and Toyo Ink SC Holdings Co. Ltd. exemplify upstream control over pigment and binder quality. Siegwerk Druckfarben AG & Co. KGaA anchors the specialized formulator segment through polymer emulsion expertise. Huber Group represents regional manufacturing density strategies that compress lead times for European print service providers.
| Leading Market Players |
|---|
| Toyo Ink SC Holdings Co. Ltd. |
| Nazdar Ink Technologies |
| DIC Corporation |
| Huber Group |
| Fujifilm Sericol |
| Flint Group |
| Sun Chemical Group |
| Bauhinia Variegata Ink & Chemicals |
| Siegwerk Druckfarben AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese acrylic resin production is compressing formulation margins while simultaneously extending supplier payment terms for German and Indian ink producers. This utilization asymmetry between raw material supply and finished ink demand creates divergent pricing power across the value chain, with integrated pigment-resin operators capturing margin that blenders cannot access.
Pricing Analysis
After-sales technical service revenue now drives lifetime value capture across the Global Water-Based Inks Market, with color-matching support and press-side troubleshooting commanding premium multiples over bulk formulation sales. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels separates food-contact validated formulations from commercial print grades. Cost compression in economy tiers is intensifying because Guangdong converters consolidate volume toward environmentally certified suppliers. Packaging companies with sustainability scorecard requirements show lowest price sensitivity; commodity commercial printers exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier relationships with European flexible packaging converters, reflecting working capital pressure from energy-intensive drying operations. Raw material supply concentrates in China for acrylic resins, Germany for specialized polymer emulsions, and India for pigment dispersions. Formulation chemistry draws from crude oil derivatives for styrene-acrylate binders, titanium dioxide for opacity, and bio-based feedstocks for emerging sustainable alternatives. Single-source vulnerability sits with nanoparticle dispersion equipment manufacturers in Japan and Germany. Distribution runs through regional blending facilities co-located with technical service laboratories in Wisconsin, Bavaria, and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against solvent-borne ink recovery as energy costs moderate and UV-LED hybrid systems mature. Incumbents must navigate the threat of performance convergence between aqueous and solvent chemistries on non-absorbent films.
For Market Incumbents: Pre-empt solvent system resurgence by accelerating nanoparticle opacity performance on oriented polypropylene without corona pre-treatment. Anchor backward integration into acrylic resin production to buffer styrene price volatility. Lock in technical service co-location with Unilever and Nestlé procurement committees before sustainability scorecard criteria harden.
For New Entrants and Emerging Players: Build out local blending capacity in Maharashtra and Gujarat to capture FSSAI compliance-driven consolidation among Indian flexible packaging converters. Target narrow-web label printers in Lombardy with photoinitiator-free UV-LED curable hybrid offerings. Lead with energy-cured water systems that eliminate natural gas dependency as the go-to-market wedge.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nanoparticle dispersion technology as sub-100nm equipment requirements escalate. Five-to-ten year viability favors integrated pigment-resin operators over regional blenders lacking upstream control. Acquire specialized polymer emulsion formulators with documented EU Green Deal compliance certification. Monitor MEE enforcement escalation in Guangdong as the inflection signal for Chinese market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Laboratory Co-location | Real-time color matching for Wisconsin and Bavaria packaging lines compresses startup waste cycles. |
| Backward Integration into Acrylic Resin | In-house styrene-acrylate production buffers quarterly cost instability from crude oil derivatives. |
| Nanoparticle Dispersion Capability Buildout | Sub-100nm opacity performance on oriented polypropylene eliminates corona pre-treatment capital expenditure. |
| Photoinitiator-Free UV-LED Hybrid Launch | Energy-cured water systems eliminate natural gas dependency for Italian narrow-web converters. |
| Environmental Compliance Certification Investment | Documented MEE wastewater standards alignment secures supplier consolidation in Guangdong clusters. |
Research Methodology
Initial hypotheses were tested against primary input from flexible packaging procurement managers, gravure press operators, polymer emulsion R&D directors, and regulatory compliance officers, then refined against secondary validation from customs trade data, EPA enforcement records, REACH Annex XVII filings, and EU Green Deal implementation reports. Bottom-up triangulation across formulation chemistry interviews combined with top-down demand modeling from beverage and food brand sustainability disclosures.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product type, technology tier, application substrate, and end-user procurement sophistication. CAGRs derived from capacity utilization rates in Chinese resin production, converter retooling timelines in Germany and France, and enforcement intensity trajectories for MEE wastewater standards. Industry-specific inputs included nanoparticle dispersion adoption curves and UV-LED curing infrastructure deployment patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed resin producers or accelerated solvent system innovation by European competitors would shift outcomes. Macroeconomic energy cost volatility, regulatory deviation on extended producer responsibility timelines, or breakthrough substrate pre-treatment technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
United States Printing Inks Market
Printing Inks
Food Marking Inks Market
Printing Inks
UV Cured Inks Market
Printing Inks
Functional Printing Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Printing Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Commercial Printing Market
Printing Inks
Global Digital Inks Market