
 Lithography Inks Market | 2026-2036
Lithography Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Lithography Inks Market Analysis
Japanese chemical producers is recalibrating capacity allocations across photoresist-compatible ink lines. DIC Corporation leverages its integrated pigment synthesis network to sustain supply security for high-purity grades. FUJIFILM Holdings America Corporation anchors North American demand through specialized formulations for semiconductor packaging substrates. Siegwerk Druckfarben AG & Co. KGaA competes in European food-contact segments with migration-controlled product portfolios.
Lithography inks comprise finely dispersed pigments or dyes in resin vehicles, formulated with controlled viscosity between 30 and 80 Poise for precise transfer through offset blanket cylinders or direct imaging systems. These formulations enable high-resolution pattern replication on paper, film, and metalized substrates for commercial, industrial, and electronic applications. UV-curable formulations command premium positioning due to instant polymerization and elimination of volatile organic compound emissions. Offset technology retains volume leadership in long-run publishing and corrugated packaging, while digital lithography segments expand fastest in short-run personalized packaging and pharmaceutical serialization. Water-based systems dominate food packaging applications where FDA and EU food-contact compliance is mandatory.
REACH restrictions on aromatic amines and heavy metal pigments in Europe, FDA food-contact notification requirements under 21 CFR in the United States, and Japan's JIS standards for printing ink safety collectively constrain formulation freedom and elevate R&D expenditure. Compliance with these frameworks now functions as a market access gate rather than a voluntary quality marker. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Semiconductor packaging substrate manufacturers are pulling lithography ink formulations toward tighter viscosity tolerances and metal-ion purity thresholds, compressing supplier qualification cycles and fragmenting procurement across specialized grades.
Growth Catalysts
- UV-curable instant polymerization:Semiconductor fabricators in Japan and South Korea specify these formulations for wafer-level packaging, eliminating solvent emissions while accelerating throughput.
- REACH aromatic amine restrictions:European ink producers are reformulating pigment dispersions ahead of enforcement deadlines, creating first-mover certification premiums for compliant suppliers.
- Corrugated packaging volume:Long-run offset lithography for e-commerce shipping boxes sustains demand for conventional resin-vehicle inks across East Asian converting clusters.
Market Restraints
- Photoresist-grade pigment concentration:High-purity colorant synthesis capacity clusters with Japanese chemical conglomerates, exposing downstream formulators to allocation risk.
- Heavy metal pigment substitution costs:Cadmium and lead-based colorants still anchor certain high-opacity applications, forcing expensive reformulation where REACH and FDA food-contact rules intersect.
- Digital inkjet displacement in short runs:Pharmaceutical serialization and personalized packaging segments are bypassing lithography entirely for variable-data direct imaging.
Strategic Opportunities
- Water-based food-contact compliance in North America:FDA 21 CFR notification pathways for new polymer vehicles remain underutilized by European suppliers with existing EFSA clearances.
- India electronics manufacturing zones:BIS certification requirements for imported printing materials create localization incentives for ink compounders near Gujarat and Tamil Nadu semiconductor assembly plants.
- Dual-cure formulation convergence:Hybrid UV-thermal systems enable adhesion to low-surface-energy films for flexible electronics substrates, opening medical device packaging applications.
Industry Challenges
- Colorimetric calibration expertise scarcity:Formulators struggle to recruit spectrophotometry specialists capable of matching Delta-E tolerances below 1.0 for semiconductor alignment marks.
- Cross-jurisdiction inventory stranding:Divergent REACH, FDA, and JIS heavy metal thresholds force SKU proliferation and complicate regional hub stocking strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithography Inks Market |
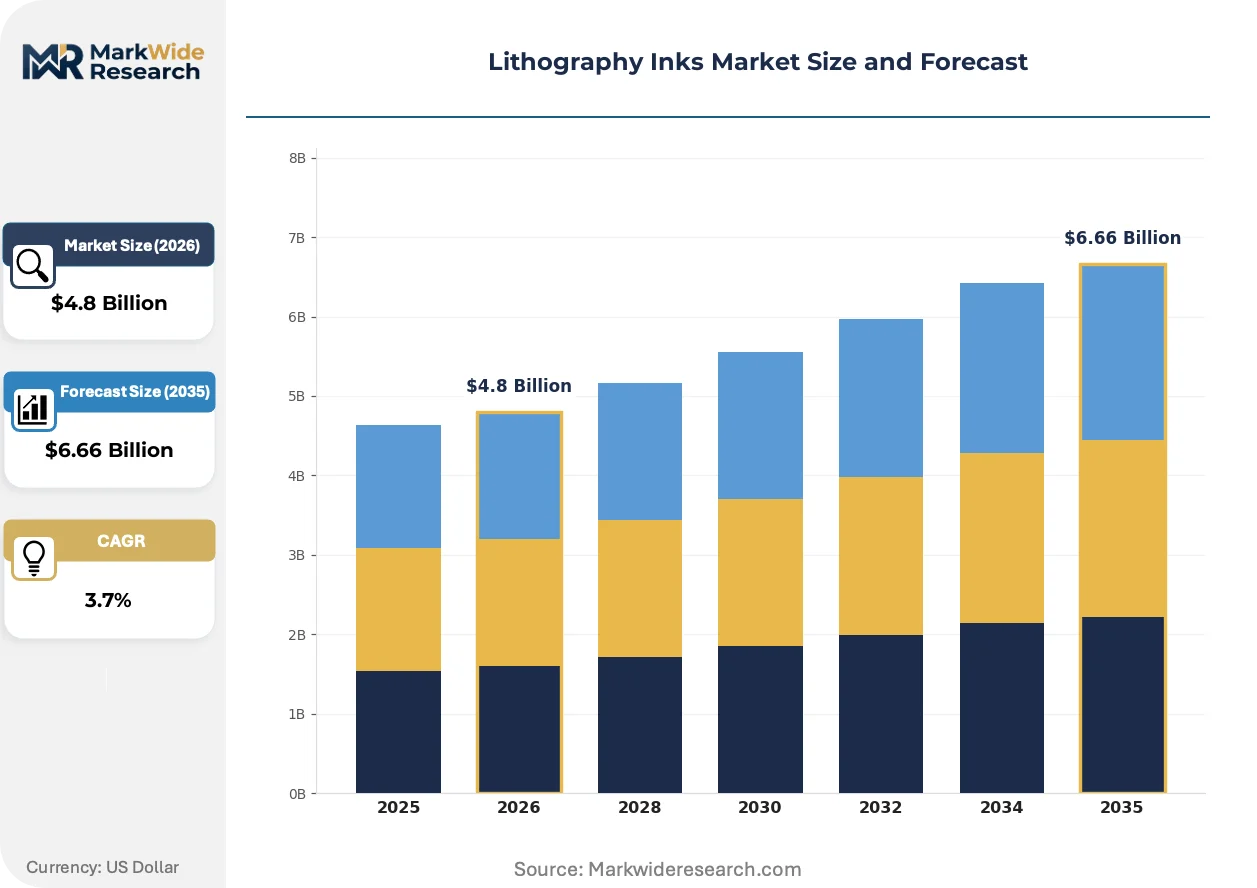
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, UV-Curable, Solvent-Based, Hybrid End User: Packaging, Publishing, Commercial Printing, Labeling Technology: Offset, Flexo, Digital, Gravure Application: Food Packaging, Pharmaceuticals, Textiles, Stationery |
| Companies Covered | DIC Corporation, Flint Group, FUJIFILM Holdings America Corporation, Huber Group, INX International Ink Co., Siegwerk Druckfarben AG & Co. KGaA, T&K Toka Co. Ltd., Tokyo Printing Ink Mfg. Co. Ltd., Toyo Ink Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithography Inks Market Emerging Trajectories
Formulation chemistry and regulatory compliance frameworks are locking into tighter co-evolution, with ink producers racing to pre-certify platforms against multiple jurisdiction standards simultaneously rather than sequentially.
Nano-particle pigment dispersion technology is overtaking conventional micron-scale milling for sub-10-micron feature printing in advanced packaging. Taiwan-based substrate producers specify these grades for redistribution layer patterning. The technology is compressing minimum viable batch sizes and enabling just-in-time formulation at foundry-adjacent sites.
EU Green Deal chemical sustainability reporting requirements are forcing disclosure of full substance inventories across ink supply chains. Formulators serving food-contact and toy segments face the steepest documentation burdens. German packaging converters are demanding third-party-verified carbon footprints as procurement gate criteria.
Consolidated specification-setting by semiconductor substrate consortia is displacing individual foundry ink approvals. Buyers in South Korea and Japan now delegate technical qualification to equipment-OEM partnerships. This concentrates vendor selection power with Tokyo Electron and SCREEN Holdings process tool divisions.
Lithography Inks Market Segmentation
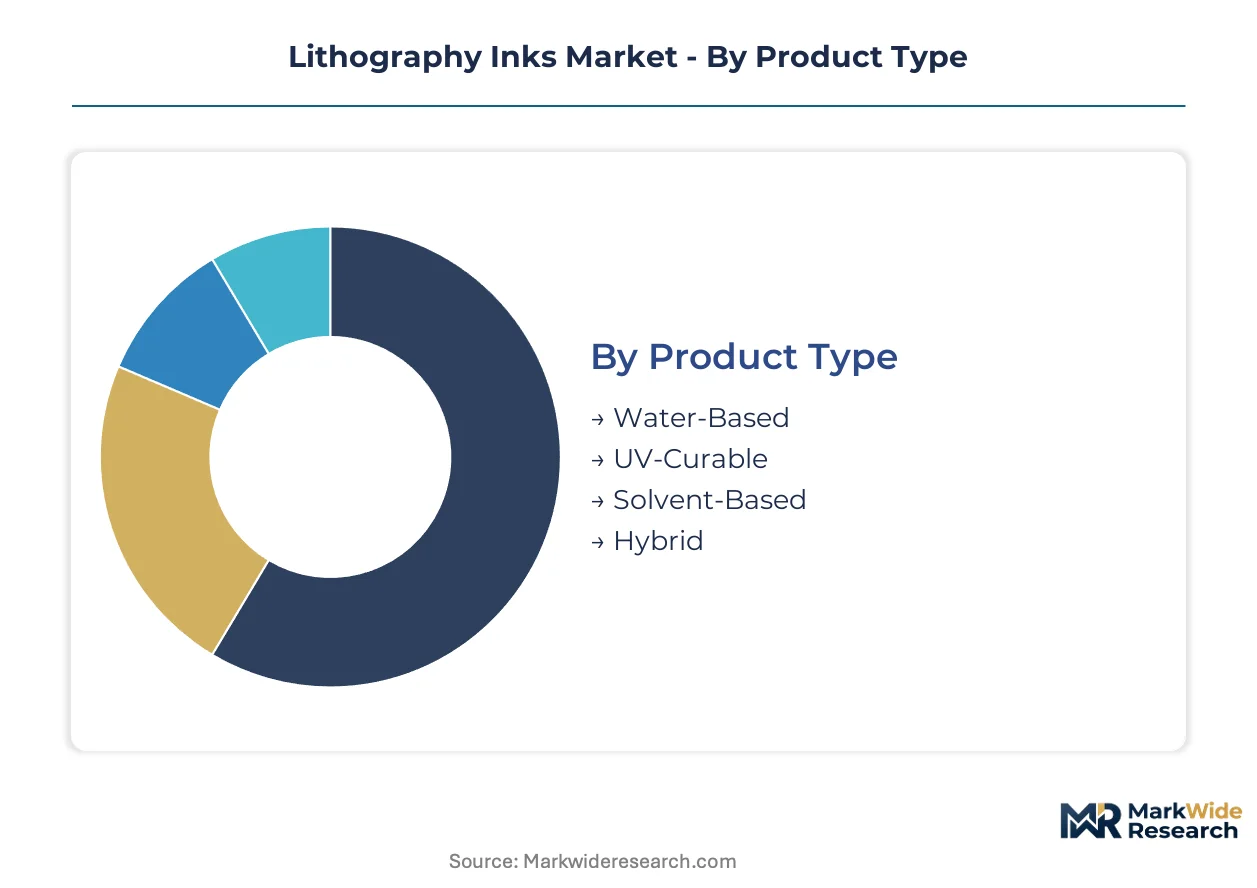
Segmentation in lithography inks reveals how formulation chemistry and regulatory compliance requirements fragment procurement across end-use verticals. Each dimension—product chemistry, end user, technology platform, and application—carries distinct certification burdens that constrain supplier eligibility and shape margin structures.
Product Type:
Water-based formulations require FDA 21 CFR food-contact notification in the United States and EFSA compliance in Europe, while UV-curable grades face REACH aromatic amine scrutiny and JIS standards in Japan.
- Water-Based:Acrylic and polyurethane resin vehicles dispersed in aqueous carriers dominate food packaging applications. FDA notification pathways for new polymer vehicles remain underutilized by European suppliers with existing EFSA clearances, creating first-mover opportunities in North American corrugated and flexible food packaging.
- UV-Curable:Photoinitiator-activated acrylate oligomers polymerize instantly under UV exposure, eliminating solvent emissions. Semiconductor fabricators in Japan and South Korea specify these formulations for wafer-level packaging, where throughput acceleration justifies premium pricing over thermal drying systems.
- Solvent-Based:Traditional hydrocarbon and ester solvent vehicles persist in long-run publishing and industrial decorative printing where evaporation drying infrastructure is sunk.
- Hybrid:Dual-cure systems combining UV and thermal mechanisms enable adhesion to low-surface-energy films for flexible electronics substrates.
Water-based sits at the top of the volume ranking, with UV-curable climbing the fastest.
End User:
Customer procurement power varies sharply across this dimension, with semiconductor packaging substrate manufacturers imposing the tightest viscosity tolerances and metal-ion purity thresholds.
- Packaging:Corrugated e-commerce shipping boxes sustain demand for conventional resin-vehicle inks across East Asian converting clusters. REACH heavy metal thresholds and FDA food-contact rules force expensive reformulation where regulations intersect.
- Publishing:Long-run offset lithography for books and periodicals retains volume leadership but faces digital displacement pressure. Water-based systems are gaining share in magazine production where VOC regulations tighten.
- Commercial Printing:Short-run personalized materials and marketing collateral increasingly bypass lithography for inkjet systems.
- Labeling:Pharmaceutical serialization requirements favor variable-data digital technologies over conventional lithographic platemaking.
Packaging commands the largest revenue pool, while semiconductor-linked packaging applications expand most quickly.
Technology:
Equipment-OEM partnerships in South Korea and Japan now delegate technical qualification to process tool divisions, concentrating vendor selection power with Tokyo Electron and SCREEN Holdings.
- Offset:Blanket cylinder transfer systems retain dominance in long-run publishing and corrugated packaging. DIC Corporation leverages integrated pigment synthesis networks to sustain supply security for high-purity offset grades specified by Japanese substrate producers.
- Flexo:Anilox roll metering suits flexible packaging and label applications where substrate thickness varies. Water-based flexo formulations dominate food-contact segments in Europe where REACH aromatic amine restrictions bite hardest.
- Digital:Direct imaging bypasses platemaking entirely, capturing pharmaceutical serialization and personalized packaging from lithographic competitors.
- Gravure:Engraved cylinder systems persist in high-volume decorative and publication printing where capital equipment is depreciated.
Offset maintains volume leadership, with digital gaining share fastest in short-run segments.
Application:
Migration-controlled product portfolios separate premium suppliers from commodity competitors in food-contact and pharmaceutical segments.
- Food Packaging:FDA and EU food-contact compliance is mandatory, with water-based systems dominating. German packaging converters now demand third-party-verified carbon footprints as procurement gate criteria under EU Green Deal sustainability reporting requirements.
- Pharmaceuticals:Serialization mandates and anti-counterfeiting features favor variable-data digital technologies. Nano-particle pigment dispersions specified by Taiwan-based substrate producers enable sub-10-micron feature printing for advanced packaging redistribution layers.
- Textiles:Specialty formulations for fabric printing face less stringent regulatory burdens than food-contact applications.
- Stationery:Commodity grades compete primarily on cost and color gamut rather than certification premiums.
Food Packaging generates the highest certification-driven margins, with Pharmaceuticals showing the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between REACH-compliant Europe and FDA-governed North America creates compliance-cost arbitrage, pushing formulation R&D toward jurisdictions with harmonized standards while production clusters concentrate where semiconductor packaging demand is densest.
Japan
Wafer-level packaging demand from Tokyo Electron and SCREEN Holdings process tool partnerships drives specification-setting for photoresist-compatible ink grades. METI oversees JIS standards for printing ink safety that constrain heavy metal thresholds. The Kanto region around Tokyo anchors integrated pigment synthesis networks serving high-purity semiconductor substrate applications.
South Korea
Semiconductor fabricators specify UV-curable formulations for throughput acceleration in advanced packaging lines. MFDS maintains migration controls for food-contact materials that parallel REACH aromatic amine restrictions. The Seoul Capital Area concentrates procurement delegation to equipment-OEM partnerships, compressing supplier qualification cycles.
United States
FDA 21 CFR food-contact notification requirements for new polymer vehicles create first-mover certification premiums for compliant water-based formulations. EPA VOC regulations tighten in magazine production segments. The Pacific Northwest and Texas electronics manufacturing corridors pull lithography ink consumption toward semiconductor packaging substrates.
Germany
EU Green Deal chemical sustainability reporting requirements force disclosure of full substance inventories across ink supply chains. ECHA REACH enforcement on aromatic amines and heavy metal pigments drives reformulation ahead of deadlines. The Ruhr industrial cluster and Bavarian packaging converting regions demand third-party-verified carbon footprints as procurement gates.
India
BIS certification requirements for imported printing materials create localization incentives near Gujarat and Tamil Nadu semiconductor assembly plants. The country's national pharmaceutical regulator aligns serialization mandates with variable-data digital displacement pressures. Maharashtra and Karnataka electronics manufacturing zones anchor demand for migration-controlled food-contact and pharmaceutical packaging grades.
Lithography Inks Market Vendor Landscape
Japanese producers anchor one tier through integrated pigment synthesis networks; European specialists hold certification-driven positions in food-contact segments. The supplier base fragments across equipment-OEM partnerships in East Asia and independent formulators serving corrugated packaging in Europe and North America. Three archetypes dominate: chemical conglomerates with captive colorant supply, regional ink compounders with regulatory pre-certification depth, and digital-technology hybrids bypassing lithography entirely. Competitive moves concentrate on dual-cure formulation R&D partnerships and carbon footprint verification for EU Green Deal compliance.
Among Japan-based chemical producers, DIC Corporation and T&K Toka Co. Ltd. exemplify the integrated-pigment-synthesis archetype, while FUJIFILM Holdings America Corporation represents the regional-formulation-specialist model with North American anchoring. These three occupy positions that reflect the market's geographic split between East Asian semiconductor packaging demand and Western regulatory compliance premiums.
| Leading Market Players |
|---|
| DIC Corporation |
| Flint Group |
| FUJIFILM Holdings America Corporation |
| Huber Group |
| INX International Ink Co. |
| Siegwerk Druckfarben AG & Co. KGaA |
| T&K Toka Co. Ltd. |
| Tokyo Printing Ink Mfg. Co. Ltd. |
| Toyo Ink Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive pigment synthesis networks at DIC Corporation and T&K Toka Co. Ltd. anchor both supply security and pricing power for photoresist-compatible ink grades, compressing margins for downstream formulators lacking backward integration into high-purity colorant production.
Pricing Analysis
Distributor margins on UV-curable semiconductor packaging grades run 15-20 points above conventional offset inks due to qualification complexity and metal-ion purity thresholds. Three-tier pricing structure across photoresist-grade, food-contact certified, and commodity corrugated tiers separates premium capture from volume erosion. Cost compression in standard offset segments intensifies as digital inkjet displacement accelerates in short-run pharmaceutical serialization. Semiconductor substrate manufacturers show lowest price sensitivity, while corrugated packaging converters in East Asia negotiate hardest on resin-vehicle formulations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Tokyo Electron and SCREEN Holdings process tool partnerships, bypassing traditional distribution layers for qualified semiconductor packaging grades. Raw material concentration in Japan and South Korea for photoresist-grade pigments, Germany for specialty photoinitiators, and China for commodity acrylic resins creates geographic dependency. Single-source vulnerability in high-purity colorant synthesis exposes formulators to allocation risk during capacity recalibration. Distribution runs through equipment-OEM technical qualification partnerships in East Asia and independent regional compounders in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithography inks function as a stable compounder anchored by semiconductor packaging substrate demand, where wafer-level packaging expansion sustains premium-grade consumption regardless of publishing segment cyclicality.
For Market Incumbents: Extend certification depth across REACH, FDA 21 CFR, and JIS standards simultaneously rather than sequentially to preempt cross-jurisdiction inventory stranding. Deepen backward integration into nano-particle pigment dispersion technology specified by Taiwan-based substrate producers for sub-10-micron feature printing. Lock long-term supply agreements with Tokyo Electron and SCREEN Holdings process tool divisions before qualification cycles compress further. For New Entrants and Emerging Players: Enter via FDA 21 CFR food-contact notification pathways for water-based polymer vehicles, where European suppliers with existing EFSA clearances have underinvested in North American corrugated and flexible packaging. Target BIS certification localization near Gujarat and Tamil Nadu semiconductor assembly plants, where Indian electronics manufacturing zones create procurement pull for migration-controlled grades. Lead with carbon footprint verification to meet EU Green Deal procurement gates demanded by German packaging converters. For Investors and Strategic Acquirers: Roll-up economics work for regional ink compounders with regulatory pre-certification depth because compliance moats in food-contact and pharmaceutical segments resist commoditization pressure. The 5-10 year viability window favors acquisition of mid-cap formulators holding dual-cure formulation capabilities for flexible electronics substrates. Watch for inflection when semiconductor substrate consortia consolidate specification-setting authority, accelerating vendor selection concentration with equipment-OEM partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | DIC Corporation's captive colorant supply secures allocation priority during high-purity grade shortages. |
| Dual-Cure Formulation R&D Partnerships | Hybrid UV-thermal systems enable adhesion to low-surface-energy films for medical device packaging. |
| Carbon Footprint Verification Programs | Third-party certification satisfies EU Green Deal procurement gates at German packaging converters. |
| Equipment-OEM Technical Qualification | Tokyo Electron partnerships compress vendor selection cycles for semiconductor substrate producers. |
| Multi-Jurisdiction Pre-Certification | Simultaneous REACH, FDA, and JIS compliance prevents cross-border inventory stranding. |
Methodological Framework
Coverage spans Japan, South Korea, the United States, Germany, and India, with primary inputs from each combining interviews with semiconductor packaging substrate procurement managers, ink formulator R&D directors, corrugated packaging converters, regulatory affairs specialists at chemical producers, and distribution channel partners. Secondary validation drew from ECHA REACH enforcement bulletins, FDA 21 CFR food-contact notification databases, METI JIS standard publications, SEC filings from listed chemical conglomerates, and trade customs data on photoresist-grade pigment flows. Bottom-up demand modeling across end-use verticals triangulated with top-down supply capacity assessments.
Granularity-level modeling operated at product chemistry tier, end-use vertical, technology platform, and application segment dimensions, with additional disaggregation by regional regulatory cluster and metal-ion purity threshold. CAGRs were derived from segment-level volume trajectories weighted by value-per-unit differentials across the projection horizon. Forecast inputs incorporated semiconductor packaging substrate capacity buildout schedules, REACH aromatic amine restriction enforcement timelines, and digital inkjet displacement rates in pharmaceutical serialization.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time inventory positioning data at regional hub stocking locations introduce uncertainty bands around quarterly demand fluctuations. Forecasts reflect base assumptions on equipment-OEM partnership stability and pigment synthesis capacity allocation priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Molecular Ink Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
North America Printing Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Food Grade Inks Market