
 Automotive Low Emission Vehicle Market | 2026-2036
Automotive Low Emission Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Low Emission Vehicle Market Analysis
Multi-source battery procurement is repositioning how automakers manage supply security and cost volatility. Tesla leverages its in-house cell production at Gigafactories to sustain margin control across the value chain. Toyota anchors its competitive stance through hybrid electric vehicle expertise while navigating solid-state battery development timelines. BYD dominates vertical integration from lithium mining through finished vehicle assembly, a structure that insulates pricing power.
Automotive low emission vehicles integrate electric drivetrains, energy storage systems, and power electronics to deliver propulsion with minimal or zero tailpipe emissions, typically achieving CO2 outputs below 50 grams per kilometer under standardized test cycles. The vehicle type dimension shows battery electric vehicles capturing the fastest expansion trajectory as charging infrastructure density improves and lithium-ion pack costs decline. Within battery technology, solid-state configurations represent the emerging margin pool, though lithium-ion maintains near-term production scale leadership due to established cathode supply chains and cell manufacturing equipment.
The EPA tailpipe standards and Euro 7 emission framework are compressing internal combustion engine production timelines, directly shaping OEM platform investment priorities. China's MIIT new energy vehicle mandates and credit trading system create enforced demand floors that manufacturers must satisfy through battery electric or plug-in hybrid volume. Stakeholders must monitor regulatory calibration between emission limits and infrastructure subsidy phase-outs, as premature support withdrawal risks demand discontinuity before total cost parity stabilizes.
Market Dynamics
Automotive low emission vehicle production is concentrating around battery chemistry standardization as lithium iron phosphate and nickel manganese cobalt cathodes compete for platform allocation, while OEMs face compressed development cycles from Euro 7 and EPA tailpipe mandates.
Growth Catalysts
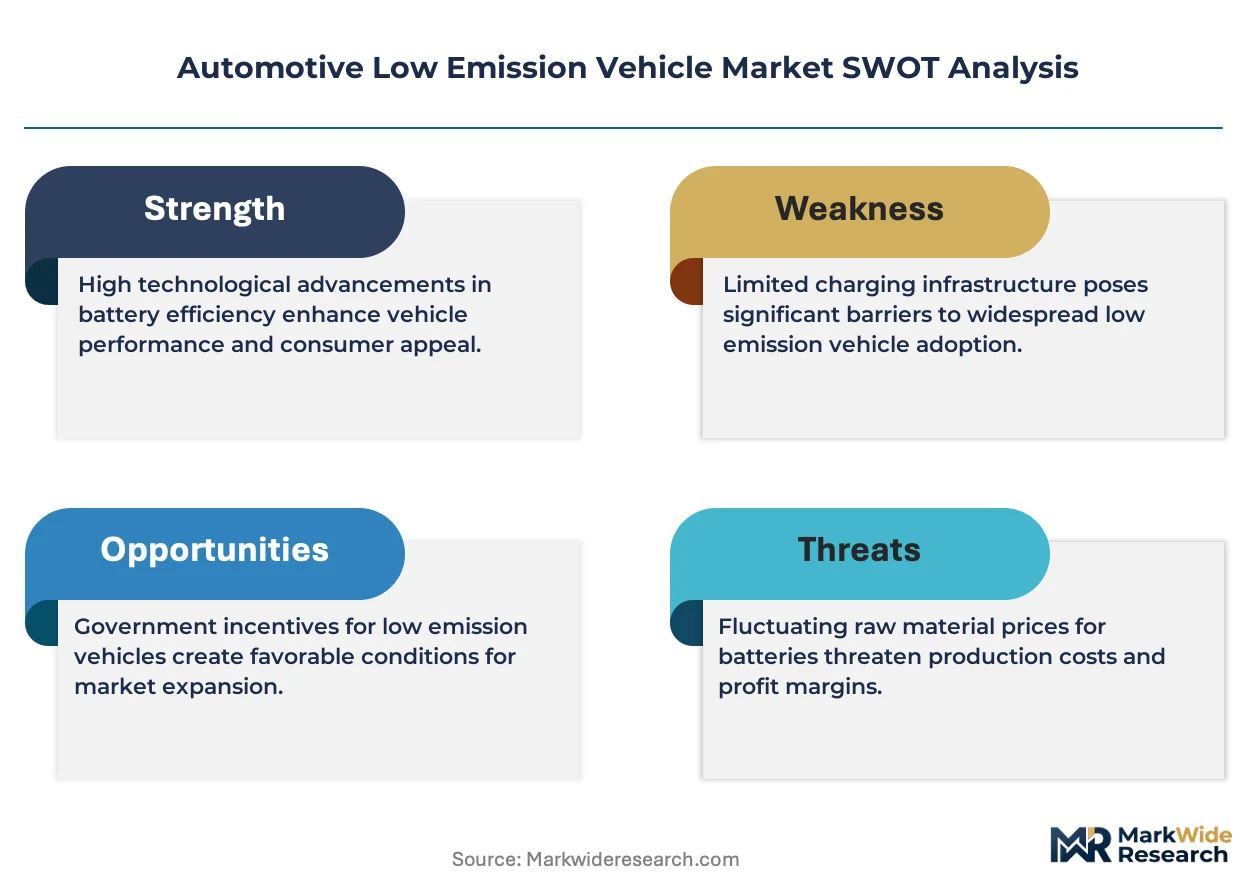
- EPA Tier 3 and Euro 7 tailpipe standards:These frameworks enforce CO2 emission ceilings that eliminate internal combustion engine viability for new passenger car platforms by 2030.
- Charging infrastructure density improvements:Public DC fast charging networks in Germany, France, and the Netherlands now enable battery electric vehicle operation without home charging access.
- Lithium-ion pack cost declines:Cathode active material processing scale and cell manufacturing automation have reduced pack-level costs below internal combustion powertrain parity thresholds.
Market Restraints
- Critical mineral supply concentration:Cobalt refining capacity concentrates in the Democratic Republic of Congo and Chinese processing facilities, creating price volatility exposure.
- Charging interoperability fragmentation:Multiple connector standards and payment systems across national markets create consumer friction and fleet deployment complexity.
- Grid capacity constraints:Distribution infrastructure in older urban centers cannot support simultaneous fast charging demand from commercial fleets without capital-intensive upgrades.
Strategic Opportunities
- Commercial fleet electrification in India:Two-wheeler and three-wheeler last-mile delivery segments remain underpenetrated relative to passenger cars, with PLI scheme subsidies reducing acquisition barriers.
- Solid-state battery technology convergence:Sulfide and oxide electrolyte chemistries paired with silicon anodes promise energy density improvements that could extend range thresholds for heavy-duty applications.
- Battery-as-a-service channel innovation:Subscription models separating vehicle purchase from energy storage ownership reduce upfront costs and transfer residual value risk to financial intermediaries.
Industry Challenges
- Power electronics engineering talent scarcity:Inverter and onboard charger design capabilities lag behind cell chemistry and software development hiring pipelines.
- Homologation timeline compression:UN ECE R100 and R10 certification requirements for high-voltage systems extend validation cycles beyond platform launch targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Low Emission Vehicle Market |
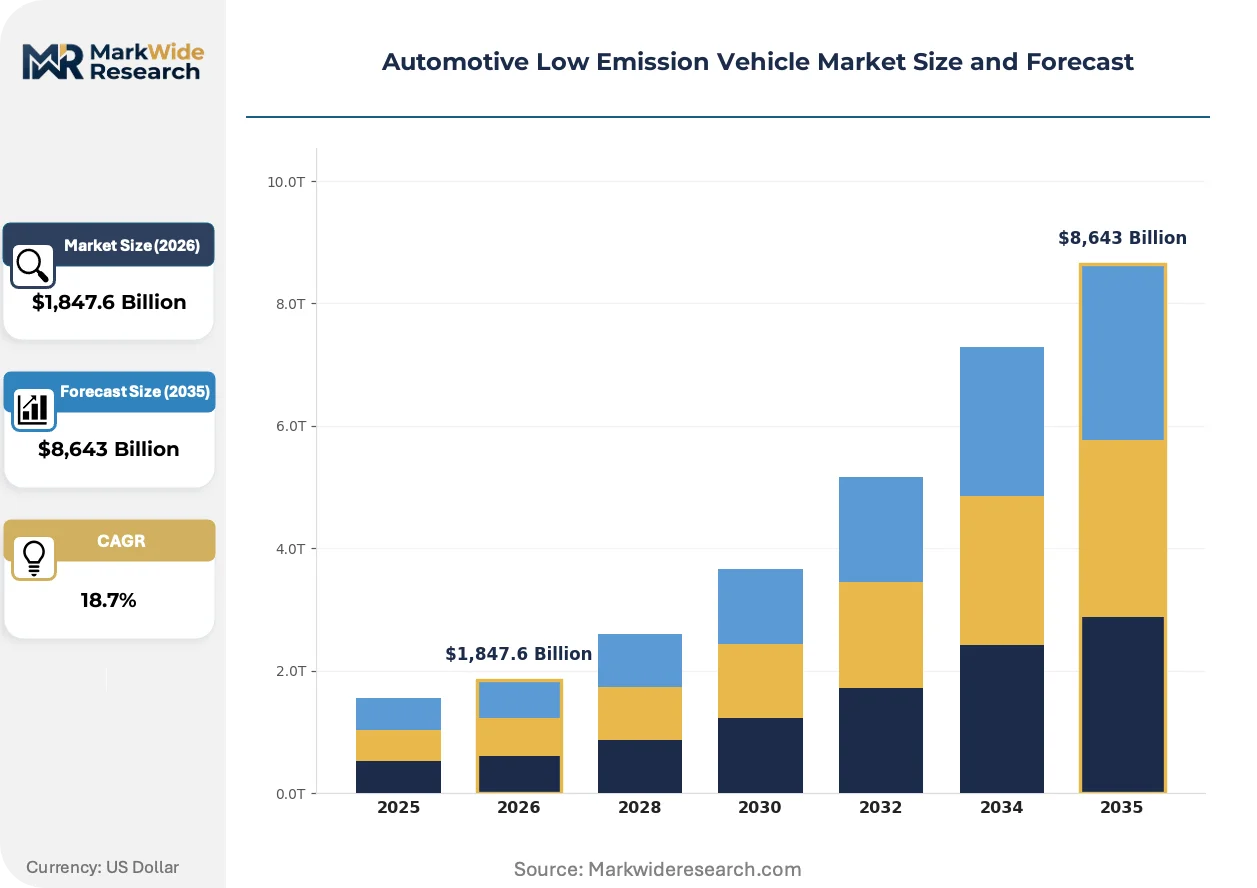
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $8,643 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Hybrid Electric Vehicle Drive System: Front-Wheel Drive, All-Wheel Drive, Rear-Wheel Drive, Dual-Motor Battery Technology: Lithium-Ion, Solid State, Nickel-Metal Hydride, Lead Acid Charging Infrastructure: Level 1 Charger, Level 2 Charger, DC Fast Charger, Wireless Charging |
| Companies Covered | Toyota Motor Corporation, Tesla Inc, Volkswagen AG, Hyundai Motor Company, General Motors Company, Nissan Motor Co., Ltd., Honda Motor Co., Ltd., BMW AG, BYD Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Low Emission Vehicle Market Emerging Trajectories
Battery pack architecture is modularizing around cell-to-pack and cell-to-chassis designs that eliminate module housings and structural redundancy. This shift compresses manufacturing steps while altering crash safety engineering requirements.
Cell-to-chassis integration is modularizing vehicle platform development by embedding energy storage directly into floor structures. Premium and mass-market OEMs in South Korea and China are adopting this approach to reduce part count and assembly labor. The structural consequence is compressing tier-one supplier roles in battery enclosure manufacturing.
The EU Green Deal's 2035 internal combustion engine phase-out mandate is forcing powertrain investment reallocation across European OEM engineering centers. This policy eliminates hybrid transitional strategies for volume manufacturers and redirects capital toward dedicated battery electric architectures. Passenger car segments in Germany, France, and Italy are responding with accelerated platform consolidation and shared component sourcing.
Fleet procurement is consolidating around total cost of ownership metrics rather than sticker price comparisons, with energy and maintenance cost differentials driving contract structures. Commercial lessors and mobility service operators are displacing individual ownership in urban last-mile segments. This behavioral shift is most visible in Nordic markets and the Netherlands where taxation structures amplify operating cost advantages.
Automotive Low Emission Vehicle Market Segmentation
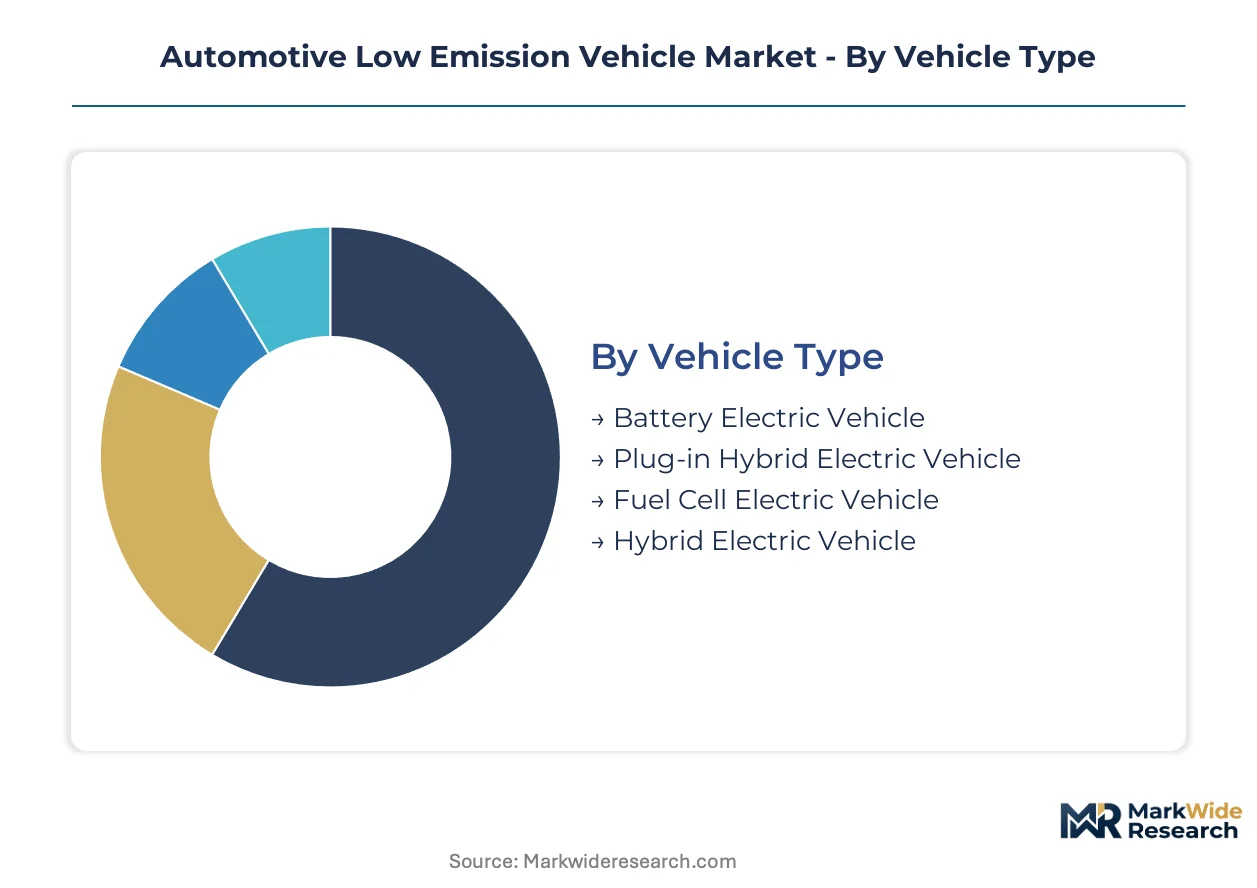
Segmentation in automotive low emission vehicles reveals how engineering choices cascade through manufacturing investment, regulatory compliance pathways, and consumer access barriers. Each dimension—vehicle architecture, drivetrain configuration, energy storage chemistry, and refueling interface—creates distinct competitive arenas with divergent margin structures and capital intensity requirements.
Vehicle Type:
Battery chemistry supply chains concentrate in East Asian cell manufacturing hubs, directly shaping which vehicle architectures achieve production scale first.
- Battery Electric Vehicle:Pure electric propulsion eliminates tailpipe emissions entirely through lithium-ion or solid-state energy storage integrated with permanent magnet synchronous motors. Demand clusters in China and the Netherlands where urban density and charging infrastructure subsidies compress range anxiety; EPA Tier 3 compliance deadlines in the United States accelerate fleet procurement away from internal combustion.
- Plug-in Hybrid Electric Vehicle:Dual powertrain architecture combines downsized internal combustion engines with grid-chargeable battery packs enabling 40-80 kilometer electric-only operation. European fleet operators in Germany and France favor this transitional technology where charging infrastructure gaps persist and Euro 7 standards demand emission reductions without full electrification commitment.
- Fuel Cell Electric Vehicle:Proton exchange membrane stacks convert hydrogen to electricity with water vapor as sole byproduct, requiring high-pressure storage tanks and dedicated refueling infrastructure.
- Hybrid Electric Vehicle:Non-plugable battery-electric assist systems capture regenerative braking energy to supplement internal combustion without grid dependency.
Battery Electric Vehicle absorbs the bulk of installed capacity; Plug-in Hybrid Electric Vehicle is expanding most quickly.
Drive System:
Cost tier differentiation separates mass-market front-wheel configurations from premium all-wheel and dual-motor architectures commanding manufacturing complexity premiums.
- Front-Wheel Drive:Single motor mounted transversely drives the front axle through a fixed-ratio reduction gearbox, minimizing component count and assembly labor. Volume manufacturers in South Korea and Spain prioritize this architecture for compact passenger cars where packaging efficiency and production cost control dominate platform economics.
- All-Wheel Drive:Dual or triple motor layouts distribute torque across both axles with electronic torque vectoring, requiring sophisticated power electronics and thermal management systems. Nordic markets and Alpine region consumers demand this configuration for winter traction performance, with Norwegian taxation structures amplifying operating cost advantages for electric all-wheel drive over internal combustion equivalents.
- Rear-Wheel Drive:Longitudinal motor placement enables balanced weight distribution favored in performance-oriented passenger cars and commercial delivery vans.
- Dual-Motor:Independently controlled front and rear power units deliver maximum traction and acceleration capability without mechanical differentials.
Front-Wheel Drive carries the highest production volumes; All-Wheel Drive climbs the fastest as premium segment electrification accelerates.
Battery Technology:
Application-specific energy density requirements and thermal stability demands fragment cathode chemistry selection across passenger, commercial, and industrial vehicle segments.
- Lithium-Ion:Nickel manganese cobalt and lithium iron phosphate cathode variants dominate current production, with cell-to-pack architectures reducing enclosure mass and assembly steps. China's MIIT new energy vehicle mandates enforce minimum battery electric and plug-in hybrid production quotas that sustain lithium-ion demand floors regardless of commodity price cycles.
- Solid State:Sulfide and oxide electrolyte configurations replace flammable liquid electrolytes with ceramic or glassy ionic conductors, promising energy density improvements exceeding 400 watt-hours per kilogram. Japanese and South Korean manufacturers anchor development timelines toward heavy-duty trucking and aviation applications where safety margins and gravimetric efficiency justify premium cell costs.
- Nickel-Metal Hydride:Mature chemistry retains cost advantages in mild hybrid systems with shallow discharge cycles and moderate energy throughput requirements.
- Lead Acid:Lowest-cost option restricted to auxiliary power and starter functions in hybrid architectures due to energy density limitations.
Lithium-Ion commands manufacturing scale leadership; Solid State gains share fastest as electrolyte processing yields improve.
Charging Infrastructure:
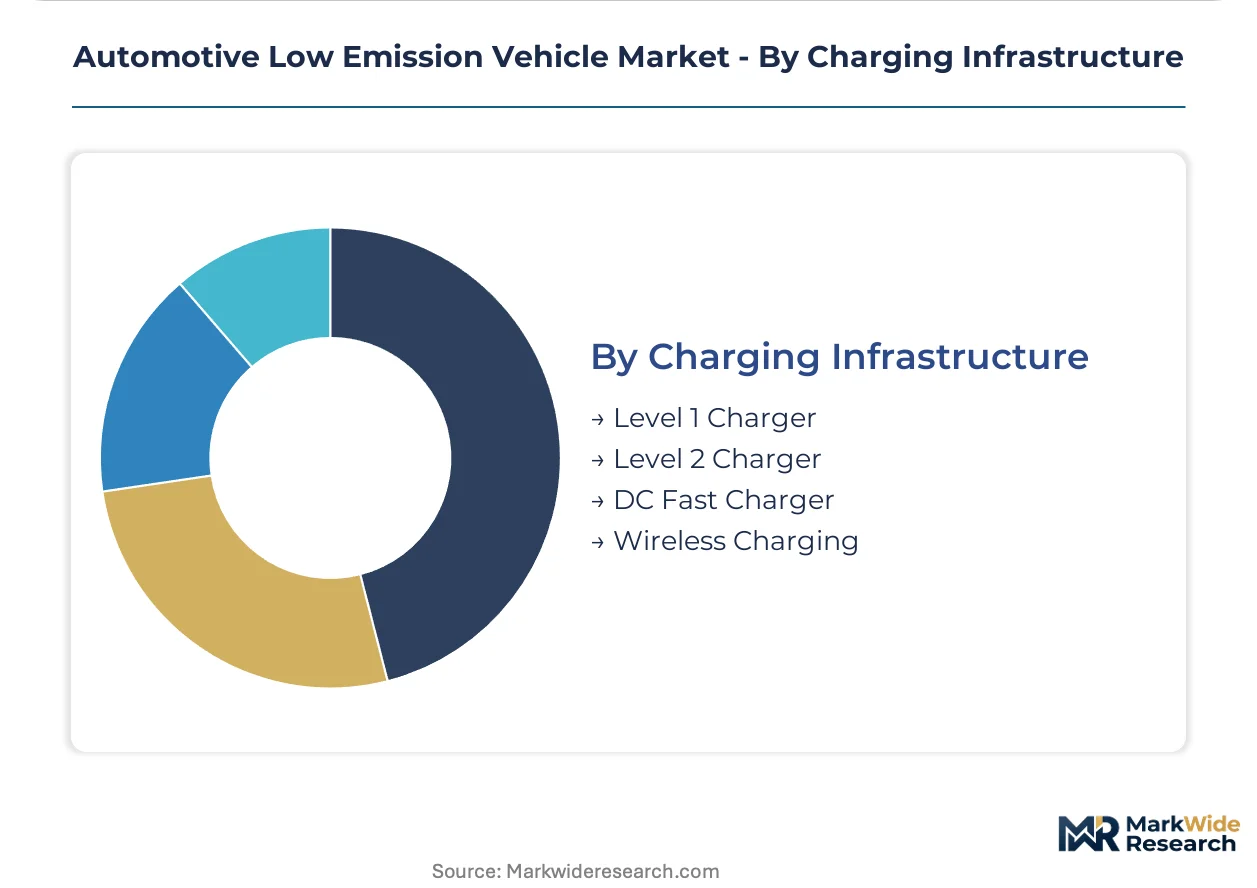
Customer type separation—residential versus commercial fleet versus public access—determines which charging modalities achieve deployment density and revenue sustainability.
- Level 1 Charger:Standard alternating current residential outlets delivering 1-2 kilowatts enable overnight charging without dedicated installation, though full battery replenishment requires 20-40 hours. Individual owners in apartment-dense Japanese and Italian urban centers rely on this modality where parking space ownership and electrical panel upgrades face regulatory and landlord coordination barriers.
- DC Fast Charger:Direct current systems bypass onboard conversion to deliver 50-350 kilowatts, enabling 10-80 percent state-of-charge cycles in 20-40 minutes. Commercial fleet operators across Germany, France, and the Netherlands negotiate long-term charging service contracts that lock in energy pricing and prioritize highway corridor access for logistics electrification.
- Level 2 Charger:240-volt alternating current installations delivering 7-19 kilowatts balance charging speed against electrical infrastructure requirements for workplace and multi-unit dwelling deployment.
- Wireless Charging:Inductive power transfer through pavement-embedded coils eliminates connector wear and enables autonomous vehicle operation without human intervention.
DC Fast Charger absorbs capital deployment concentration; Level 2 Charger expands most quickly as workplace and residential installation subsidies proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing capacity and domestic demand, while Germany, the United States, Japan, and the Netherlands anchor regional electrification trajectories through distinct regulatory and infrastructure pathways.
China
Domestic OEMs and battery manufacturers command vertical production chains from lithium refining through finished vehicle assembly. MIIT new energy vehicle mandates enforce minimum production quotas that sustain battery electric and plug-in hybrid volume floors. The Yangtze River Delta cluster around Shanghai and Ningbo hosts cathode active material processing facilities and cell manufacturing plants serving both domestic and export markets.
Germany
Fleet operators accelerate procurement of battery electric commercial vans and passenger cars as total cost of ownership advantages materialize against diesel equivalents. The EU Green Deal's 2035 internal combustion engine phase-out redirects engineering center investment toward dedicated electric architectures. Bavaria and Baden-Württemberg concentrate R&D facilities and pilot production lines for solid-state battery development.
United States
EPA Tier 3 tailpipe standards compress internal combustion engine viability windows for new passenger car platforms by 2030. The Inflation Reduction Act's domestic content requirements reshape battery supply chain sourcing decisions for assembly plants in Michigan, Tennessee, and South Carolina. California's Advanced Clean Cars II regulation mandates increasing zero-emission vehicle sales percentages that cascade through neighboring state adoptions.
Japan
Hybrid electric vehicle expertise retains market position while manufacturers navigate solid-state battery development timelines toward heavy-duty applications. METI funding programs support hydrogen fuel cell infrastructure deployment for commercial trucking corridors. The Nagoya industrial corridor maintains concentration in power electronics and motor manufacturing for both domestic OEMs and export supply.
Netherlands
Taxation structures amplify operating cost advantages for battery electric vehicles in fleet and individual ownership segments. Public DC fast charging networks now enable operation without home charging access, reducing consumer friction in Amsterdam and Rotterdam urban densities. The Eindhoven region hosts charging equipment manufacturing and smart grid integration testing facilities.
Automotive Low Emission Vehicle Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers commit capital to cell manufacturing and dedicated electric vehicle platforms. The market structures around a tiered hierarchy: integrated battery-vehicle producers, established automotive OEMs transitioning powertrain portfolios, and emerging specialists in charging infrastructure and power electronics. Three archetypes define positioning: vertical integrators controlling cell chemistry through assembly, platform licensors leveraging modular architectures across segments, and software-centric entrants prioritizing autonomous and connected vehicle stacks. Competitive intensity centers on manufacturing scale attainment and charging network access agreements.
Among established automotive OEMs, Toyota Motor Corporation and Volkswagen AG exemplify divergent strategic postures within the transition, while Tesla Inc occupies a position as the archetype for integrated battery and vehicle production. BYD Company Ltd anchors the vertically integrated model with control from raw material processing through finished vehicle distribution. These three represent distinct competitive templates that other manufacturers reference in platform investment and partnership decisions.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Tesla Inc |
| Volkswagen AG |
| Hyundai Motor Company |
| General Motors Company |
| Nissan Motor Co., Ltd. |
| Honda Motor Co., Ltd. |
| BMW AG |
| BYD Company Ltd |
| Others |
Supply Flow & Price Mechanics
Cell-to-pack architecture standardization is compressing manufacturing labor and enclosure material costs while redistributing bargaining power toward cathode active material suppliers in China and South Korea. This structural shift simultaneously lowers pack-level production expenses and concentrates margin capture upstream in lithium refining and precursor chemical processing.
Pricing Analysis
Warranty and service bundling separates fleet procurement contracts from individual retail transactions, with commercial lessors negotiating long-term battery performance guarantees and residual value protection. Three-tier pricing structure across premium, standard, and economy levels reflects energy density differentials and thermal management system sophistication. Pricing pressure stems from lithium carbonate spot market volatility and cathode material processing overcapacity in Chinese manufacturing hubs. Fleet operators exhibit highest price sensitivity due to total cost of ownership benchmarking against diesel equivalents, while premium passenger segments absorb technology premiums for solid-state battery pre-orders.
Supply Chain Analysis
UN ECE R100 and R10 certification requirements gate market access for high-voltage battery systems and power electronics, filtering component suppliers by validation timeline and testing facility access. Geographic concentration centers on China for cathode active material processing, South Korea for cell manufacturing equipment, and Japan for separator film and electrolyte formulations. Raw material dependencies include lithium spodumene concentrates, nickel sulfate, and cobalt hydroxide. Single-source vulnerability persists in rare earth permanent magnet supply for traction motors. Distribution runs through Tier 1 system integrators supplying OEM assembly plants with modular battery pack and inverter assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPA Tier 3 and Euro 7 tailpipe frameworks impose compliance costs that exceed smaller manufacturer engineering budgets, erecting regulatory moats around incumbent OEMs with dedicated electrification platforms and homologation expertise.
For Market Incumbents: Anticipate margin compression from Chinese battery-integrated manufacturers entering European and North American fleet segments through local assembly partnerships. Prioritize backward integration into cathode precursor chemical production to secure supply continuity and cost visibility. Accelerate solid-state battery pilot lines in German and Japanese R&D corridors to maintain technology differentiation as lithium-ion commoditization advances. For New Entrants and Emerging Players: Begin with commercial fleet electrification in Indian two-wheeler and three-wheeler last-mile delivery segments where PLI scheme subsidies reduce capital barriers and incumbent presence remains limited. Target battery-as-a-service subscription models that separate vehicle purchase from energy storage ownership, transferring residual value risk to financial intermediaries. Partner with charging infrastructure operators for exclusive highway corridor access agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by established automotive OEMs seeking power electronics engineering capabilities and solid-state battery patent portfolios. Long-term viability favors vertically integrated cell-to-vehicle producers with captive lithium supply and multi-regional assembly footprints. Monitor electrolyte processing yield improvements in sulfide and oxide solid-state chemistries as inflection indicators for heavy-duty application commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in cathode active material volumes from Chinese and South Korean processing facilities for platform scale. |
| Software-Defined Vehicle Investment | Enables over-the-air powertrain optimization and subscription revenue streams beyond hardware margins. |
| Charging Infrastructure Partnership | Secures DC fast charging network priority access for fleet operators across German and Dutch highway corridors. |
| Platform Standardization | Reduces part count and assembly complexity across multiple vehicle classes sharing cell-to-chassis architectures. |
| Geographic Manufacturing Footprint | Positions assembly capacity within IRA domestic content zones to satisfy credit eligibility requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, charging infrastructure operators, and fleet leasing managers. Bottom-up vehicle production and registration databases from IHS Markit and national motor vehicle agencies combined with top-down energy storage demand models from cathode material trade flows. EPA and MIIT regulatory impact assessments provided policy scenario inputs.
Production volume streams reconciled against battery cell manufacturing capacity announcements and lithium chemical supply contracts across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, battery chemistry, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of historical penetration rates against charging infrastructure density and total cost of ownership parity thresholds. Solid-state battery commercialization timelines and critical mineral price volatility scenarios informed sensitivity testing.
Underlying measurement precision varies by segment; battery electric vehicle volume forecasts carry tighter precision than fuel cell electric vehicle projections given infrastructure deployment uncertainty. Forecasts reflect assumptions around regulatory compliance deadlines, subsidy phase-out schedules, and cathode material processing yield improvements. A model refresh is warranted upon material change in lithium carbonate pricing or solid-state battery manufacturing yield thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
India CNG Vehicles Market