
 Global CNG and LPG Vehicle Market | 2026-2036
Global CNG and LPG Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global CNG and LPG Vehicle Market Foresight
Asset-light fleet leasing is narrowing the capital barrier for mid-sized logistics firms to deploy CNG and LPG vehicles at scale. Maruti Suzuki India Ltd anchors the passenger CNG segment through factory-fitted bi-fuel systems across its hatchback lineup. Volkswagen AG competes in European light commercial channels with dedicated CNG van platforms engineered to EURO 6 emissions thresholds. Tata Motors Limited dominates South Asian bus procurement through its in-house CNG powertrain foundry in Pune.
Global CNG and LPG vehicles are internal combustion engine platforms modified with high-pressure cylindrical tanks rated to 200-250 bar for CNG or welded steel vessels for LPG, delivering spark-ignited combustion with 15-25% lower CO2 emissions than equivalent gasoline engines. Their primary commercial purpose is to satisfy fleet operators and public transport authorities facing statutory emission ceilings without the infrastructure dependency or battery weight penalties of full electrification. Compressed Natural Gas occupies the largest volume share among fuel types because pipeline distribution networks in India, Iran, and Argentina already reach major population centers. Heavy Duty Trucks represent the fastest-expanding vehicle category as logistic companies face carbon-accounting pressure from retail shippers demanding Scope 3 reductions. Fleet Leasing Companies capture disproportionate margin pools by bundling fuel-card contracts with maintenance obligations across multi-year operating leases.
The US EPA administers greenhouse gas standards for medium and heavy-duty vehicles that effectively exclude uncertified alternative-fuel conversions from interstate commerce. India's BIS mandates IS 15508 certification for CNG cylinder integrity, while the EU Green Deal's F-Gas Regulation pressures member states to accelerate methane infrastructure as a bridge fuel. Stakeholders must monitor how carbon-border adjustment mechanisms treat CNG-derived CO2 intensity relative to renewable biogas certificates.
Market Dynamics
Fleet leasing structures are compressing capital barriers for mid-sized logistics operators, while municipal clean-air mandates in São Paulo, Delhi, and Tehran accelerate bi-fuel procurement timelines. This dual pressure—financial access on one side, regulatory compliance on the other—defines current competitive positioning.
Growth Catalysts
- India's PLI scheme for automotive manufacturing:Domestic CNG powertrain capacity is expanding through production-linked incentives that subsidize component localization and assembly scale.
- Brazil's dense retail CNG station network:Petrobras infrastructure in São Paulo state enables fleet operators to refuel without range anxiety, anchoring South American demand concentration.
- EURO 6 emissions thresholds:Light commercial operators across European urban zones face statutory ceilings that bi-fuel platforms satisfy without battery weight penalties.
Market Restraints
- Cylinder certification complexity:India's BIS mandates IS 15508 integrity testing that extends homologation timelines and raises compliance costs for aftermarket conversions.
- Pipeline distribution gaps:Interior provinces in Argentina and Iran lack last-mile CNG infrastructure, forcing fleet operators to dual-fuel with gasoline and erode operating economics.
- Battery-electric substitution:Falling lithium-ion pack costs and expanding fast-charging corridors in Chinese and European megacities divert procurement budgets from bi-fuel alternatives.
Strategic Opportunities
- Biogas certificate arbitrage:The EU Green Deal's carbon-border adjustment mechanisms create margin pools for operators sourcing renewable methane with verifiable CO2 intensity discounts.
- Heavy-duty truck electrification gaps:Long-haul freight corridors between Brazilian agricultural hubs and coastal ports exceed battery range viability, preserving CNG economics for 500+ kilometer routes.
- Urban bus fleet mandates:Indian state transport corporations in Maharashtra and Gujarat are tendering exclusively CNG-powered city buses, locking in decade-long procurement pipelines.
Industry Challenges
- High-pressure vessel fabrication skills:Welding technicians qualified for 250-bar cylindrical tank production remain concentrated in Pune and São Paulo industrial clusters, creating geographic hiring bottlenecks.
- Dual-fuel engine mapping complexity:Spark timing calibration across varying methane compositions requires software competency that legacy diesel mechanics lack, slowing service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CNG and LPG Vehicle Market |
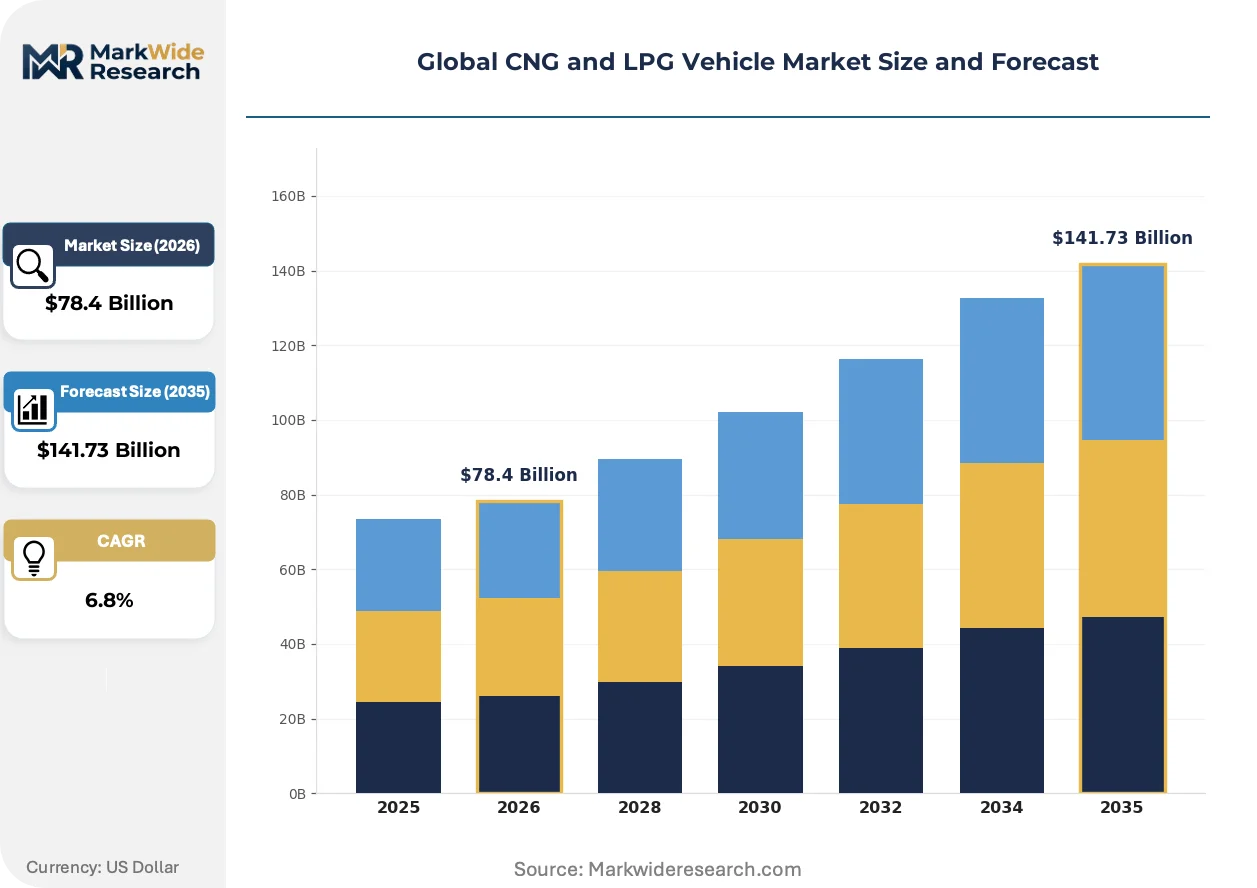
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Compressed Natural Gas, Liquefied Petroleum Gas, Biogas, Renewable CNG Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Duty Trucks, Buses End User: Fleet Operators, Public Transport Authorities, Logistic Companies, Government Bodies Distribution Channel: Direct Sales, Dealership Networks, Online Platforms, Fleet Leasing Companies |
| Companies Covered | Honda Motor Company, Volkswagen AG, Maruti Suzuki India Ltd, General Motors, IVECO, Hyundai Motor Company, Ford Motor Company, Suzuki Motor Corporation, Tata Motors Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CNG and LPG Vehicle Market Shifts & Advancements
Telematics integration is digitizing fleet management protocols, while regulatory frameworks in multiple geographies harden emissions accounting standards. These parallel developments are compressing the operational gap between alternative-fuel and electric platforms.
Onboard refueling equipment is digitizing cylinder pressure monitoring and fuel consumption logging. Logistics operators in Indian and Brazilian urban corridors are adopting these systems at accelerating pace. Real-time data streams are digitizing maintenance scheduling and warranty claim verification, reducing unplanned downtime for leased CNG truck fleets.
The EU F-Gas Regulation is pressuring member states to accelerate methane infrastructure as a bridge fuel toward full decarbonization. Industrial consequence includes mandatory leak detection protocols at compression stations and retail outlets. Light commercial van segments in Germany and Italy are responding with dedicated CNG platforms engineered to tighter certification standards than gasoline baselines.
Fuel-card bundling is displacing standalone vehicle procurement in mid-sized fleet operations. Leasing companies capture margin pools by integrating maintenance obligations and refueling contracts across multi-year terms. This pattern concentrates most visibly in São Paulo state, where Petrobras-branded station networks enable volume discount structures unavailable to fragmented owner-operators.
Global CNG and LPG Vehicle Market Segmentation
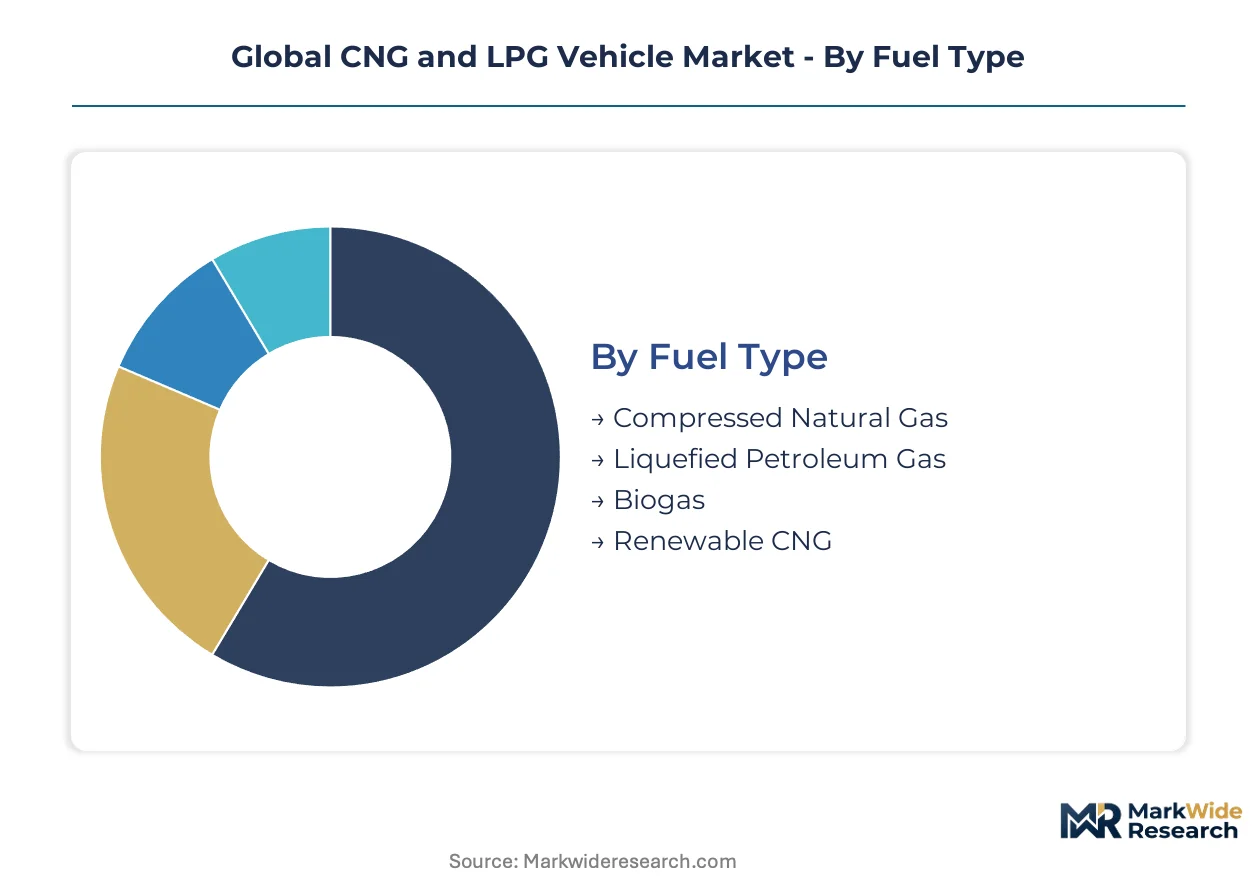
Segmentation in the CNG and LPG vehicle market reveals how fuel infrastructure availability, vehicle duty cycles, and procurement contracting structures determine where capital deploys. Each dimension carries distinct aftermarket service intensities and margin profiles that shape vendor strategies.
Fuel Type:
Aftermarket service intensity varies sharply across fuel chemistries, with cylinder recertification schedules and fuel system calibration demands creating divergent lifetime revenue streams for maintenance providers.
- Compressed Natural Gas:High-pressure 200-250 bar storage systems dominate fleet applications where pipeline distribution exists. Demand concentrates in Indian urban corridors and São Paulo state, where municipal mandates force conversion timelines and Petrobras station density eliminates range anxiety.
- Liquefied Petroleum Gas:Welded steel vessels operating at lower pressures serve markets lacking methane pipeline infrastructure. Adoption clusters in European light commercial segments where EURO 6 thresholds apply and bi-fuel retrofits extend existing vehicle lifecycles.
- Biogas:Renewable methane certificates command premium pricing in EU carbon-border accounting frameworks.
- Renewable CNG:Pipeline-injected biomethane qualifies for Scope 3 reduction claims by retail shippers.
Compressed Natural Gas holds the largest share; momentum sits with Renewable CNG.
Vehicle Type:
Cost tier stratification separates premium factory-fitted platforms from economy conversion kits, with warranty coverage and financing availability determining accessible market depth.
- Heavy Duty Trucks:Long-haul freight configurations exploit CNG economics on 500+ kilometer corridors where battery range proves inadequate. Procurement concentrates among Brazilian agricultural logistics operators and Indian interstate fleet operators facing carbon-accounting pressure from multinational retail clients.
- Buses:Urban transit authorities in Maharashtra and Gujarat states tender exclusively CNG-powered city bus fleets, locking in decade-long procurement pipelines with state transport corporations.
- Passenger Cars:Factory-fitted bi-fuel hatchbacks anchor Indian consumer demand through Maruti Suzuki's dealership networks.
- Light Commercial Vehicles:EURO 6-compliant van platforms serve German and Italian urban delivery zones.
Buses hold the largest share; Heavy Duty Trucks are climbing the fastest.
End User:
Volume concentration among large-scale procurers creates procurement leverage that compresses unit margins while securing long-term service contracts.
- Fleet Operators:Mid-sized logistics firms deploy asset-light leasing structures to bypass capital barriers, bundling fuel-card contracts with maintenance obligations across multi-year terms.
- Public Transport Authorities:State-level tendering in India and municipal mandates in São Paulo generate predictable order pipelines with stringent localization requirements.
- Logistic Companies:Scope 3 reduction targets from retail shippers drive bi-fuel procurement for long-haul corridors.
- Government Bodies:Defense and postal fleets in Iran and Argentina maintain dual-fuel capability where infrastructure gaps persist.
Fleet Operators hold the largest share; momentum sits with Public Transport Authorities.
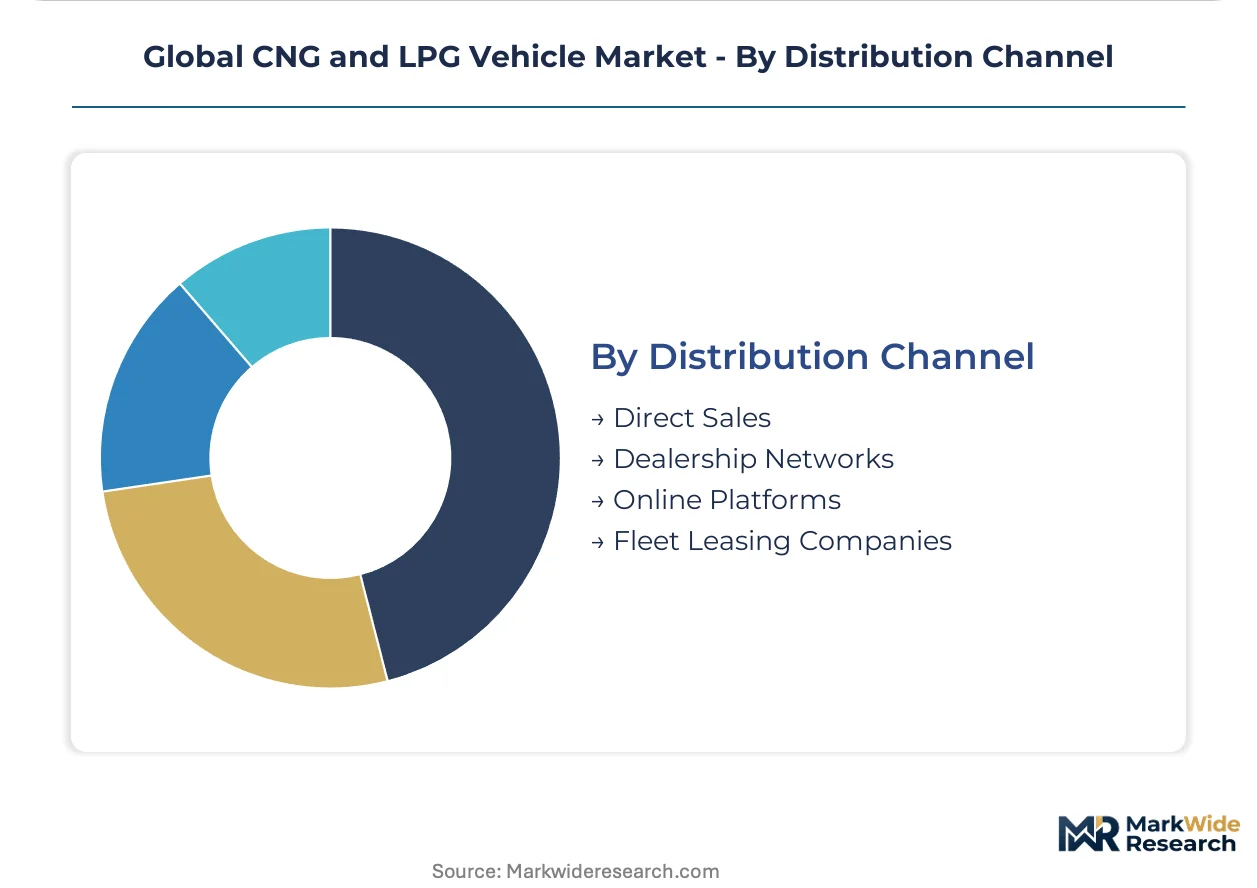
Distribution Channel:
Customer type segmentation distinguishes price-sensitive owner-operators from value-oriented fleet managers seeking integrated service bundles.
- Fleet Leasing Companies:Integrated providers capture disproportionate margin pools by combining vehicle supply, maintenance obligations, and fuel-card contracts. Concentration is highest in São Paulo state where Petrobras volume discounts reward consolidated procurement.
- Dealership Networks:Factory-authorized channels dominate passenger car distribution in India, with Maruti Suzuki's bi-fuel hatchback lineup moving through captive retail infrastructure.
- Direct Sales:Bus manufacturers like Tata Motors engage state transport corporations through tender-based procurement.
- Online Platforms:Digital marketplaces facilitate aftermarket conversion kit sales to fragmented owner-operators.
Fleet Leasing Companies hold the largest share; Dealership Networks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for CNG cylinder fabrication equipment tilts toward German and Italian machinery suppliers, while export flows of factory-fitted bi-fuel vehicles concentrate through Indian and Brazilian assembly plants serving regional fleet demand.
India
State transport corporations in Maharashtra and Gujarat tender exclusively CNG-powered city buses, locking in decade-long procurement pipelines. The BIS mandates IS 15508 certification for cylinder integrity, extending homologation timelines for aftermarket conversions. Pune hosts Tata Motors' in-house CNG powertrain foundry, supplying domestic bus manufacturers and export markets across South Asia.
Brazil
Petrobras maintains the densest retail CNG station network outside Asia across São Paulo state, eliminating range anxiety for agricultural logistics operators on 500+ kilometer corridors to coastal ports. ANVISA coordinates with environmental regulators on fuel quality standards. São Paulo's industrial belt concentrates welding technicians qualified for 250-bar cylindrical tank production, creating geographic hiring bottlenecks for expanding fabrication capacity.
Germany
Light commercial van segments respond to EURO 6 emissions thresholds with dedicated CNG platforms engineered to certification standards exceeding gasoline baselines. The EU F-Gas Regulation pressures federal and state governments to accelerate methane infrastructure as a bridge fuel. Industrial clusters in Bavaria and Baden-Württemberg house component suppliers for high-pressure fuel system integration.
United States
The EPA administers greenhouse gas standards for medium and heavy-duty vehicles that effectively exclude uncertified alternative-fuel conversions from interstate commerce, compressing aftermarket opportunity. California's Air Resources Board maintains supplemental zero-emission vehicle mandates that divert procurement toward battery-electric alternatives. Midwest fleet operators face infrastructure gaps that force dual-fuel capability with gasoline, eroding operating economics.
Iran
Pipeline distribution networks reach major population centers in Tehran and provincial capitals, anchoring CNG demand for passenger car conversions. The national petroleum ministry coordinates station deployment through state-owned distribution entities. Interior provinces lack last-mile CNG infrastructure, compelling government and postal fleets to maintain dual-fuel capability where compression station density falls below operational thresholds.
Global CNG and LPG Vehicle Market Competitive Landscape
On the supply side, the industry is tiered between integrated OEMs with captive powertrain foundries and regional conversion specialists serving aftermarket demand. Factory-fitted bi-fuel platforms command premium positioning through warranty coverage and financing availability, while economy conversion kits compete on upfront cost for price-sensitive owner-operators. Two strategic archetypes dominate: vertically integrated automotive conglomerates with multi-brand portfolios, and national champions focused on domestic fleet leasing integration. Capacity expansion and fuel-card bundling represent the dominant competitive moves, with leasing companies capturing margin pools by combining vehicle supply, maintenance obligations, and refueling contracts.
Among Asian automotive conglomerates, Maruti Suzuki India Ltd and Tata Motors Limited exemplify the national champion archetype, anchoring domestic procurement pipelines through state-level tendering relationships and dealership network density. Volkswagen AG occupies a position within the integrated OEM tier, representing European engineering compliance with EURO 6 thresholds across light commercial channels. These three companies illustrate how geographic origin and corporate structure correlate with divergent go-to-market strategies.
| Leading Market Players |
|---|
| Honda Motor Company |
| Volkswagen AG |
| Maruti Suzuki India Ltd |
| General Motors |
| IVECO |
| Hyundai Motor Company |
| Ford Motor Company |
| Suzuki Motor Corporation |
| Tata Motors Limited |
| Others |
Supply & Pricing Matrix
Undercapacity in Brazilian 250-bar cylinder fabrication is compressing supplier margins while amplifying pricing power for Pune-based foundries serving Indian OEMs. Fleet leasing companies exploit this geographic asymmetry by bundling maintenance contracts that internalize volatility, converting capital expenditure into predictable operating cost structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium factory-fitted platforms, certified aftermarket conversions, and economy retrofit kits. Price differentiation rests on IS 15508 certification grade and after-sales service bundling, with uncertified conversions facing exclusion from interstate commerce under EPA greenhouse gas standards. Cost compression in economy tiers is intensifying because BIS homologation timelines extend delivery schedules. Owner-operators in interior provinces exhibit highest price sensitivity, while fleet operators prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Contract manufacturing concentrates with Tata Motors' captive Pune foundry, Maruti Suzuki's integrated bi-fuel assembly lines, and Volkswagen AG's EURO 6-certified van platforms. Geographic supply concentration centers on India, Brazil, and Germany for powertrain components, with high-pressure vessel steel sourcing from German and Italian machinery suppliers. Raw material dependencies include specialized welding alloys, methane-compatible sealing compounds, and carbon-fiber composite wraps. Single-source vulnerability persists for 250-bar cylinder fabrication equipment. Distribution runs through fleet leasing companies capturing margin pools via fuel-card bundling, dealership networks for passenger vehicles, and tender-based direct sales for municipal bus procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel-card interoperability is emerging as the platform-economics inflection, with telematics integration creating network effects that lock fleet operators into consolidated leasing ecosystems.
For Market Incumbents: Harden cylinder certification moats by deepening IS 15508 and EURO 6 compliance investment ahead of carbon-border adjustment mechanism rollout. Secure welding technician pipelines in São Paulo and Pune industrial clusters to defend fabrication capacity against battery-electric substitution pressure. Vertical integration into biogas certificate sourcing captures renewable methane premium pools. For New Entrants and Emerging Players: Establish a beachhead in heavy-duty truck electrification gaps across Brazilian agricultural corridors exceeding battery range viability. Target interior Iranian provinces where dual-fuel capability commands operational premiums due to pipeline distribution gaps. Deploy onboard refueling equipment with real-time pressure monitoring as differentiated fleet management software. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet leasing companies integrating maintenance obligations with fuel-card contracts across multi-year terms. Long-term viability hinges on biogas certificate arbitrage within EU carbon-accounting frameworks. Acquisition targets should display captive powertrain foundry capacity and state-level tendering relationships. Monitor lithium-ion pack cost trajectories in Chinese and European megacities as battery-electric inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cylinder Certification Investment | IS 15508 compliance secures homologation timelines for Indian aftermarket conversions. |
| Biogas Supply Agreement | Renewable methane certificates qualify for EU carbon-border adjustment mechanism discounts. |
| Fleet Telematics Integration | Real-time pressure monitoring digitizes maintenance scheduling for leased truck operations. |
| Technician Training Pipeline | Qualified welding skills for 250-bar vessels remain concentrated in São Paulo and Pune clusters. |
| State Tendering Relationship | Maharashtra and Gujarat transport corporations lock decade-long CNG bus procurement pipelines. |
Research Methodology
The analysis maps CNG powertrain fabrication, LPG retrofit conversion, and biogas certificate trading sub-sectors, each validated through fleet operations managers, OEM platform engineers, aftermarket service technicians, and municipal procurement officers. Primary interview data triangulates against vehicle production databases, BIS certification registries, EU F-Gas Regulation filings, and Petrobras station network disclosures. Bottom-up fleet deployment estimates reconcile with top-down fuel consumption trends across Indian, Brazilian, and German regulatory clusters.
Assumptions held fixed include current EURO 6 and EPA greenhouse gas threshold stringency, while battery-electric range improvement and biogas injection rates were varied across sensitivity scenarios. The analytical framework models vehicle class, fuel chemistry, procurement contracting structure, and regional infrastructure density throughout the forecast period. CAGRs derive from deployment run-rates, station build-out pipelines, and carbon-accounting pressure from retail shipper Scope 3 targets.
Sensitivities concentrate around lithium-ion cost trajectories, methane infrastructure subsidy continuity, and carbon-border adjustment mechanism treatment of CNG-derived CO2 intensity. Quarterly review of battery-electric fast-charging corridor expansion, biogas certificate pricing, and municipal tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market