
 Flavor Modulators Market | 2026-2036
Flavor Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Modulators Market Foresight
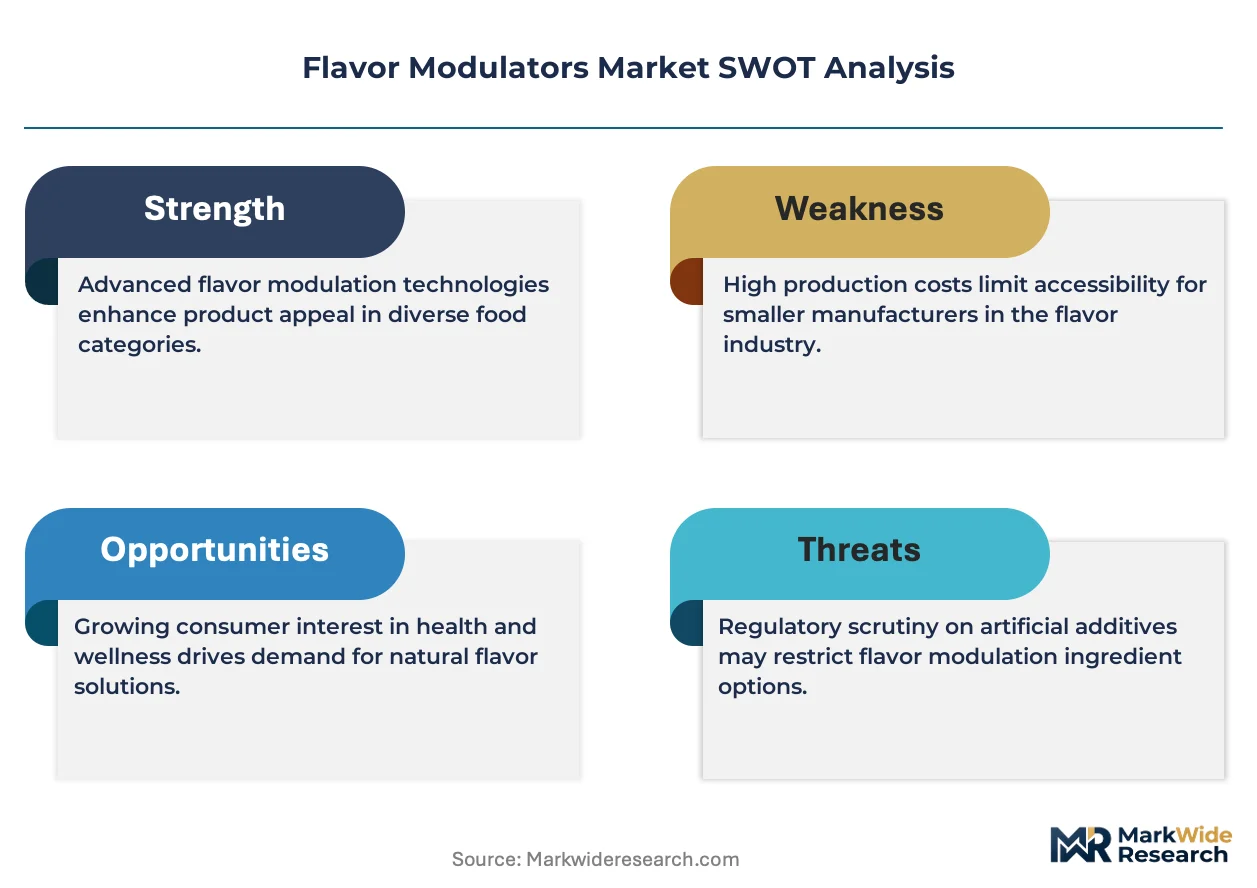
The flavor modulators category is restructuring around a sharp split between premium clean-label modulators and commodity taste-maskers. Givaudan SA leverages its integrated flavor science platform to dominate high-value sweetness enhancement for reduced-sugar beverages. Kerry Group plc anchors its position through specialized salt-reduction systems for meat alternatives. DSM-Firmenich AG competes across umami booster applications with fermentation-derived technologies.
Flavor modulators are functional ingredients that alter human taste perception through interaction with gustatory receptors, typically formulated as receptor agonists, antagonists, or allosteric modulators at concentrations below flavor threshold levels. Their primary commercial purpose is enabling significant reduction of sugar, sodium, or bitter compounds in finished foods without sacrificing sensory acceptability. Sweetness enhancers lead product type revenue pools due to beverage industry reformulation urgency, while bitterness suppressors represent the fastest-expanding segment as plant-protein applications multiply. Within application categories, meat alternatives command premium pricing for modulator systems that mask off-notes from pea and soy proteins.
The FDA governs flavor modulator safety through GRAS self-affirmation and food additive petition pathways, while the EFSA mandates novel food assessments for receptor-interacting ingredients under EU regulation. These frameworks shape demand by determining speed-to-market and labeling requirements for modulator suppliers. Stakeholders must monitor evolving taste-receptor toxicology standards and anticipate jurisdiction-specific clean-label definitions that will determine which modulator chemistries retain market access.
Market Dynamics
Beverage reformulation mandates are compressing development timelines for sweetness enhancers as CPG brands face binding sugar-reduction commitments. The regulatory divergence between FDA GRAS self-affirmation and EFSA novel food assessments is fragmenting approval pathways.
Growth Catalysts
- Sugar-reduction mandates:The FDA's updated Nutrition Facts labeling requirements pressure beverage manufacturers to reformulate legacy portfolios. Clean-label sweetness enhancers enable compliance without sensory trade-offs.
- Plant-protein expansion:Meat alternative producers in the United States require bitterness suppressors to mask off-notes from pea and soy protein isolates. This application segment commands premium pricing for modulator systems.
- Fermentation-derived technologies:Biomanufacturing platforms are reducing production costs for umami boosters. Food technologists are integrating these modulators into sodium-reduced savory applications.
Market Restraints
- Regulatory friction:EFSA's novel food assessment timelines extend market entry by 18-24 months compared to FDA pathways. European suppliers face competitive disadvantage in speed-to-market.
- Input cost volatility:Botanical extract feedstocks for clean-label modulators fluctuate with agricultural yields. Supplier concentration in specific growing regions amplifies price instability.
- Technical limitation:Receptor-specific modulators exhibit variable efficacy across demographic taste sensitivity profiles. Formulation standardization remains unresolved.
Strategic Opportunities
- Underpenetrated geographies:India's FSSAI is developing novel food frameworks for taste-modifying ingredients. Early entrants will shape regulatory precedent in this high-growth market.
- Regulatory tailwind:The EU Green Deal's sustainable food system targets incentivize sodium and sugar reduction. EFSA-approved modulators gain preferential access to reformulation contracts.
- Emerging applications:Functional beverage categories in Japan are adopting sweetness enhancers for diabetic-friendly positioning. METI's health claims framework supports this positioning.
Industry Challenges
- Taste-receptor toxicology expertise:The shortage of sensory scientists with gustatory receptor biology training constrains R&D throughput. Contract research organizations face capacity bottlenecks.
- GRAS dossier preparation:FDA self-affirmation requires extensive safety data packages. Smaller suppliers struggle with documentation costs and expert witness procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Modulators Market |
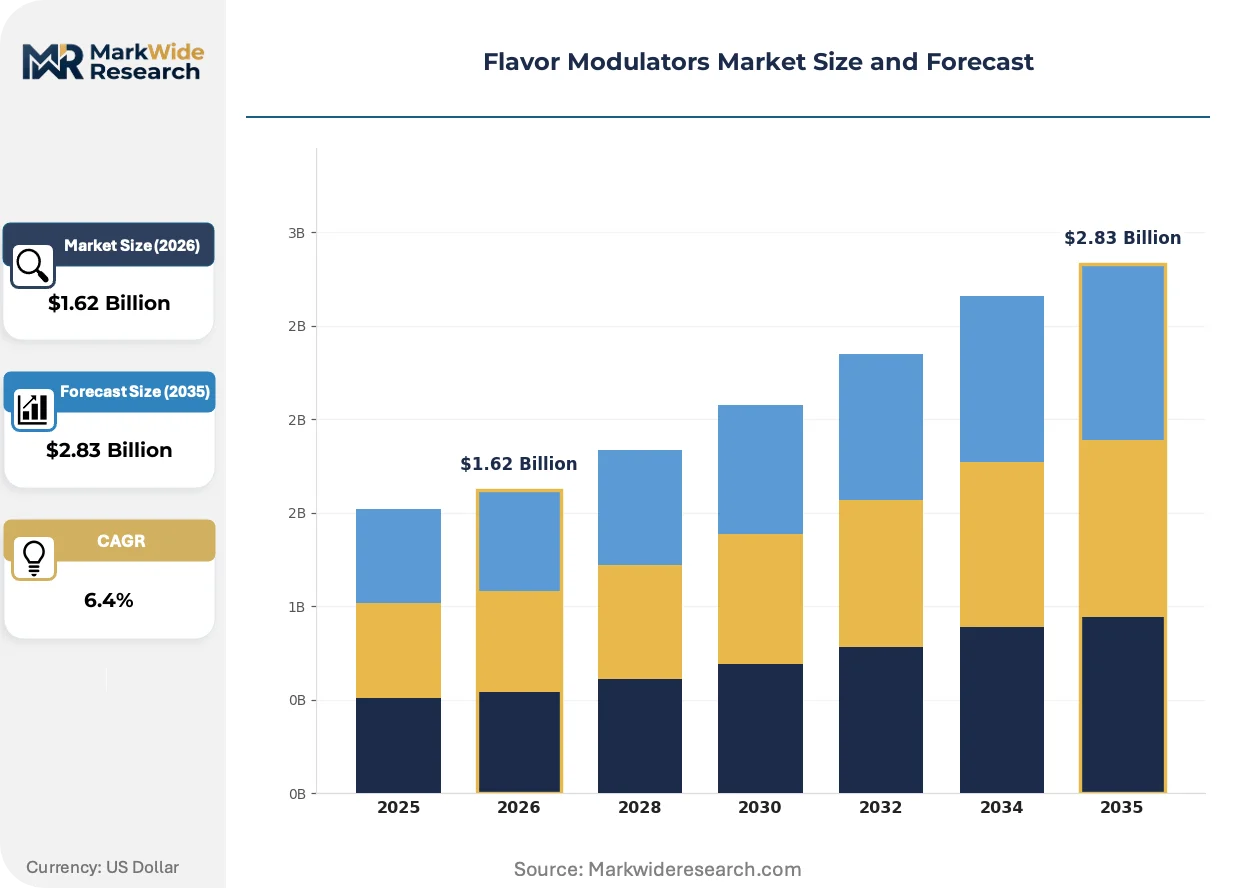
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.83 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetness Enhancers, Salt Reducers, Bitterness Suppressors, Sourness Maskers, Umami Boosters Application: Beverages, Confectionery, Meat Alternatives, Dairy Products, Bakery Items End User: Food Processing Companies, Ingredient Manufacturers, Flavor Houses, Consumer Packaged Goods Brands Form: Liquid, Powder, Granular, Emulsions, Spray-Dried |
| Companies Covered | Givaudan SA, International Flavors & Fragrances Inc., DSM-Firmenich AG, Kerry Group plc, Symrise AG, Ingredion Incorporated, Sensient Technologies Corporation, Tate & Lyle PLC, Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Modulators Market Shifts & Advancements
Biotechnology platforms are displacing traditional extraction methods for modulator production. Computational taste receptor modeling is compressing discovery timelines.
Allosteric modulation chemistry is absorbing investment from major flavor houses. Beverage formulators are adopting these compounds for sugar reduction targets below 50% replacement thresholds. The technology is absorbing market share from first-generation sweetness enhancers with pronounced temporal profile defects.
EFSA's 2023 guidance on taste-modifying substances as novel foods is tightening safety data requirements. Ingredient suppliers are restructuring dossier preparation workflows. European beverage manufacturers are accelerating pre-submission consultations to secure competitive positioning.
CPG procurement teams are consolidating supplier relationships around integrated flavor-modulator platforms. Direct ingredient sourcing from biotech specialists is displacing traditional flavor house intermediaries. This pattern is most visible in United States beverage manufacturing where vertical integration pressures are strongest.
Flavor Modulators Market Segmentation
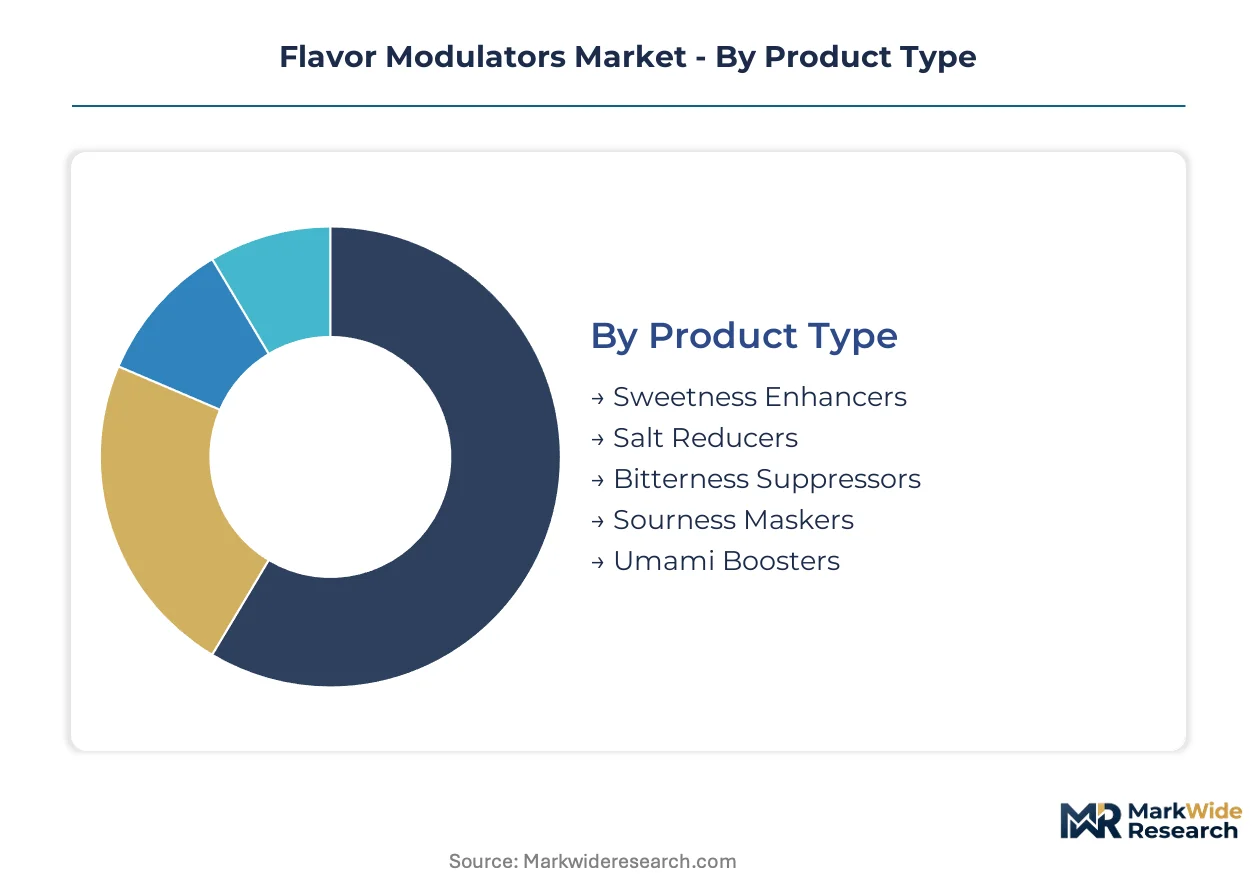
Flavor modulators demand heterogeneous formulation approaches across product categories, with receptor-targeting chemistries requiring precise matching to end-use matrices. Segmentation reveals how sweetness enhancement dominates beverage reformulation while bitterness suppression captures premium positioning in plant-protein applications.
Product Type:
Receptor interaction mechanisms differentiate modulator performance across gustatory pathways, determining efficacy thresholds and temporal profiles.
- Sweetness Enhancers:These compounds function as positive allosteric modulators at T1R2/T1R3 sweet receptors, amplifying sucrose perception at sub-threshold concentrations. Beverage manufacturers in the United States deploy these modulators to achieve sugar reductions exceeding 30% without sensory degradation. The FDA's GRAS pathway enables rapid formulation iteration for CPG brands facing labeling mandates.
- Bitterness Suppressors:Operating as TAS2R receptor antagonists, these ingredients block activation by alkaloids and isoflavones prevalent in plant proteins. Meat alternative producers command premium pricing for systems masking pea protein off-notes. This segment is expanding most quickly as fermentation-derived protein isolates multiply.
- Salt Reducers:Umami pathway amplifiers that enhance sodium perception without chloride content increase.
- Sourness Maskers:pH-neutralizing compounds that attenuate organic acid detection in functional beverages.
- Umami Boosters:Glutamate receptor agonists and nucleotide potentiators for savory sodium reduction.
Mature deployment sits with Sweetness Enhancers. Newer deployment is concentrated in Bitterness Suppressors.
Application:
Matrix compatibility requirements vary sharply across food categories, with water-activity and lipid-content dictating modulator stability and release kinetics.
- Beverages:High-water-activity matrices favor liquid sweetness enhancers with rapid receptor kinetics. Carbonated soft drink reformulation in the United States drives volume demand as brands adapt to FDA nutrition labeling. Clean-label positioning requires fermentation-derived or botanical-extract modulators with transparent supply chains.
- Meat Alternatives:Complex protein matrices with substantial lipid fractions demand multi-modal modulator systems addressing bitterness, astringency, and metallic off-notes simultaneously. Premium pricing reflects formulation complexity and the functional positioning of finished products.
- Confectionery:Low-water-activity environments require encapsulated modulators with delayed-release profiles.
- Dairy Products:Fat-protein emulsion matrices modulate receptor accessibility and temporal perception.
- Bakery Items:Thermal processing stability constrains modulator selection for oven-applied applications.
Volume concentration favors Beverages. Value capture concentrates in Meat Alternatives.
End User:
Procurement sophistication and technical integration capabilities segment buyer types across the value chain.
- Food Processing Companies:Direct manufacturers of finished goods with captive R&D capabilities. These buyers integrate modulators into proprietary formulation platforms, often sourcing through multi-year supply agreements with integrated flavor houses.
- Consumer Packaged Goods Brands:Marketing-led organizations outsourcing technical formulation. CPG procurement teams in the United States are consolidating supplier relationships around platforms combining modulators with complementary flavor systems.
- Ingredient Manufacturers:Suppliers of intermediate inputs requiring modulator compatibility with their own processing conditions.
- Flavor Houses:Traditional intermediaries facing displacement as biotech specialists establish direct CPG relationships.
Technical specification authority rests with Food Processing Companies. Procurement volume aggregates through Consumer Packaged Goods Brands.
Form:
Physical presentation determines handling economics, dispersion uniformity, and shelf-stability in diverse manufacturing environments.
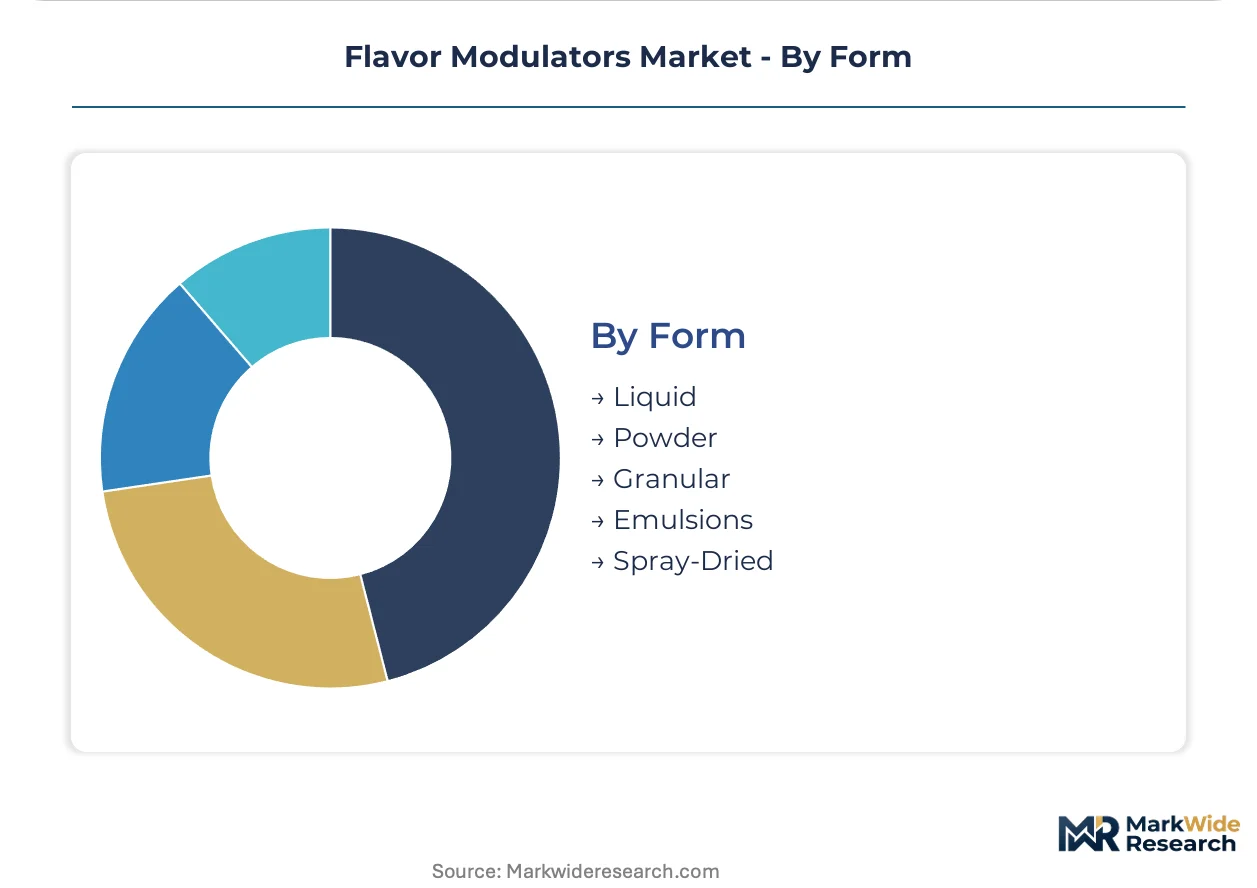
- Liquid:Pumpable concentrates with immediate dispersibility in aqueous systems. Beverage manufacturing lines favor liquid forms for continuous processing integration and reduced dust exposure.
- Powder:Free-flowing particulates with extended shelf stability and reduced transportation costs. Bakery and confectionery applications prefer powder forms for dry-blending compatibility.
- Granular:Agglomerated particles with reduced dusting and improved flow characteristics.
- Emulsions:Oil-in-water dispersions for lipid-rich matrices requiring homogeneous distribution.
- Spray-Dried:Encapsulated formats protecting volatile actives from oxidation and moisture.
Processing efficiency favors Liquid in high-throughput beverage plants. Stability requirements drive Spray-Dried adoption in ambient distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American flavor modulator procurement as CPG headquarters clusters concentrate technical specification authority. Beverage reformulation mandates from the FDA drive contract velocity across Midwest manufacturing corridors.
United States
Beverage manufacturers in Atlanta and St. Louis deploy sweetness enhancers to meet FDA Nutrition Facts labeling deadlines. The GRAS self-affirmation pathway enables rapid formulation iteration compared to European alternatives. Chicago-based procurement teams consolidate supplier relationships around integrated flavor-modulator platforms.
Germany
Meat alternative producers in Cologne and Hamburg require bitterness suppressors for pea-protein masking applications. EFSA novel food assessments extend approval timelines by 18-24 months versus FDA pathways. Bavarian ingredient suppliers navigate stricter safety data requirements under 2023 EFSA guidance.
Japan
Functional beverage brands in Tokyo and Osaka adopt sweetness enhancers for diabetic-friendly product positioning. METI's health claims framework supports reduced-sugar positioning in retail channels. Kansai-region manufacturing clusters integrate fermentation-derived umami boosters into sodium-reduced savory applications.
India
Plant-protein startups in Mumbai and Bangalore seek bitterness suppression systems for indigenous legume formulations. FSSAI novel food frameworks for taste-modifying ingredients remain under development. Early entrants shape regulatory precedent in this high-growth formulation market.
Brazil
Sugar-reduction initiatives in São Paulo beverage manufacturing drive sweetness enhancer procurement from international suppliers. ANVISA regulatory alignment with FDA pathways accelerates ingredient approval compared to European timelines. Southeast industrial corridors concentrate reformulation activity for export-oriented CPG brands.
Flavor Modulators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and receptor-biology capabilities. The vendor base stratifies between integrated flavor science platforms and specialized biotech suppliers. Three archetypes dominate: multinational flavor houses with captive R&D, fermentation-technology specialists, and botanical-extraction suppliers. Competitive moves concentrate on M&A for receptor-biology assets and direct CPG relationships displacing traditional intermediaries.
Within the integrated flavor house tier, Givaudan SA and DSM-Firmenich AG occupy positions spanning sweetness enhancement and umami booster applications. Kerry Group plc represents the specialized systems approach, anchoring salt-reduction capabilities for protein alternative matrices. These three exemplify how scale and regulatory dossier expertise determine access to multi-year supply agreements with North American and European CPG procurement teams.
| Leading Market Players |
|---|
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich AG |
| Kerry Group plc |
| Symrise AG |
| Ingredion Incorporated |
| Sensient Technologies Corporation |
| Tate & Lyle PLC |
| Corbion N.V. |
| Others |
Supply & Pricing Matrix
A sharp bifurcation between premium fermentation-derived modulators and commodity botanical extracts manifests in both pricing power and sourcing configurations. GRAS-certified sweetness enhancers command substantial premiums through integrated flavor house platforms, while bulk botanical suppliers face margin compression from agricultural yield volatility and buyer consolidation around direct biotech relationships.
Pricing Analysis
Value-based pricing anchored to sugar-reduction efficacy outcomes dominates the premium tier. Three-tier pricing structure across premium fermentation-derived, standard botanical-extract, and economy synthetic modulator levels reflects certification grade and receptor specificity. Cost compression in commodity botanical tiers is intensifying because CPG procurement teams are consolidating supplier relationships. Food processing companies with captive R&D capabilities exhibit lowest price sensitivity, while ingredient manufacturers sourcing for resale show highest sensitivity to per-kilogram fluctuations.
Supply Chain Analysis
Dual-sourcing requirements from major beverage manufacturers mandate multi-supplier qualification for critical sweetness enhancers. Supply concentration centers on the United States for GRAS-affirmed fermentation platforms, India for botanical extraction feedstocks, and Germany for precision biomanufacturing equipment. Raw material dependencies include corn-derived dextrose for fermentation media, specialized yeast strains, and pea protein isolates for bitterness masking applications. Tariff exposure on botanical imports from specific growing regions creates supply chain risk. Distribution runs through integrated flavor house technical service teams rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over fermentation-derived production platforms determines margin capture. Players are pursuing backward integration into biomanufacturing capacity to escape commodity pricing traps.
For Market Incumbents: Anchor market position through captive production of allosteric modulators with superior temporal profiles. Defensive consolidation around direct CPG relationships displaces traditional flavor house intermediaries. Capacity addition in United States Midwest manufacturing corridors secures proximity to beverage reformulation demand. Investment in GRAS dossier expertise creates regulatory moats against emerging biotech specialists.
For New Entrants and Emerging Players: Regional plant-protein startups in India represent the most penetrable buyer archetype for bitterness suppression systems. White-space concentration in FSSAI framework development allows early entrants to shape regulatory precedent. Direct technical service models bypassing flavor house intermediaries offer viable go-to-market positioning for fermentation-technology specialists.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-technology specialists given EFSA novel food approval momentum as a catalyst. Long-term viability over the next decade hinges on regulatory dossier depth and receptor-biology IP portfolios. Acquisition targets should demonstrate integrated production platforms with GRAS self-affirmation capabilities. Deviation in FDA taste-receptor toxicology standards would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive biomanufacturing of allosteric modulators reduces dependency on botanical extract volatility. |
| GRAS Self-Affirmation Investment | FDA pathway acceleration enables rapid formulation iteration for CPG brands facing labeling mandates. |
| Direct CPG Relationship Development | Technical service integration with beverage manufacturers displaces traditional flavor house intermediaries. |
| EFSA Novel Food Pre-Submission | Early engagement with European regulators secures competitive positioning in sodium-reduction applications. |
| Receptor-Biology Asset Acquisition | Gustatory receptor modeling capabilities compress discovery timelines for next-generation modulators. |
Research Methodology
Multi-period observation of FDA GRAS affirmation timelines and EFSA novel food assessment patterns anchored the trend analysis, supplemented by interviews with flavor house R&D directors, CPG procurement managers, fermentation platform engineers, and regulatory affairs specialists at ingredient suppliers. Secondary validation drew from FDA GRAS notices, EFSA scientific opinions on taste-modifying substances, FSSAI draft frameworks, and customs trade data on botanical extract imports. Bottom-up segment sizing triangulated against top-down market construction.
Input-output matrices modeled demand across product type, application matrix, end-user procurement sophistication, and physical form dimensions over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included beverage reformulation commitment tracking and plant-protein capacity buildout announcements.
Revisions become necessary when FDA taste-receptor toxicology standards shift or EFSA novel food assessment timelines extend materially. Forecasts reflect assumptions on regulatory pathway efficiency and receptor-specific modulator efficacy stability. Deviation in clean-label definition evolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
North America Flavors and Fragrances Market