
 Royal Jelly Extract Market | 2026-2036
Royal Jelly Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Royal Jelly Extract Market Insights
Buyer concentration among nutraceutical distributors is restructuring procurement dynamics across the royal jelly extract value chain. Y.S. Organic Bee Farms leverages its vertically controlled apiary network to secure consistent raw material grades. NOW Foods competes through broad retail shelf presence and standardized potency labeling. Jiangshan Bee Enterprise anchors Asia-Pacific supply with integrated extraction and freeze-drying capabilities.
Royal jelly extract is a secretion from the hypopharyngeal glands of worker honeybees, containing 10-hydroxy-2-decenoic acid, proteins, and B-vitamins, typically harvested at 48-72 hours post-stimulation and preserved via lyophilization to maintain bioactive integrity; its primary commercial purpose centers on functional ingredient applications where immunomodulatory and dermatological properties command formulation premiums. Liquid formulations lead current volume owing to lower processing overhead and flexible dosing, while capsules capture expanding margin pools as unit-dose convenience aligns with pharmacy and online channel growth. Nutraceutical end-use outpaces cosmetics in velocity, though pharmaceutical-grade certifications command the highest price realization per kilogram.
EFSA novel food assessments govern European market entry for imported royal jelly concentrates, while China's NMPA and SAMR jointly oversee health food registration and GB standard compliance for domestic and export-bound production. The U.S. FDA exercises dietary supplement jurisdiction through DSHEA enforcement, with FTC monitoring structure-function claims across e-commerce channels. Stakeholders must monitor evolving maximum residue limits for antibiotics and pesticides in beekeeping operations, as regulatory tightening in major consuming jurisdictions threatens supply continuity for non-compliant producers.
Market Dynamics
EFSA novel food authorization requirements are restructuring European import economics for royal jelly extract, forcing non-EU suppliers to absorb compliance costs or exit the market entirely while domestic Chinese consumption absorbs surplus volumes redirected from blocked channels.
Growth Catalysts
- Immunomodulatory bioactives:10-hydroxy-2-decenoic acid validation in peer-reviewed pharmacology journals is electrifying nutraceutical formulator procurement. Supplement brands now specify minimum potency thresholds in supply contracts.
- China's health food registration pathway:NMPA and SAMR streamlined GB standard compliance for royal jelly-derived health foods, accelerating domestic brand launches and export certification reciprocity.
- Lyophilization cost compression:Industrial freeze-drying equipment manufacturers in Shandong Province have reduced capital recovery periods for extraction facilities, expanding viable processor economics.
Market Restraints
- Apis mellifera colony volatility:Varroa mite infestations and pesticide exposure in commercial beekeeping operations constrain raw royal jelly yield consistency across major producing regions.
- EFSA novel food assessment timelines:Eighteen-to-twenty-four-month authorization durations for imported concentrates create working capital strain for Asian suppliers targeting European pharmaceutical and nutraceutical buyers.
- Plant-based adaptogen substitution:Ashwagandha and reishi mushroom extracts compete for identical shelf space in immunity-positioned supplements, pressuring price realization for royal jelly formulations.
Strategic Opportunities
- Dermatological cosmeceutical channels:Korean beauty retailers and medical spa networks are expanding topical royal jelly SKUs, creating premium positioning outside commoditized supplement aisles.
- ISO 22000 and HACCP convergence:Dual certification alignment between Chinese GB standards and international food safety frameworks enables single-audit market access across multiple jurisdictions.
- Direct-to-practitioner distribution:Functional medicine clinics and integrative health networks bypass traditional retail markup structures, capturing margin pools previously allocated to pharmacy and mass-market channels.
Industry Challenges
- Apis genetics specialization:Shortage of queen bee breeders capable of selecting high-yield royal jelly genetic lines limits processor capacity expansion regardless of capital availability.
- Antibiotic residue testing protocols:Evolving maximum residue limits in EU, US, and Chinese jurisdictions require continuous analytical method upgrades at extraction facilities, compressing operating margins for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Royal Jelly Extract Market |
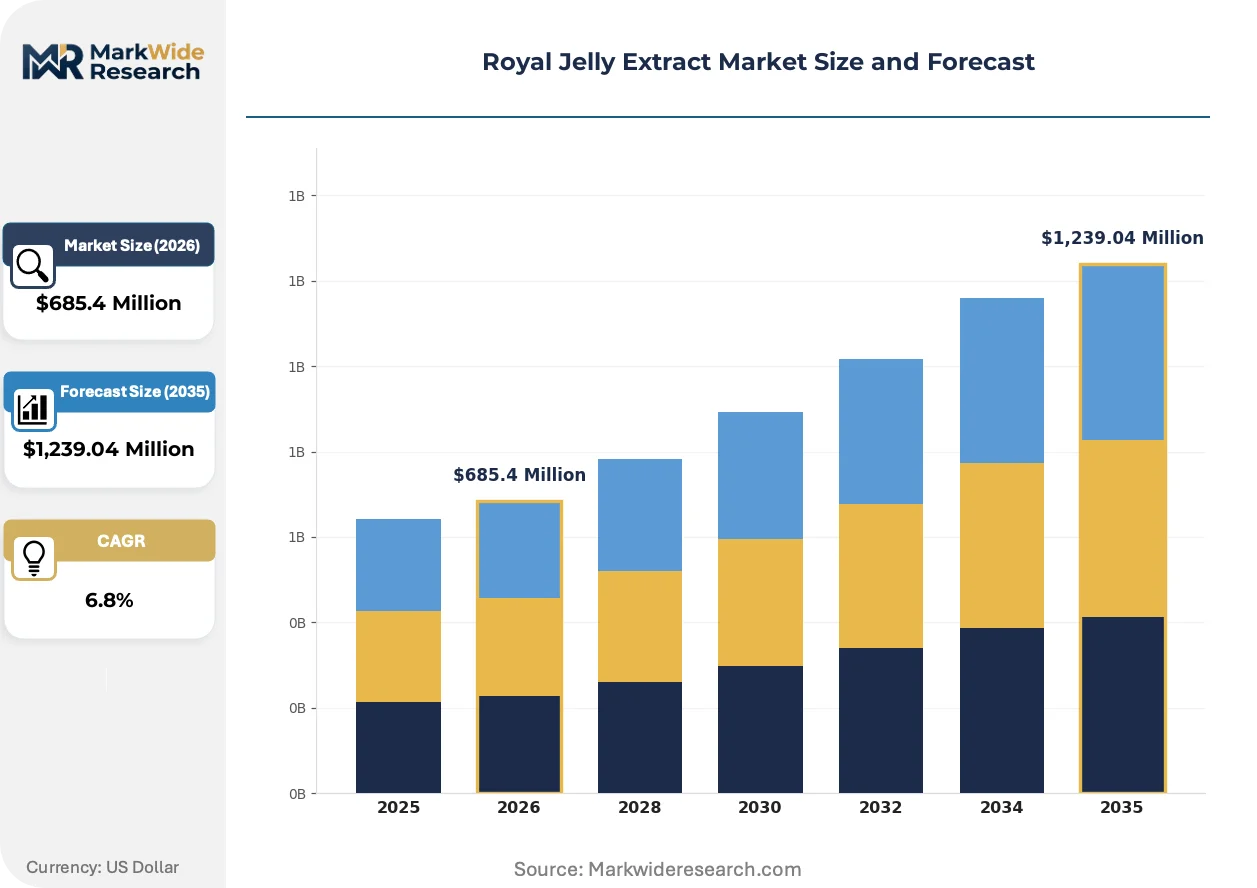
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Capsules, Creams End Use: Cosmetics, Pharmaceuticals, Nutraceuticals, Food & Beverages Packaging Type: Bottles, Jars, Sachets, Blisters Sales Channel: Online, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Y.S. Organic Bee Farms, NOW Foods, Durham's Bee Farm, Swanson Health Products, Jiangshan Bee Enterprise, Solgar Inc., Puritan’s Pride, Nu-Health Products, Source Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Royal Jelly Extract Market Trends and Innovations
Bioprocessing advances and regulatory harmonization pressures are compressing traditional extraction economics while opening formulation frontiers in adjacent therapeutic categories. Three developments are restructuring competitive positioning.
Subcritical water extraction technology is electrifying bioactive recovery rates from fresh royal jelly while eliminating organic solvent residues that complicate pharmaceutical-grade certification. German and Japanese extraction equipment manufacturers are retrofitting existing lyophilization facilities with modular subcritical units, enabling processors to serve both nutraceutical and API contract manufacturing markets from identical feedstock inputs. The technology is electrifying margin structures by collapsing the traditional separation between food-grade and pharmaceutical-grade production lines.
REACH registration requirements for novel bee-derived substances are extending compliance timelines for European market entry, particularly for hydrolyzed royal jelly proteins targeting cosmetic applications. ECHA substance evaluation workflows now encompass endocrine disruption screening that was previously absent from food-contact assessments, forcing reformulators to generate additional toxicology data packages. Cosmetic ingredient houses with existing REACH portfolios for honey-derived materials are leveraging read-across arguments to accelerate royal jelly analog registrations.
Subscription-based supplement replenishment models are displacing pharmacy and health food store purchasing for core royal jelly consumers. Direct-to-consumer platforms capture recurring revenue streams while accumulating longitudinal efficacy data that supports structure-function claim substantiation for FTC compliance. This channel migration is most visible in North American and Australian markets where postal infrastructure supports cold-chain delivery of liquid formulations previously restricted to retail refrigeration.
Royal Jelly Extract Market Segmentation
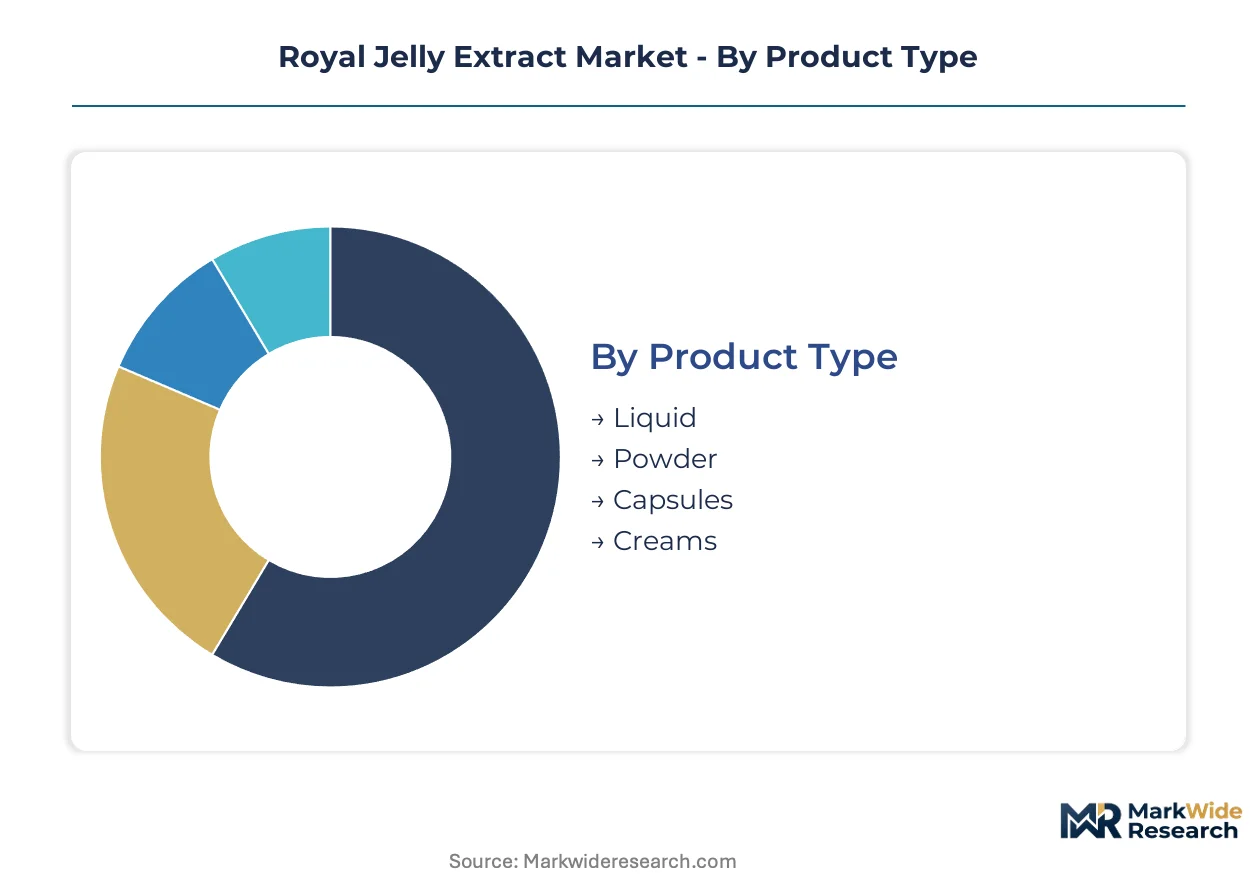
Royal jelly extract segmentation reflects divergent processing economics and channel requirements across pharmaceutical, nutraceutical, and cosmetic applications. Formulators select product formats based on bioactive stability needs, dosage precision, and regulatory compliance burdens specific to each end-use category.
Product Type:
Liquid formulations dominate volume throughput while powder and capsule formats capture formulation premiums in regulated channels.
- Liquid:Fresh or reconstituted aqueous suspensions retain full enzymatic activity and 10-hydroxy-2-decenoic acid concentration without thermal degradation. Bulk procurement concentrates in Chinese TCM manufacturers and European nutraceutical blenders seeking flexible dosing integration. Cold-chain logistics constrain distribution reach but preserve bioactive integrity for pharmaceutical-grade applications.
- Powder:Lyophilized particulate forms enable ambient storage and precise unit dosing for tablet compression and encapsulation. Demand clusters in North American supplement contract manufacturers requiring standardized potency for DSHEA-compliant labeling. Shandong Province freeze-drying capacity expansion has compressed per-kilogram processing costs.
- Capsules:Gelatin or vegetable-derived shells deliver pre-measured royal jelly doses for pharmacy and direct-to-consumer channels. Korean and Japanese health food retailers specify enteric-coated variants to protect gastric acid-labile proteins.
- Creams:Emulsion-based topical delivery systems incorporate royal jelly for dermatological positioning in cosmeceutical and medical spa networks.
Mature deployment sits with liquid extracts in traditional medicine and bulk ingredient supply. Newer deployment is concentrated in capsules and creams targeting unit-dose convenience and premium topical positioning.
End Use:
Application segmentation tracks divergent regulatory pathways and margin structures across health-positioned and beauty-positioned channels.
- Nutraceuticals:Dietary supplement formulations leverage immunomodulatory and adaptogenic claims in immunity and anti-aging product lines. NMPA health food registration in China and FDA DSHEA compliance in the United States impose distinct substantiation requirements. Subscription-based replenishment models are displacing pharmacy purchasing in North American markets.
- Cosmetics:Topical applications exploit humectant and collagen-stimulating properties in Korean beauty retail and European medical spa channels. REACH registration for hydrolyzed royal jelly proteins extends compliance timelines for European cosmetic ingredient houses.
- Pharmaceuticals:API-grade extracts require GMP certification and antibiotic residue testing for clinical trial supply and compounded formulations. EFSA novel food assessments govern European pharmaceutical excipient applications.
- Food & Beverages:Functional food fortification incorporates royal jelly into honey blends, energy shots, and fermented beverages in Japanese and Chinese markets.
Volume concentration remains in nutraceutical channels. Steepest expansion trajectory is visible in cosmetics as Korean beauty retailers expand royal jelly SKU counts.
Packaging Type:
Primary packaging selection balances shelf-life extension, portability, and retail channel compliance requirements.
- Bottles:Amber glass or opaque polymer containers protect photosensitive bioactives in liquid royal jelly retail formats. German and Swiss pharmacy chains specify child-resistant closures for adult supplement positioning.
- Jars:Wide-mouth containers accommodate cream and paste consistencies for cosmetic and TCM-apothecary distribution. Japanese department store cosmetics halls favor premium glass jar presentation.
- Sachets:Single-serve foil laminates enable sampling programs and travel-format distribution in Asian convenience retail. Chinese e-commerce platforms utilize sachet formats for subscription box inclusion.
- Blisters:Thermoformed PVC or aluminum cavities protect capsule integrity from moisture and oxidation in pharmacy and clinical trial supply.
Established infrastructure supports bottle and jar formats. Sachet and blister deployment is accelerating in e-commerce and pharmacy channels respectively.
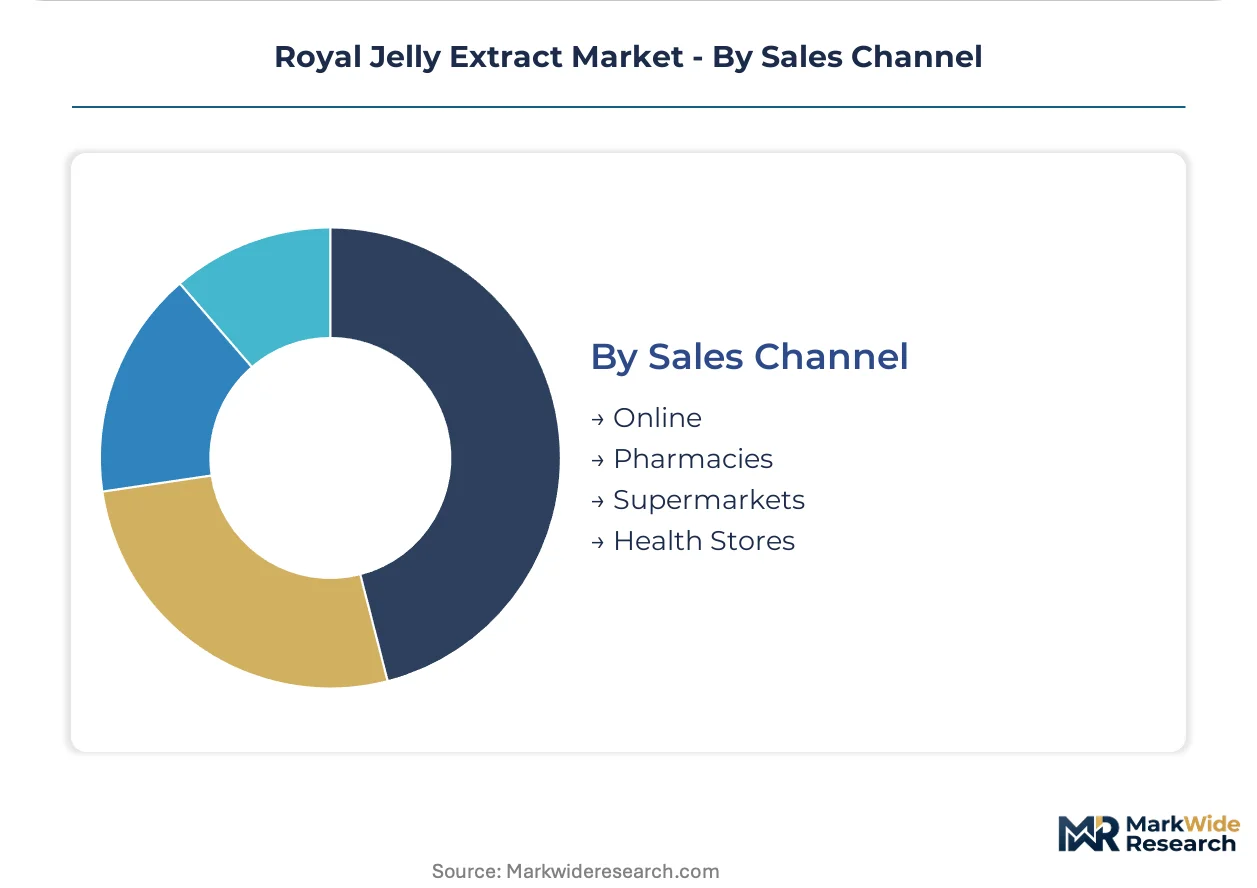
Sales Channel:
Channel segmentation reflects shifting consumer procurement patterns and margin capture strategies across physical and digital retail.
- Online:Direct-to-consumer platforms and marketplace aggregators bypass traditional retail markup structures while accumulating longitudinal efficacy data for FTC claim substantiation. Australian and North American markets show strongest cold-chain logistics maturity for liquid formulation delivery.
- Pharmacies:Professional recommendation channels command premium positioning for standardized-potency capsules and pharmacist-counseled regimens. European pharmacy chains require EFSA-compliant labeling for royal jelly shelf placement.
- Supermarkets:Mass-market retail placement competes on price with plant-based adaptogens in immunity supplement aisles. Private-label penetration is compressing branded margin pools.
- Health Stores:Specialty retailers emphasize organic certification and apiary traceability for enthusiast consumers seeking unprocessed royal jelly formats.
Dominant volume flows through pharmacy and supermarket infrastructure. Online channels are gaining share fastest as subscription models lock in recurring purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apis mellifera colony density in Shandong Province anchors raw material availability for downstream processors. Zhejiang and Fujian provinces supplement domestic Chinese supply with specialized queen breeding operations. Export-oriented extraction facilities cluster near Qingdao port infrastructure to minimize cold-chain transit times.
China
Traditional Chinese Medicine manufacturers in Hangzhou and Guangzhou drive bulk liquid extract procurement for tonic formulations. SAMR health food registration streamlines domestic brand launches while GB standard compliance enables export certification reciprocity. Jiangshan Bee Enterprise anchors Zhejiang Province supply with integrated freeze-drying capabilities serving pharmacy and direct-to-consumer channels.
United States
Subscription-based supplement replenishment models displace pharmacy purchasing for core royal jelly consumers in California and New York metro markets. FDA DSHEA enforcement governs dietary supplement labeling while FTC monitors structure-function claims across e-commerce channels. NOW Foods leverages broad retail shelf presence through standardized potency labeling compliant with federal requirements.
Germany
Pharmaceutical-grade extract demand concentrates in Bavarian and North Rhine-Westphalian compounding pharmacies. EFSA novel food assessments govern imported concentrate authorization, creating eighteen-to-twenty-four-month compliance timelines for Asian suppliers. Düsseldorf-based nutraceutical blenders specify minimum 10-hydroxy-2-decenoic acid thresholds in supply contracts.
Japan
Functional food fortification into honey blends and fermented beverages drives consumption in Tokyo and Osaka metropolitan areas. METI oversees health food claims substantiation while PMDA evaluates pharmaceutical excipient applications. Kyoto-based cosmetics houses expand topical royal jelly SKU counts through department store retail channels.
South Korea
Korean beauty retailers and medical spa networks in Seoul and Busan accelerate dermatological cosmeceutical adoption. MFDS health functional food registration enables immunity-positioned supplement marketing. Gyeonggi-do extraction facilities serve both domestic pharmacy chains and export-bound cosmetic ingredient houses.
Royal Jelly Extract Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and direct-to-practitioner distribution channels. The vendor base stratifies across apiary-controlled supply chains, contract extraction specialists, and retail-brand distributors. Three archetypes dominate: vertically integrated beekeepers with captive raw material, lyophilization-focused processors with Shandong equipment access, and brand houses with pharmacy and e-commerce channel control. Competitive moves center on EFSA novel food authorization acquisition and ISO 22000-HACCP dual certification alignment.
Within the apiary-integrated tier, Y.S. Organic Bee Farms exemplifies vertical control over raw material grades through proprietary colony management. NOW Foods occupies the mass-market brand position with standardized labeling across retail channels. Jiangshan Bee Enterprise anchors Asia-Pacific supply architecture with Zhejiang Province extraction infrastructure. These three represent distinct competitive vectors: captive supply security, retail distribution breadth, and regional processing scale.
| Leading Market Players |
|---|
| Y.S. Organic Bee Farms |
| NOW Foods |
| Durham's Bee Farm |
| Swanson Health Products |
| Jiangshan Bee Enterprise |
| Solgar Inc. |
| Puritan's Pride |
| Nu-Health Products |
| Source Naturals |
| Others |
Pricing and Supply Chain Analysis
Lyophilization energy costs cascade through Shandong Province extraction facilities into three-tier pricing structures across premium, standard, and economy levels, with pharmaceutical-grade certifications commanding formulation premiums while bulk liquid extracts compete on volume scale for TCM manufacturers.
Pricing Analysis
Certification-bundling separates EFSA-authorized concentrates from unregistered commodity grades, with antibiotic residue testing protocols and ISO 22000 alignment driving price differentiation between pharmacy-channel capsules and supermarket-positioned liquids. Subscription replenishment models in North America bundle cold-chain logistics into recurring pricing, while spot-market procurement in Hangzhou apothecaries leaves freight and storage unbundled. Price erosion runs through mass-market immunity supplements as ashwagandha substitution intensifies shelf-space competition. TCM manufacturers exhibit highest price sensitivity; pharmaceutical compounders in Bavaria demonstrate lowest sensitivity due to GMP compliance requirements.
Supply Chain Analysis
GB standard compliance mandates for health food registration in China are reshaping sourcing patterns, pressuring non-compliant processors to upgrade analytical capabilities or exit export channels. Raw royal jelly harvests draw from Shandong, Zhejiang, and Fujian provinces, with queen bee genetic lines resting on specialized breeding operations near Hangzhou. Varroa mite colony volatility and evolving antibiotic residue limits in EU and US jurisdictions create single-source vulnerability for processors lacking multi-jurisdiction certification. Distribution runs through Qingdao port infrastructure for export-bound freeze-dried powders, while domestic Chinese consumption absorbs surplus liquid volumes via TCM manufacturer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Royal jelly extract procurement operates under acute queen bee breeder scarcity, with genetic specialization bottlenecks propping pricing power for apiary-integrated incumbents regardless of downstream processing capacity expansion.
For Market Incumbents: Cement captive supply security through backward integration into high-yield queen breeding operations in Zhejiang and Shandong provinces, insulating against Varroa-driven yield volatility. Defend pharmacy channel positioning by accelerating EFSA novel food authorization acquisition before REACH registration requirements extend compliance timelines for hydrolyzed protein variants. Prioritize ISO 22000-HACCP dual certification alignment to enable single-audit market access across EU, US, and Chinese regulatory clusters. For New Entrants and Emerging Players: Subcritical water extraction technology offers a technology-first wedge into pharmaceutical-grade API contract manufacturing, collapsing traditional separation between food-grade and pharmaceutical-grade production economics. Target dermatological cosmeceutical channels in Seoul medical spa networks and Kyoto department store cosmetics halls, where premium topical positioning escapes commoditized supplement aisle competition. Pursue direct-to-practitioner distribution through functional medicine clinics in California and New York metro markets, bypassing retail markup structures while accumulating longitudinal efficacy data. For Investors and Strategic Acquirers: EFSA authorization approval for a non-EU supplier is the leading indicator that regulatory moats are widening, signaling consolidation opportunity for compliant processors with excess lyophilization capacity. Five-to-ten year viability favors apiary-integrated mid-cap specialists with Shandong equipment access and existing dual-certification portfolios. Monitor SAMR health food registration acceleration rates in China as inflection signal for domestic absorption capacity versus export redirection pressure.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization Acquisition | Eighteen-to-twenty-four-month compliance timelines create first-mover advantage for authorized suppliers in German pharmacy channels. |
| Subcritical Water Extraction Retrofit | German and Japanese equipment manufacturers enable processors to serve nutraceutical and API markets from identical feedstock inputs. |
| Queen Breeding Backward Integration | Specialized Apis mellifera genetic lines in Zhejiang anchor raw material security against colony volatility pressures. |
| Direct-to-Practitioner Channel Development | Functional medicine clinics in North American metro markets capture margin pools previously allocated to pharmacy intermediaries. |
| ISO 22000-HACCP Dual Certification Alignment | Single-audit compliance across Chinese GB standards and international food safety frameworks reduces recurrent certification burden. |
Research Methodology
Multi-period observation of NMPA health food registration volumes, EFSA authorization timelines, and Shandong Province lyophilization capacity utilization anchored the trend analysis, supplemented by interviews with apiary operations managers, extraction facility technical directors, nutraceutical procurement leads at European pharmacy chains, and regulatory affairs specialists at SAMR and FDA. Secondary validation drew from SAMR health food registration databases, EFSA novel food opinions, FDA DSHEA warning letters, customs export records from Qingdao port, and GB standard compliance filings. Bottom-up processor capacity modeling triangulated against top-down consumption estimates from TCM manufacturer procurement patterns and subscription platform shipment data.
Input-output matrices mapped raw royal jelly harvest volumes through lyophilization yield coefficients into finished product availability across liquid, powder, capsule, and cream formats over the projection horizon. Segmentation dimensions modeled included product type, end-use category, packaging format, and sales channel, with geographic regulatory clusters treated as distinct supply-constrained markets. CAGRs derived from fitted growth curves applied to validated base-year estimates, incorporating queen bee genetic improvement rates, subcritical extraction technology adoption curves, and channel migration patterns from pharmacy to online replenishment models.
Several conditions sit outside the modeled scope, including extreme weather impacts on Apis mellifera colony health, abrupt antibiotic residue limit revisions in major jurisdictions, and breakthrough synthetic production of 10-hydroxy-2-decenoic acid bioactives. Forecasts reflect documented assumptions regarding regulatory timeline stability and genetic breeding program continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Clean Label Flavors Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market