
 Africa Food Flavor Market | 2026-2036
Africa Food Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Flavor Market Outlook
Flavor customization services is decoupling product value from raw material costs across the Africa food flavor landscape. Givaudan leverages its regional technical centers to tailor savory profiles for local meat and snack applications. Firmenich SA anchors its position through deep botanical sourcing partnerships in East and Southern Africa. Kerry Group PLC competes by extending integrated taste and nutrition platforms to pan-African food manufacturers seeking streamlined procurement.
Food flavors comprise aromatic compounds, essential oils, extracts, and synthesized molecules formulated to impart specific taste and olfactory characteristics to consumable products. These formulations typically achieve potency at concentrations below one percent by weight, requiring precise carrier systems and stability engineering for heat, pH, and shelf-life tolerance across diverse processing conditions. Natural flavor profiles command premium positioning as clean-label momentum intensifies among African urban consumers, while artificial segments retain volume dominance in price-sensitive mass-market beverages. Savory applications lead structural growth, driven by rising processed meat and instant noodle consumption in Nigeria, Egypt, and South Africa.
FSSAI-aligned standards in Nigeria and South Africa's Department of Health labeling mandates are tightening additive disclosure requirements, redirecting R&D investment toward plant-derived alternatives and fermentation-based building blocks. The country's national food regulator in Egypt has intensified import inspection protocols for synthetic flavor precursors, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving national standards across Africa's fragmented regulatory landscape while building flexible formulation capabilities that pivot between natural, artificial, and organic certifications without redundant capital deployment.
Market Dynamics
Clean-label mandates from South Africa's Department of Health and Nigeria's FSSAI-aligned standards are forcing reformulation cycles across the continent's flavor supply base. Manufacturers now maintain parallel natural and artificial formulation pipelines to navigate fragmented national requirements without duplicating capital expenditure.
Growth Catalysts
- Instant Noodle Proliferation:Nigeria's processed food corridor around Lagos-Abuja drives concentrated demand for savory flavor systems in convenience meals.
- Port-Proximate Manufacturing:Beverage and confectionery plants cluster near West African port infrastructure, reducing lead times for imported flavor precursors.
- Fermentation-Based Building Blocks:Advances in microbial production of aromatic compounds offer cost-competitive natural alternatives to botanical extraction.
Market Restraints
- Import Inspection Protocols:Egypt's national food regulator intensifies scrutiny of synthetic flavor precursors, creating compliance delays for non-certified suppliers.
- Vanillin Price Volatility:Dependence on petrochemical and clove-derived feedstocks exposes formulators to input cost swings.
- Natural Extract Supply Concentration:East African botanical sourcing partnerships concentrate in limited growing regions vulnerable to climate disruption.
Strategic Opportunities
- East African Expansion:Kenya and Ethiopia present underpenetrated markets for savory flavor applications in emerging processed meat sectors.
- E-Commerce B2B Platforms:Digital procurement channels connect pan-African food manufacturers directly with regional flavor distributors, compressing traditional intermediary margins.
- Organic Certification Pipeline:South African export-oriented food producers seek certified-organic flavor inputs to access premium European retail channels.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise in heat-stable and pH-tolerant carrier systems remains concentrated in South Africa and Egypt.
- Dual-Certification Overhead:Maintaining parallel natural, artificial, and organic formulation capabilities strains R&D budgets without guaranteed volume commitment from buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Flavor Market |
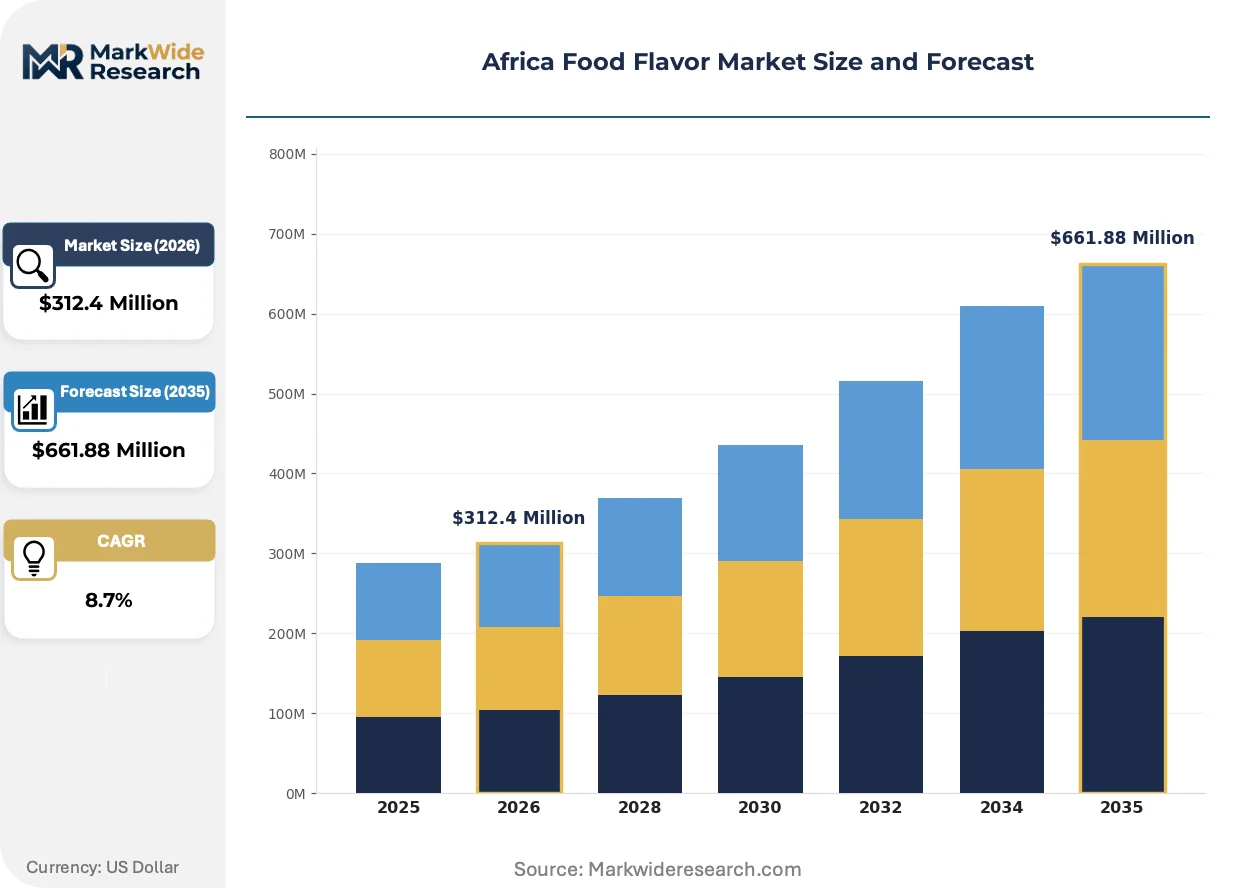
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Artificial, Organic, Customized Flavor Profile: Sweet, Savory, Spicy, Sour Application: Beverages, Snacks, Dairy, Bakery End User: Manufacturers, Retailers, Food Service, Households |
| Companies Covered | Symrise AG, Sensient Technologies Corporation, Givaudan, Corbion Purac, Firmenich SA, International Flavors & Fragrances Inc., Kerry Group PLC, Fruition, Koninklijke DSM NV, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Flavor Market Strategic Shifts
Flavor delivery technologies are fragmenting traditional supply relationships as African food manufacturers seek localized technical support. Three developments are compressing innovation cycles and redrawing competitive boundaries across the continent.
Encapsulation technology is decentralizing flavor manufacturing by enabling regional compounders to produce heat-stable and shelf-life-extended formulations previously requiring imported finished goods. Mid-sized Nigerian and South African processors now license spray-drying and coacervation methods from equipment suppliers rather than purchasing proprietary flavor systems. This capability transfer compresses the value captured by multinational flavor houses while expanding addressable volume for regional technical service providers.
South Africa's Department of Health labeling mandates now require granular disclosure of additive categories including flavor enhancers and carriers. Reformulation timelines have compressed from eighteen months to under nine months for major beverage and snack producers seeking to avoid clean-label penalties in retail channels. Egyptian and Nigerian regulators are observing this enforcement pattern, signaling probable alignment within the analysis window.
Direct technical collaboration between flavor suppliers and African food manufacturers is displacing traditional distributor-mediated relationships. Kenyan and Ghanaian bakery and dairy processors now commission customized savory and sweet profiles through embedded application laboratories rather than selecting from standard catalogs. This specification depth locks in volume commitment while raising switching costs for competing suppliers.
Africa Food Flavor Market Segmentation
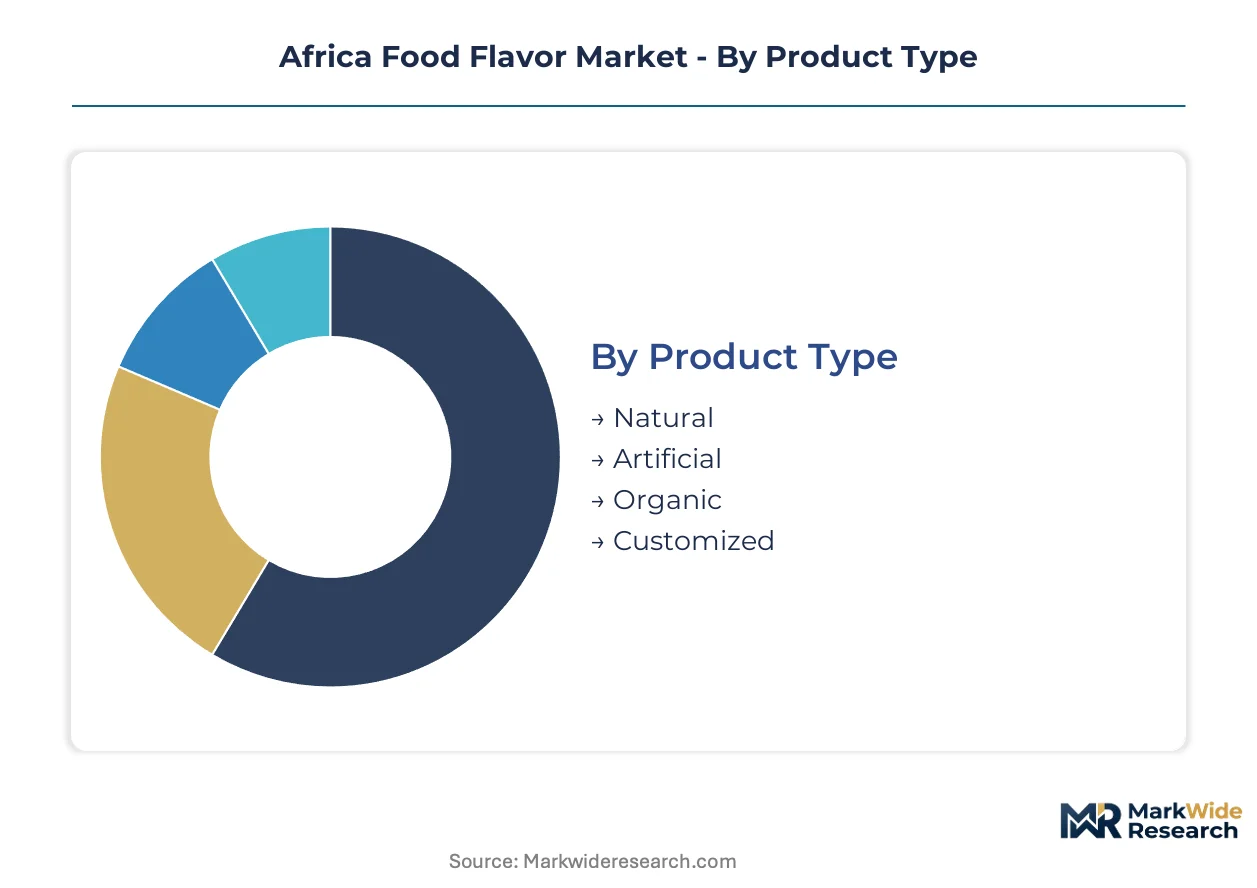
Flavor formulators in Africa navigate divergent technical requirements across product types and end-use applications. Segmentation reveals where natural extract investments yield premium positioning versus where artificial systems maintain cost advantage in price-sensitive categories.
Product Type:
Natural and artificial segments operate as parallel supply chains with limited formulation overlap, while organic and customized categories demand integrated technical partnerships from raw material through finished application.
- Natural:Botanical extracts and essential oils derived from East African and Southern African growing regions. Nigerian beverage manufacturers and South African snack producers drive procurement of clean-label compliant systems, though clove and vanilla feedstock volatility compresses margin stability.
- Artificial:Synthesized aromatic compounds manufactured from petrochemical precursors. Mass-market beverage plants in Egypt and Nigeria retain volume dominance here, as FSSAI-aligned disclosure requirements in West Africa push gradual reformulation toward natural alternatives without full substitution.
- Organic:Certified-organic extracts meeting EU export standards for South African processed food exporters.
- Customized:Application-specific formulations developed through embedded technical collaboration between suppliers and manufacturers.
Volume placements concentrate in artificial systems; the faster expansion belongs to natural extracts.
Flavor Profile:
Cost tiers separate commodity flavor applications from specialized technical development, with savory commanding premium formulation investment and sweet profiles competing on scale economies.
- Savory:Complex umami and meat-like systems built on yeast extracts, hydrolyzed proteins, and fermentation-derived building blocks. Instant noodle manufacturers in Nigeria's Lagos-Abuja corridor and processed meat processors in Egypt anchor demand, as heat-stable carrier engineering requires specialized technical expertise concentrated in South Africa.
- Sweet:Vanilla, fruit, and confectionery profiles leveraging both natural and artificial precursors. Beverage bottlers near West African port infrastructure and confectionery plants in Ghana drive procurement scale, though vanillin price swings from petrochemical and botanical sources create input cost pressure.
- Spicy:Capsicum and pungent profiles for snack seasoning and sauce applications.
- Sour:Acidic and fermented taste systems for beverage and dairy categories.
Margin capture favors savory applications; sweet profiles dominate absolute volume throughput.
Application:
Geographic concentration patterns differ sharply across beverage, snack, dairy, and bakery segments, with port-proximate infrastructure shaping procurement logistics for imported flavor precursors.
- Beverages:Carbonated soft drinks, juices, and flavored water systems requiring pH-stable and heat-tolerant formulations. Plants clustered near Lagos, Accra, and Cairo ports minimize lead times for concentrated flavor imports, though Egyptian import inspection protocols for synthetic precursors create compliance friction for non-certified suppliers.
- Snacks:Savory seasoning systems for extruded and fried products. Nigerian and South African processed snack manufacturers expand flavor portfolios to capture urban consumer spending, with encapsulation technology enabling regional compounders to produce heat-stable formulations previously imported as finished goods.
- Dairy:Fermented and fresh milk flavor systems for yogurt and flavored milk.
- Bakery:Yeast-compatible and oven-stable profiles for bread and pastry applications.
Procurement scale clusters in beverages; snack applications are climbing the fastest.
End User:
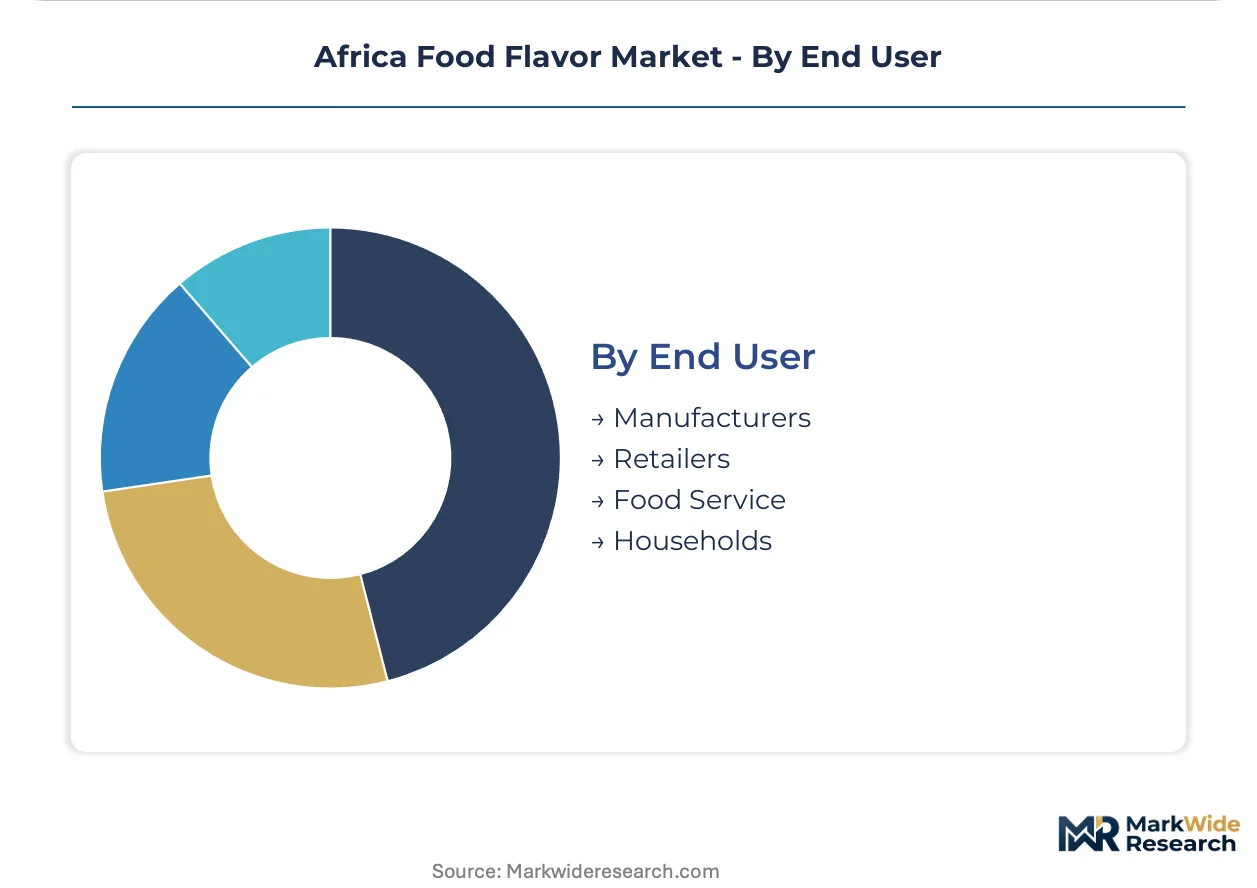
Customer type determines specification depth and technical service intensity, with manufacturers demanding embedded laboratory collaboration while retailers and food service prioritize catalog selection and logistics reliability.
- Manufacturers:Pan-African food processors seeking integrated taste and nutrition platforms with streamlined procurement. Kenyan and Ghanaian bakery and dairy processors commission customized profiles through embedded application laboratories rather than standard catalogs, locking in volume commitment and raising switching costs.
- Retailers:Private-label and branded product developers requiring rapid reformulation cycles. South Africa's Department of Health labeling mandates compress timelines from eighteen months to under nine months for clean-label compliance.
- Food Service:Restaurant chains and institutional caterers with standardized flavor requirements.
- Households:Direct consumer purchases of retail flavor products.
Technical integration concentrates with manufacturers; retailer channel growth is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors the continent's flavor procurement activity, with the Lagos-Abuja manufacturing corridor concentrating Nigeria's beverage and confectionery demand near Apapa port infrastructure.
Nigeria
Instant noodle manufacturers and processed snack producers drive savory flavor procurement along the Lagos-Abuja corridor. FSSAI-aligned standards from the country's national food regulator mandate granular additive disclosure, compressing reformulation timelines. Beverage plants cluster near Lagos port facilities to minimize lead times for imported flavor precursors.
South Africa
Export-oriented food producers seek certified-organic flavor inputs for European retail channels, while domestic snack manufacturers expand clean-label portfolios. The Department of Health's updated labeling requirements push reformulation toward natural extracts. Technical expertise in heat-stable carrier systems concentrates in Gauteng's industrial zones.
Egypt
Processed meat processors anchor demand for complex umami systems built on fermentation-derived building blocks. The national food regulator has intensified import inspection protocols for synthetic flavor precursors, creating compliance barriers for non-certified suppliers. Manufacturing activity clusters near Cairo's port infrastructure and Suez Canal access points.
Kenya
Emerging processed meat sectors present underpenetrated demand for savory flavor applications. Bakery and dairy processors commission customized profiles through embedded application laboratories rather than standard catalogs. Nairobi's industrial zones host growing technical collaboration between regional compounders and multinational flavor houses.
Ghana
Confectionery plants near Tema port drive procurement scale for sweet flavor profiles, though vanillin price volatility from petrochemical and botanical sources creates input cost pressure. The country's food safety authority observes South African labeling enforcement patterns, signaling probable regulatory alignment. Regional compounders leverage encapsulation technology to produce heat-stable formulations previously imported as finished goods.
Africa Food Flavor Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Africa's flavor supply base. Multinational houses with integrated technical centers and botanical sourcing partnerships dominate premium formulation segments, while regional compounders capture volume through licensed encapsulation technology and localized production. Three archetypes define competitive positioning: integrated taste-and-nutrition platforms, specialized natural extract suppliers, and application-focused technical service providers. Capacity expansion through fermentation-based building block investments and strategic partnerships for East African botanical sourcing represent the dominant competitive moves.
Among Switzerland-based specialists, Givaudan and Firmenich SA exemplify the integrated technical center archetype, anchoring premium positioning through embedded application laboratories and deep botanical sourcing partnerships across East and Southern Africa. Kerry Group PLC, an Ireland-based public limited company, occupies a position within the taste-and-nutrition platform tier, competing through streamlined procurement integration for pan-African food manufacturers.
| Leading Market Players |
|---|
| Symrise AG |
| Sensient Technologies Corporation |
| Givaudan |
| Corbion Purac |
| Firmenich SA |
| International Flavors & Fragrances Inc. |
| Kerry Group PLC |
| Fruition |
| Koninklijke DSM NV |
| Others |
Value Chain & Pricing Dynamics
Flavor chemist expertise concentrated in Gauteng and Cairo industrial zones widens the spread between premium natural formulations and commodity artificial tiers, as labor-cost differentials for heat-stable carrier engineering cascade through finished-product pricing.
Pricing Analysis
Value-based pricing anchored to clean-label compliance outcomes separates certified-organic extracts for South African export processors from artificial systems serving Nigerian mass-market beverage plants. Price differentiation tracks certification grade and customization depth, with FSSAI-aligned disclosure mandates in West Africa compressing margins on synthetic formulations. Cost pressure intensifies in artificial tiers as clove and petrochemical feedstock volatility feeds through vanillin input costs. Mass-market beverage manufacturers exhibit highest price sensitivity; export-oriented snack producers accept premium positioning for EU-compliant natural extracts.
Supply Chain Analysis
South Africa's Department of Health labeling mandates and Nigeria's FSSAI-aligned standards are reshaping sourcing toward regional botanical partnerships and fermentation-derived building blocks. Supply concentration rests on East African growing regions for botanical feedstocks, Egyptian and Nigerian port infrastructure for precursor imports, and South African technical centers for carrier-system engineering. Raw material dependencies include clove-derived vanillin, yeast extracts, and hydrolyzed proteins. Single-source vulnerability concentrates in East African botanical regions exposed to climate disruption. Distribution runs through multinational flavor houses with embedded technical laboratories serving pan-African manufacturers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as regulatory compliance costs and dual-certification R&D overhead force sub-scale compounders toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from licensed encapsulation technology transferring to Nigerian and Ghanaian regional compounders. Defend position by deepening botanical sourcing partnerships in Kenya and Ethiopia to secure climate-resilient feedstock pipelines. Prioritize fermentation-based building block investments to decouple natural-flavor costs from agricultural volatility.
For New Entrants and Emerging Players: Launch via e-commerce B2B platforms connecting directly with Kenyan and Ethiopian processed meat manufacturers, bypassing traditional distributor intermediaries. Target underpenetrated savory applications in East Africa's emerging instant noodle and processed meat sectors. Lead with application-focused technical service rather than catalog-based product selection to lock in volume commitment.
For Investors and Strategic Acquirers: Re-rating potential sits with regional compounders possessing licensed encapsulation capabilities and established distributor relationships given accelerating technology transfer from multinational houses. Long-term viability favors asset-light technical service providers with flexible formulation pipelines spanning natural, artificial, and organic certifications. Monitor Egyptian import inspection protocol enforcement as an inflection signal for synthetic precursor supply disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| East African Botanical Sourcing Partnership | Secures climate-resilient feedstock supply for natural extract portfolios in Kenya and Ethiopia. |
| Fermentation-Based Building Block Investment | Reduces dependence on clove and petrochemical vanillin precursors exposed to price volatility. |
| Licensed Encapsulation Technology Deployment | Enables Nigerian and Ghanaian regional compounders to produce heat-stable formulations locally. |
| Embedded Application Laboratory Expansion | Locks in volume commitment from Kenyan and Ghanaian bakery and dairy processors through direct technical collaboration. |
| Organic Certification Pipeline Development | Accesses premium European retail channels for South African export-oriented food producers. |
Study Parameters
Multi-period observation of flavor formulation patent filings, regulatory disclosure patterns, and port-of-entry inspection volumes anchored the trend analysis, supplemented by interviews with flavor chemists, procurement leads at pan-African beverage and snack manufacturers, regulatory affairs directors at national food regulators, and technical directors at regional compounding facilities. Secondary validation drew from customs and trade data, FSSAI and Department of Health regulatory filings, botanical sourcing records from East African agricultural cooperatives, and SEC disclosures from listed multinational flavor houses. Bottom-up demand modeling across application segments triangulated against top-down supply-side capacity assessments.
Segment-weighting approaches distributed value and volume across natural, artificial, organic, and customized product types; savory, sweet, spicy, and sour flavor profiles; beverage, snack, dairy, and bakery applications; and manufacturer, retailer, food service, and household end users throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical formulation adoption rates and regulatory enforcement timelines. Industry-specific inputs included fermentation technology maturation curves and climate disruption probabilities for East African growing regions.
The model assumes a particular technology adoption path for encapsulation and fermentation-derived building blocks; alternative pathways for microbial aromatic compound production would alter the outlook for natural-flavor cost competitiveness. Forecasts reflect assumptions regarding regulatory alignment timelines across Nigeria, South Africa, and Egypt, plus sustained urbanization-driven processed food demand in West African manufacturing corridors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market