
 Europe Aluminum Extrusion Market | 2026-2036
Europe Aluminum Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminum Extrusion Market Intelligence
Aluminum extrusion toolmaking capacity is bifurcating between high-volume automotive die lines and short-run architectural specialists. Norsk Hydro ASA leverages captive smelting and recycling assets to control billet cost through energy-price volatility. Constellium SE anchors aerospace-grade hard-alloy supply from its French and German rolling-extrusion complexes. AMAG Austria Metall AG sustains margin through Austrian hydropower-backed primary metal and specialized 6xxx-series profiles.
Europe aluminum extrusion shapes aluminum alloy billets—typically 6xxx-series (Al-Mg-Si) or 7xxx-series (Al-Zn-Mg-Cu)—through a steel die under ram pressures exceeding 300 MPa, producing constant-cross-section components for load-bearing frames and thermal-management systems. The transportation application leads value generation as OEMs substitute extruded crash structures for stamped steel in battery-electric architectures. Formed profiles dominate volume, though tubes command premium pricing in heat-exchanger and HVAC condenser networks where leak-tight dimensional tolerance is critical.
The EU Green Deal's carbon-border adjustment and REACH substance restrictions reshape billet sourcing rules, compelling extruders to document Scope 1-3 emissions or face exclusion from public-infrastructure tenders. ECHA's evolving candidate list for SVHCs pressures surface-treatment suppliers to phase chromate conversion coatings in favor of trivalent chrome or thin-film organic alternatives. Stakeholders must monitor Germany's KBA vehicle-type approval protocols for extruded-aluminum crashworthiness, as these standards propagate across EU member states through UNECE harmonization.
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanism is forcing European extruders to restructure billet sourcing around documented Scope 1-3 emissions, creating competitive separation between smelters with hydropower-backed metal and those dependent on grid electricity.
Growth Catalysts
- Transportation electrification:German and French OEMs are substituting extruded aluminum crash structures for stamped steel in battery-electric vehicle platforms, pulling high-strength 6xxx-series profiles into chassis programs.
- REACH substance restrictions:ECHA's evolving candidate list for SVHCs is accelerating phase-out of hexavalent chrome conversion coatings, opening procurement slots for suppliers with trivalent chrome or thin-film organic surface treatments.
- Nearshoring of die production:Toolmaking capacity is concentrating in Germany's industrial corridor to serve just-in-time delivery requirements for automotive extrusion programs with sub-48-hour die changeover protocols.
Market Restraints
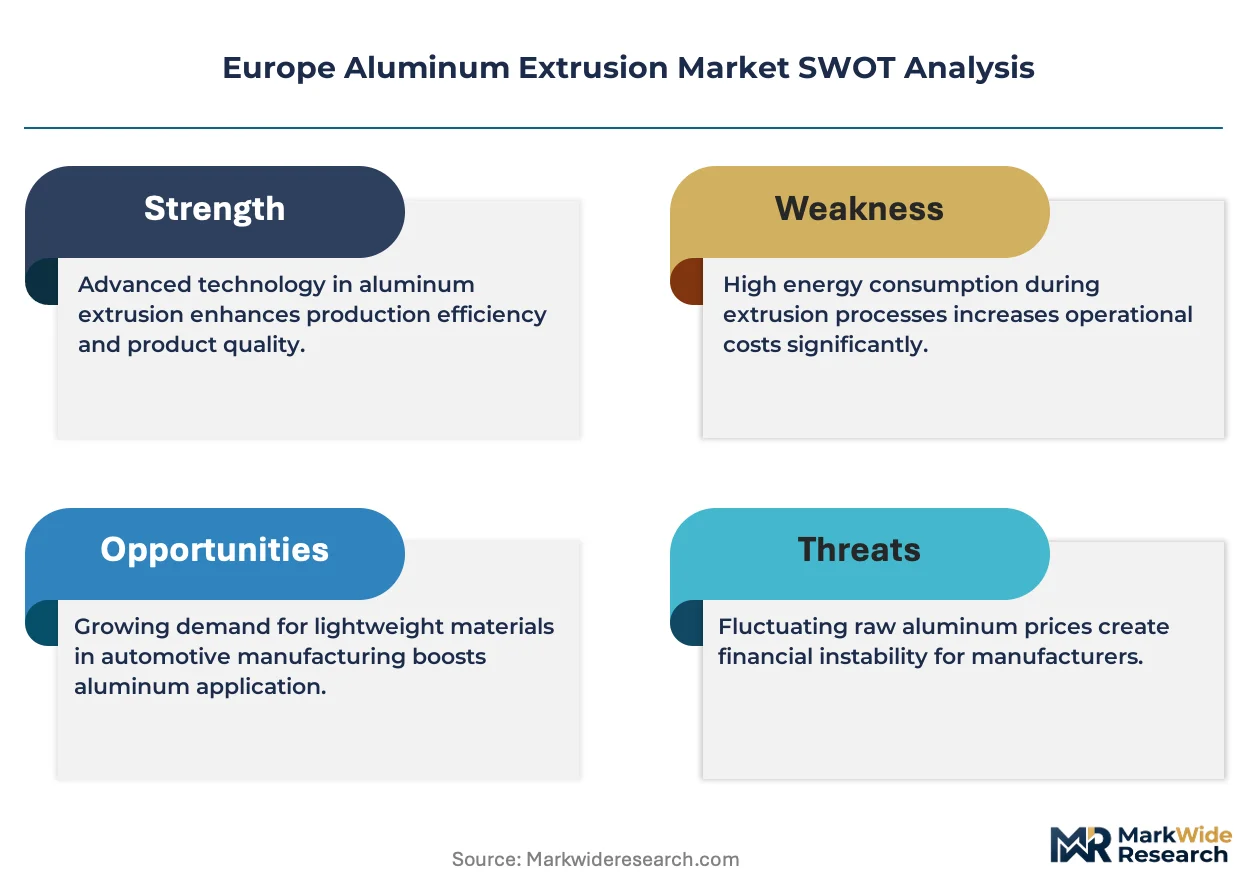
- Primary metal cost volatility:European spot electricity prices continue to drive billet cost swings, compressing margins for extruders without captive smelting or long-term power purchase agreements.
- Die steel supply concentration:Specialty H13 and H11 tool steel for extrusion dies sources predominantly from Austrian and Swedish producers, creating single-point vulnerability for high-volume automotive die lines.
- Hard-alloy capacity scarcity:7xxx-series aerospace-grade extrusion capacity remains locked in French and German rolling-extrusion complexes, limiting supply elasticity for Tier 2 automotive suppliers.
Strategic Opportunities
- Poland and Czech Republic industrial corridors:Underpenetrated extrusion capacity in Central Europe offers logistics-cost advantages for supplying German OEMs while qualifying for EU cohesion fund infrastructure tenders.
- Closed-loop recycling ecosystems:Post-consumer aluminum scrap collection networks in France and Benelux are enabling extruders to market low-carbon secondary billet into public procurement frameworks with embodied-carbon thresholds.
- Thermal management convergence:Heat-exchanger manufacturers are integrating extruded microchannel tubes with phase-change materials, opening premium pricing in HVAC and battery-cooling applications.
Industry Challenges
- Die design engineering talent:Finite-element simulation expertise for complex hollow-profile dies remains concentrated among retiring specialists in Austria and Germany, constraining new product development timelines.
- KBA type-approval certification:Germany's vehicle-type approval protocols for extruded-aluminum crashworthiness require 18-24 month validation cycles, delaying revenue recognition for new automotive programs.
- Legacy ERP integration:Smaller architectural extruders struggle to connect shop-floor die-correction data with customer-facing order management systems, fragmenting traceability documentation for REACH compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminum Extrusion Market |
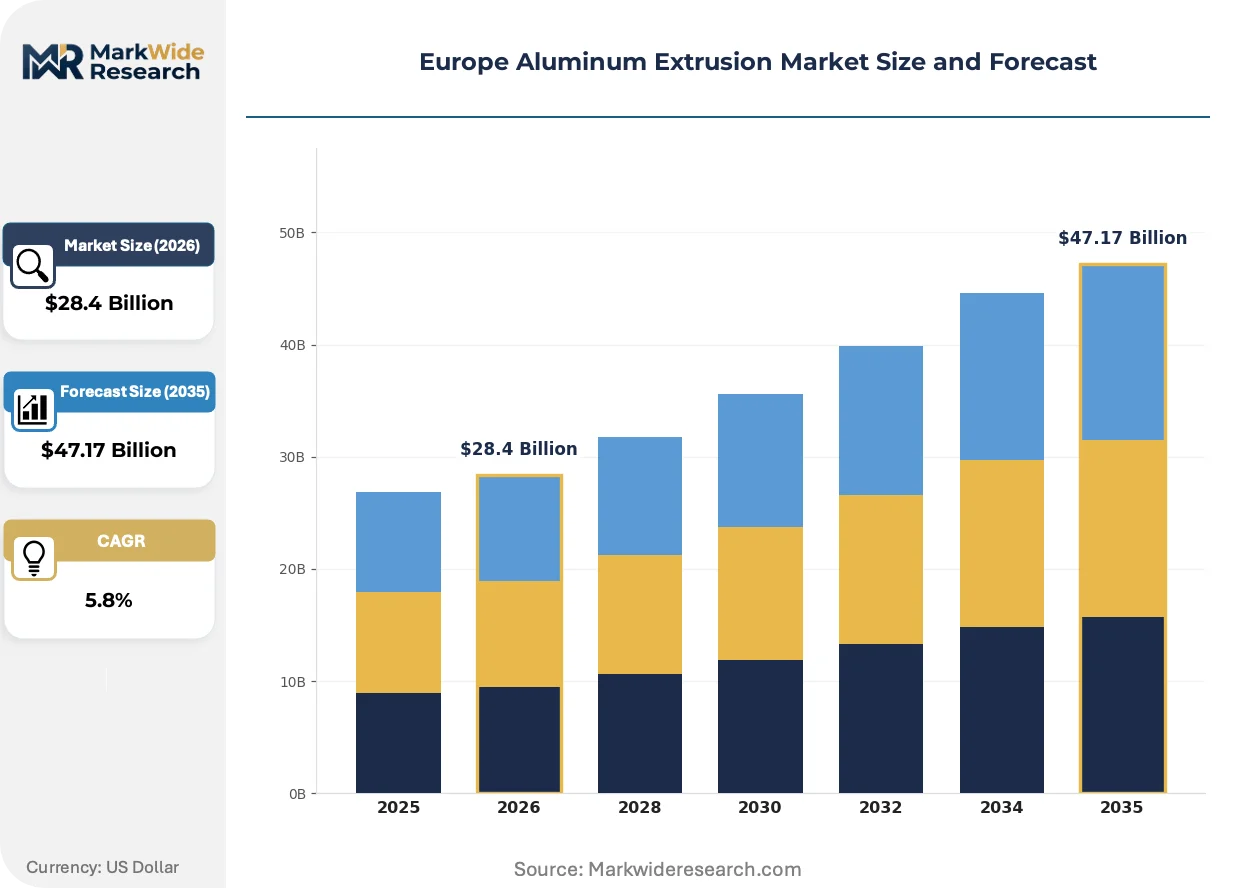
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Formed Profiles, Tubes, Bars, Sheets End User: Automotive Manufacturers, Construction Contractors, Aerospace Firms, Consumer Goods Companies Application: Architectural, Industrial, Transportation, Electrical Technology: Direct Extrusion, Indirect Extrusion, Hot Extrusion, Cold Extrusion |
| Companies Covered | Norsk Hydro ASA, Alupress, Constellium SE, Arconic Corporation, Alcomet, AMAG Austria Metall AG, EST Germany, Kaiser Aluminum Corporation, Metra Holding S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminum Extrusion Market Strategic Shifts & Innovations
Extrusion technology is bifurcating between high-speed automotive lines demanding sub-millimeter tolerance and flexible architectural systems enabling mass customization, with digital thread integration becoming the decisive capability separator.
Hydrostatic extrusion presses operating at ram pressures exceeding 600 MPa are displacing conventional direct extrusion for high-strength 7xxx-series aerospace profiles. Airbus and Safran suppliers in France are adopting these systems to produce near-net-shape landing gear components with 15% material yield improvement. The technology is displacing machined-from-solid aluminum forgings in structural airframe applications where weight reduction justifies capital intensity.
EU F-Gas Regulation phase-down mandates are tightening refrigerant containment requirements for HVAC heat exchangers. Extruders serving the sector must now guarantee leak-tight dimensional tolerances below 50 microns on microchannel tube walls to accommodate higher-pressure CO2 refrigerants. German OEMs are qualifying suppliers through accelerated thermal-cycle testing protocols that compress traditional 12-month validation into 16-week programs.
Automotive Tier 1 suppliers are consolidating extrusion procurement under single-source framework agreements with integrated logistics guarantees. Bosch and Continental are replacing spot-market billet purchasing with five-year tolling contracts that transfer energy-price risk to extruders in exchange for volume commitments. This concentration is most visible in Bavaria and Baden-Württemberg, where battery-housing programs require synchronized delivery of 200+ distinct profile geometries.
Europe Aluminum Extrusion Market Segmentation
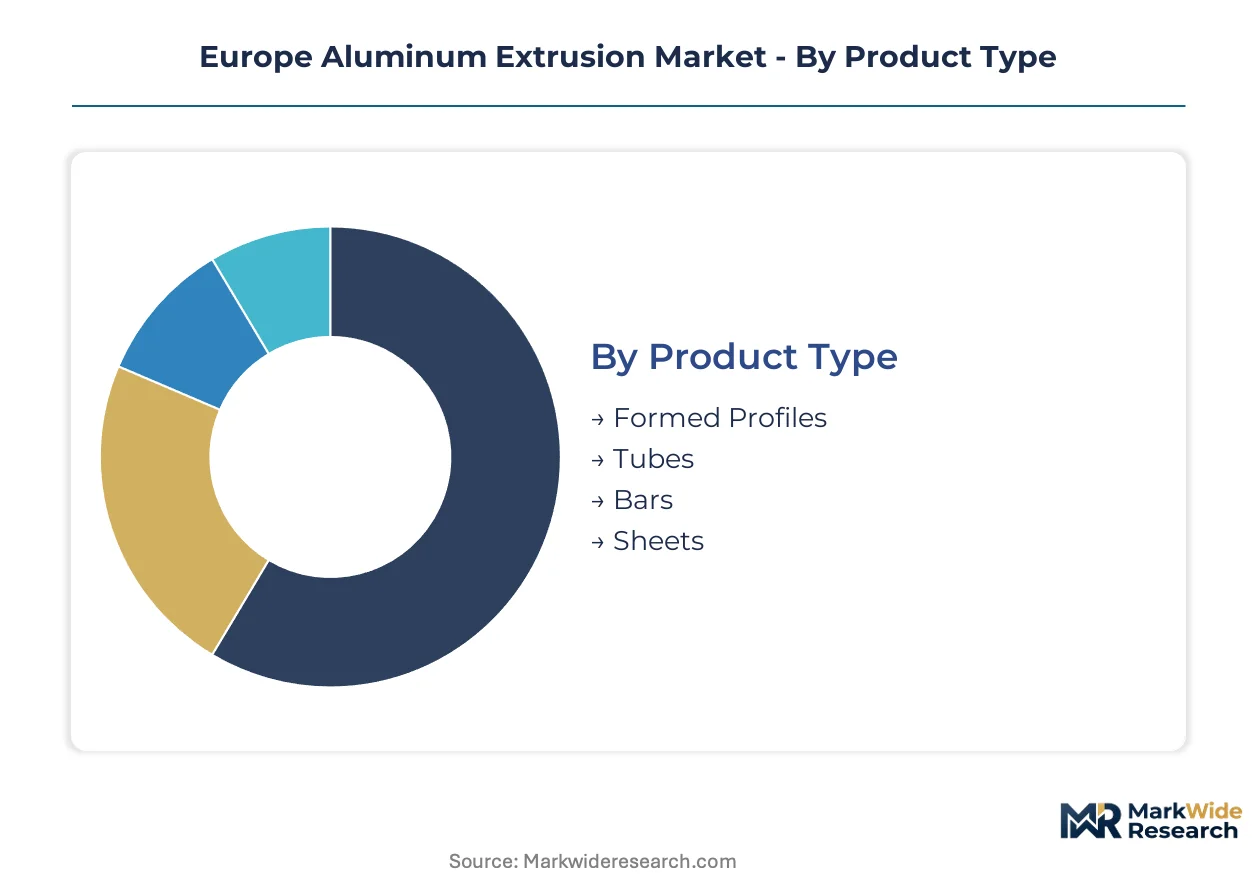
Extrusion buyers in Europe segment supply by mechanical specification and process capability rather than commodity grade. Substitution pressure from composite materials and roll-formed steel varies sharply across these dimensions, reshaping investment priorities for German and French producers.
Product Type:
Formed profiles face the most acute substitution threat from carbon-fiber reinforced polymers in automotive closure panels, while tubes maintain process-based moats in thermal systems.
- Formed Profiles:Constant-cross-section components produced through steel dies at ram pressures exceeding 300 MPa, typically in 6xxx-series alloys. German OEMs in Bavaria specify these for battery-electric vehicle chassis members where crash-energy absorption requirements lock in aluminum over steel. The segment absorbs the highest volume of EU Green Deal-compliant low-carbon billet.
- Tubes:Hollow profiles with wall thickness tolerances below 50 microns for leak-tight HVAC and battery-cooling applications. French heat-exchanger manufacturers in the Rhône-Alpes cluster specify microchannel tubes for CO2 refrigerant systems under F-Gas Regulation mandates, commanding premium pricing over solid forms.
- Bars:Solid round and rectangular stock for machining feedstock in industrial equipment. Austrian hydropower-backed smelters supply this grade to Central European machine builders.
- Sheets:Flat extruded plate for architectural cladding and transportation flooring. Italian facade specialists source these for Mediterranean infrastructure tenders with embodied-carbon documentation requirements.
Formed profiles anchor the volume base while tubes gain share at the steepest rate.
End User:
Cost tier separation is pronounced, with aerospace firms paying 3-4x the billet-equivalent price of construction contractors for hard-alloy certification and traceability.
- Automotive Manufacturers:German and French OEMs specify high-strength 6xxx-series crash structures with 18-24 month KBA type-approval validation cycles. Bosch and Continental framework agreements concentrate procurement among extruders with synchronized logistics guarantees for 200+ profile geometries.
- Construction Contractors:Architectural systems buyers prioritize flexibility and short-run capability over metallurgical sophistication. Benelux post-consumer scrap networks enable low-carbon secondary billet positioning for public procurement frameworks.
- Aerospace Firms:Airbus and Safran suppliers in France demand 7xxx-series hard alloys with aerospace-grade certification from rolling-extrusion complexes. Hydrostatic extrusion at 600+ MPa ram pressure yields 15% material savings over machined forgings for landing gear components.
- Consumer Goods Companies:Appliance and electronics housings requiring cosmetic surface quality and moderate strength. Polish and Czech extruders serve this tier with logistics-cost advantages into German distribution.
Automotive manufacturers dominate value capture while aerospace firms expand most quickly on per-kilogram margins.
Application:
Volume concentration in transportation applications is reshaping capacity allocation, with industrial applications retreating to secondary billet and shorter runs.
- Architectural:Curtain wall systems, window frames, and structural glazing supports. German facade engineers specify thermal-break profiles with documented Scope 1-3 emissions for EU public-infrastructure tenders.
- Industrial:Machine frames, conveyor systems, and material handling equipment. This tier absorbs the highest share of recycled-content billet from French and Benelux collection networks.
- Transportation:Battery-electric vehicle platforms, rail rolling stock, and marine superstructures. French and German OEMs substitute extruded aluminum for stamped steel in lightweight chassis programs, pulling capacity from architectural lines.
- Electrical:Busbar systems, heat sinks, and electromagnetic shielding enclosures. Austrian producers leverage hydropower-backed primary metal for conductivity-critical applications.
Transportation commands the capacity expansion while electrical maintains the most stable pricing through conductivity specifications.
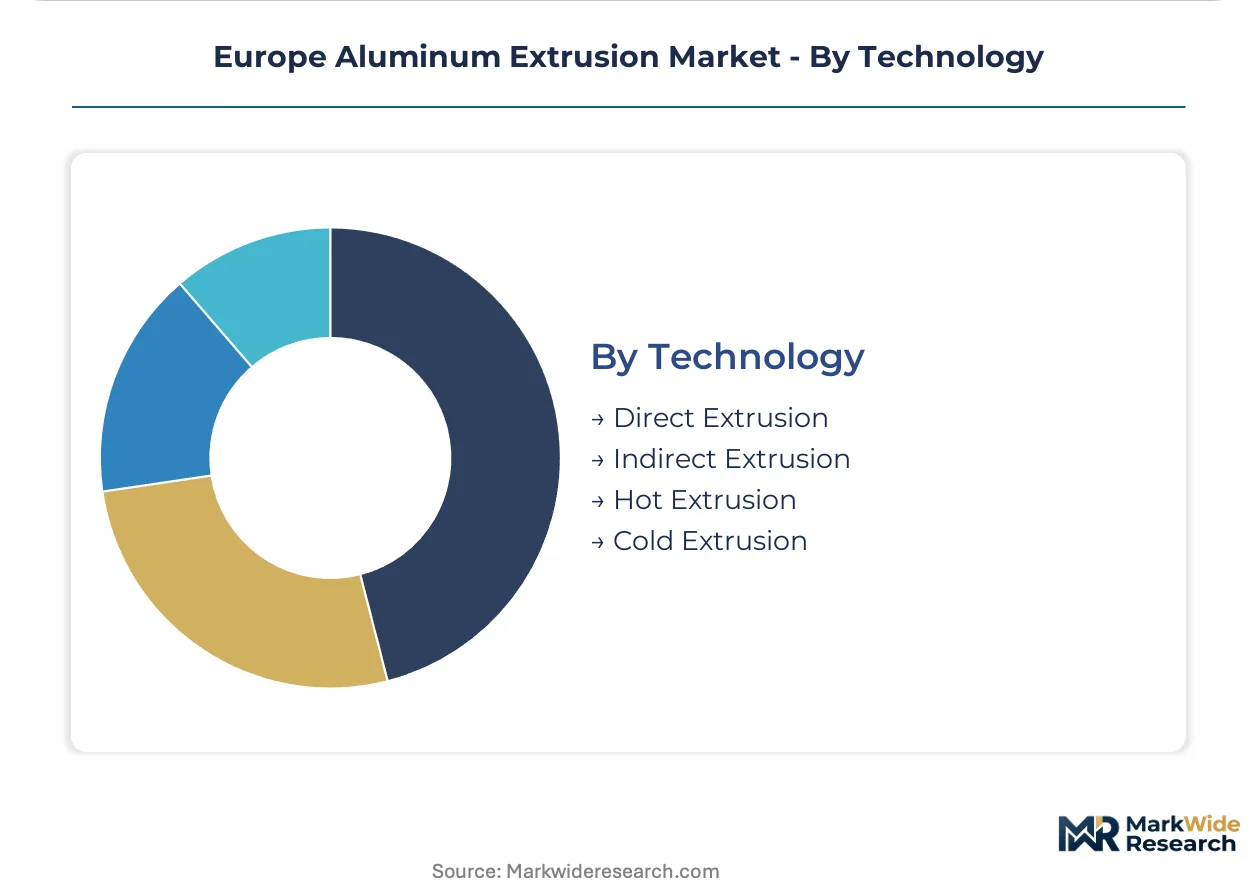
Technology:
Process selection determines alloy range and tolerance capability, with direct extrusion retaining volume leadership despite hydrostatic advances in premium niches.
- Direct Extrusion:Billet pushed through stationary die by ram pressure; standard for 6xxx-series automotive and architectural profiles. German industrial corridor extruders operate sub-48-hour die changeover protocols for just-in-time automotive delivery.
- Indirect Extrusion:Die moves against stationary billet, reducing friction and enabling finer tolerances. French aerospace suppliers adopt this for 7xxx-series hard alloys where material yield improvement justifies slower throughput.
- Hot Extrusion:Billet heated above recrystallization temperature for complex hollow profiles. Austrian die design specialists concentrate finite-element simulation expertise for these geometries.
- Cold Extrusion:Room-temperature forming for high-strength, close-tolerance components in limited alloy ranges. German precision engineering clusters specify this for small-batch industrial applications.
Direct extrusion holds the volume base while hydrostatic variants within indirect and hot categories climb the fastest on aerospace qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA vehicle-type approval protocols in Germany anchor regulatory harmonization across EU member states, with UNECE standards propagating from Stuttgart and Munich testing centers into French and Austrian certification workflows.
Germany
Bavarian OEMs specify high-strength 6xxx-series crash structures for battery-electric platforms, pulling capacity from architectural lines. The KBA mandates 18-24 month validation cycles for extruded-aluminum crashworthiness. Stuttgart and Munich industrial corridors concentrate die design engineering talent for complex hollow-profile geometries.
France
Airbus and Safran suppliers in the Rhône-Alpes cluster demand 7xxx-series hard alloys with aerospace-grade certification. ECHA's evolving SVHC candidate list accelerates phase-out of hexavalent chrome conversion coatings. Toulouse and Lyon rolling-extrusion complexes lock in hydrostatic extrusion capacity for landing gear components.
Austria
AMAG leverages hydropower-backed primary metal to sustain margin through energy-price volatility. REACH substance restrictions pressure surface-treatment suppliers toward trivalent chrome alternatives. Upper Austrian smelters supply conductivity-critical 6xxx-series grades to Central European machine builders.
Poland
Underpenetrated extrusion capacity offers logistics-cost advantages for supplying German OEMs. EU cohesion fund infrastructure tenders qualify Polish producers for public procurement frameworks. Silesian and Greater Poland industrial corridors attract tolling contracts transferring energy-price risk from Bavarian Tier 1 suppliers.
Benelux
Post-consumer aluminum scrap collection networks enable low-carbon secondary billet positioning. The EU Green Deal's carbon-border adjustment mechanism rewards documented Scope 1-3 emissions tracing. Belgian and Dutch extruders serve architectural systems buyers prioritizing flexibility over metallurgical sophistication.
Europe Aluminum Extrusion Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive smelting and recycling assets separating the former from energy-price-exposed competitors. The upper tier commands automotive framework agreements through synchronized logistics guarantees, while specialists survive on short-run architectural flexibility and surface-treatment differentiation. Strategic archetypes include hydropower-backed primary metal producers, aerospace-grade hard-alloy rollers, and Central European logistics-cost optimizers. Competitive moves concentrate on backward integration into billet supply and die steel sourcing security.
Among integrated Nordic producers, Norsk Hydro ASA exemplifies the captive-smelting archetype controlling cost through energy-price volatility. French and German rolling-extrusion complexes, represented by Constellium SE, anchor aerospace-grade hard-alloy supply with 7xxx-series certification. Austrian hydropower specialists, with AMAG Austria Metall AG occupying this position, sustain margin through low-carbon primary metal and specialized 6xxx-series profiles.
| Leading Market Players |
|---|
| Norsk Hydro ASA |
| Alupress |
| Constellium SE |
| Arconic Corporation |
| Alcomet |
| AMAG Austria Metall AG |
| EST Germany |
| Kaiser Aluminum Corporation |
| Metra Holding S.p.A |
| Others |
Cost & Logistics Intelligence
Long-term tolling contracts transferring energy-price risk from Bavarian Tier 1 suppliers to extruders now lock in both billet access and margin visibility across the European aluminum extrusion market. These five-year frameworks with Bosch and Continental synchronize delivery of 200-plus profile geometries while insulating OEMs from spot electricity volatility.
Pricing Analysis
Geographic price spreads of 8-12 percent separate German automotive-grade 6xxx-series profiles from Polish and Czech architectural stock. Three-tier pricing structure across aerospace-certified, automotive-validated, and construction-standard grades reflects KBA type-approval investment and die engineering intensity. Cost compression in architectural tiers intensifies because Benelux secondary billet floods public procurement frameworks. Construction contractors exhibit highest price sensitivity while Airbus and Safran suppliers accept 3-4x billet-equivalent premiums for 7xxx-series hard-alloy certification.
Supply Chain Analysis
Just-in-time inventory protocols dominate German automotive corridors where sub-48-hour die changeover requirements eliminate strategic stockpiling. Supply concentrates in Germany, France, and Austria for high-value extrusion while Poland and Czech Republic absorb tolling overflow. The chain draws from captive Austrian and Swedish H13/H11 die steel, hydropower-backed primary metal, and French aerospace rolling-extrusion complexes. Single-source vulnerability in specialty tool steel creates chokepoint exposure. Distribution runs through synchronized logistics guarantees to Bavarian and Baden-Württemberg OEM clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-fiber reinforced polymers threaten automotive closure panels while steel roll-forming challenges non-structural architectural systems. Incumbents must defend substitution pressure through metallurgical differentiation and captive supply control.
For Market Incumbents: Consolidate die design engineering talent in Stuttgart and Munich corridors before specialist retirement accelerates. Secure long-term power purchase agreements or captive smelting to offset electricity price volatility compressing margins. Defend against carbon-fiber substitution by deepening KBA crashworthiness certification moats. For New Entrants and Emerging Players: Differentiate on low-carbon secondary billet positioning using French and Benelux post-consumer scrap networks. Target Polish and Czech industrial corridors for logistics-cost advantages into German OEM supply chains. Pursue EU cohesion fund infrastructure tenders with documented Scope 1-3 emissions tracing as the go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward hydropower-backed integrated producers with captive recycling assets and aerospace-grade hard-alloy certification. Long-term viability over the next decade rests on carbon-border adjustment compliance and F-Gas Regulation positioning. Watch for KBA validation cycle acceleration as the inflection signal indicating automotive program win rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Supply | Captive smelting insulates Norsk Hydro and AMAG from European electricity price swings. |
| Hydrostatic Extrusion Capacity Buildout | French rolling-extrusion complexes capture 15% material yield improvement for Airbus landing gear. |
| Closed-Loop Recycling Ecosystem | Benelux scrap networks enable low-carbon secondary billet qualification for EU public tenders. |
| Die Steel Supply Security | Long-term offtake from Austrian and Swedish producers mitigates single-source vulnerability. |
| Surface Treatment Transition | Trivalent chrome and thin-film organic alternatives secure REACH SVHC compliance for ECHA mandates. |
Research Approach
The analysis maps transportation electrification, aerospace hard-alloy demand, and architectural systems segments, each validated through extrusion plant managers, OEM platform engineers, heat-exchanger procurement leads, and die design specialists. Primary interviews with Tier 1 supplier sourcing directors and rolling-extrusion complex technical directors combined with secondary validation from ECHA SVHC candidate list updates, KBA type-approval protocols, EU customs trade data, and UNECE harmonization documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks against European aluminum association production statistics and OEM bill-of-materials disclosures validated segment-level outputs across the projection horizon. The analytical framework modeled product type, end-user tier, application, and technology dimensions with alloy-series specificity. CAGRs derived from regression analysis of historical capacity utilization, electrification penetration curves, and carbon-border adjustment implementation phasing. Forecast inputs incorporated F-Gas Regulation refrigerant phase-down timelines and REACH substance restriction evolution.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or hydropower capacity expansion would require recalibration. Forecasts reflect assumptions regarding KBA validation cycle stability, die steel supply continuity, and automotive platform aluminum intensity trends. Revision becomes warranted when carbon-fiber cost-parity thresholds or steel roll-forming tolerance improvements cross critical adoption levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Stainless Steel 400 Series Market
Metals
India Metal Fabrication Market
Metals
Global Vanadium Market
Metals
US Copper Scrap Market
Metals
High Purity Lead Market
Metals
Metal Powder Market
Metals
Aluminum Scrap Recycling Market
Metals
Rolled Steel Motor Market
Metals
Steel Ingots Market
Metals
Steel Wire Market
Metals
Battery Metals Market
Metals
Lithium Tungstate Market
Metals
Electrolytic Iron Market
Metals
Stainless Steel Sheet Market
Metals
Global Tin Market
Metals
Industrial Silver Market