
 Phytoceramide Supplement Market | 2026-2036
Phytoceramide Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Phytoceramide Supplement Market Analytics
Skincare enthusiasts is collapsing the historical dominance of general health-conscious consumers as the primary buyer archetype in phytoceramide purchasing. DSM Nutritional Products leverages its biotechnology heritage to supply high-purity wheat-derived ceramide precursors to finished-goods manufacturers. Herbalife Nutrition anchors its position through multi-level distribution networks that penetrate emerging middle-class wellness segments across Latin America and Southeast Asia. Amway Corporation competes through vertically controlled supply chains spanning botanical extraction to encapsulated finished products.
Phytoceramide supplements comprise lipid molecules structurally analogous to human skin ceramides, typically extracted from wheat, rice, or sweet potato sources and standardized to contain glucosylceramides or glycosylceramides at concentrations ranging from 0.5% to 2% by weight. These compounds function primarily to support skin barrier integrity and moisture retention when consumed orally, bridging dermatological science with nutritional intervention. Capsules dominate current volume due to dosage precision and stability advantages over liquid formats, while powders represent the fastest-growing configuration as functional food and beverage brands incorporate phytoceramides into smoothie bases and collagen co-formulations. Wheat-derived sources retain the largest share of commercial supply, though sweet potato extraction is gaining manufacturing investment as allergen-free positioning commands retail premiums.
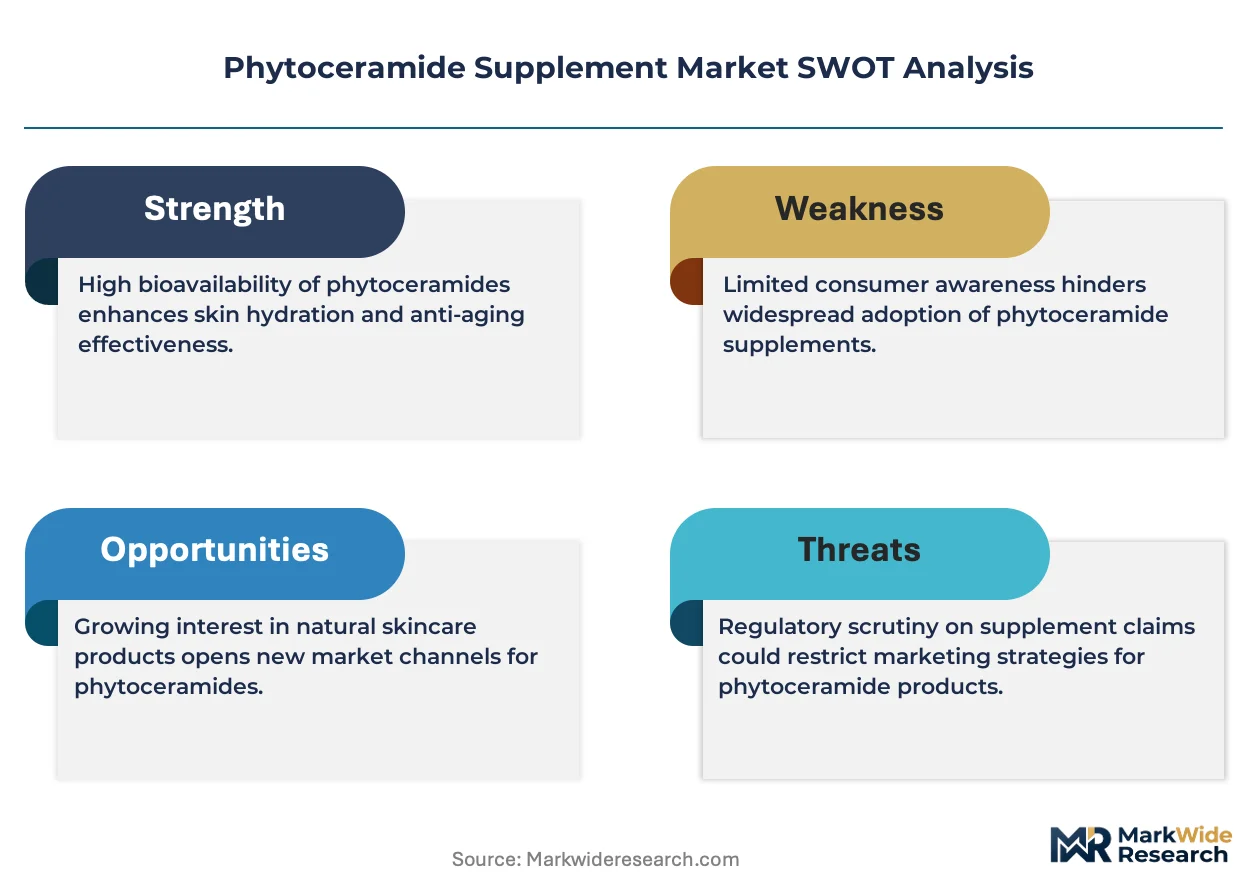
The FDA exercises oversight through DSHEA and New Dietary Ingredient notifications, requiring safety documentation for novel phytoceramide extraction methods before market entry. EFSA in Europe evaluates health claim substantiation under the Nutrition and Health Claims Regulation, constraining how brands communicate skin-moisture benefits to consumers. Japan's Ministry of Health, Labour and Welfare maintains FOSHU approval pathways that confer competitive advantage on ceramide products achieving functional-food status. Stakeholders must monitor evolving substantiation requirements for structure-function claims as regulatory scrutiny of ingestible beauty ingredients intensifies across major jurisdictions.
Market Dynamics
Topical-adjacent ingestible beauty is collapsing the historical boundary between dermatology and nutritional intervention, forcing suppliers to restructure around dual-channel distribution serving both aesthetic clinics and direct-to-consumer wellness platforms.
Growth Catalysts
- FOSHU Approval Pathway:Japan's Ministry of Health, Labour and Welfare confers competitive advantage on ceramide products achieving functional-food status, accelerating premium positioning in East Asian retail.
- Sweet Potato Extraction:Allergen-free sourcing commands retail premiums as manufacturers redirect capital from wheat-dependent supply chains toward tuber-derived glucosylceramides.
- DSHEA Framework:The FDA's structure-function claim pathway permits skin-moisture benefit communication without pharmaceutical registration, lowering market entry barriers for botanical ingredient suppliers.
Market Restraints
- Wheat Supply Concentration:Dominant sourcing from Triticum aestivum creates allergen-labeling liabilities and price volatility tied to agricultural commodity cycles.
- EFSA Health Claim Constraints:The Nutrition and Health Claims Regulation limits substantiated skin-moisture messaging to narrow, pre-approved language, compressing marketing differentiation.
- Collagen Co-Formulation Substitution:Established ingestible beauty ingredients with deeper clinical bibliography capture shelf space and consumer mindshare in functional beverage formulations.
Strategic Opportunities
- Latin American Middle-Class Penetration:Multi-level distribution networks access emerging wellness segments in Brazil and Mexico where dermatologist endorsement carries disproportionate purchasing influence.
- Powder Format Innovation:Functional food and beverage brands incorporate phytoceramides into smoothie bases, expanding beyond capsule-dominant configurations into daily consumption rituals.
- CE Marking Harmonization:Convergence toward unified European cosmetic-ingredient standards reduces regulatory fragmentation costs for cross-border supplement launches.
Industry Challenges
- New Dietary Ingredient Notification Timelines:The FDA's safety documentation requirements for novel extraction methods extend product development cycles by 12-18 months.
- Standardization of Glucosylceramide Assays:Inconsistent analytical methods across laboratories create batch-to-batch potency disputes between raw material suppliers and finished-goods manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytoceramide Supplement Market |
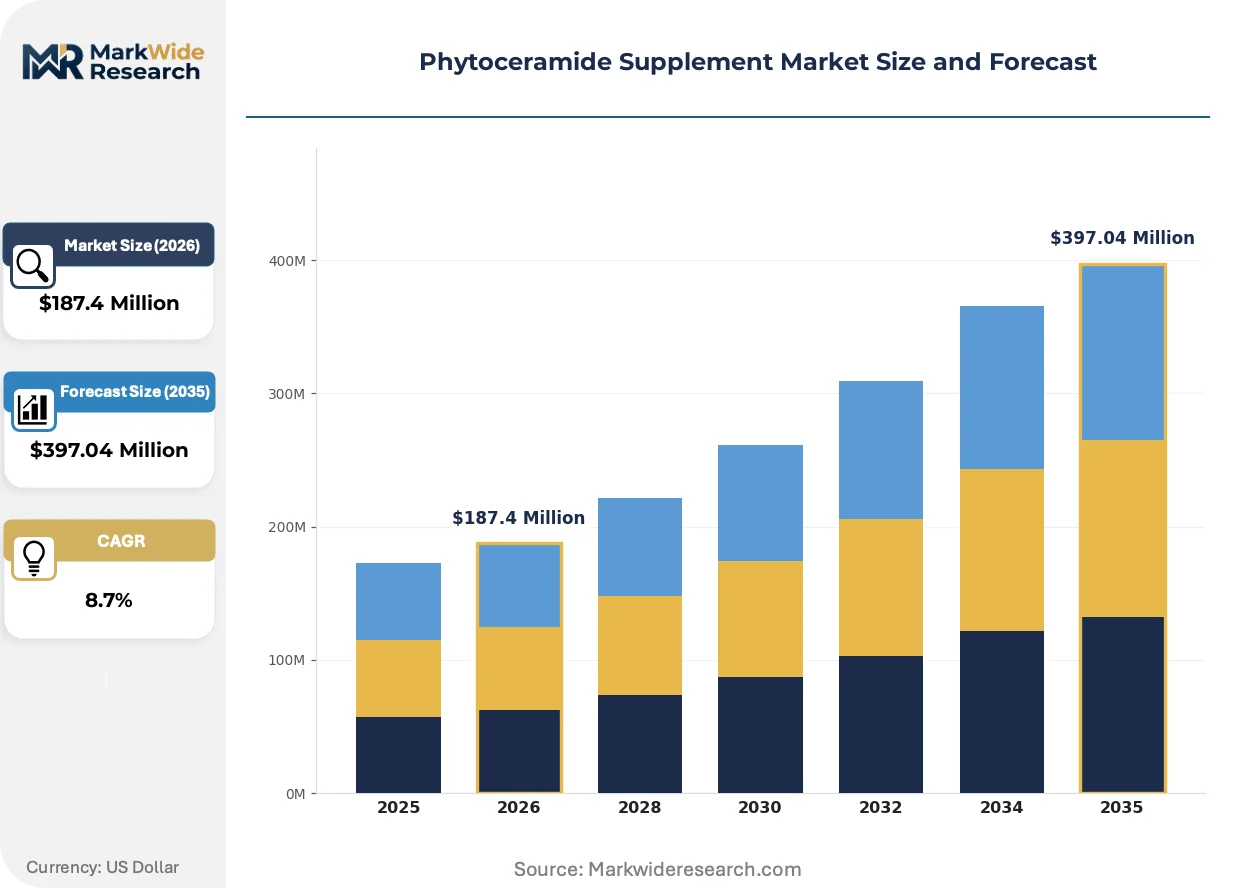
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Tablets, Liquids Source: Plant-Based, Wheat, Rice, Sweet Potato Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets End User: Health-Conscious Consumers, Athletes, Elderly, Skincare Enthusiasts |
| Companies Covered | NutraScience Labs, DSM Nutritional Products, Amway Corporation, Archer Daniels Midland Company, GNC Holdings, Inc., Herbalife Nutrition, Swisse Wellness Pty Ltd, NaturesAid Ltd., Healthy Origins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytoceramide Supplement Market Evolving Landscape
Encapsulation technology is compressing dosage volumes while preserving lipid stability, enabling phytoceramide integration into formats previously incompatible with oil-soluble actives.
Microencapsulation via spray-drying and liposomal delivery is miniaturizing particle sizes below 50 microns, permitting seamless suspension in aqueous beverage matrices without phase separation. Skincare enthusiasts adopting powder-based morning routines drive adoption velocity. This format expansion is compressing the historical capsule monopoly and fragmenting manufacturing equipment requirements across supplier tiers.
REACH registration deadlines for novel plant-derived lipids are tightening substance documentation requirements for wheat and rice extraction byproducts entering European cosmetic-supply chains. Manufacturers must submit extended safety data sets covering dermal sensitization and oral toxicity endpoints. Small-scale botanical extractors without dedicated regulatory affairs functions face compliance cost barriers that favor mid-cap suppliers with in-house toxicology capabilities.
Subscription-based replenishment models are displacing single-transaction retail purchases as the dominant acquisition channel for repeat phytoceramide consumers. Direct-to-consumer wellness brands capture lifetime value through personalized skin-assessment quizzes that algorithmically match ceramide dosage to self-reported hydration concerns. This behavioral shift concentrates most visibly in United States metropolitan markets where same-day delivery logistics support just-in-time supplement resupply.
Phytoceramide Supplement Market Segmentation
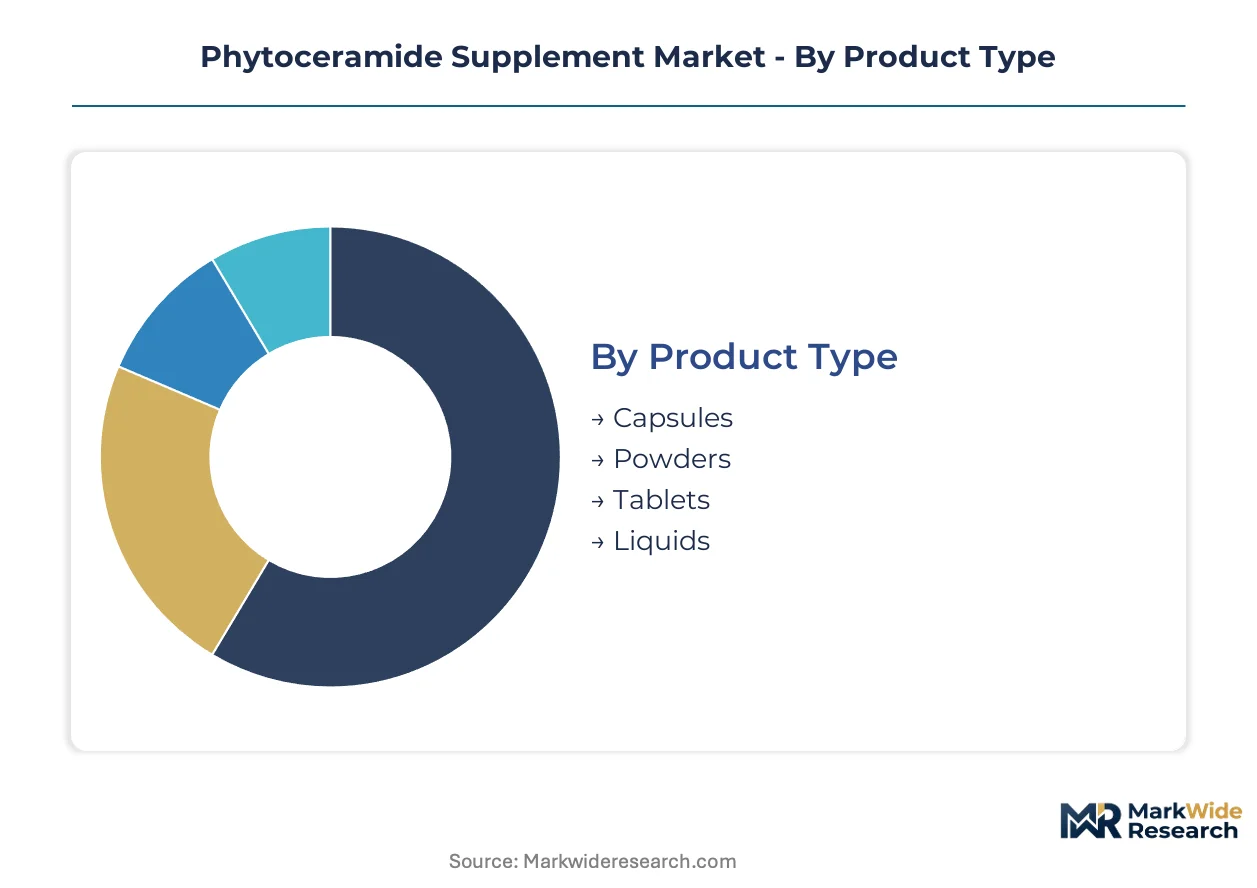
Phytoceramide supplement segmentation reveals how formulation chemistry, sourcing provenance, and channel economics fragment margin capture across distinct buyer workflows. Suppliers must align production assets with the specific consumption rituals and regulatory exposures embedded in each segment cluster.
Product Type:
Margin pools concentrate in formats that solve stability and dosing precision problems for finished-goods manufacturers.
- Capsules:Gelatin or vegetable-based shells encapsulate lipid-active phytoceramides in standardized doses, protecting glucosylceramides from oxidative degradation during shelf storage. United States direct-to-consumer wellness brands favor this configuration for subscription replenishment models requiring precise monthly dosing. Capsules hold installed capacity. Powders is rotating up the share rankings.
- Powders:Spray-dried or lyophilized phytoceramide concentrates enable seamless suspension in aqueous matrices, supporting integration into collagen co-formulations and functional beverage bases. Functional food brands in Japan and South Korea drive procurement volumes for FOSHU-eligible product lines. Powder format innovation is expanding most quickly as morning ritual consumption displaces pill-based regimens among skincare enthusiasts.
- Tablets:Compressed solid-dose forms offer cost-efficient manufacturing for mass-market retail positioning, though lipid binding challenges require specialized excipient formulations. European pharmacy chains stock tablet configurations for elderly consumers accustomed to solid-dose supplement routines.
- Liquids:Oil-based suspensions deliver phytoceramides in liposomal or micellar delivery systems, targeting pediatric or dysphagia-sensitive populations. Limited commercial traction reflects stability constraints and higher logistics costs for temperature-sensitive shipments.
Capsule infrastructure dominates current manufacturing footprints. Powder investments are accelerating fastest among contract manufacturers.
Source:
Supply concentration and allergen liability reshape margin structures across botanical extraction pathways.
- Plant-Based:Broad-spectrum botanical extracts containing mixed glucosylceramide profiles from unspecified vegetable matrices serve private-label manufacturers seeking cost-competitive positioning. Quality variability limits penetration into dermatologist-endorsed supplement lines.
- Wheat:Triticum aestivum-derived glucosylceramides retain the deepest clinical bibliography and established GRAS status in United States regulatory frameworks. Wheat supply concentration creates allergen-labeling liabilities and price volatility tied to agricultural commodity cycles. Wheat holds installed capacity. Sweet Potato is rotating up the share rankings.
- Rice:Oryza sativa extraction yields ceramide precursors with hypoallergenic positioning suitable for gluten-sensitive consumer segments. Japanese and South Korean manufacturers favor rice-derived sources for domestic functional food formulations.
- Sweet Potato:Ipomoea batatas tuber extraction delivers allergen-free glucosylceramides commanding retail premiums in clean-label positioning. Manufacturing investment is redirecting capital toward tuber-derived sources as wheat-dependent supply chains face EFSA scrutiny.
Wheat extraction infrastructure remains entrenched. Sweet potato capacity additions are climbing the fastest among alternative sourcing investments.
Distribution Channel:
Channel economics fragment based on customer acquisition costs and lifetime value capture mechanisms.
- Online Retail:Direct-to-consumer platforms leverage algorithmic skin-assessment quizzes to personalize phytoceramide dosage recommendations and lock in subscription replenishment. United States metropolitan markets concentrate same-day delivery logistics supporting just-in-time resupply. Online Retail holds installed capacity. Health Stores is rotating up the share rankings.
- Health Stores:Specialty retailers curate premium phytoceramide assortments with visible shelf positioning and staff consultation, bridging ingestible beauty education with transaction completion. Latin American multi-level distribution networks penetrate emerging middle-class wellness segments through health store partnerships.
- Pharmacies:Licensed drugstore channels require regulatory compliance documentation that filters out unstandardized suppliers, concentrating procurement among established pharmaceutical-grade manufacturers. European pharmacy chains enforce CE marking and extended safety data requirements.
- Supermarkets:Mass-market grocery placement demands price-competitive formulations and high-volume packaging configurations, compressing margins for finished-goods suppliers. Limited phytoceramide penetration reflects category education gaps among general merchandise buyers.
Online subscription models concentrate customer lifetime value. Health store partnerships are gaining share fastest in emerging market expansions.
End User:
Buyer archetype evolution is collapsing historical segment boundaries between general wellness and dermatological intervention.
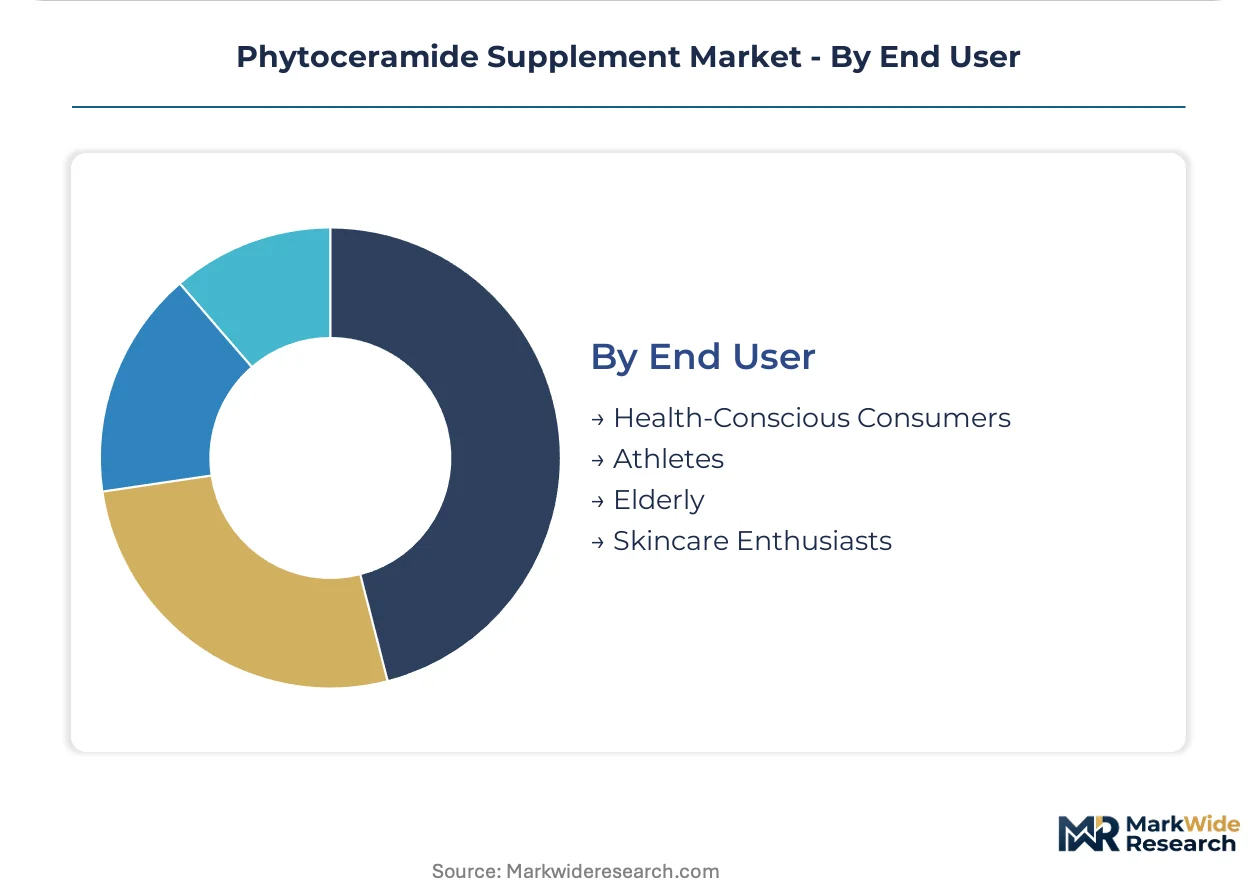
- Health-Conscious Consumers:Broad wellness seekers incorporate phytoceramides into multi-ingredient supplement stacks targeting systemic inflammation and general skin health maintenance. This segment faces share erosion as topical-adjacent ingestible beauty redefines category positioning.
- Athletes:Performance-focused consumers pursue phytoceramides for exercise-induced barrier stress recovery, though clinical substantiation lags behind collagen and electrolyte categories in sports nutrition. Powder formats align with pre- and post-workout beverage rituals.
- Elderly:Aging populations target ceramide supplementation for age-related epidermal thinning and moisture retention decline, driving pharmacy-channel preference for solid-dose familiarity. Japan's aging demographic supports sustained functional food demand.
- Skincare Enthusiasts:Aesthetic-conscious buyers bridge dermatological science with nutritional intervention, demanding clinically substantiated claims and premium sourcing transparency. Skincare enthusiasts is displacing historical dominance of general health-conscious consumers as the primary buyer archetype, commanding premium shelf positioning in United States direct-to-consumer channels.
General wellness consumers retain volume base. Skincare enthusiasts are climbing fastest in revenue contribution and margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skincare enthusiasts cluster disproportionately in United States metropolitan markets, where direct-to-consumer wellness brands and dermatologist-endorsed supplement lines command premium shelf positioning. Subscription-based replenishment models concentrate lifetime value capture in coastal cities with same-day delivery logistics.
United States
Direct-to-consumer wellness platforms and dermatology clinic partnerships drive procurement volumes for wheat-derived and sweet potato-sourced formulations. FDA DSHEA structure-function claim pathways permit skin-moisture benefit communication without pharmaceutical registration. New York and Los Angeles anchor premium positioning for subscription-based phytoceramide brands targeting skincare enthusiasts.
Japan
Aging demographics and functional food culture sustain demand for FOSHU-approved ceramide products in daily consumption rituals. Ministry of Health, Labour and Welfare approval pathways confer competitive advantage on products achieving functional-food status. Tokyo-Osaka corridor manufacturers dominate East Asian supply for rice-derived glucosylceramide formulations.
Germany
Pharmacy-channel preference for solid-dose supplements and extended safety documentation requirements filter procurement toward established pharmaceutical-grade suppliers. EFSA Nutrition and Health Claims Regulation constrains substantiated skin-moisture messaging to narrow pre-approved language. Bavaria and North Rhine-Westphalia concentrate contract manufacturing capacity for European private-label distribution.
South Korea
Beauty-from-within consumer culture and morning ritual consumption patterns accelerate powder format adoption in functional beverage applications. MFDS regulatory frameworks govern functional food labeling for ceramide-containing products. Seoul Capital Area brands lead collagen co-formulation innovation incorporating phytoceramides into smoothie bases.
Brazil
Emerging middle-class wellness segments and multi-level distribution networks penetrate Latin American markets where dermatologist endorsement carries disproportionate purchasing influence. ANVISA oversees dietary supplement registration and health claim substantiation requirements. São Paulo anchors regional headquarters for direct-selling organizations targeting skincare-conscious consumers.
Phytoceramide Supplement Market Competitive Landscape
Player mix skews toward biotechnology-derived ingredient suppliers and vertically integrated direct-selling organizations with captive distribution networks. Market structure concentrates margin capture among mid-cap specialists controlling extraction-to-encapsulation supply chains and multi-level marketing platforms accessing emerging middle-class segments. Three strategic archetypes dominate: biotechnology heritage suppliers of high-purity ceramide precursors, vertically controlled botanical extractors, and algorithmic direct-to-consumer wellness brands. Competitive dynamics center on backward integration into allergen-free sourcing and geographic expansion through health store partnerships.
Within the biotechnology heritage tier, DSM Nutritional Products exemplifies high-purity wheat-derived ceramide precursor supply to finished-goods manufacturers. Herbalife Nutrition occupies a position representing multi-level distribution penetration across Latin American and Southeast Asian emerging markets. Amway Corporation sits within the vertically integrated archetype, spanning botanical extraction through encapsulated finished products.
| Leading Market Players |
|---|
| NutraScience Labs |
| DSM Nutritional Products |
| Amway Corporation |
| Archer Daniels Midland Company |
| GNC Holdings, Inc. |
| Herbalife Nutrition |
| Swisse Wellness Pty Ltd |
| NaturesAid Ltd. |
| Healthy Origins |
| Others |
Value Network & Pricing Analysis
Sweet potato extraction replacing wheat-dependent supply chains simultaneously redistributes manufacturing geography toward East Asian tuber cultivation zones and compresses pricing premiums for allergen-free positioning as capacity scales.
Pricing Analysis
Encapsulation technology pricing gaps separate spray-dried microencapsulation formats from conventional oil-based suspensions and legacy gelatin capsules. Three-tier pricing structure across premium, standard, and economy levels reflects glucosylceramide concentration purity and FOSHU certification status. Pricing pressure stems from collagen co-formulation substitution in functional beverage channels. Skincare enthusiasts show lowest price sensitivity, while mass-market health-conscious consumers drive volume at compressed margins.
Supply Chain Analysis
Japan and South Korea anchor rice-derived glucosylceramide extraction for domestic FOSHU formulations, while the United States and Brazil concentrate wheat and sweet potato processing infrastructure. Raw material dependencies center on Triticum aestivum grain supply, Ipomoea batatas tuber harvests, and specialized liposomal delivery phospholipids. Supply chain risk hinges on single-source vulnerability in wheat gluten allergen labeling disputes. Distribution runs through direct-to-consumer subscription platforms and multi-level marketing networks penetrating Latin American middle-class segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against collagen co-formulation capture of ingestible beauty shelf space, requiring incumbents to differentiate through dermatological science positioning and clinical substantiation investment.
For Market Incumbents: Fortify supply chain control through backward integration into sweet potato cultivation partnerships in East Asia, eliminating wheat allergen liability while securing premium positioning. Deepen FOSHU certification portfolios to maintain functional-food status advantage against collagen substitution in Japanese and South Korean retail channels.
For New Entrants and Emerging Players: Algorithmic skin-assessment personalization represents an under-served service layer where incumbent direct-to-consumer brands rely on generic quiz templates. Penetrate Latin American health store partnerships in São Paulo and Mexico City where dermatologist endorsement carries disproportionate purchasing influence. Launch powder-format collagen co-formulations targeting morning ritual consumption patterns.
For Investors and Strategic Acquirers: The market sits at a format-transition phase that favors mid-cap specialists controlling extraction-to-encapsulation supply chains over pure-play ingredient suppliers. Long-term viability across the next decade rests on allergen-free sourcing certification and multi-level distribution network depth. Watch for FOSHU approval velocity as inflection indicator for East Asian functional-food positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Sweet Potato Sourcing Transition | Allergen-free positioning commands retail premiums as EFSA scrutiny intensifies wheat-labeling compliance. |
| Microencapsulation Capacity Expansion | Spray-drying investments enable seamless phytoceramide suspension in aqueous beverage matrices. |
| FOSHU Certification Pathway | Japan's Ministry of Health, Labour and Welfare approval confers functional-food competitive advantage. |
| Direct-to-Consumer Platform Launch | Algorithmic skin-assessment quizzes lock in subscription replenishment lifetime value capture. |
| Latin American Distribution Partnership | Multi-level networks penetrate Brazil and Mexico where dermatologist endorsement drives purchasing. |
Research Methodology
Initial hypotheses were tested against primary input from finished-goods formulation scientists, regulatory affairs specialists at botanical extractors, dermatology clinic procurement managers, and direct-to-consumer brand operations leads and refined through secondary validation against FDA New Dietary Ingredient notifications, EFSA health claim registers, Japan FOSHU approval databases, and customs trade records for glucosylceramide raw material flows. Bottom-up volume modeling triangulated against top-down market sizing across extraction source, format configuration, and channel economics.
Variance decomposition across the projection horizon isolates volume drivers by format type, sourcing provenance, end-user archetype, and regional regulatory cluster. CAGRs were derived from segment-level growth trajectory analysis incorporating FOSHU approval pipeline velocity, sweet potato cultivation capacity expansion timelines, and collagen co-formulation competitive substitution rates. Forecast inputs include powder format adoption curves in functional beverage applications and subscription replenishment model penetration in United States metropolitan markets.
Forecasts assume regulatory continuity in FDA DSHEA structure-function pathways, EFSA Nutrition and Health Claims Regulation enforcement, and Japan FOSHU approval frameworks; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in novel extraction method safety documentation timelines and functional-food certification velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Vegan Collagen Powder Market