
 Bee Pollen Supplements Market | 2026-2036
Bee Pollen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Bee Pollen Supplements Market Outlook
Plant-based protein alternatives is hardening competition against traditional whey formulations in sports nutrition aisles. NOW Foods leverages its manufacturing scale to occupy the mass-market capsule segment. Comvita anchors its position through Manuka honey cross-selling infrastructure in Australasia. Beekeeper's Naturals differentiates via direct-to-consumer subscription models targeting urban wellness demographics.
Bee pollen supplements consist of collected floral pollen processed into ingestible forms, typically containing 20-35% protein, 25-30% carbohydrates, and variable flavonoid profiles depending on botanical origin. Manufacturers employ freeze-drying or low-temperature dehydration to preserve enzymatic activity and bioactive compounds for immune support and energy metabolism applications. Capsules dominate volume through pharmacy and professional channel penetration, while powders capture margin in functional food blending applications. Online retail channels exhibit the fastest expansion trajectory, though health stores retain higher basket values through staff-assisted purchasing.
The FDA regulates bee pollen under dietary supplement provisions of DSHEA, requiring substantiated structure-function claims without pre-market approval, while EFSA novel food assessments govern EU market entry for non-traditional bee pollen sources. India's FSSAI enforces label declarations for allergen warnings and geographical origin tracking on imported apiary products. Stakeholders must monitor evolving pollinator health regulations that could constrain raw material availability and trigger supply chain restructuring.
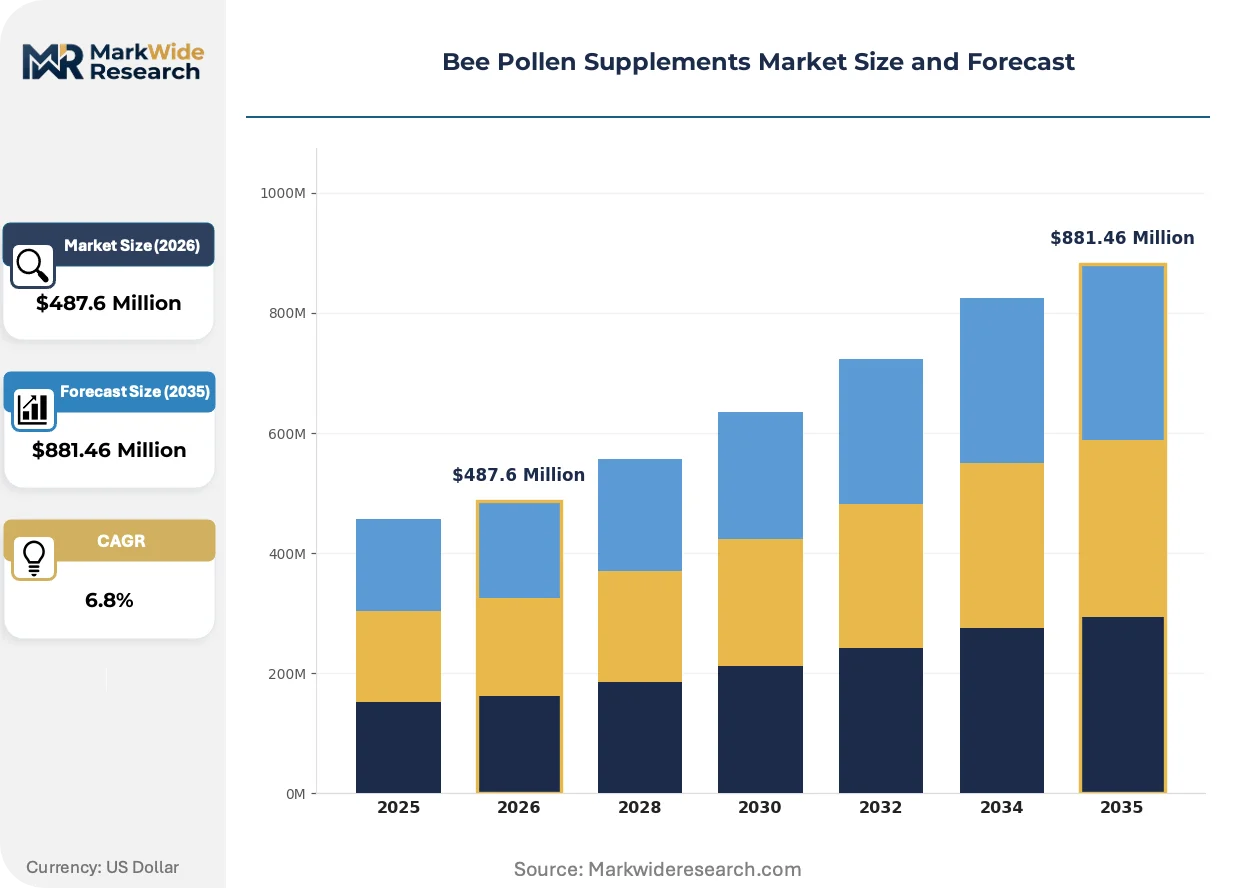
Market Dynamics
EU Novel Food Regulation assessments are fragmenting market entry timelines for non-traditional bee pollen sources, forcing manufacturers to build parallel compliance dossiers while fitness-driven protein demand pulls supply chains toward freeze-dried formats.
Growth Catalysts
- DSHEA framework flexibility:The FDA's structure-function claim pathway allows immune support and energy metabolism positioning without pre-market approval, accelerating US product launches.
- Freeze-drying technology maturation:Low-temperature dehydration preserves enzymatic bioactivity that heat processing destroys, enabling premium positioning in pharmacy channels.
- German natural health retail density:Concentrated health store networks in urban corridors sustain higher basket values through staff-assisted purchasing of origin-traceable products.
Market Restraints
- EFSA novel food assessment timelines:Extended safety evaluations for non-EU pollen sources create 18-24 month entry delays and capital lockup.
- Apiary supply concentration:Raw material availability concentrates in Mediterranean and Eastern European beekeeping cooperatives, exposing buyers to climate-induced harvest volatility.
- Plant protein substitution pressure:Pea and rice protein isolates capture sports nutrition shelf space with lower allergen labeling burdens and simpler supply chains.
Strategic Opportunities
- FSSAI import pathway formalization:India's allergen warning and geographical origin tracking mandates create first-mover advantage for compliant suppliers in emerging urban wellness markets.
- Direct-to-consumer subscription infrastructure:Urban wellness demographics demonstrate willingness to commit to recurring deliveries of traceable, single-origin formulations.
- Manuka honey cross-selling integration:Established Australasia distribution networks for therapeutic-grade honey products enable bundled pollen supplement penetration with minimal incremental channel cost.
Industry Challenges
- Botanical origin authentication complexity:Flavonoid profile verification requires mass spectrometry capabilities that mid-tier manufacturers lack in-house, forcing reliance on third-party laboratories with 6-8 week turnaround times.
- Pollinator health regulatory uncertainty:Evolving restrictions on neonicotinoid use and hive transportation rules threaten raw material availability and may force supply chain restructuring toward captive apiary partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bee Pollen Supplements Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Granules, Liquid Extracts End User: Fitness Enthusiasts, Health-Conscious Consumers, Nutritional Supplements Retailers, Athletes Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Stores Form: Organic, Raw, Blend, Processed |
| Companies Covered | YS Eco Bee Farms, NOW Foods, Beekeeper's Naturals, Swanson Health Products, Apis Flora, Manuka Health, Stakich, Comvita, Dabur India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bee Pollen Supplements Market Strategic Shifts
Processing technology convergence and regulatory fragmentation are redrawing competitive boundaries, with preservation methods and compliance infrastructure becoming primary differentiation vectors rather than raw material sourcing alone.
Freeze-drying is consolidating quality-tier segmentation by preserving heat-sensitive enzymes and flavonoid compounds that spray-drying degrades. Premium sports nutrition buyers now specify freeze-dried origin in procurement contracts. This technology compression is forcing mid-tier processors to upgrade capital equipment or retreat to commodity capsule segments.
EFSA novel food safety assessments are lengthening evaluation windows for pollen from non-EU botanical sources, creating competitive moats for established European suppliers. Manufacturers are responding by building dedicated regulatory affairs teams and pre-submission consultation budgets. Non-traditional origin products face 18-24 month delays versus 6-9 months for EU-sourced equivalents.
Subscription commerce is displacing health store replenishment among urban millennials and Gen Z wellness consumers. Direct-to-consumer platforms capture recurring revenue with origin-transparency features that retail packaging cannot match. This channel rotation is most visible in North American and Australian metropolitan markets where delivery infrastructure and credit-card subscription penetration are mature.
Bee Pollen Supplements Market Segmentation
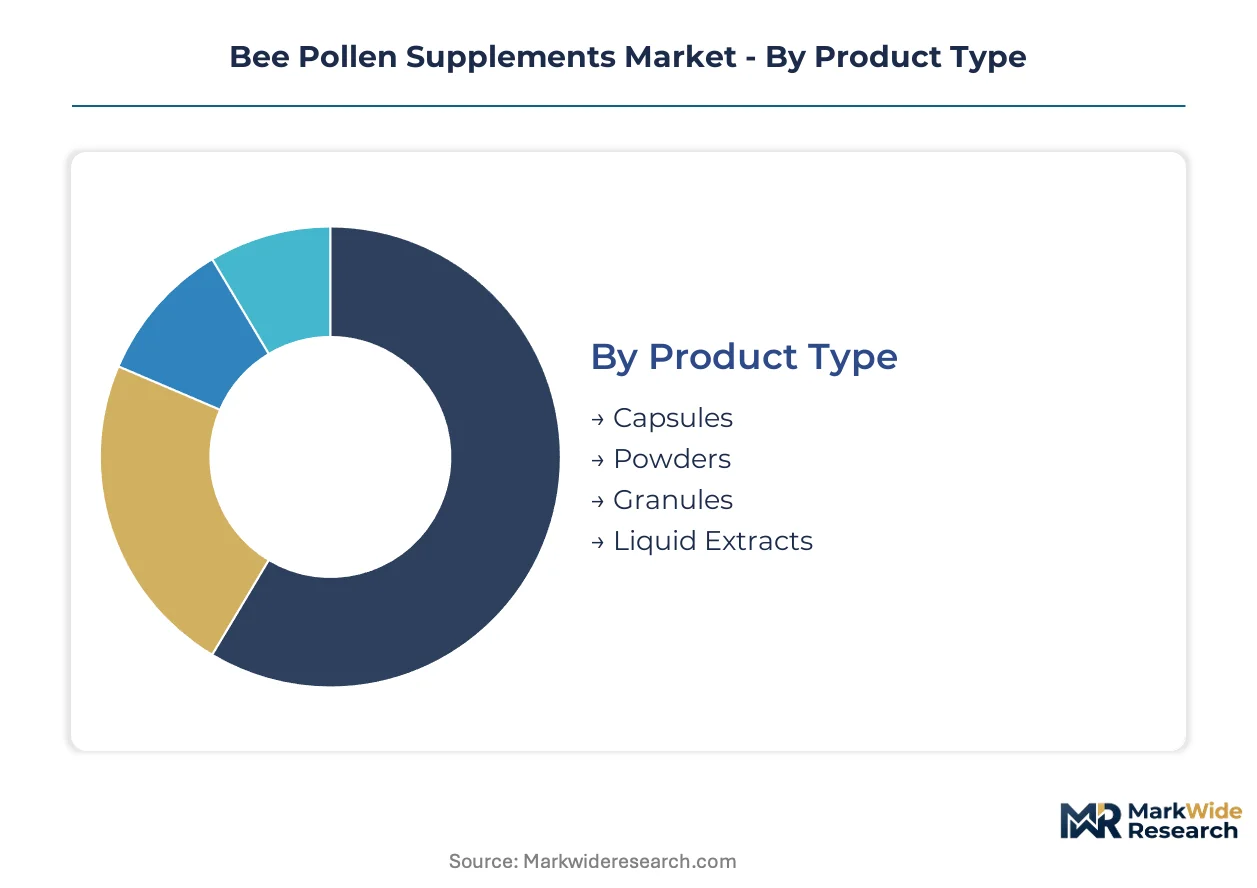
Bee pollen supplement segmentation reflects competing pressures between convenience-driven formats and bioactivity preservation. Manufacturers must align product architecture with channel-specific purchasing behaviors and end-user technical sophistication.
Product Type:
Processing technology defines competitive tiering, with thermal sensitivity and enzymatic preservation separating premium from commodity positioning.
- Capsules:Hard-shell gelatin or vegetable-based encapsulation delivers standardized 500-1000mg doses with extended shelf stability. Pharmacy and professional channels in Germany concentrate demand here, driven by practitioner recommendation protocols and precise dosing requirements.
- Powders:Fine-milled pollen enables functional food integration and smoothie applications, capturing margin in sports nutrition blending. Freeze-dried powders command premium positioning through retained enzymatic activity that heat-processed alternatives lose.
- Granules:Coarse, unprocessed pollen pellets appeal to purist consumers seeking minimal intervention. Direct-to-consumer subscription models in North American urban markets favor this format for perceived authenticity.
- Liquid Extracts:Alcohol or glycerin-based tinctures offer rapid absorption and flexible dosing. Health store staff-assisted purchasing in Australasia drives trial of this format.
Capsules lead on scale; powders lead on momentum.
End User:
Customer archetypes stratify by protein literacy, purchase frequency, and channel preference.
- Fitness Enthusiasts:Protein-alternative seekers with high formulation scrutiny and brand switching propensity. Sports nutrition retailers and online direct-to-consumer platforms capture this cohort through subscription infrastructure and origin transparency features.
- Health-Conscious Consumers:Broad wellness demographic prioritizing immune support and energy metabolism claims. Staff-assisted health store purchasing in German urban corridors sustains higher basket values for this segment.
- Nutritional Supplements Retailers:B2B procurement specialists managing inventory turnover and margin optimization. This segment demands consistent supply reliability and regulatory documentation for shelf placement.
- Athletes:Competitive and professional performers with anti-doping compliance requirements and batch testing needs. This niche commands premium pricing but requires third-party certification infrastructure.
Fitness enthusiasts lead on scale; athletes lead on margin expansion.
Distribution Channel:
Channel economics determine margin capture and customer acquisition cost structures.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with subscription automation and origin-traceable storytelling. Urban millennial and Gen Z wellness demographics in North America and Australia demonstrate highest recurring delivery commitment rates.
- Health Stores:Staff-assisted specialty retailers with trained personnel guiding product selection. German natural health product retail corridors sustain this channel's relevance through higher basket values and trust-based purchasing.
- Supermarkets:Mass-market placement with limited staff interaction and price-competitive positioning. Capsule formats dominate here due to shelf stability and impulse purchase compatibility.
- Specialty Stores:Sports nutrition and organic-focused retailers with curated assortments and enthusiast clientele. Powder formats gain traction in this channel through functional food cross-merchandising.
Online retail leads on momentum; health stores lead on basket value retention.
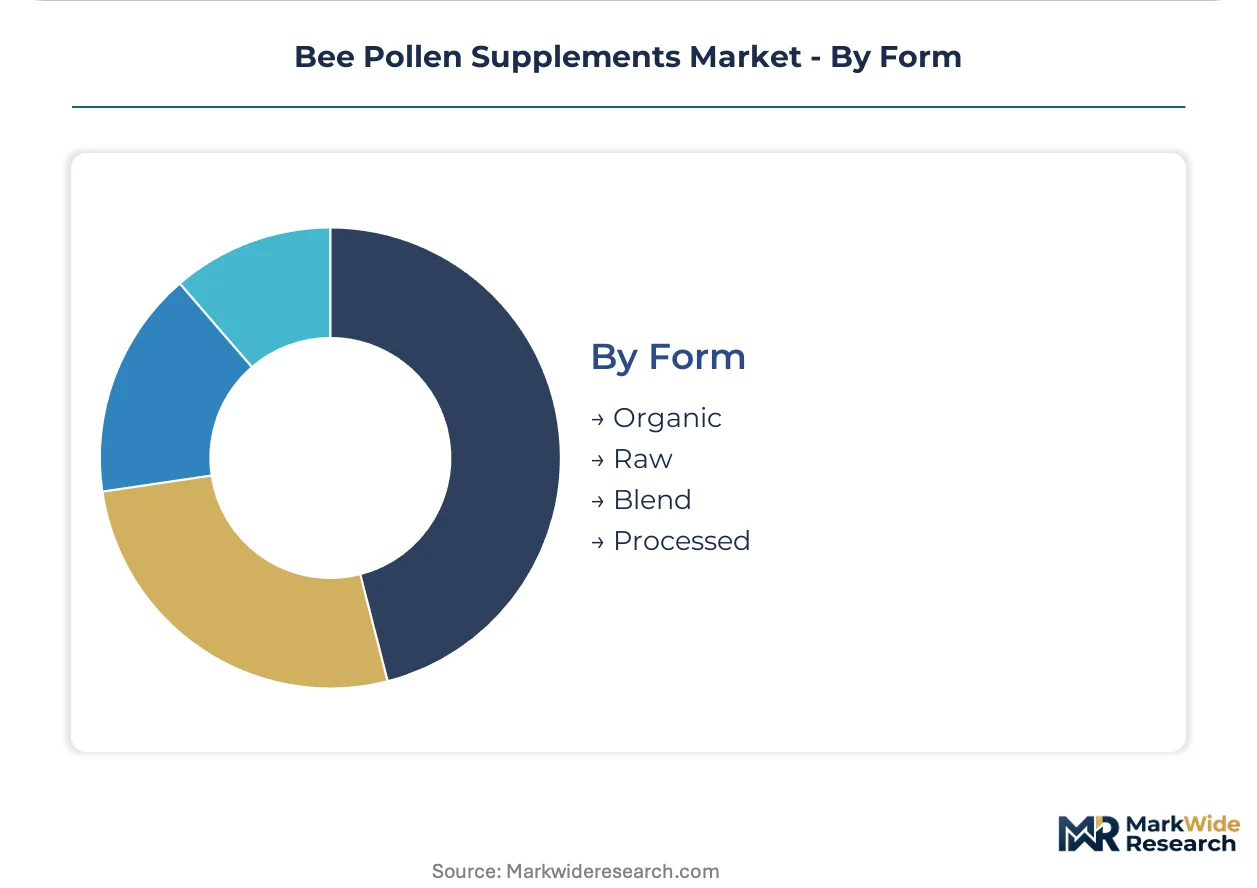
Form:
Certification and processing intensity create pricing architecture and supply chain complexity tiers.
- Organic:Certified apiary operations with prohibited synthetic inputs and documented hive management protocols. EU Novel Food Regulation compliance requirements and EFSA assessments govern market entry for non-EU organic sources.
- Raw:Unheated, minimally processed pollen retaining full enzymatic and flavonoid profiles. Freeze-drying technology preserves bioactivity that spray-drying degrades, enabling premium pharmacy channel positioning.
- Blend:Pollen combined with propolis, royal jelly, or other apiary derivatives for synergistic positioning. Manuka honey cross-selling infrastructure in Australasia enables bundled penetration with minimal incremental channel cost.
- Processed:Heat-treated or spray-dried products with extended shelf life and lower price positioning. Commodity capsule manufacturing scales through this form for mass-market penetration.
Raw leads on premium pricing; organic leads on regulatory moat construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German natural health retail corridors concentrate European demand through practitioner-guided purchasing of origin-traceable products. Fitness-driven protein alternatives pull supply chains toward freeze-dried formats across multiple jurisdictions.
United States
Fitness enthusiasts and urban wellness demographics drive capsule and powder adoption through direct-to-consumer subscription platforms. The FDA's DSHEA framework permits structure-function immune support claims without pre-market approval, accelerating product launches. California and New York metro areas anchor e-commerce penetration with recurring delivery infrastructure for traceable formulations.
Germany
Health-conscious consumers sustain staff-assisted purchasing in dense urban health store networks with higher basket values. EFSA novel food assessments govern entry for non-EU pollen sources, creating 18-24 month compliance timelines. Bavaria and North Rhine-Westphalia concentrate natural product retail corridors where origin documentation commands premium positioning.
India
Urban wellness markets in Mumbai and Delhi-NCR demonstrate appetite for imported apiary products with allergen-transparent labeling. FSSAI mandates geographical origin tracking and allergen warnings on imported supplements, creating first-mover advantage for compliant suppliers. Maharashtra and Karnataka lead emerging channel development through pharmacy and online retail expansion.
Australia
Manuka honey cross-selling infrastructure enables bundled pollen supplement penetration with minimal incremental channel cost. TGA therapeutic goods oversight applies to higher-dose formulations while standard supplements operate under complementary medicine provisions. Sydney and Melbourne metropolitan markets drive subscription commerce adoption among millennial wellness consumers.
China
Traditional medicine integration sustains demand for granule and liquid extract formats in coastal urban centers. NMPA dietary supplement registration requirements create extended approval timelines for imported products versus domestic manufacturing. Yangtze River Delta and Pearl River Delta clusters concentrate processing capacity and e-commerce distribution infrastructure.
Bee Pollen Supplements Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers build parallel compliance dossiers for multi-jurisdiction entry. The vendor base stratifies across three tiers: mass-market capsule processors, premium freeze-dried specialists, and direct-to-consumer subscription platforms. Strategic archetypes include scale-driven pharmaceutical-channel suppliers, origin-traceable boutique formulators, and honey-cross-selling Australasia networks. M&A activity targets captive apiary partnerships, while technology licensing agreements spread freeze-drying capabilities beyond legacy equipment holders.
Among US-based operators, NOW Foods occupies a position exemplifying mass-market manufacturing scale, while Beekeeper's Naturals anchors the direct-to-consumer subscription archetype. Comvita represents the honey-cross-selling infrastructure model rooted in Australasia distribution networks. These three patterns illustrate how competitive positioning increasingly depends on channel-specific customer acquisition structures rather than raw material sourcing alone.
| Leading Market Players |
|---|
| YS Eco Bee Farms |
| NOW Foods |
| Beekeeper's Naturals |
| Swanson Health Products |
| Apis Flora |
| Manuka Health |
| Stakich |
| Comvita |
| Dabur India |
| Others |
Value Chain & Pricing Dynamics
Family-owned Mediterranean apiary cooperatives anchor raw material sourcing, their fragmented ownership structure limiting price-setting leverage while preserving traditional hive management practices that command certification premiums in German pharmacy channels.
Pricing Analysis
Input-cost pass-through from freeze-drying equipment and botanical origin authentication runs unevenly across tiered pricing structures. Premium-mid-economy pricing differentiation separates freeze-dried pharmacy-grade capsules from spray-dried mass-market alternatives, with certification grade and enzymatic bioactivity preservation driving spreads. Cost compression in commodity capsule tiers intensifies as plant protein substitutes capture sports nutrition shelf space. Nutritional supplement retailers exhibit highest price sensitivity due to inventory turnover pressures, while direct-to-consumer subscription buyers accept recurring premiums for single-origin traceability.
Supply Chain Analysis
EU Novel Food Regulation assessments reshape sourcing toward EU-member apiary operations with established EFSA dossiers. Raw material flows concentrate in Spain, Romania, and Bulgaria, where beekeeping cooperatives supply floral pollen with documented botanical provenance. Supply chains draw from hive equipment, low-temperature dehydration machinery, and third-party mass spectrometry laboratories for flavonoid verification. Single-source vulnerability concentrates in Mediterranean climate-dependent harvest cycles. Distribution runs through pharmacy wholesalers, health store networks, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where EFSA novel food compliance timelines in Europe stretch 18-24 months versus DSHEA structure-function flexibility in the United States, creating launch-cost differentials that favor US-first product strategies.
For Market Incumbents: Anticipate plant protein substitution pressure by securing captive apiary partnerships in Romania and Bulgaria before pollinator health regulations constrain hive transportation. Invest in in-house mass spectrometry capabilities to reduce botanical origin authentication turnaround from 6-8 weeks to under 14 days, defending margin position against mid-tier competitors forced into third-party laboratory reliance.
For New Entrants and Emerging Players: FSSAI import pathway formalization in India opens a window for compliant suppliers in Mumbai and Delhi-NCR pharmacy expansion. Target urban wellness demographics through allergen-transparent labeling and geographical origin tracking that incumbent exporters have delayed implementing. Pursue direct-to-consumer subscription infrastructure as the go-to-market angle, capturing recurring revenue before health store networks consolidate shelf access.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier freeze-drying equipment operators lacking regulatory affairs capabilities. Long-term viability hinges on captive supply integration as climate volatility and neonicotinoid restrictions reshape raw material availability. Watch pollinator health regulatory announcements as the inflection signal indicating supply chain restructuring urgency and acquisition premium timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Apiary Partnership | Secures climate-resilient pollen supply ahead of EU hive transportation restrictions. |
| In-House Mass Spectrometry | Reduces flavonoid authentication delays from 6-8 weeks to under 14 days. |
| Direct-to-Consumer Subscription | Captures recurring revenue from urban millennials seeking origin transparency. |
| FSSAI Compliance Pre-Investment | Creates first-mover positioning in Mumbai and Delhi-NCR pharmacy channels. |
| Freeze-Drying Capacity Expansion | Preserves enzymatic bioactivity that spray-drying degrades for pharmacy-tier pricing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with apiary cooperative managers, freeze-drying equipment manufacturers, pharmacy procurement directors, health store category buyers, and regulatory affairs consultants with secondary validation against EFSA novel food assessment databases, FSSAI import notification records, FDA DSHEA structure-function claim filings, and customs trade data for apiary product flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across product type, end user, distribution channel, and certification form dimensions.
Historical reference periods anchored the projection horizon through observed EFSA assessment timeline distributions and DSHEA launch velocity patterns. The analytical framework modeled bee pollen supplement demand across processing technology, customer archetype, channel economics, and regulatory compliance tier segments. CAGRs derived from segment-level growth rate distributions weighted by observed channel expansion trajectories in North American and Australian subscription commerce. Forecast inputs incorporated freeze-drying equipment capacity buildouts and pollinator health regulatory proposal tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt neonicotinoid bans or hive disease outbreaks. Projections reflect assumptions regarding EFSA assessment duration stability and DSHEA enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Brazil Whey Protein Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Aquatic Feed Supplement Market