
 South Africa Collagen Peptides Market | 2026-2036
South Africa Collagen Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Collagen Peptides Market Insights
Subscription-based replenishment programs for collagen powders is broadening recurring revenue streams beyond one-time retail purchases. Gelita AG leverages its global manufacturing scale to supply pharmaceutical-grade hydrolyzed collagen to South African compounders. Rousselot anchors its position through backward integration into bovine raw material sourcing across Southern African abattoir networks. PB Leiner differentiates by specializing in marine-derived peptide fractions for premium cosmetic formulators.
Collagen peptides are short-chain amino acid sequences produced through controlled enzymatic hydrolysis of native collagen, typically yielding molecular weights between 2,000 and 5,000 Daltons for optimal intestinal absorption. Their primary commercial purpose centers on delivering functional protein fortification for joint health, skin elasticity, and muscle recovery applications. Hydrolyzed collagen dominates value generation due to its solubility profile and established clinical validation, while marine-sourced variants command premium positioning in cosmetics. Nutraceuticals represents the fastest-growing end-user channel as gym-affiliated consumers and aging demographics expand peptide consumption routines.
South Africa's Department of Health enforces strict health claim substantiation under the Foodstuffs, Cosmetics and Disinfectants Act, while the South African Health Products Regulatory Authority (SAHPRA) scrutinizes collagen-containing complementary medicines for quality and safety. The Consumer Protection Act further mandates transparent ingredient disclosure, pushing suppliers toward certified clean-label sourcing and third-party testing protocols. Stakeholders must monitor evolving SAHPRA guidance on peptide-based health product classifications to preempt registration bottlenecks and maintain shelf access.
Market Dynamics
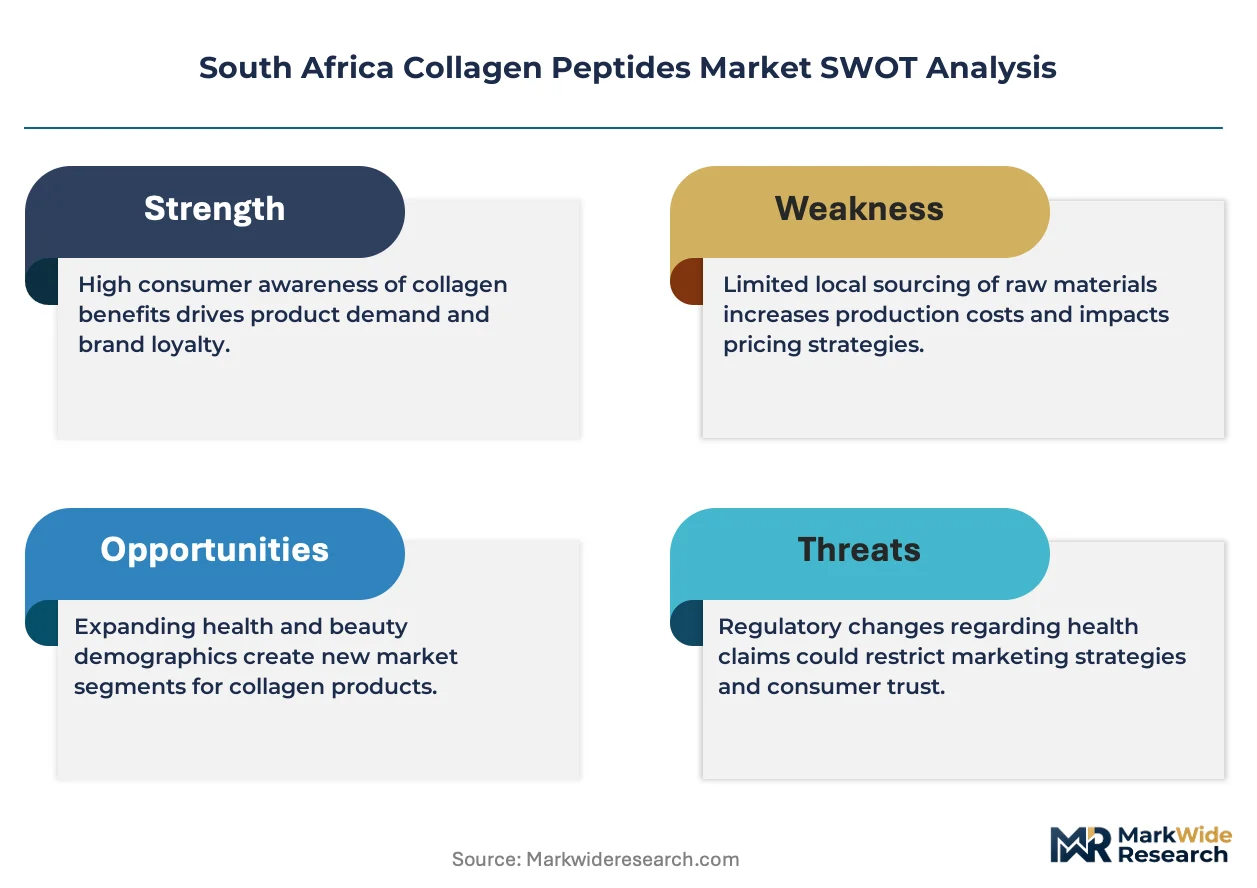
The South Africa collagen peptides market is being reshaped by tightening regulatory scrutiny over health claims substantiation, compelling manufacturers to invest in clinical validation infrastructure and third-party certification protocols to maintain shelf access under the Foodstuffs, Cosmetics and Disinfectants Act.
Growth Catalysts
- Sports nutrition expansion:Gym-affiliated consumers in Gauteng province are integrating collagen peptides into daily recovery routines, creating sustained demand pull from Johannesburg's fitness retail clusters.
- SAHPRA quality frameworks:The South African Health Products Regulatory Authority's enforcement of peptide-based product classifications is professionalizing supply chains and filtering out substandard imports.
- Anti-aging demographic shift:Aging consumers in Pretoria and surrounding urban centers are prioritizing skin elasticity and joint health applications, expanding the addressable consumer base beyond athletes.
Market Restraints
- Bovine raw material concentration:Dependence on Southern African abattoir networks for collagen sourcing creates vulnerability to livestock supply fluctuations and veterinary regulatory changes.
- Marine peptide cost structure:Wild-caught fish stock variability and cold-chain requirements for marine-derived fractions inflate input costs relative to bovine alternatives.
- Import substitution pressure:Local compounders face margin compression from pharmaceutical-grade hydrolyzed collagen imports leveraging global manufacturing scale advantages.
Strategic Opportunities
- Western Cape coastal access:Underpenetrated Cape Town and surrounding regions offer expansion potential for marine-sourced peptide distribution through specialty cosmetic formulators.
- Subscription channel innovation:Direct-to-consumer replenishment platforms bypass traditional retail markups and capture recurring revenue from health-conscious households.
- Clean-label certification convergence:The Consumer Protection Act's transparency mandates create competitive differentiation for suppliers achieving third-party testing protocols ahead of compliance deadlines.
Industry Challenges
- Bioanalytical skill scarcity:Limited local expertise in peptide molecular weight verification and enzymatic hydrolysis quality control constrains domestic manufacturing scale-up.
- Registration timeline friction:Evolving SAHPRA guidance on complementary medicine classifications creates uncertainty in product launch scheduling and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Collagen Peptides Market |
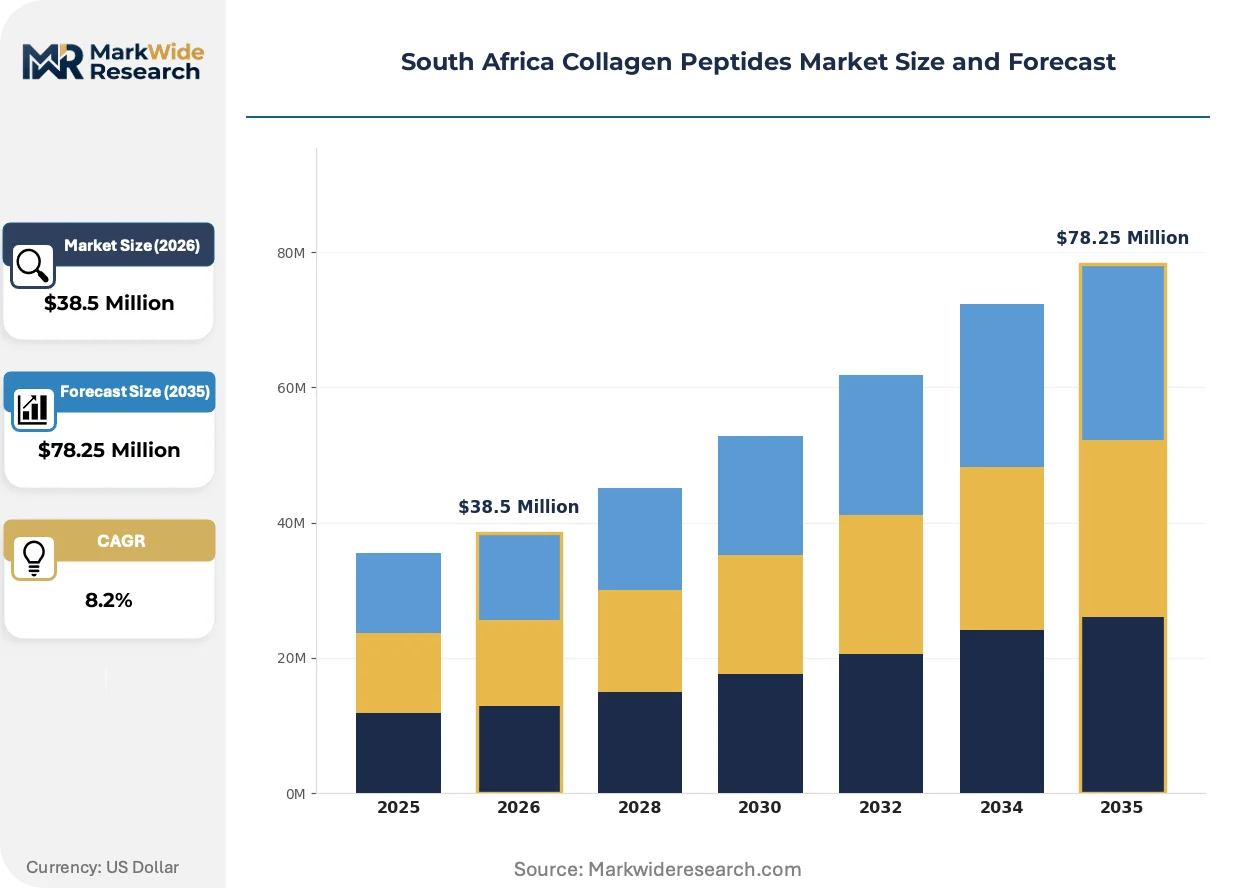
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $78.25 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Bone Broth, Collagen Snacks End User: Food Industry, Cosmetics, Nutraceuticals, Pharmaceuticals Source: Bovine, Porcine, Marine, Vegan Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Tessenderlo Group, Nitta Gelatin Inc., Gelita AG, Vital Proteins LLC, PB Leiner, Rousselot (Darling Ingredients), Amicogen Inc., Nippi Inc., Weishardt Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Collagen Peptides Market Trends and Innovations
Enzymatic hydrolysis optimization and marine sourcing diversification are actively reconfiguring competitive advantage in South Africa's collagen peptide landscape, while regulatory compliance automation and subscription commerce reshape go-to-market economics.
Precision enzymatic hydrolysis technology is converging with pharmaceutical-grade quality standards to enable tighter molecular weight control between 2,000 and 5,000 Daltons. Local compounders serving nutraceutical manufacturers are adopting these systems to meet SAHPRA bioavailability substantiation requirements. This convergence is compressing the validation timeline for new product registrations and raising barriers for uncertified competitors.
The Foodstuffs, Cosmetics and Disinfectants Act's tightened labeling requirements are forcing suppliers to restructure quality assurance departments around documentary evidence protocols. Manufacturers must now maintain batch-specific absorption studies to support functional claims on packaging. Cosmetic formulators in Gauteng are responding by consolidating supplier relationships toward vertically integrated partners with captive analytical capabilities.
Health-conscious consumers are abandoning intermittent retail purchasing in favor of automated replenishment programs tied to usage cycles. Specialty e-commerce platforms and gym-affiliated distributors in Johannesburg and Pretoria are capturing this behavioral shift through personalized dosing schedules. This pattern is most pronounced among aging demographics managing chronic joint health regimens, where adherence tracking drives subscription loyalty.
South Africa Collagen Peptides Market Segmentation
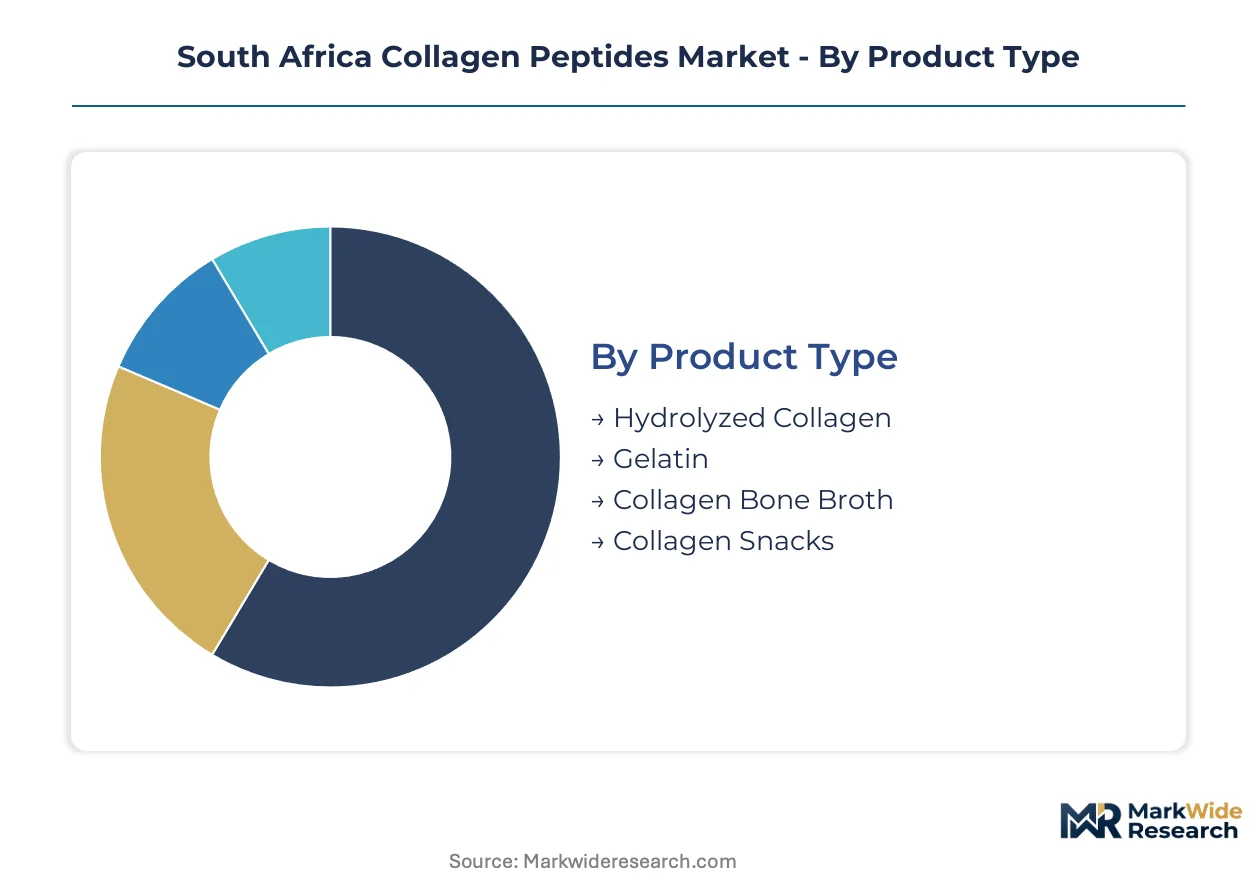
Segmentation reveals how collagen peptide suppliers must align product specifications with distinct buyer priorities across South Africa's fragmented health and wellness channels. Each dimension carries unique regulatory, pricing, and distribution implications that shape competitive strategy.
Product Type:
Buyers select collagen formats based on solubility requirements, dosage convenience, and intended application environment.
- Hydrolyzed Collagen:Enzymatically cleaved to 2,000-5,000 Dalton molecular weights for optimal intestinal absorption. Gauteng's sports nutrition retailers and aging consumers in Pretoria drive concentrated demand for unflavored powder formats that blend into beverages.
- Gelatin:Partially hydrolyzed collagen with gelling functionality retained. Food manufacturers in Johannesburg's bakery and confectionery clusters source food-grade gelatin for texture modification in premium product lines.
- Collagen Bone Broth:Traditional extraction yielding broader peptide fractions with mineral co-nutrients. Health-conscious households in Cape Town's wellness-oriented suburbs favor ready-to-consume liquid formats for perceived whole-food authenticity.
- Collagen Snacks:Functional food formats incorporating collagen into bars, gummies, and fortified items. Convenience-seeking urban professionals across Durban and Port Elizabeth purchase single-serve options for on-the-go protein supplementation.
Hydrolyzed collagen leads on scale; collagen snacks lead on momentum.
End User:
Application-specific regulatory pathways and formulation expertise requirements create distinct supplier-customer dynamics.
- Nutraceuticals:SAHPRA-registered complementary medicines and sports supplements requiring bioavailability substantiation. Johannesburg's gym-affiliated distribution networks and direct-to-consumer subscription platforms represent the steepest expansion trajectory for peptide consumption.
- Cosmetics:Topical and ingestible beauty formulations demanding low-molecular-weight marine peptides for skin elasticity claims. Specialty formulators in Cape Town and Sandton prioritize certified clean-label sourcing to satisfy the Consumer Protection Act's transparency mandates.
- Food Industry:Functional fortification of beverages, dairy alternatives, and baked goods. Major South African food manufacturers integrate collagen for protein enrichment in premium product tiers targeting health-positioned retail shelves.
- Pharmaceuticals:Excipient and active ingredient applications meeting pharmaceutical-grade specifications. Compounders serving hospital and clinic procurement channels require batch-specific documentation for SAHPRA quality frameworks.
Nutraceuticals commands volume concentration; cosmetics captures premium pricing power.
Source:
Raw material provenance determines cost structure, religious dietary acceptability, and sustainability positioning in South African consumer markets.
- Bovine:Derived from Southern African cattle abattoir networks. Domestic supply chain control supports cost competitiveness for mass-market hydrolyzed collagen serving Gauteng's retail channels.
- Marine:Wild-caught and aquaculture fish processing byproducts. Cold-chain requirements and stock variability inflate input costs, restricting penetration to premium cosmetic and specialty nutraceutical segments in coastal Western Cape markets.
- Porcine:Pigskin and bone-derived collagen excluded from halal and kosher certification. Limited addressable market constrains commercial scale despite favorable enzymatic hydrolysis yield profiles.
- Vegan:Fermentation-derived or plant-based collagen alternatives using genetically modified yeast or bacterial platforms. Emerging positioning for ethically motivated consumers in Cape Town's environmentally conscious demographic clusters.
Bovine dominates supply security; marine dominates margin expansion.
Distribution Channel:
Channel selection reflects buyer journey stage, subscription preference, and trust requirements for health claim verification.
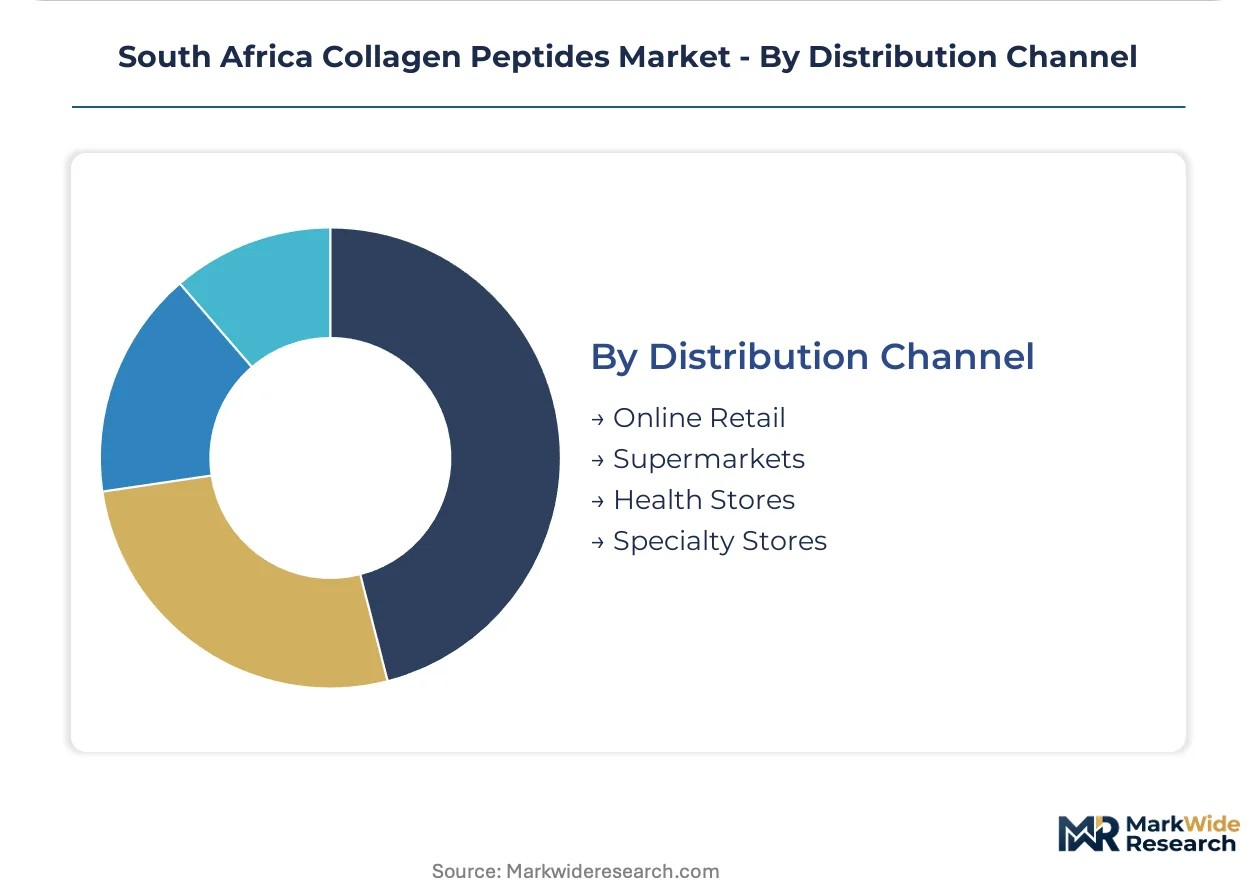
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription replenishment programs. Automated reordering systems capture recurring revenue from Johannesburg and Pretoria households managing chronic joint health regimens.
- Health Stores:Specialty retailers with trained staff capable of explaining bioavailability differences and SAHPRA registration status. Discerning consumers seek third-party certified products with documentary evidence of quality testing.
- Supermarkets:Mass-market retail chains stocking mainstream hydrolyzed collagen powders and fortified foods. Shelf placement competition intensifies as private-label entrants compress branded supplier margins.
- Specialty Stores:Cosmetic boutiques, gym pro shops, and professional clinic dispensaries. Curated assortments targeting specific end-use applications command premium positioning through expert consultation.
Online retail leads on customer acquisition efficiency; health stores lead on conversion rate for premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's collagen peptide demand diverges sharply from neighboring markets, with Gauteng province absorbing volumes comparable to entire national markets in the SADC region while coastal Western Cape channels premium marine-sourced fractions.
Gauteng Province
Johannesburg's fitness retail clusters and Pretoria's aging demographic households drive concentrated consumption of hydrolyzed collagen powders for joint health and muscle recovery applications. The Department of Health's tightened labeling requirements under the Foodstuffs, Cosmetics and Disinfectants Act compel local distributors to maintain batch-specific bioavailability documentation. Sandton's specialty cosmetic boutiques and gym pro shops curate premium peptide assortments targeting adherence-focused subscription customers.
Western Cape
Cape Town's wellness-oriented suburbs favor ready-to-consume collagen bone broth formats and marine-derived peptide cosmetics for perceived whole-food authenticity and clean-label positioning. SAHPRA scrutiny of complementary medicine classifications creates registration friction for new entrants targeting the coastal beauty channel. Stellenbosch and surrounding wine region wellness retreats incorporate ingestible collagen into hospitality offerings, expanding B2B procurement relationships.
KwaZulu-Natal
Durban's convenience-seeking urban professionals purchase single-serve collagen snack formats for on-the-go protein supplementation between work and coastal recreational activities. The Consumer Protection Act's transparency mandates push Durban-based health stores toward third-party certified suppliers with documentary evidence protocols. Umhlanga's medical tourism facilities source pharmaceutical-grade hydrolyzed collagen for post-procedure recovery protocols.
Eastern Cape
Port Elizabeth's emerging middle-class households demonstrate rising trial rates for fortified food applications as major South African food manufacturers extend premium product tiers into secondary metros. Local compounders serving the region face margin compression from pharmaceutical-grade imports leveraging global manufacturing scale. Gqeberha's retail pharmacy chains expand dedicated wellness sections to capture migrating demand from traditional supermarkets.
South Africa Collagen Peptides Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hydrolyzed collagen powders consolidating around established nutraceutical suppliers while marine peptide cosmetics fragment among specialty formulators. The vendor base organizes into three strategic archetypes: global ingredient suppliers leveraging captive raw material sourcing, regional compounders serving SAHPRA-registered complementary medicine channels, and direct-to-consumer platforms capturing subscription replenishment economics. Dominant competitive moves center on backward integration into Southern African abattoir networks and certification convergence ahead of Consumer Protection Act compliance deadlines.
Within the global supplier tier, Gelita AG and Rousselot exemplify scale-driven positioning through pharmaceutical-grade hydrolyzed collagen supply relationships with South African compounders. PB Leiner occupies a specialist position focused on marine-derived peptide fractions for premium cosmetic formulators in coastal markets. These three entities anchor the competitive structure by representing divergent raw material strategies—bovine concentration versus marine diversification—while navigating common SAHPRA registration requirements and Department of Health labeling enforcement.
| Leading Market Players |
|---|
| Tessenderlo Group |
| Nitta Gelatin Inc. |
| Gelita AG |
| Vital Proteins LLC |
| PB Leiner |
| Rousselot (Darling Ingredients) |
| Amicogen Inc. |
| Nippi Inc. |
| Weishardt Group |
| Others |
Pricing and Supply Chain Analysis
Clean-label certification mandates under South Africa's Consumer Protection Act gate qualified supply and premium-tier pricing access, forcing compounders to absorb third-party testing costs or surrender shelf position to verified competitors. This regulatory filter concentrates pricing power among SAHPRA-registered suppliers with captive analytical capabilities while compressing margins for uncertified importers.
Pricing Analysis
Capacity additions in Brazil and Argentina are reshaping price floors for bovine-derived hydrolyzed collagen entering South African ports, intensifying competition against domestic compounders. Pricing stratifies across pharmaceutical-grade, nutraceutical-grade, and food-grade tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in the standard tier is intensifying because import substitution pressure from global manufacturers leverages scale advantages. Mass-market retailers demonstrate highest price sensitivity, while cosmetic formulators in Sandton and Cape Town accept premiums for marine-sourced fractions with documented molecular weight verification.
Supply Chain Analysis
Dual-sourcing requirements from Johannesburg's nutraceutical manufacturers mandate multi-supplier qualification across Brazilian, Argentine, and domestic Southern African abattoir networks to mitigate livestock supply volatility. Raw material dependencies center on cattle hide and bone inputs, wild-caught fish processing byproducts, and enzymatic hydrolysis reagents. Single-source vulnerability persists in marine peptide cold-chain logistics through Durban and Cape Town ports. Distribution runs through compounder-to-manufacturer relationships for pharmaceutical-grade supply, with direct-to-consumer platforms capturing subscription replenishment economics in Gauteng households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's collagen peptide market functions as a regulatory compounder, where SAHPRA's evolving guidance on peptide-based health product classifications creates demand for compliance-capable suppliers. The Department of Health's tightened labeling enforcement under the Foodstuffs, Cosmetics and Disinfectants Act rewards early certification investment with shelf access advantages.
For Market Incumbents: Anticipate margin compression from pharmaceutical-grade hydrolyzed collagen imports by securing backward integration into Southern African abattoir networks and accelerating SAHPRA registration timelines for complementary medicine classifications. Prioritize certification convergence ahead of Consumer Protection Act compliance deadlines to defend position against private-label entrants. For New Entrants and Emerging Players: Cape Town's wellness-oriented suburbs represent an underserved buyer archetype for ready-to-consume collagen bone broth formats and marine-derived peptide cosmetics with clean-label positioning. Western Cape coastal access offers white-space expansion through specialty cosmetic formulators, with direct-to-consumer replenishment platforms as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders lacking SAHPRA-registered complementary medicine infrastructure but possessing captive analytical capabilities. Long-term viability centers on acquisition targets with enzymatic hydrolysis quality control expertise and established relationships with Gauteng gym-affiliated distribution networks. Watch for SAHPRA guidance finalization on peptide classifications as the inflection signal for registration bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Acceleration | Early compliance with peptide-based complementary medicine classifications secures shelf access ahead of enforcement tightening. |
| Backward Integration into Abattoir Networks | Captive supply of bovine raw materials insulates margin pressure from Argentine and Brazilian import competition. |
| Marine Sourcing Diversification | Western Cape coastal access enables premium positioning in cosmetic formulator channels with wild-caught fish stock partnerships. |
| Subscription Platform Development | Automated replenishment systems capture recurring revenue from Johannesburg and Pretoria aging demographics managing joint health regimens. |
| Clean-Label Certification Investment | Third-party testing protocols ahead of Consumer Protection Act deadlines differentiate suppliers in Sandton specialty retail channels. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and stakeholder interviews — were reconciled to construct this analysis. Primary interviews with SAHPRA registration consultants, compounder quality control directors, and Gauteng gym pro shop buyers were cross-validated against secondary sources including SAHPRA complementary medicine registers, South African customs import records, and Foodstuffs, Cosmetics and Disinfectants Act enforcement bulletins. Bottom-up demand modeling from end-user segments was triangulated against top-down supply capacity assessments across Southern African abattoir networks and global hydrolyzed collagen manufacturers.
Data-stream reconciliation employed a segmented analytical framework across product type, end user, source, and distribution channel dimensions over the projection horizon. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory milestone impacts. Forecast inputs incorporated enzymatic hydrolysis capacity expansion timelines, SAHPRA registration pipeline velocity, and subscription commerce penetration rates in Johannesburg and Pretoria metropolitan areas.
Underlying measurement precision varies by segment; hydrolyzed collagen powders and nutraceutical end-use carry tighter precision than emerging vegan collagen alternatives. Forecasts reflect assumptions regarding SAHPRA guidance stability, livestock supply continuity in Southern African abattoir networks, and cold-chain infrastructure reliability for marine peptide imports. Deviation in SAHPRA's final peptide classification framework or Department of Health labeling enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
US Ketones Market