
 Enteral Nutrition Market | 2026-2036
Enteral Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Enteral Nutrition Market Analysis
ISO 13485 certification is collapsing the competitive field for enteral device and formula suppliers, as hospitals and GPOs now mandate quality management system validation before contract eligibility. Abbott Laboratories leverages its vertically integrated nutrition science platform to sustain formulary dominance across North American health systems. Fresenius Kabi competes through specialized parenteral-to-enteral transition protocols that anchor its clinical nutrition franchise. Nestle Health Science differentiates via disease-specific formulation R&D, occupying premium positions in oncology and metabolic care segments.
Enteral nutrition comprises liquid nutrient formulations delivered through nasogastric, gastrostomy, or jejunostomy tubes to patients with functional gastrointestinal tracts who cannot achieve adequate oral intake. Standard polymeric formulas contain intact proteins, complex carbohydrates, and long-chain triglycerides requiring normal digestive capacity, while elemental formulations provide predigested macronutrients for compromised absorption. Disease-specific formulations command the highest margin pools due to clinical evidence requirements and prescriber loyalty. Pump-delivered continuous feeding dominates acute care settings where precise rate control prevents aspiration, though bolus feeding sustains growth in homecare as patients seek autonomy from mechanical dependence.
The FDA regulates enteral formulas as medical foods or tube-feeding products depending on labeling claims, while the EU Medical Device Regulation reclassifies enteral delivery pumps and sets new post-market surveillance obligations. Homecare reimbursement frameworks from CMS in the United States directly shape patient transition velocity from hospital to outpatient feeding protocols. Stakeholders must monitor evolving payer evidence requirements for disease-specific indications and anticipate how regulatory convergence between medical food and device categories will reshape compliance investment priorities.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while simultaneously elevating quality certification barriers, forcing formula and device manufacturers to restructure commercial operations around GPO compliance rather than traditional physician detailing.
Growth Catalysts
- Post-acute care expansion:Skilled nursing facilities and home health agencies in the United States are extending enteral feeding protocols beyond hospital discharge, creating sustained demand for ambulatory pump systems and pre-mixed formula portfolios.
- ISO 13485 mandates:Group purchasing organizations now require quality management system validation as a contract prerequisite, filtering out uncertified suppliers and concentrating volume among validated manufacturers.
- Elemental formula innovation:Predigested macronutrient formulations for malabsorption syndromes are capturing prescriber loyalty through demonstrated clinical outcomes in oncology and critical care settings.
Market Restraints
- Aluminum contamination thresholds:FDA medical food guidance imposes strict elemental impurity limits that elevate raw material screening costs and disqualify certain mineral premix suppliers.
- Single-source pump motor dependency:Precision stepper motors for enteral delivery devices concentrate among Japanese and German component houses, exposing assemblers to allocation risk during semiconductor shortages.
- Oral nutrition supplement substitution:Palatable high-protein beverages for dysphagia patients reduce tube-feeding necessity in early-stage neurological conditions, compressing addressable volume for standard polymeric formulas.
Strategic Opportunities
- Homecare reimbursement optimization:CMS durable medical equipment fee schedule revisions create arbitrage potential for suppliers who structure rental-to-purchase transitions around coverage determination timelines.
- Disease-specific formulation white space:Hepatic encephalopathy and pulmonary failure represent underdeveloped indication areas where clinical evidence investment could establish prescriber preference before competitor entry.
- Smart pump connectivity convergence:Integration of enteral delivery systems with electronic health record platforms and wireless inventory management is opening subscription revenue streams distinct from hardware sales.
Industry Challenges
- Clinical nutrition specialist scarcity:Registered dietitians with enteral protocol expertise are concentrated in academic medical centers, limiting staffing for community hospital and homecare program expansion.
- EU MDR transition timelines:Enteral delivery pump reclassification under the Medical Device Regulation demands extensive clinical evidence packages that compress R&D budgets and delay product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enteral Nutrition Market |
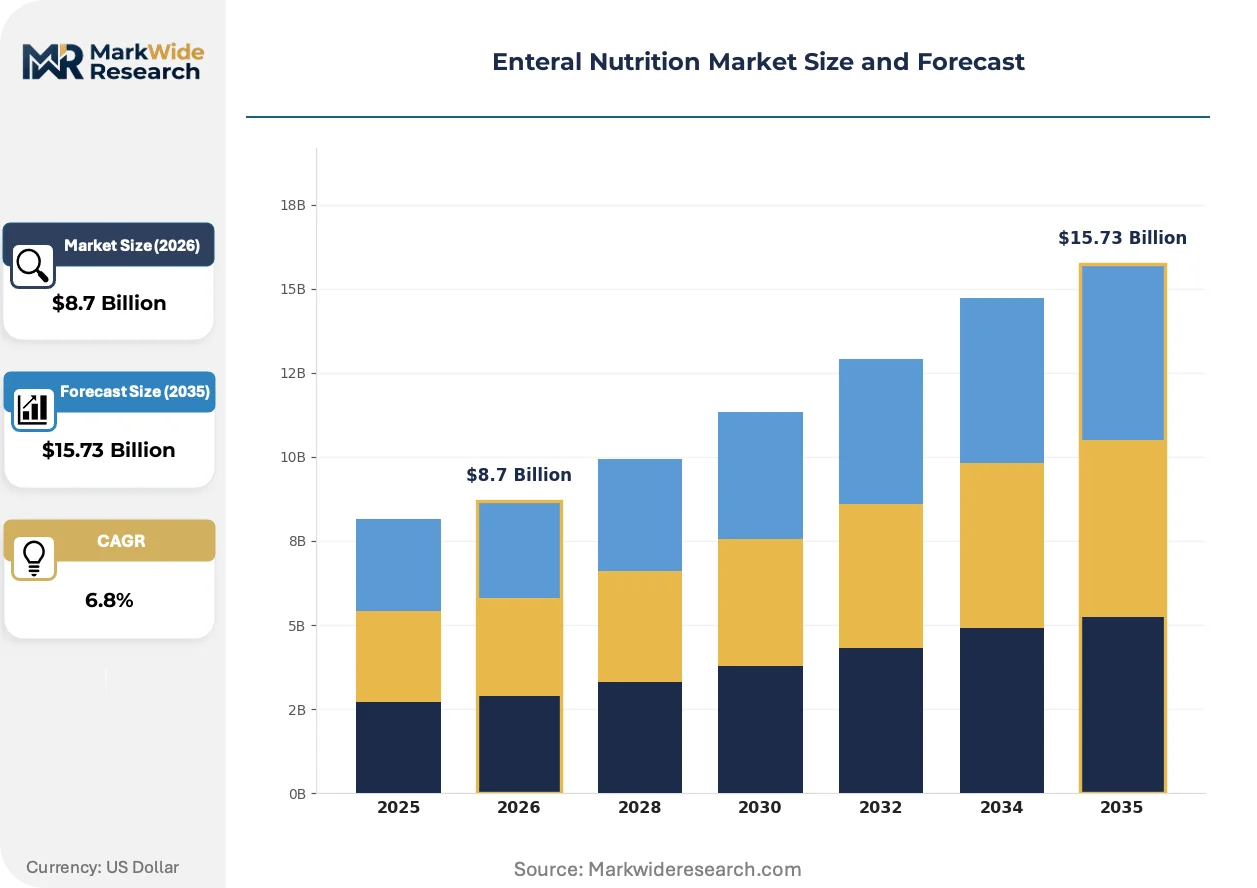
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Semi-Elemental, Elemental, Disease-Specific Delivery Mode: Bolus Feeding, Continuous Feeding, Intermittent Feeding, Pump-Delivered End User: Hospitals, Homecare, Long-Term Care Facilities, Specialty Clinics Application: Critical Care, Gastroenterology, Oncology, Pediatrics |
| Companies Covered | Abbott Laboratories, Nestle Health Science, Danone Nutricia, Fresenius Kabi, B. Braun SE, Baxter International, Reckitt Benckiser, Otsuka Pharmaceutical, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enteral Nutrition Market Emerging Trajectories
Digital integration and formulation precision are converging to transform how enteral nutrition is prescribed, monitored, and reimbursed, with connectivity and personalization displacing one-size-fits-all protocols across care settings.
Closed-loop enteral feeding systems incorporating real-time gastric residual volume sensors and automated rate adjustment algorithms are decomposing the traditional nurse-mediated monitoring model. Intensive care units in tertiary hospitals are piloting these platforms to reduce aspiration events and staffing burden. The technology is decomposing established workflow patterns and compressing demand for conventional pump alarms and manual documentation.
The FDA's updated medical food labeling requirements are mandating quantitative substantiation for structure-function claims, forcing reformulation of legacy products and retirement of unsupported indications. Manufacturers must now maintain clinical trial records equivalent to dietary supplement New Dietary Ingredient notifications. Disease-specific oncology and metabolic formulas face the steepest compliance investment given their historical reliance on practitioner belief rather than published evidence.
Hospital supply chain directors are consolidating enteral formula purchasing through integrated delivery networks that bypass traditional distributor markups. IDN-level contracts now specify formulary exclusivity in exchange for volume commitments and consignment inventory arrangements. This concentration is most advanced in the United States, where health system mergers have created regional purchasing entities with sufficient scale to dictate terms to multinational suppliers.
Enteral Nutrition Market Segmentation
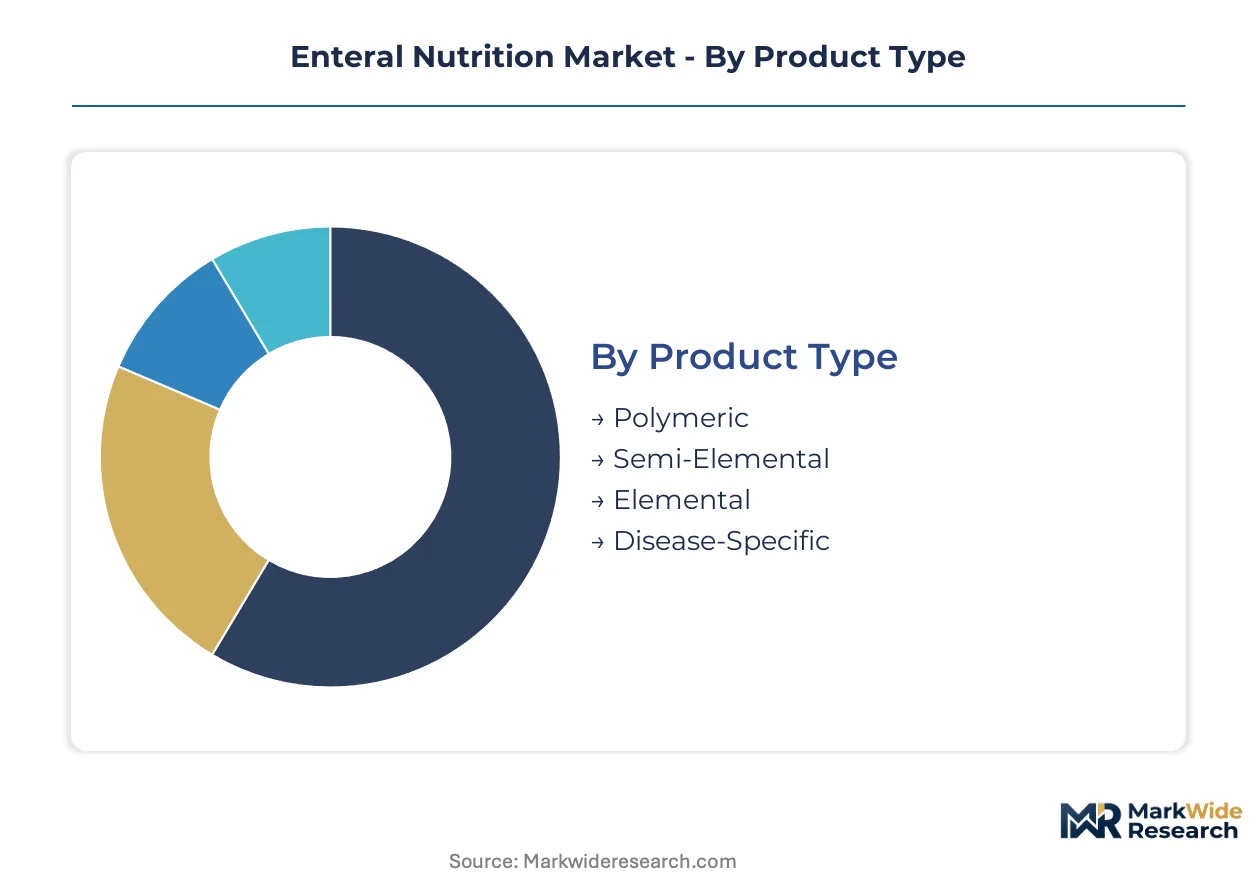
Enteral nutrition segmentation reveals distinct margin architectures across formulation complexity and care setting intensity. Product chemistry and delivery modality determine reimbursement tiering, while end-user concentration shapes procurement leverage and contract structure.
Product Type:
Disease-specific formulations command the steepest margin pools due to clinical evidence requirements and prescriber lock-in, while commodity polymeric products compete on manufacturing scale.
- Polymeric:Intact proteins, complex carbohydrates, and long-chain triglycerides requiring normal digestive capacity. Hospital procurement in the United States concentrates volume here for standard ICU protocols, though GPO consolidation is compressing per-unit margins.
- Disease-Specific:Oncology, hepatic, pulmonary, and renal formulations with condition-adjusted macronutrient profiles. Prescriber loyalty in academic medical centers sustains premium positioning despite FDA substantiation mandates for structure-function claims.
- Semi-Elemental:Partially hydrolyzed proteins and medium-chain triglycerides for compromised absorption. Intermediate pricing tier serves transitional patients.
- Elemental:Predigested macronutrients in peptide and free amino acid form. Malabsorption syndromes and short bowel cases drive niche demand.
The dominant share belongs to Polymeric, while Disease-Specific is closing the gap fastest.
Delivery Mode:
Acute care settings prioritize precision control that prevents aspiration events, whereas homecare patients trade accuracy for mechanical autonomy.
- Pump-Delivered:Programmable enteral feeding pumps with rate control and alarm systems. United States tertiary hospitals anchor demand through ICU protocols requiring continuous gastric residual monitoring.
- Bolus Feeding:Gravity or syringe-based intermittent delivery without mechanical dependence. Homecare expansion in post-acute discharge programs is expanding volume fastest as patients seek mobility.
- Continuous Feeding:24-hour nutrient delivery via pump or gravity. Standard for critical care tolerance building.
- Intermittent Feeding:Scheduled feeding cycles mimicking normal meal patterns. Long-term care facilities favor this for circadian rhythm preservation.
Pump-Delivered retains the largest installed base, though Bolus Feeding is expanding most quickly in ambulatory settings.
End User:
Procurement sophistication varies sharply across settings, with integrated delivery networks in acute care demanding quality certifications that filter supplier eligibility.
- Hospitals:Acute care facilities with ICU, step-down, and general medical units. ISO 13485 mandates from GPOs now gate contract participation, concentrating volume among validated manufacturers.
- Homecare:Durable medical equipment suppliers and home health agencies managing post-discharge feeding. CMS reimbursement timelines directly shape patient transition velocity and rental-to-purchase economics.
- Long-Term Care Facilities:Skilled nursing and assisted living operators with stable chronic populations. Lower acuity tolerates simpler delivery modes.
- Specialty Clinics:Outpatient gastroenterology and oncology infusion centers. Disease-specific formula prescribing concentrates in these settings.
Hospitals command the greatest purchasing leverage, while Homecare is gaining share fastest as post-acute protocols extend beyond discharge.
Application:
Clinical evidence requirements and prescriber specialization create distinct competitive moats across indication areas.
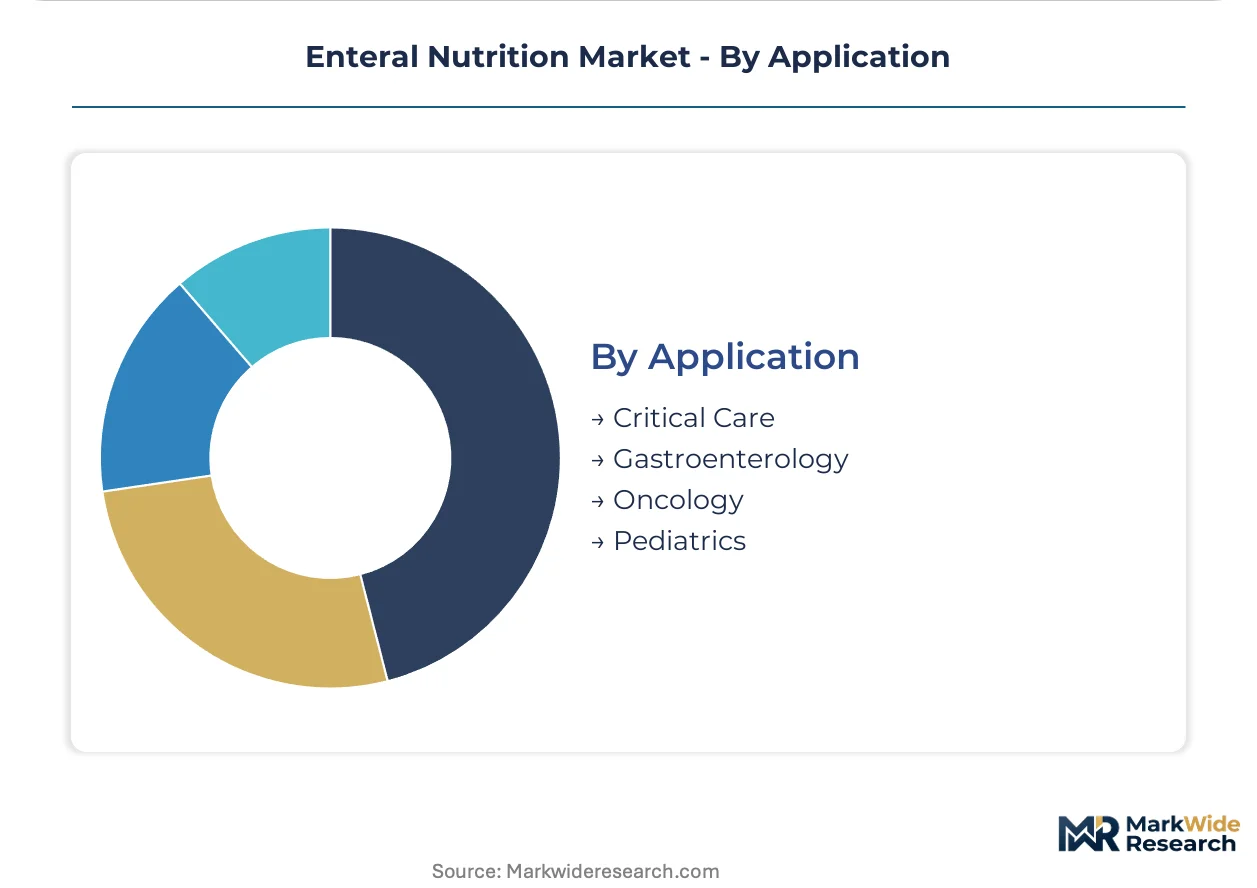
- Critical Care:ICU and step-down unit patients with temporary enteral access needs. Closed-loop feeding systems with automated rate adjustment are piloting in United States academic centers to reduce aspiration events.
- Oncology:Cancer patients with treatment-induced mucositis or obstruction. Disease-specific formulations with immune-modulating nutrients sustain premium positioning despite formulary pressure.
- Gastroenterology:Inflammatory bowel disease, malabsorption, and motility disorders. Elemental and semi-elemental products dominate this indication.
- Pediatrics:Neonatal and pediatric populations with congenital anomalies or metabolic disorders. Specialized formulation requirements and caregiver training needs elevate service intensity.
Critical Care generates the highest absolute volume, while Oncology is climbing the fastest on disease-specific formulation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy design is steering enteral nutrition procurement patterns across major markets, with government health programs and private payer frameworks determining patient access velocity and supplier contract structures.
United States
Post-acute care expansion through Medicare Advantage plans is extending enteral feeding protocols beyond hospital discharge into skilled nursing and home health settings. The FDA's updated medical food labeling requirements impose quantitative substantiation standards for structure-function claims, forcing reformulation of legacy products. The Cleveland Clinic and Mayo Clinic anchor clinical nutrition research clusters where disease-specific formulation protocols are developed and disseminated to regional health systems.
Germany
Aging demographics and statutory health insurance coverage for homecare nutrition are sustaining demand for ambulatory pump systems and pre-mixed formulas. The EU Medical Device Regulation reclassifies enteral delivery pumps and mandates extensive post-market surveillance obligations, compressing product refresh cycles. The Rhine-Ruhr metropolitan region concentrates medical device manufacturing competence, with component suppliers and assemblers clustering around Düsseldorf and Cologne.
Japan
Long-term care insurance expansion for elderly populations with dysphagia is broadening the addressable patient base for tube-feeding products. METI guidelines on medical device quality management align with ISO 13485 standards, filtering supplier eligibility for public hospital contracts. The Kansai region around Osaka hosts specialized clinical nutrition research institutes where elemental formulation protocols for malabsorption syndromes are refined.
China
Hospital infrastructure investment in tier-two and tier-three cities is expanding ICU bed capacity and associated enteral nutrition procurement volumes. NMPA medical food registration pathways are converging toward evidence-based claim substantiation requirements similar to FDA standards. The Yangtze River Delta medical device manufacturing corridor near Shanghai is attracting multinational suppliers establishing localized pump assembly and formula production operations.
Brazil
Private health insurance penetration growth is accelerating demand for disease-specific formulations in oncology and critical care segments. ANVISA medical food regulations are evolving toward stricter clinical evidence requirements for premium positioning claims. The São Paulo metropolitan area concentrates specialty clinic networks and hospital procurement decision-making for the Mercosur region, with distributors maintaining consignment inventory arrangements for high-volume accounts.
Enteral Nutrition Market Vendor Landscape
Player mix skews toward vertically integrated nutrition science conglomerates with pharmaceutical-grade manufacturing infrastructure and quality certification depth. Market structure concentrates volume among five to seven multinational suppliers holding ISO 13485 validation and GPO contract eligibility, while regional formulators compete on price for standard polymeric segments. Strategic archetypes include science-platform conglomerates leveraging R&D scale, clinical nutrition specialists with parenteral-to-enteral transition expertise, and dairy-derived ingredient houses with backward integration into protein sourcing. Competitive moves center on disease-specific formulation portfolio expansion and homecare reimbursement pathway optimization.
Among the science-platform conglomerates, Abbott Laboratories and Nestle Health Science occupy positions defined by vertically integrated nutrition research infrastructure and formulary dominance across North American health systems. Fresenius Kabi represents the clinical nutrition specialist archetype with parenteral-to-enteral transition protocol expertise. These three entities exemplify how quality certification depth and reimbursement pathway knowledge create defensive positioning against price-competitive regional suppliers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestle Health Science |
| Danone Nutricia |
| Fresenius Kabi |
| B. Braun SE |
| Baxter International |
| Reckitt Benckiser |
| Otsuka Pharmaceutical |
| FrieslandCampina |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates contract eligibility and price differentiation simultaneously in the enteral nutrition market, filtering suppliers into tiered qualification bands that determine formulary access and margin capture potential across hospital procurement systems.
Pricing Analysis
Cost-plus contracts with medical device component indexation dominate pump procurement, while formula pricing stratifies across premium disease-specific, standard polymeric, and economy private-label tiers. Price differentiation rests on clinical evidence depth and GPO formulary exclusivity rather than manufacturing scale alone. Cost compression in standard polymeric segments is intensifying because hospital IDN consolidation demands volume rebates. Long-term care facilities exhibit highest price sensitivity; academic medical centers prioritize clinical outcomes over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of elemental formula precursors and precision pump motors supersedes just-in-time preferences given semiconductor allocation volatility and mineral premix contamination screening delays. Manufacturing concentrates in the United States, Germany, and Japan for device assembly; China and India for active pharmaceutical ingredient sourcing. Raw material dependencies include peptide hydrolysates, medium-chain triglycerides, and precision stepper motors. Single-source pump motor vulnerability from Japanese and German component houses exposes assemblers to allocation risk. Distribution runs through integrated delivery networks that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enteral nutrition is fundamentally a service-attach opportunity where smart pump connectivity subscriptions and remote monitoring contracts expand faster than hardware sales, creating recurring revenue layers that offset capital equipment margin compression.
For Market Incumbents: Shield formulary dominance by deepening backward integration into peptide and MCT ingredient sourcing before supply scarcity elevates raw material costs. Accelerate FDA substantiation dossiers for oncology and hepatic disease-specific claims to preempt competitor entry into premium formulation white space. ISO 13485 recertification investment must precede GPO contract renewals to maintain eligibility.
For New Entrants and Emerging Players: Lead with homecare reimbursement pathway optimization rather than acute care formulary penetration, where GPO consolidation has foreclosed access. Target skilled nursing facility pump rental-to-purchase transitions where CMS fee schedule arbitrage creates margin opportunity. White-space concentration in hepatic encephalopathy and pulmonary failure formulations offers prescriber loyalty building before evidence requirements harden.
For Investors and Strategic Acquirers: EU MDR pump reclassification reshapes the acquisition landscape by elevating clinical evidence burdens that strain R&D budgets at sub-scale device manufacturers. Long-term viability favors targets with captive disease-specific formulation portfolios and validated quality management systems. The signal to watch is CMS durable medical equipment fee schedule compression velocity, which accelerates hardware commoditization and elevates software-subscription business model attractiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Pump Connectivity Development | EHR integration and wireless inventory management open subscription revenue streams distinct from device sales. |
| Disease-Specific Formulation Expansion | Hepatic and pulmonary indication development builds prescriber loyalty before FDA substantiation mandates harden. |
| Homecare Reimbursement Pathway Optimization | CMS rental-to-purchase transition structuring captures post-acute care expansion velocity beyond hospital discharge. |
| Backward Integration into Peptide Sourcing | Captive hydrolysate supply secures elemental formulation margins against raw material allocation risk. |
| EU MDR Clinical Evidence Investment | Post-market surveillance package completion maintains pump market access against reclassification deadlines. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital procurement directors, GPO contracts managers, clinical nutrition specialists, and enteral device biomedical engineers and refined through secondary validation against FDA medical food guidance documents, CMS Medicare fee schedules, EU MDR technical documentation requirements, and hospital formulary databases. Bottom-up volume modeling from individual health system procurement data was triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across formulation type, delivery modality, care setting intensity, and regional reimbursement framework shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends. Forecast inputs included ICU bed capacity expansion trajectories, post-acute care discharge protocol adoption curves, and ISO 13485 certification penetration rates among supplier bases.
Forecasts assume regulatory continuity in FDA medical food labeling regimes and EU MDR transition timelines; material policy shifts would require re-modeling. Specific risk factors include aluminum contamination threshold revisions, single-source component allocation disruptions, and oral nutrition supplement substitution acceleration. Revision becomes warranted when CMS durable medical equipment fee schedule compression crosses thresholds that invalidate rental-to-purchase economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Garcinia Cambogia Extract Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market