
 Middle East and Africa Omega-3 Products Market | 2026-2036
Middle East and Africa Omega-3 Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Omega-3 Products Market Foresight
Subscription-based replenishment programs for omega-3 softgels is hardening into a core revenue stream across e-commerce platforms serving Gulf consumers. DSM Nutritional Products leverages its algae-derived DHA portfolio to anchor supply contracts with Saudi pharmaceutical distributors. BASF SE sustains competitive positioning through backward integration into Antarctic krill harvesting operations. Cargill competes on price in the bulk fish oil segment, supplying African animal nutrition compounders with unrefined triglyceride concentrates.
Middle East and Africa omega-3 products encompass concentrated eicosapentaenoic acid and docosahexaenoic acid formulations extracted via molecular distillation or supercritical CO2 processing, standardized to 30-90% active fatty acid content for human therapeutic and nutritional applications. Algal oil commands premium positioning among vegetarian and halal-conscious consumers in the UAE and Qatar, where fish-derived alternatives face religious scrutiny. Pharmaceutical-grade omega-3 ethyl esters generate the densest margin pools, with South African compounding pharmacies and Egyptian hospital procurement channels driving volume in this application tier. Softgel formulations dominate unit sales through retail pharmacy networks, though liquid emulsions gain traction in pediatric and geriatric patient segments.
South Africa's Health Products Regulatory Authority enforces stability testing and label claim verification for imported omega-3 supplements, while Saudi Arabia's SFDA mandates halal certification for all marine-derived nutritional products entering the Kingdom. The UAE's MOHAP registration requirements for dietary supplements create compliance barriers that favor established multinationals with dedicated regulatory affairs teams. Stakeholders must monitor evolving Gulf standardization initiatives for EPA/DHA potency labeling and oxidation limits, as harmonization across GCC member states would reshape competitive access dynamics.
Market Dynamics
Algae-derived DHA extraction technology is compressing reliance on marine fisheries across Gulf pharmaceutical supply chains, while halal certification mandates from Saudi Arabia's SFDA and the UAE's MOHAP registration protocols are restructuring competitive access for international suppliers.
Growth Catalysts
- SFDA Halal Mandates:Saudi Arabia's mandatory halal certification for marine-derived nutritional products creates compliant supply scarcity that rewards pre-certified importers with procurement preference in hospital and pharmacy channels.
- Medical Aid Reimbursement:South Africa's private healthcare schemes increasingly cover therapeutic omega-3 formulations, expanding addressable patient populations beyond out-of-pocket supplement buyers.
- Supercritical CO2 Processing:This extraction method enables higher EPA/DHA concentration ratios without thermal degradation, meeting pharmaceutical-grade purity thresholds required by Egyptian hospital procurement specifications.
Market Restraints
- Antarctic Krill Supply Concentration:Five operators control bulk krill harvesting operations, creating input bottlenecks for phospholipid-bound omega-3 formulations destined for premium Gulf retail channels.
- Fish Oil Oxidation Sensitivity:Peroxide value instability during Middle Eastern summer logistics degrades triglyceride concentrate quality, forcing refrigerated transport cost premiums that compress margin pools for bulk African compound feed suppliers.
- UAE Third-Party Verification:MOHAP's requirement for independent EPA/DHA potency certificates adds 8-12 week registration timelines that disadvantage smaller importers lacking dedicated regulatory affairs infrastructure.
Strategic Opportunities
- Pediatric Liquid Emulsions:Underpenetrated geriatric and pediatric formulation segments in Qatar and Kuwait offer white space for taste-masked, high-bioavailability products bypassing softgel swallowing difficulties.
- Subscription Replenishment Models:Gulf e-commerce platforms are hardening automatic delivery programs into core revenue streams, locking in 6-12 month purchase commitments that reduce customer acquisition cost volatility.
- GCC Label Harmonization:Pending standardization initiatives for EPA/DHA potency disclosure and oxidation limit thresholds would consolidate multi-country compliance into single certification pathways, favoring scaled multinationals.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Few Gulf laboratories employ technicians capable of gas chromatography fatty acid profiling to the precision required by SFDA and MOHAP verification protocols, creating testing bottlenecks.
- Cold Chain Infrastructure Gaps:Last-mile temperature-controlled distribution remains inconsistent across Nigerian and Kenyan retail pharmacy networks, limiting shelf-stable algal oil penetration despite superior oxidation resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Omega-3 Products Market |
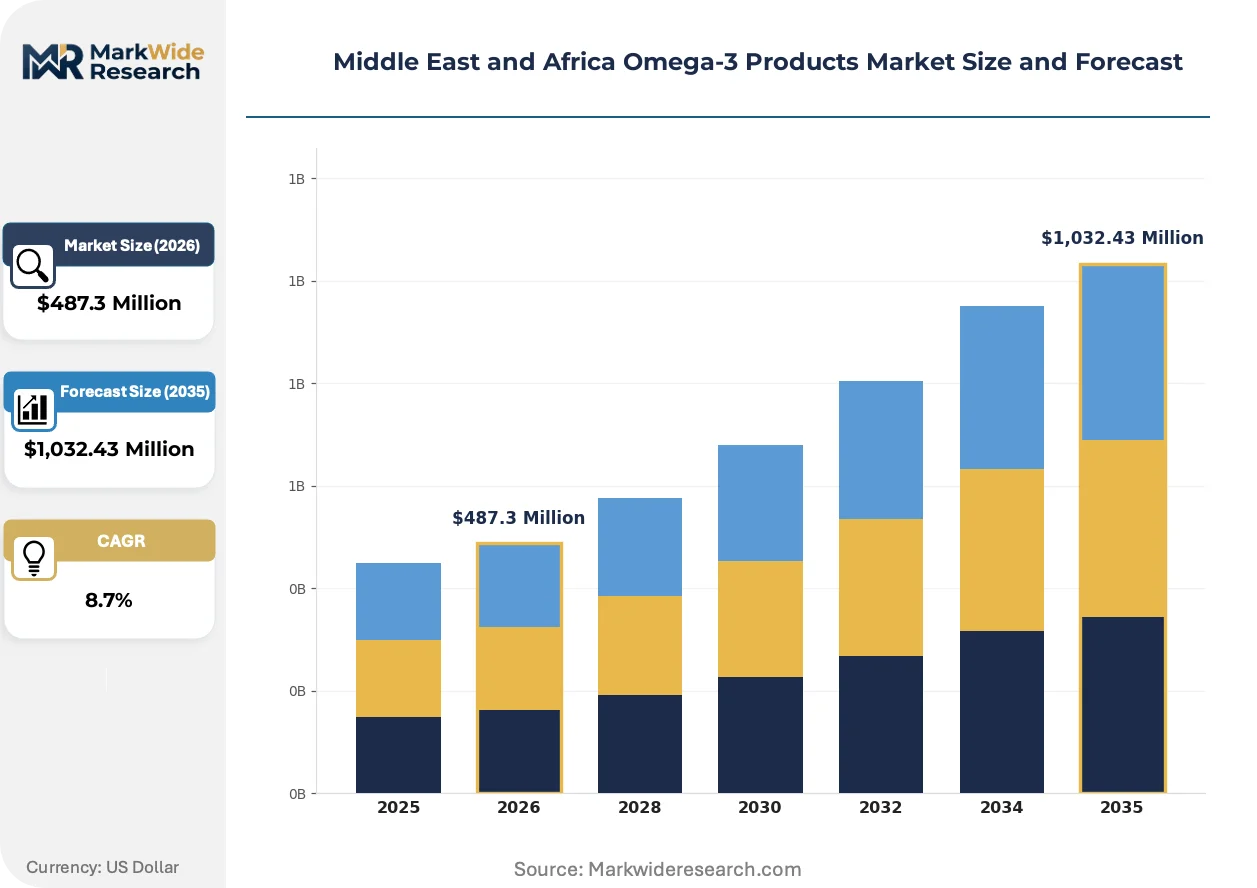
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Emulsified Omega-3 Form: Softgels, Capsules, Liquid, Powder Application: Dietary Supplements, Functional Foods, Pharmaceutical, Animal Nutrition Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | DSM Nutritional Products, BASF SE, Cargill, Nordic Naturals, Epax Norway, Omega Protein Corporation, Amgen Inc., Windmill Health Products, Amway Corp, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Omega-3 Products Market Shifts & Advancements
Processing technology convergence with religious dietary compliance requirements is reshaping raw material sourcing strategies, while regulatory disclosure mandates are forcing transparency upgrades across supply documentation.
Algae fermentation systems producing DHA without marine biomass are overtaking fish oil derivatives in UAE and Qatar pharmaceutical procurement. Halal-conscious hospital formulary committees in Dubai and Abu Dhabi are specifying fermentation-origin certificates ahead of contract awards. This technology is compressing traditional anchovy and sardine reduction fishery offtake volumes in premium therapeutic segments.
South Africa's Health Products Regulatory Authority now enforces accelerated stability testing protocols for imported omega-3 supplements, rejecting submissions with peroxide value degradation curves exceeding 18-month thresholds. This industrial consequence is forcing reformulation toward antioxidant-stabilized ethyl ester matrices. Egyptian hospital procurement channels are responding by pre-qualifying only suppliers with in-house accelerated aging validation capabilities.
Direct-to-patient subscription models are displacing traditional pharmacy counter purchasing among chronic cardiovascular patients in Saudi Arabia and the UAE. Gulf e-commerce platforms now capture replenishment orders through mobile-optimized interfaces with prescriber-integrated dosage reminders. This channel shift is most visible in Riyadh and Jeddah, where medical aid scheme integration enables automated co-payment processing without patient reimbursement friction.
Middle East and Africa Omega-3 Products Market Segmentation
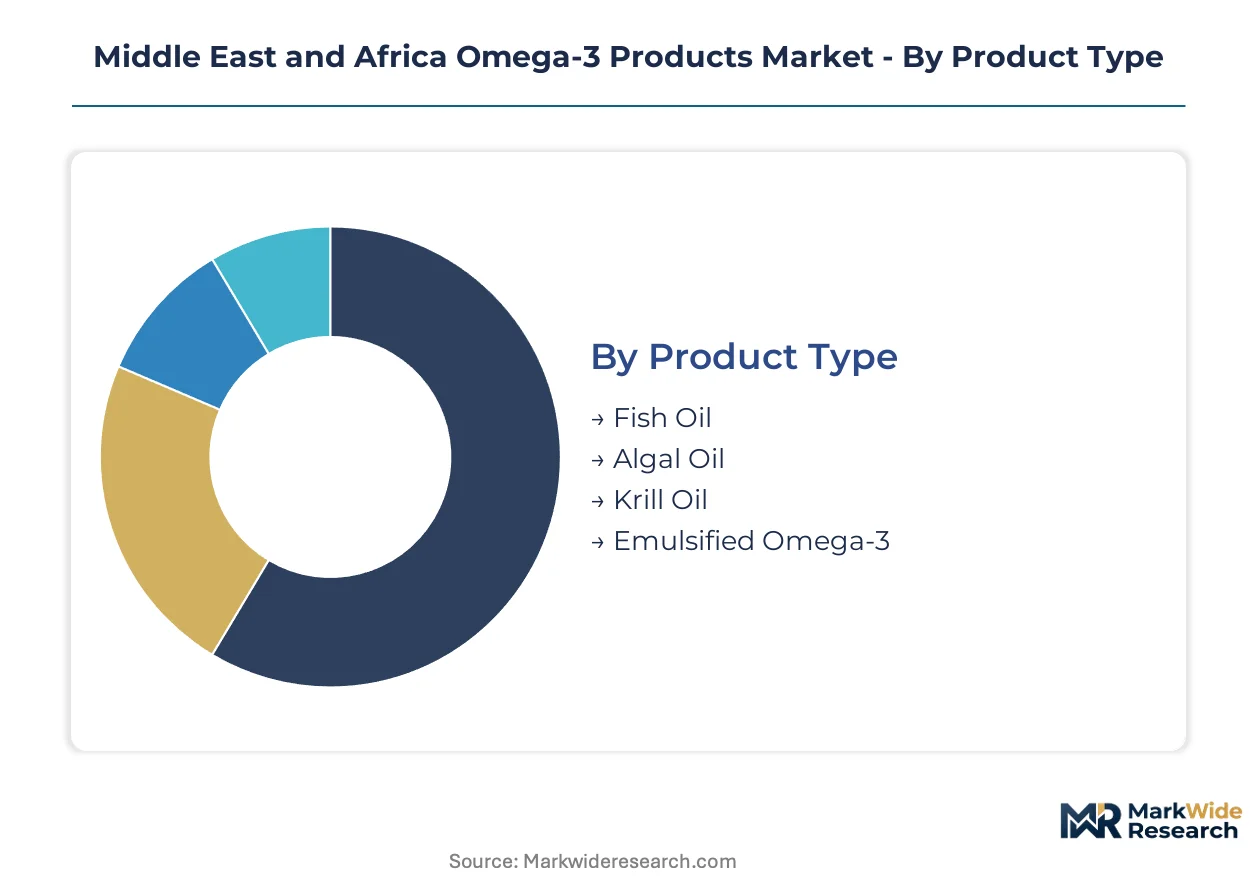
Omega-3 product segmentation in the Middle East and Africa reflects divergent paths between commodity bulk supply and certified therapeutic formulations. Religious dietary requirements, pharmaceutical registration protocols, and cold-chain infrastructure limitations create distinct competitive arenas across each dimension.
Product Type:
Standardization dominates fish oil and krill oil sourcing, while algal oil and emulsified formats demand customized extraction and certification investments.
- Fish Oil:Triglyceride and ethyl ester concentrates derived from anchovy, sardine, and mackerel reduction fisheries, typically standardized to 30-60% EPA/DHA content. South African medical aid schemes and Egyptian hospital procurement channels drive volume, though summer oxidation sensitivity forces refrigerated logistics premiums that erode margin pools for bulk compounders.
- Algal Oil:Fermentation-derived DHA from Schizochytrium and Crypthecodinium strains, commanding 40-60% price premiums over marine alternatives. UAE and Qatar hospital formulary committees specify fermentation-origin certificates ahead of contract awards, compressing traditional fishery offtake in premium therapeutic segments.
- Krill Oil:Phospholipid-bound EPA/DHA with superior bioavailability, sourced from Antarctic Euphausia superba harvesting operations controlled by five operators. Supply concentration creates input bottlenecks for premium Gulf retail positioning.
- Emulsified Omega-3:Water-dispersible formulations with enhanced absorption kinetics, targeting pediatric and geriatric swallowing difficulties in Kuwait and Qatar.
Leading the category by volume: Fish Oil. Expanding most quickly: Algal Oil.
Form:
Unit economics and patient compliance requirements split this category between high-throughput softgel manufacturing and specialized delivery innovations.
- Softgels:Gelatin or plant-based capsule shells containing 500-1000mg omega-3 concentrates, dominating retail pharmacy unit sales across Saudi Arabia and the UAE. Subscription replenishment programs through Gulf e-commerce platforms now capture 6-12 month purchase commitments that reduce customer acquisition cost volatility.
- Liquid:Oil-based or emulsified preparations with dosing flexibility for pediatric and geriatric populations, gaining traction where swallowing difficulties limit softgel adherence. Taste-masking formulations unlock underpenetrated segments in Qatar and Kuwait.
- Capsules:Two-piece hard gelatin or HPMC shells accommodating powder or granule fills, serving halal-conscious consumers seeking alternatives to softgel gelatin sources.
- Powder:Microencapsulated or free-flowing concentrates for functional food integration and animal nutrition compounding, supplied by Cargill to African feed manufacturers on price-competitive terms.
Dominant by manufacturing scale: Softgels. Steepest expansion trajectory: Liquid.
Application:
Margin structures diverge sharply between reimbursed pharmaceutical channels and out-of-pocket supplement purchases.
- Pharmaceutical:Prescription-grade ethyl esters and concentrated EPA formulations for cardiovascular and prenatal indications, generating the densest margin pools. Egyptian hospital procurement specifications and South African compounding pharmacies drive volume in this application tier.
- Dietary Supplements:Over-the-counter softgels and capsules for general wellness, concentrated in UAE and Saudi retail pharmacy networks. SFDA halal mandates and MOHAP third-party verification requirements favor established multinationals with dedicated regulatory affairs infrastructure.
- Functional Foods:Omega-3 fortification of dairy, bakery, and beverage products, limited by oxidative stability challenges and Gulf consumer taste preferences.
- Animal Nutrition:Unrefined triglyceride concentrates for aquaculture and livestock feed, with Cargill competing on price for African compounder supply contracts.
Highest value concentration: Pharmaceutical. Gaining share fastest: Dietary Supplements.
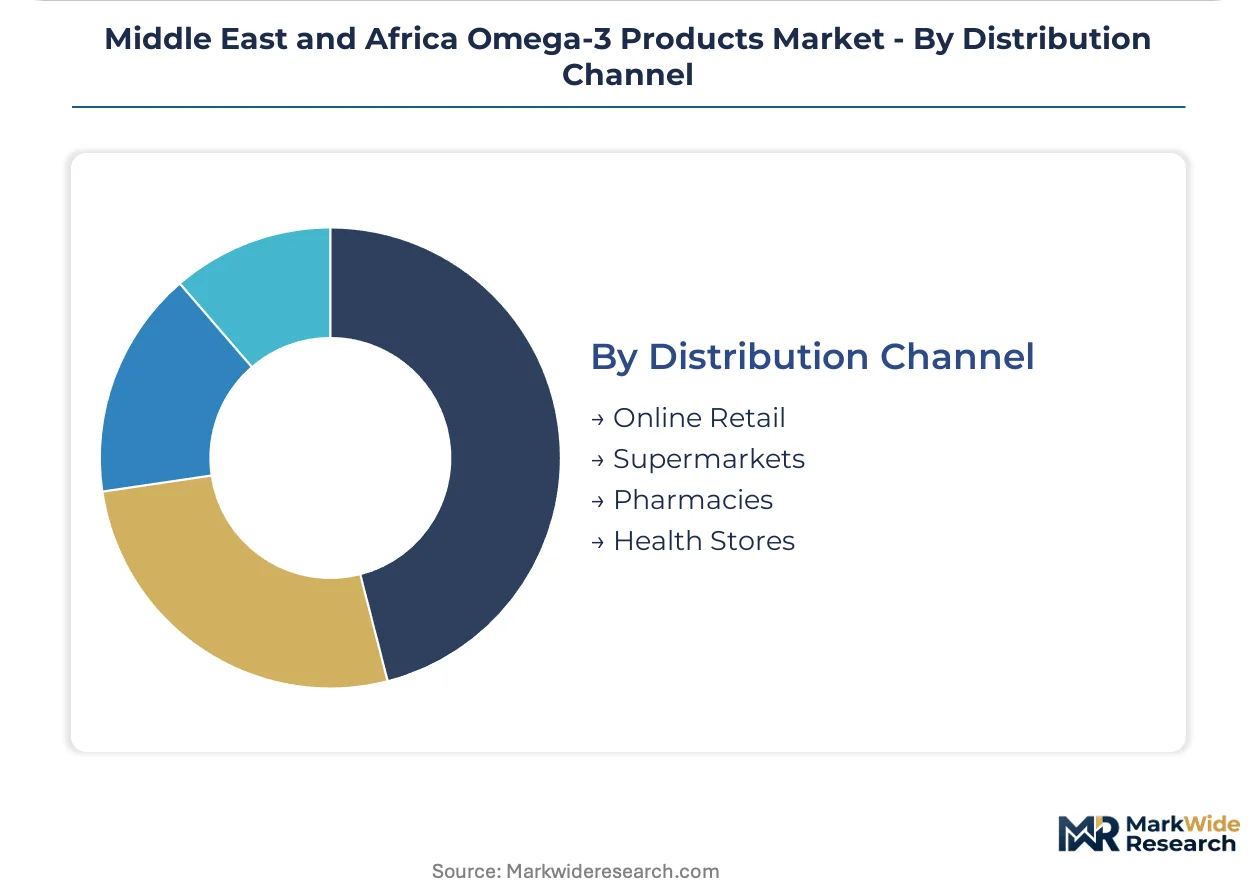
Distribution Channel:
Channel selection determines regulatory exposure and customer lifetime value capture.
- Pharmacies:Licensed retail outlets with SFDA and MOHAP registration compliance, capturing chronic cardiovascular patient replenishment through prescriber-integrated dosage reminders in Riyadh and Jeddah.
- Online Retail:Gulf e-commerce platforms with mobile-optimized interfaces and medical aid scheme integration, hardening automatic delivery programs into core revenue streams.
- Supermarkets:Mass-market supplement placement for price-sensitive consumers, constrained by ambient temperature storage limitations during Middle Eastern summer months.
- Health Stores:Specialist retailers targeting fitness and wellness segments, with inconsistent cold-chain infrastructure across Nigerian and Kenyan networks limiting premium algal oil penetration.
Primary volume channel: Pharmacies. Climbing the fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors pharmaceutical-grade omega-3 distribution across the Gulf Cooperation Council corridor, with Jebel Ali Free Zone warehousing serving as the primary entry point for halal-certified concentrates bound for Saudi and Qatari hospital networks.
United Arab Emirates
Hospital formulary committees in Dubai and Abu Dhabi specify fermentation-origin DHA certificates ahead of contract awards, compressing traditional fishery offtake in premium therapeutic segments. MOHAP's third-party verification protocols favor established multinationals with dedicated regulatory affairs infrastructure. Jebel Ali pharmaceutical logistics clusters now host temperature-controlled storage for algal oil concentrates serving the wider Gulf.
Saudi Arabia
SFDA mandatory halal certification for marine-derived nutritional products creates compliant supply scarcity that rewards pre-certified importers with procurement preference. Riyadh and Jeddah medical aid scheme integration enables automated co-payment processing for chronic cardiovascular patient replenishment. The Kingdom's hospital procurement channels drive volume in prescription-grade ethyl ester formulations.
South Africa
Private healthcare schemes increasingly cover therapeutic omega-3 formulations, expanding addressable patient populations beyond out-of-pocket supplement buyers. The Health Products Regulatory Authority enforces accelerated stability testing protocols, rejecting submissions with peroxide value degradation curves exceeding thresholds. Cape Town and Johannesburg compounding pharmacies anchor pharmaceutical-grade distribution.
Egypt
Hospital procurement specifications demand pharmaceutical-grade purity thresholds that supercritical CO2 processing enables without thermal degradation. Egyptian procurement channels pre-qualify only suppliers with in-house accelerated aging validation capabilities. Cairo's pharmaceutical distribution networks concentrate imports for redistribution across North African markets.
Qatar and Kuwait
Underpenetrated pediatric and geriatric formulation segments offer white space for taste-masked, high-bioavailability liquid emulsions bypassing softgel swallowing difficulties. Halal-conscious consumers in Doha and Kuwait City drive premium positioning for algae-derived alternatives. Retail pharmacy networks in these markets show fastest adoption of subscription-based replenishment programs.
Middle East and Africa Omega-3 Products Market Competitive Landscape
Capital-heavy producers with Antarctic krill harvesting operations and algae fermentation infrastructure compete with asset-light brand marketers and regional distributors for Gulf pharmacy shelf space. Market structure concentrates around three strategic archetypes: integrated marine biomass harvesters, fermentation technology specialists, and price-competitive bulk triglyceride suppliers. Dominant competitive moves include backward integration into raw material sourcing and regulatory certification pre-positioning ahead of harmonized GCC labeling standards.
Among integrated biomass operators, BASF SE exemplifies the capital-intensive archetype through upstream control over Antarctic harvesting operations. DSM Nutritional Products anchors the fermentation technology tier with algae-derived DHA portfolios securing Saudi pharmaceutical distributor contracts. Cargill occupies the price-driven position, supplying unrefined concentrates to African animal nutrition compounders on volume-competitive terms.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| BASF SE |
| Cargill |
| Nordic Naturals |
| Epax Norway |
| Omega Protein Corporation |
| Amgen Inc. |
| Windmill Health Products |
| Amway Corp |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in Saudi Arabia and state-linked pharmaceutical distributors across the Gulf Cooperation Council corridor anchor supply-side discipline, compressing margin volatility for halal-certified omega-3 concentrates while extracting premium pricing from hospital formulary committees in Dubai and Riyadh. Their procurement preference contracts with fermentation-origin DHA suppliers create tiered access barriers that smaller importers cannot match, hardening price stratification across pharmaceutical-grade and commodity bulk segments.
Pricing Analysis
Pharmaceutical-grade purity thresholds tied to Egyptian hospital procurement specifications and South African medical aid reimbursement criteria anchor value-based pricing for concentrated EPA/DHA formulations. Price differentiation separates fermentation-origin algal oil carrying halal certification premiums from unrefined fish oil triglycerides competing on volume terms for African animal nutrition compounders. Pricing pressure stems from summer oxidation sensitivity forcing refrigerated transport cost premiums across Middle Eastern logistics corridors, compressing margin pools for bulk suppliers serving price-sensitive feed manufacturers.
Supply Chain Analysis
Antarctic krill harvesting operations rest on five controlled operators, while algae fermentation infrastructure concentrates in Netherlands and China production facilities serving Gulf pharmaceutical distributors. Raw material dependencies span Schizochytrium and Crypthecodinium strains for DHA production, Antarctic Euphausia superba biomass for phospholipid-bound formulations, and anchovy-sardine reduction fisheries for commodity triglyceride concentrates. Single-source vulnerability in krill phospholipid supply creates input bottlenecks for premium Gulf retail channels. Distribution runs through Jebel Ali Free Zone temperature-controlled warehousing for GCC hospital network redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in halal-certified marine-derived inputs prop pricing power for pre-certified importers, with fermentation-origin DHA capacity shortages creating durable scarcity premiums across Gulf hospital procurement channels.
For Market Incumbents: Deploy backward integration into algae fermentation infrastructure to secure captive supply of halal-certifiable DHA ahead of SFDA and MOHAP regulatory tightening. Consolidate regulatory affairs capabilities across GCC member states to capture harmonized labeling standardization benefits, defending against emerging plant-based omega-3 entrants exploiting gelatin-free positioning in softgel alternatives. For New Entrants and Emerging Players: Begin with pediatric liquid emulsion formulations in Qatar and Kuwait, where taste-masked high-bioavailability products face minimal incumbent saturation and swallowing difficulties limit softgel adherence. Target subscription-based replenishment programs through Gulf e-commerce platforms as the go-to-market angle, leveraging automated delivery infrastructure already hardened into core revenue streams by established pharmacy networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation technology specialists with validated MOHAP and SFDA certification pathways in UAE and Saudi Arabia, positioned to capture procurement preference as supply scarcity intensifies. Long-term viability hinges on algae-derived DHA displacing marine fishery dependence across therapeutic segments. Watch Antarctic krill harvest quota restrictions as the inflection signal for phospholipid-bound omega-3 supply disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-Positioning | SFDA and MOHAP mandates reward pre-certified suppliers with hospital procurement preference in Riyadh and Dubai. |
| Algae Fermentation Capacity Expansion | Fermentation-origin DHA certificates displace marine fishery offtake in UAE and Qatar hospital formulary committees. |
| Subscription Platform Integration | Gulf e-commerce automatic delivery programs capture 6-12 month purchase commitments from chronic cardiovascular patients. |
| Cold Chain Infrastructure Investment | Temperature-controlled Jebel Ali warehousing enables algal oil concentrate redistribution across GCC member states. |
| Accelerated Stability Testing Capabilities | South African Health Products Regulatory Authority protocols reject submissions lacking 18-month peroxide value validation. |
Research Methodology
Multi-period observation of EPA/DHA potency labeling standardization initiatives, halal certification mandate rollouts, and medical aid reimbursement expansion anchored the trend analysis, supplemented by interviews with pharmaceutical distributor procurement managers, hospital formulary committee directors, regulatory affairs specialists at multinational nutrition companies, and compound pharmacy operators across Cape Town and Johannesburg. Primary fieldwork combined with secondary validation through SFDA and MOHAP regulatory filings, South African Health Products Regulatory Authority stability testing protocols, Egyptian hospital procurement specifications, and GCC customs trade data. Bottom-up volume modeling across product type, form, application, and distribution channel dimensions triangulated against top-down macroeconomic indicators.
Input-output matrices mapped fermentation-origin DHA production capacity, Antarctic krill harvest volumes, and fish oil reduction fishery offtake against Gulf hospital procurement demand, Egyptian pharmaceutical-grade specifications, and South African medical aid coverage expansion across the projection horizon. Segmentation dimensions spanned product type differentiation between algal, fish, and krill oil sourcing strategies; form factor variation across softgel, liquid, and emulsified delivery; application tier separation between pharmaceutical prescription and dietary supplement channels; and distribution channel evolution from pharmacy counter to e-commerce subscription. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through and substitution effects between marine and fermentation-origin inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade ethyl ester formulations carry tighter precision than commodity bulk triglyceride concentrates due to standardized purity thresholds and documented procurement specifications. Forecasts incorporate assumptions around GCC regulatory harmonization timelines, algae fermentation yield improvements, and krill harvest quota stability that could revise trajectory if disrupted. A small set of triggers—Antarctic harvest restriction announcements, MOHAP third-party verification protocol amendments, and South African medical aid scheme coverage decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market