
 Global Liver Health Supplements Market | 2026-2036
Global Liver Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liver Health Supplements Market Foresight
Asset-light contract manufacturing and white-label financing is narrowing the capital barrier for mid-tier entrants in liver health supplements. Jarrow Formulas leverages deep R&D intensity in standardized botanical extracts to sustain premium positioning. NOW Foods anchors its competitive stance through vertical integration from raw material sourcing to finished goods. Himalaya Wellness Company differentiates via Ayurvedic formulation heritage and controlled distribution across pharmacy channels in South Asia and Europe.
Liver health supplements comprise orally administered nutraceutical formulations containing hepatoprotective botanicals, phospholipids, and amino acid derivatives, typically standardized to active markers such as silymarin content in milk thistle extract. These products function to support hepatic detoxification pathways, modulate inflammatory cytokine expression, and maintain membrane integrity in hepatocytes under metabolic stress. Milk thistle extract occupies the dominant value position within product type segmentation due to extensive clinical citation and consumer recognition, while turmeric curcumin and N-acetylcysteine represent faster-growing categories as inflammation-focused positioning gains traction. Softgels and liquid extracts command margin premiums over tablets and powders by improving bioavailability claims and dosing convenience for aging demographics.
The FDA exercises post-market surveillance authority under DSHEA while cGMP regulations mandate identity, purity, and composition verification for all domestic and imported supplement batches. EFSA novel food assessments and health claim restrictions in Europe shape permissible marketing language and constrain rapid product positioning shifts. Japan's Ministry of Health, Labour and Welfare maintains FOSHU and non-FOSHU distinction systems that gate functional liver claims behind clinical substantiation requirements. Stakeholders must monitor evolving pharmacovigilance linkages between hepatotoxicity signal detection and botanical ingredient restrictions across these three regulatory poles.
Market Dynamics
The FDA's intensified cGMP enforcement is compressing supplier margins while elevating quality verification costs across the liver health supplements value chain, forcing mid-tier manufacturers toward contract manufacturing partnerships or exit.
Growth Catalysts
- FOSHU Distinction System:Japan's Ministry of Health, Labour and Welfare gates functional liver claims behind clinical substantiation, creating a premium tier for validated formulations that commands pricing power in aging demographics.
- Phospholipid Complexation Technology:Advanced delivery systems incorporating phosphatidylcholine matrices enhance silymarin bioavailability, opening formulation differentiation pathways for hepatoprotective botanicals.
- Germany's Alcohol Moderation Trend:Declining per-capita alcohol consumption among aging cohorts redirects preventive spending toward liver support supplements through pharmacy and wellness center channels.
Market Restraints
- Milk Thistle Raw Material Concentration:Silybum marianum cultivation clusters in limited Mediterranean and Eastern European growing regions, exposing supply chains to climate volatility and agricultural input cost swings.
- EFSA Health Claim Restrictions:The European Food Safety Authority's stringent novel food assessments and prohibited disease-prevention language constrain marketing flexibility and compress positioning latitude for inflammation-focused products.
- Synthetic N-Acetylcysteine Substitution:Pharmaceutical-grade NAC manufactured through petrochemical synthesis offers lower unit economics than botanical-derived alternatives, pressuring natural-positioned formulations on cost.
Strategic Opportunities
- India's Ayurvedic Export Channel:Controlled pharmacy distribution networks and heritage formulation credibility position Indian manufacturers to capture European and North American demand for traditional liver botanicals.
- Fitness Center Integration:Preventive liver care protocols within wellness facilities create a direct-to-consumer channel bypassing retail markup structures and enabling subscription-based replenishment models.
- Softgel Bioavailability Positioning:Lipid-based delivery formats targeting aging demographics with swallowing difficulties and absorption concerns command margin premiums over compressed tablet alternatives.
Industry Challenges
- Pharmacovigilance Signal Detection:Linkages between hepatotoxicity reports and botanical ingredient restrictions require continuous post-market surveillance infrastructure that strains smaller manufacturers' regulatory affairs capabilities.
- cGMP Batch Verification Timelines:Identity, purity, and composition testing protocols for imported raw materials extend production lead times and tie up working capital in inventory holding costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liver Health Supplements Market |
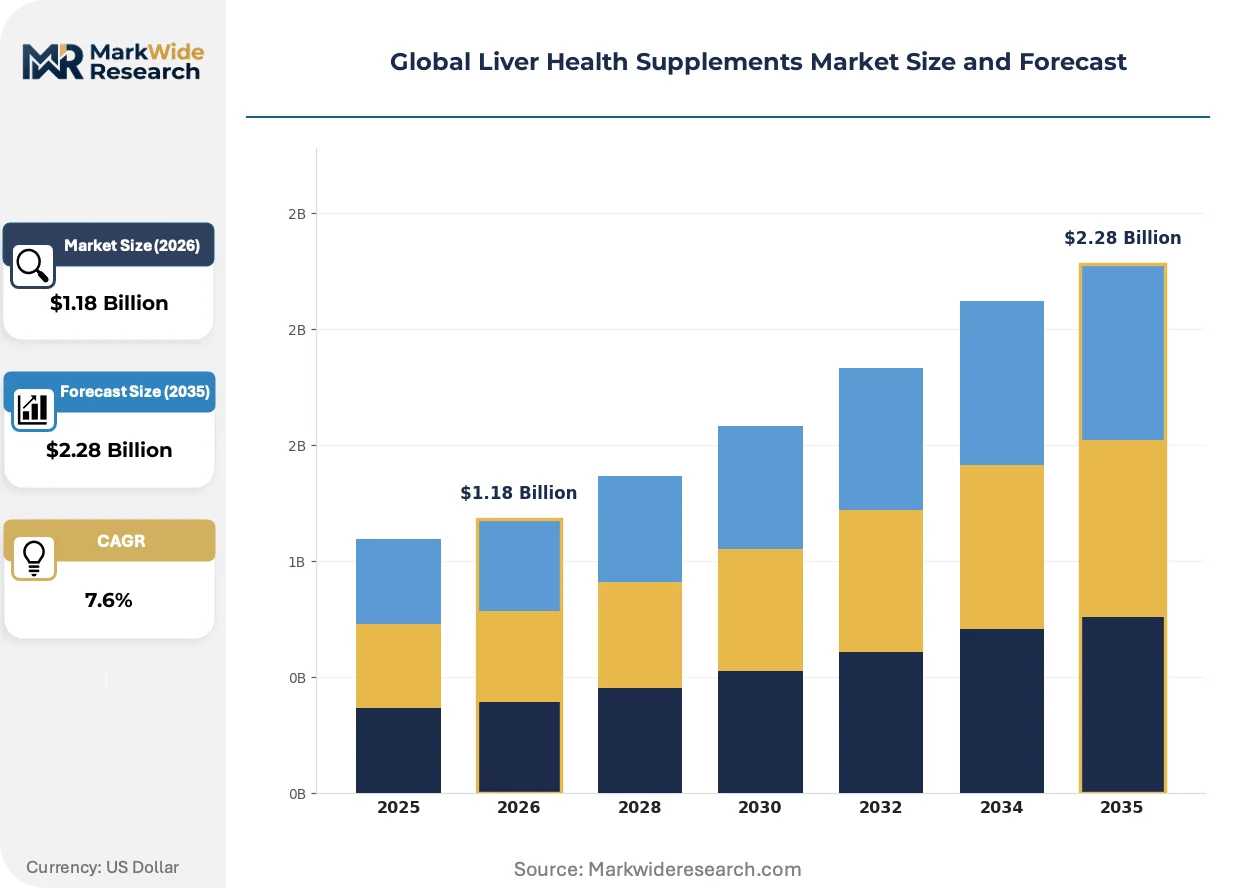
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Thistle Extract, Phosphatidylcholine, Artichoke Leaf, Dandelion Root, Turmeric Curcumin, NAC Form: Capsules, Tablets, Powders, Liquid Extracts, Softgels, Gummies Application: Fatty Liver, Hepatitis Support, Detoxification, Antioxidant Support, Bile Production, General Wellness End User: Pharmacies, Wellness Centers, Nutritional Stores, Online Retailers, Hospitals, Fitness Facilities |
| Companies Covered | Jarrow Formulas, Inc., Swisse Wellness PTY LTD, Himalaya Wellness Company, NOW Foods Inc., Blackmores, Amway Corporation, Nature's Bounty, Gaia Herbs, Enzymedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liver Health Supplements Market Shifts & Advancements
Formulation science and regulatory compliance automation are compressing traditional competitive advantages in the liver health supplements sector, rewarding capitalized players with integrated quality systems.
Liposomal encapsulation technology is collapsing the bioavailability gap between high-dose botanical extracts and their synthetic pharmaceutical counterparts. Wellness centers and preventive care clinics in Germany and Japan are adopting these advanced delivery formats at accelerated procurement cycles. This technology compression is eliminating the historical trade-off between natural positioning and clinical efficacy demonstration.
EFSA's evolving novel food assessment frameworks are tightening permissible marketing language for inflammation-modulating claims across European member states. Manufacturers must now substantiate hepatic enzyme modulation effects through clinical trials to maintain shelf positioning in pharmacy channels. Turmeric curcumin formulations face the most acute compliance pressure, with several member states requiring reformulation or claim reduction.
Direct-to-consumer subscription models are displacing traditional retail pharmacy distribution for maintenance-dose liver support products. Fitness facilities and corporate wellness programs in the United States are consolidating procurement through specialized nutraceutical distributors that bundle liver health with metabolic panels. This channel shift is most visible in urban coastal markets where preventive care spending concentrates among affluent aging demographics.
Global Liver Health Supplements Market Segmentation
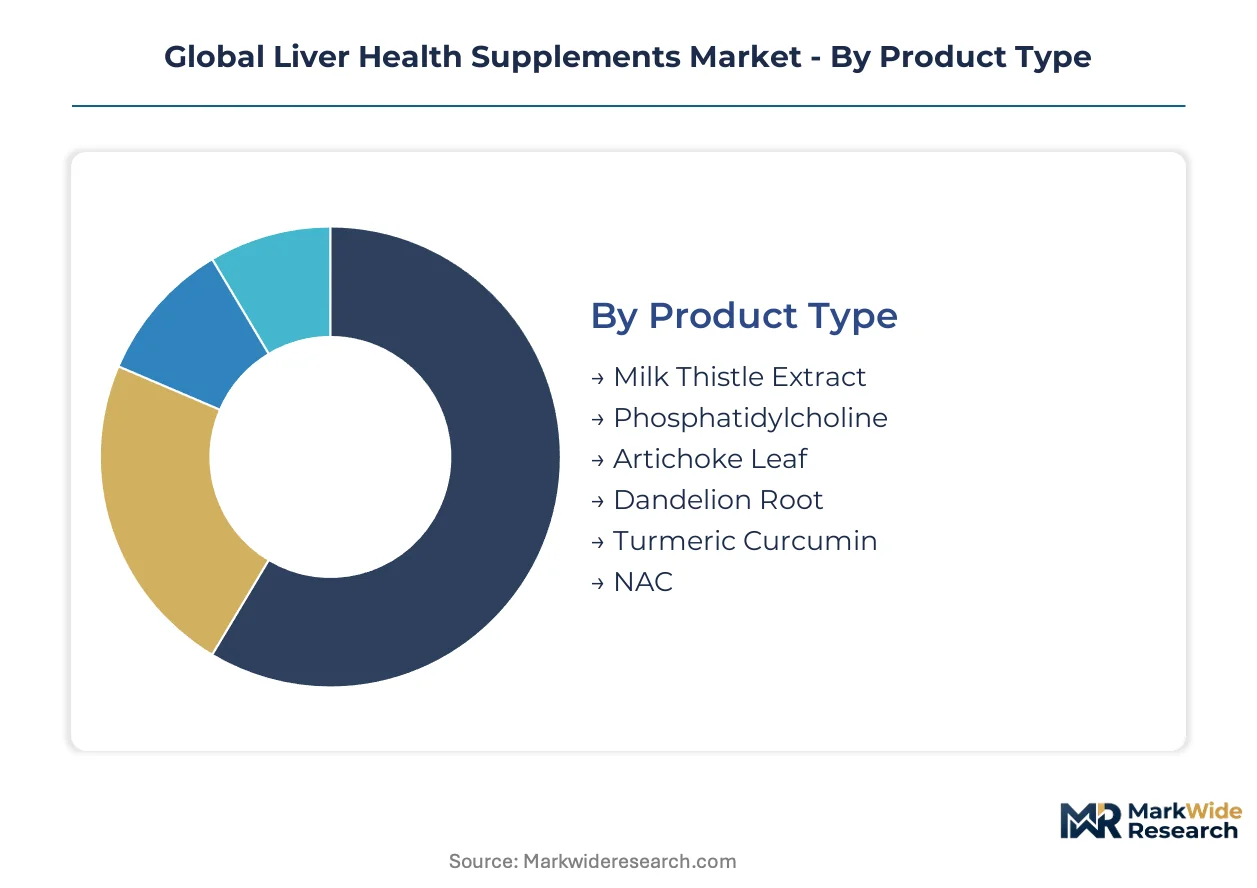
Liver health supplements segment across four dimensions that determine formulation investment, channel strategy, and regulatory positioning. Product type and form classifications drive manufacturing capital allocation, while application and end-user splits dictate marketing claims and distribution partnerships.
Product Type:
Mature standardized extracts dominate current revenue, while emerging bioavailability-enhanced complexes capture formulation R&D budgets.
- Milk Thistle Extract:Standardized silymarin content defines quality tiers across pharmacy and wellness channels. United States demand concentrates in standardized 80% silymarin extracts for aging demographics pursuing alcohol moderation protocols.
- Turmeric Curcumin:Inflammation-modulating positioning expands faster than traditional hepatoprotective claims. Germany's pharmacy channel absorbs high-curcuminoid formulations as EFSA scrutiny forces clinical substantiation investments.
- Phosphatidylcholine:Lipid-based liver support complexes from soy or sunflower lecithin.
- Artichoke Leaf:Cynarin-standardized extracts targeting bile production support.
- Dandelion Root:Traditional botanical with diuretic and hepatic positioning in European markets.
- NAC:N-acetylcysteine bridges pharmaceutical and nutraceutical positioning with glutathione precursor claims.
Milk Thistle Extract retains volume leadership; Turmeric Curcumin holds the steepest expansion curve.
Form:
Cost tier stratification separates premium delivery technologies from commodity compression formats.
- Softgels:Lipid-encapsulated matrices improve lipophilic botanical absorption and command margin premiums. Japan's aging population drives procurement through pharmacy channels where swallowing convenience determines repurchase rates.
- Liquid Extracts:Alcohol-free glycerite bases and liposomal suspensions target pediatric and geriatric compliance. Wellness centers in Germany integrate these into preventive care protocols with dosing flexibility advantages.
- Capsules:Two-piece gelatin or vegetable-derived shells for powdered extracts.
- Tablets:Compressed formats with binding agents for cost-sensitive retail tiers.
- Powders:Bulk active ingredients for compounding pharmacies and functional food integration.
- Gummies:Gelatin or pectin-based chewables targeting younger demographics and taste-sensitive users.
Softgels dominate pharmacy premium tiers; Gummies are climbing the fastest among direct-to-consumer channels.
Application:
Customer type stratification separates clinical-condition targeting from maintenance wellness positioning.
- Detoxification:Post-exposure and seasonal cleanse protocols drive repeat purchase cycles. United States fitness facilities bundle these with metabolic panels for corporate wellness contracts.
- Fatty Liver:Non-alcoholic steatohepatitis adjuvant support concentrates demand among metabolic syndrome demographics. Japan's FOSHU framework gates functional claims, creating premium validation tiers.
- Antioxidant Support:Glutathione pathway modulation for oxidative stress management.
- Hepatitis Support:Adjunct botanical formulations alongside conventional antiviral therapy.
- Bile Production:Choleretic botanicals for digestive and hepatic function integration.
- General Wellness:Maintenance-dose multibotanicals for preventive consumption.
Detoxification retains volume leadership; Fatty Liver holds the steepest expansion curve.
End User:
Geography concentration shapes channel margin structures and regulatory compliance burdens.
- Online Retailers:Direct-to-consumer platforms compress traditional pharmacy markups while expanding subscription replenishment. United States coastal urban markets concentrate preventive care spending through specialized nutraceutical distributors.
- Wellness Centers:Integrated preventive protocols bundle liver support with diagnostic panels. Germany's alcohol moderation trend redirects spending through these channels as consumers seek professional guidance.
- Pharmacies:Regulated retail with pharmacist consultation requirements in European markets.
- Nutritional Stores:Specialty retail with trained staff for botanical education.
- Hospitals:Clinical adjuvant use under physician supervision.
- Fitness Facilities:Gym-based retail and corporate wellness program integration.
Online Retailers retain volume leadership; Wellness Centers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in India and China supply raw botanical extracts to formulators in the United States, Germany, and Japan, creating a trade flow where processing value concentrates in import markets with stringent quality verification requirements.
United States
Aging demographics pursuing alcohol moderation protocols drive pharmacy channel demand for standardized milk thistle extracts. FDA cGMP enforcement elevates identity and purity testing costs for imported raw materials. Los Angeles and New York wellness centers bundle liver support with metabolic panels for corporate wellness contracts.
Germany
Declining per-capita alcohol consumption among aging cohorts redirects preventive spending toward pharmacy-distributed hepatoprotective formulations. EFSA health claim restrictions constrain inflammation-focused marketing language for turmeric curcumin products. Bavaria's pharmacy networks absorb high-curcuminoid formulations requiring clinical substantiation investments.
Japan
FOSHU distinction systems gate functional liver claims behind clinical validation, creating premium tiers for substantiated formulations. METI oversight maintains strict novel food assessment protocols for botanical imports. Tokyo's aging population drives softgel procurement through pharmacy channels where swallowing convenience determines repurchase behavior.
India
Controlled pharmacy distribution networks and Ayurvedic formulation heritage position domestic manufacturers for European and North American export growth. FSSAI quality standards align with import market verification requirements for botanical extracts. Gujarat and Maharashtra processing clusters concentrate milk thistle and turmeric extraction capacity for international formulators.
China
Domestic cultivation of Silybum marianum supplies both local formulators and export markets, though NMPA oversight tightens novel food registration for imported finished supplements. Yangtze River Delta manufacturing bases produce phospholipid complexation technologies for bioavailability-enhanced delivery systems.
Global Liver Health Supplements Market Competitive Landscape
On the supply side, the industry is structured around three tiers: premium botanical specialists with heritage formulation credibility, mid-scale contract manufacturers leveraging asset-light white-label platforms, and vertically integrated raw material processors controlling extraction-to-finished-goods pipelines. Strategic archetypes include R&D-intensive standardization leaders, Ayurvedic heritage exporters, and pharmacy-channel vertically integrated players. Competitive moves concentrate on phospholipid complexation technology licensing and fitness center direct procurement partnerships.
Within the heritage-formulation tier, Himalaya Wellness Company and Jarrow Formulas occupy positions emphasizing Ayurvedic credibility and standardized botanical R&D intensity respectively. NOW Foods anchors the vertically integrated archetype with captive supply chain control from raw material sourcing through finished goods production. These three entities exemplify how formulation science investment and channel-specific distribution partnerships separate premium positioning from commodity compression.
| Leading Market Players |
|---|
| Jarrow Formulas, Inc. |
| Swisse Wellness PTY LTD |
| Himalaya Wellness Company |
| NOW Foods Inc. |
| Blackmores |
| Amway Corporation |
| Nature's Bounty |
| Gaia Herbs |
| Enzymedica |
| Others |
Supply & Pricing Matrix
Undercapacity in Mediterranean Silybum marianum cultivation regions tightens raw material availability and amplifies supplier pricing power for standardized milk thistle extracts. Buyers face extended contract negotiations as agricultural input volatility and climate stress compress predictable procurement windows.
Pricing Analysis
Wellness center buyers anchor subscription-based pricing structures for maintenance-dose liver support protocols. Three-tier pricing structure across premium liposomal formulations, standard softgel extracts, and economy-tier compressed tablets reflects bioavailability claims and certification grade. Pricing pressure stems from FDA cGMP compliance costs elevating quality verification expenditures. Direct-to-consumer channels exhibit lowest price sensitivity due to subscription lock-in, while pharmacy distributors face margin compression from retail markup competition.
Supply Chain Analysis
Extended payment terms from European formulators to Indian extraction facilities characterize supplier-financing arrangements in botanical supply chains. Silybum marianum cultivation clusters in Spain, Poland, and China; phospholipid complexation technology draws from Yangtze River Delta manufacturing bases. Single-source vulnerability concentrates in Mediterranean milk thistle harvests exposed to drought cycles. Distribution runs through specialized nutraceutical distributors bundling liver health with metabolic panels for corporate wellness contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fitness center platform economics are displacing traditional pharmacy distribution, creating interoperability requirements between supplement procurement and diagnostic panel integration.
For Market Incumbents: Insulate premium positioning through captive phospholipid complexation technology licensing and backward integration into standardized botanical extraction. Jarrow Formulas' R&D intensity model demonstrates how clinical substantiation investments gate FOSHU-tier pricing in Japan. Control pharmacy channel shelf positioning against white-label contract manufacturer encroachment. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting United States coastal urban markets where preventive care spending concentrates. India's Ayurvedic export channel offers penetrable white-space for heritage-formulation credibility in European pharmacy networks. Fitness center integration bypasses retail markup structures and enables recurring-revenue capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wellness center and fitness facility channel specialists with diagnostic panel bundling capabilities. Long-term viability favors acquisition targets with integrated quality systems navigating FDA cGMP and EFSA novel food frameworks. Watch pharmacovigilance signal detection linkages to botanical ingredient restrictions as inflection indicators for formulation portfolio risk.| Strategic Initiative | Industry Significance |
|---|---|
| Phospholipid Complexation Licensing | Enhanced silymarin bioavailability opens premium formulation tiers in Japan's pharmacy channels. |
| Fitness Center Direct Procurement | Bypasses retail markup structures and enables subscription-based replenishment model capture. |
| FOSHU Clinical Substantiation Investment | Gates functional liver claims behind validation requirements in Japan's aging demographic. |
| Ayurvedic Export Channel Expansion | Leverages controlled pharmacy distribution networks for European and North American demand capture. |
| cGMP Quality System Automation | Compresses batch verification timelines and reduces working capital tied in inventory holding. |
Research Methodology
Cross-validation between primary interviews with formulation scientists, regulatory affairs directors, and wellness center procurement managers anchors the qualitative findings. Secondary sources include FDA warning letters, EFSA novel food opinions, FOSHU registration databases, and customs trade records for botanical extract flows. Bottom-up demand modeling triangulates against top-down market sizing across product type, delivery form, application, and end-user channel dimensions.
Calibration against historical price trajectories for milk thistle raw materials and softgel manufacturing capacity utilization informs the analytical framework across the projection horizon. Segmentation dimensions encompass standardized extract tiers, bioavailability-enhanced delivery technologies, detoxification versus fatty liver applications, and pharmacy versus wellness center channel splits. CAGRs derive from elasticity-adjusted demand curves incorporating aging demographic projections and alcohol moderation trend penetration.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mid-tier contract manufacturers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Camu Camu Extract Market