
 South America Nutricosmetics Market | 2026-2036
South America Nutricosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Nutricosmetics Market Analytics
Brazil is reshaping nutricosmetics manufacturing capacity across South America through expanded collagen extraction and encapsulation facilities in São Paulo state. Natura & Co. leverages its direct-sales network to control last-mile distribution into Brazilian households. O Boticário anchors regional R&D spending on bioactive peptide formulations for skin elasticity. Herbalife Nutrition Ltd. competes through nutrition-club channels that blur supplement and beauty positioning.
Nutricosmetics comprise ingestible formulations containing bioactive compounds—collagen peptides, antioxidant polyphenols, lipid-soluble vitamins—delivered via capsules, powders, or fortified beverages, designed to improve skin, hair, and nail physiology from systemic circulation rather than topical application. Collagen dominates product-type revenue due to established consumer awareness and visible-results marketing, while gummies within the form segment capture fastest growth by converting younger demographics skeptical of pill regimens. Pharmacy channels within distribution maintain premium price positioning through pharmacist consultation, whereas online retail erodes that margin pool via subscription models and influencer-driven discovery.
ANVISA governs novel ingredient approval and health-claim substantiation for nutricosmetics sold in Brazil, forcing reformulation cycles that favor capitalized multinationals over import-reliant entrants. Argentina's national food regulator and Chile's Ministry of Health apply parallel but non-harmonized standards, fragmenting compliance costs for brands spanning the Mercosur trade zone. Stakeholders must monitor whether pending regulatory convergence talks unify labeling and clinical-evidence thresholds, or perpetuate the current patchwork that rewards single-country specialization.
Market Dynamics
ANVISA's tightened novel food ingredient approval rules are forcing reformulation cycles across Brazil's nutricosmetics sector, privileging capitalized multinationals with in-house clinical validation capabilities over import-dependent entrants.
Growth Catalysts
- Bioactive peptide encapsulation:São Paulo-based manufacturers are scaling micro-encapsulation facilities to stabilize collagen and polyphenol bioavailability, extending product shelf life and expanding pharmacy distribution reach.
- Millennial skin-health demand:Brazilian consumers aged 25-40 are driving gummy format adoption, converting skeptical demographics who reject traditional pill regimens through flavor-masked delivery systems.
- Digital-pharmacy channel overlap:São Paulo and Rio de Janeiro metropolitan corridors now host integrated online-offline models where subscription platforms leverage pharmacist consultation credibility.
Market Restraints
- Bovine collagen input volatility:Raw material costs fluctuate with Brazilian cattle cycle conditions and export demand from Asian gelatin processors, compressing margin pools for domestic formulators.
- ANVISA approval timelines:Novel ingredient substantiation requirements extend product development cycles, freezing smaller brands out of innovation pipelines.
- Topical skincare substitution:Established dermatological brands with proven efficacy claims capture budget-conscious consumers seeking immediate visible results.
Strategic Opportunities
- Argentina regulatory harmonization:Pending Mercosur convergence talks could unify labeling standards, enabling Brazilian manufacturers to scale cross-border without duplicative compliance costs.
- Marine collagen diversification:Chilean fishery byproduct sourcing offers supply chain resilience against bovine price cycles, with Patagonian processors developing cosmetic-grade hydrolysate capacity.
- Nutrition-club channel expansion:Direct-sales networks in Colombian and Peruvian urban centers replicate Brazilian community-based distribution models for supplement-beauty hybrid positioning.
Industry Challenges
- Clinical evidence generation:Substantiating systemic skin-health claims requires dermatological endpoint studies that strain R&D budgets and extend time-to-market.
- Cross-border logistics fragmentation:Non-harmonized Mercosur customs procedures for novel food ingredients create inventory delays and compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Nutricosmetics Market |
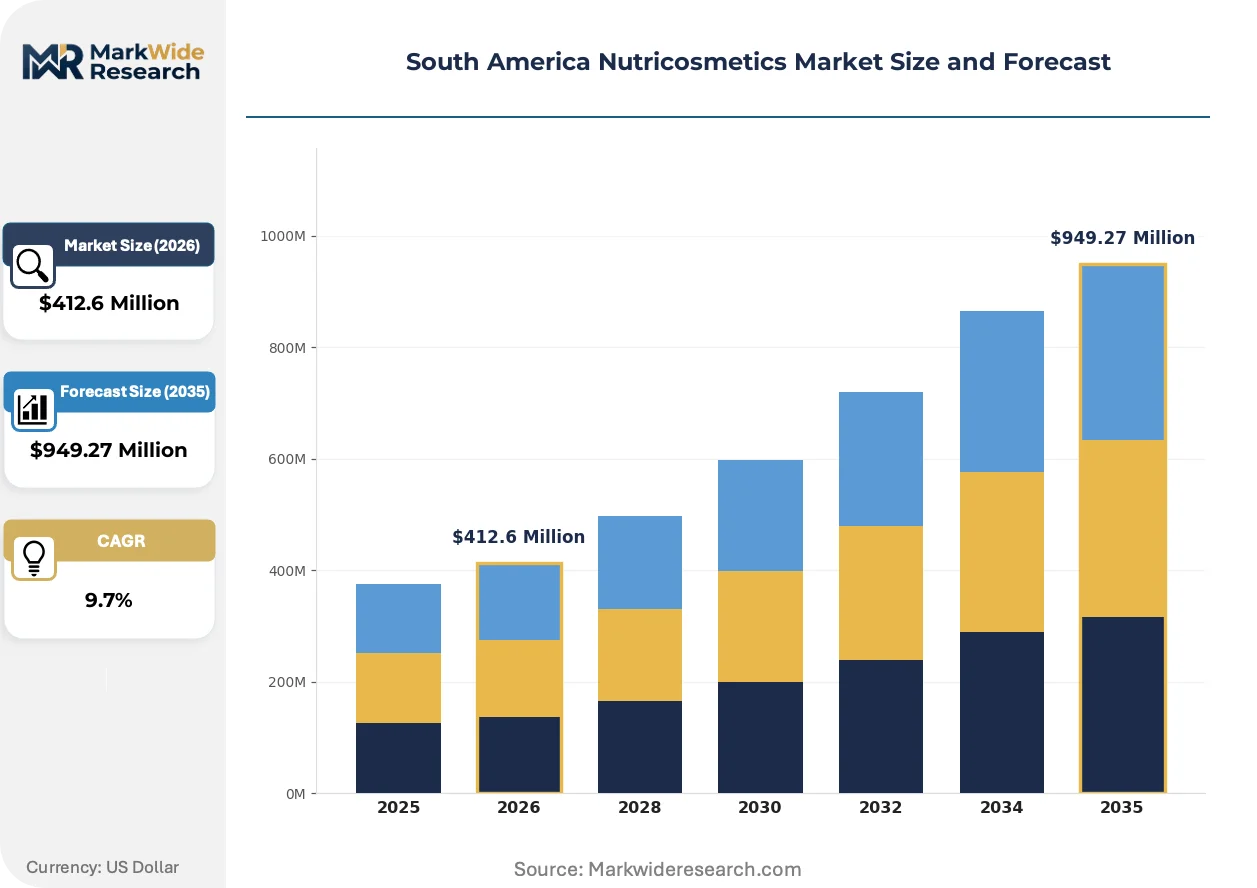
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Collagen, Antioxidants End User: Female Consumers, Male Consumers, Age 18-25, Seniors Form: Pills, Powders, Gummies, Beverages Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores |
| Companies Covered | Natura & Co., O Boticário, Amway Corp., Herbalife Nutrition Ltd., Nestlé, Bayer AG, Integralmedica, Shiseido Company, Limited, Swisse, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Nutricosmetics Market Evolving Landscape
Brazil's nutricosmetics sector is converging ingestible and topical beauty paradigms through delivery-system innovation, regulatory-driven formulation science, and generational consumption-pattern shifts.
Micro-encapsulation technology is hybridizing collagen and antioxidant stability with controlled-release kinetics. São Paulo manufacturers are adopting lipid-shell and alginate-matrix systems to protect bioactives from gastric degradation. This convergence is compressing the efficacy gap between pharmaceutical-grade supplements and conventional nutraceuticals, enabling pharmacy-channel premium positioning.
ANVISA's updated novel food ingredient framework mandates peer-reviewed clinical substantiation for systemic beauty claims. Brazilian formulators now commission dermatological endpoint studies measuring skin elasticity and hydration biomarkers. The regulation most affects collagen peptide and polyphenol categories, pushing brands toward established GRAS-status ingredients with existing safety dossiers.
Subscription-based discovery models are displacing traditional pharmacy counter sales among Brazilian millennials. Influencer-curated boxes and auto-replenishment platforms capture trial-to-repeat conversion through personalized regimen algorithms. This shift concentrates in São Paulo's digitally native consumer base, where social commerce integration outperforms conventional retail foot traffic.
South America Nutricosmetics Market Segmentation
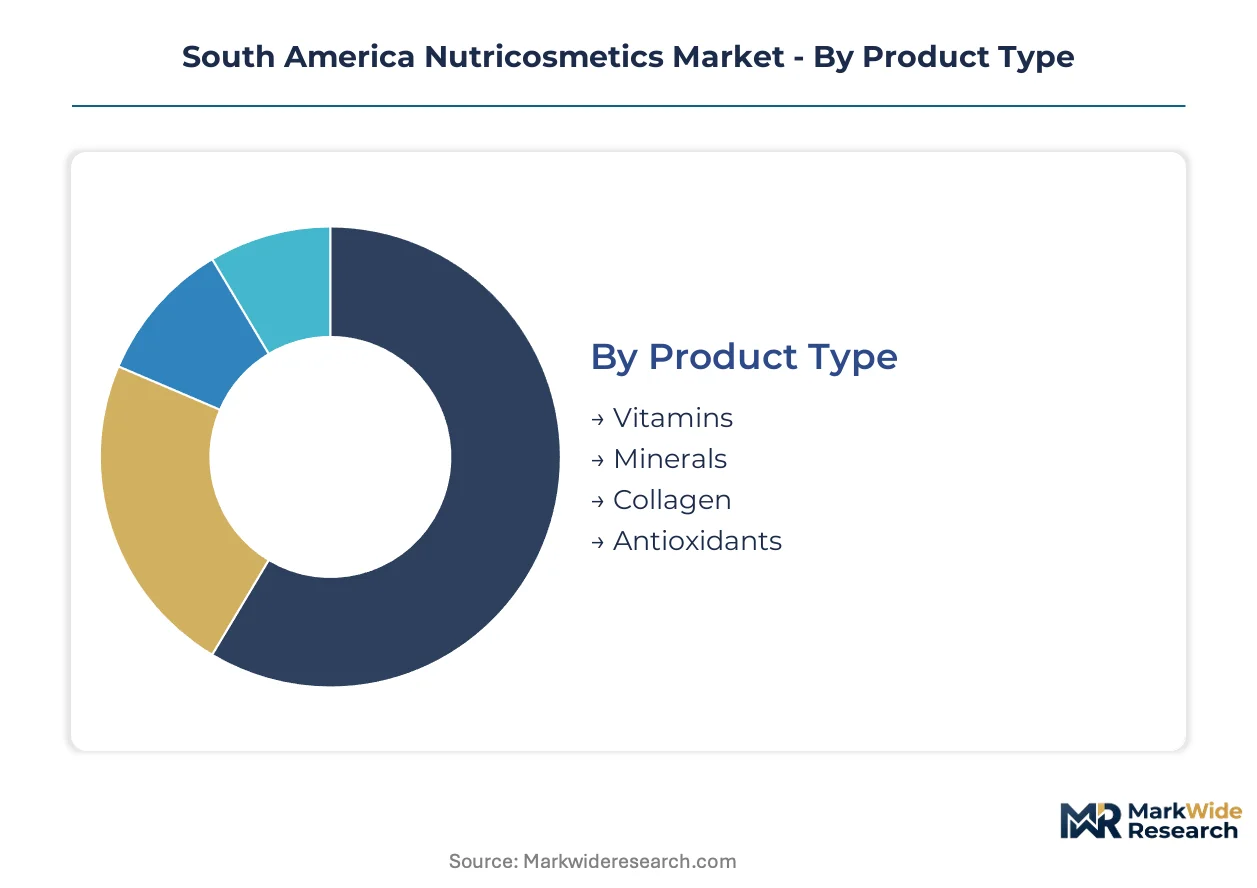
Nutricosmetics manufacturers in South America configure service models around format stability and channel-specific education needs. Collagen peptides require cold-chain logistics support in Brazil's interior, while gummy formats demand humidity-controlled storage protocols distinct from tablet distribution.
Product Type:
After-sales service intensity varies sharply across bioactive categories, with collagen peptides requiring stability monitoring and antioxidant formulations needing light-exposure management through final delivery.
- Collagen:Hydrolyzed peptide chains derived from bovine or marine sources dominate pharmacy-channel revenue through visible-results marketing. São Paulo metropolitan demand concentrates among millennial consumers seeking skin elasticity solutions, though ANVISA's novel ingredient rules extend validation timelines for new sourcing variants.
- Antioxidants:Polyphenol complexes from Brazilian açaí and green tea extracts command premium positioning through bioavailability claims. Rio de Janeiro's dermatology-influenced consumer base drives concentration here, constrained by batch-to-batch standardization challenges in natural extract sourcing.
- Vitamins:Lipid-soluble formulations (A, E, D) address systemic skin-health positioning with established safety dossiers easing ANVISA compliance.
- Minerals:Zinc and selenium complexes target nail and hair physiology segments with lower R&D substantiation burdens than novel botanicals.
Collagen holds the largest share; momentum sits with antioxidants as polyphenol clinical validation expands.
End User:
Cost tier stratification separates premium clinical-positioned products from mass-market accessibility plays across demographic segments.
- Female Consumers:Primary demand anchor across all South American markets, with Brazilian women aged 25-40 driving subscription-model adoption for skin-health regimens. São Paulo's digitally native cohort converts through influencer-curated discovery platforms.
- Age 18-25:Gummy format preference dominates this cohort, with flavor-masked delivery systems overcoming pill-regimen skepticism. Brazilian university corridors in Campinas and Curitiba show concentrated trial-to-repeat patterns.
- Male Consumers:Emerging segment concentrated in Brazilian fitness culture, with collagen positioned for recovery rather than beauty claims.
- Seniors:Pharmacy-channel reliance and pharmacist consultation preference define this group's procurement patterns, with joint-skin combined positioning gaining traction.
Female consumers command the dominant revenue pool; the 18-25 age bracket is expanding most quickly through format innovation.
Form:
Application suitability dictates manufacturing investment allocation, with beverage formats requiring aseptic filling capacity distinct from solid-dose equipment.
- Gummies:Gelatin or pectin-based matrices mask bioactive bitterness while enabling precise dosing. Brazilian millennial adoption concentrates in São Paulo's social-commerce channels, where subscription boxes drive trial conversion.
- Pills:Hard-shell capsules and tablets retain pharmacy-channel dominance through perceived clinical credibility and extended shelf stability.
- Powders:Collagen peptide concentrates appeal to fitness-adjacent positioning with flexible dosing protocols.
- Beverages:Ready-to-drink fortified formats require cold-chain infrastructure limiting distribution to Brazil's southeastern urban corridors.
Pills retain the largest installed base; gummies gain share fastest through generational format preference shifts.
Distribution Channel:
Geographic concentration patterns in Brazil's southeast determine channel prioritization, with São Paulo and Rio de Janeiro hosting overlapping physical and digital infrastructure.
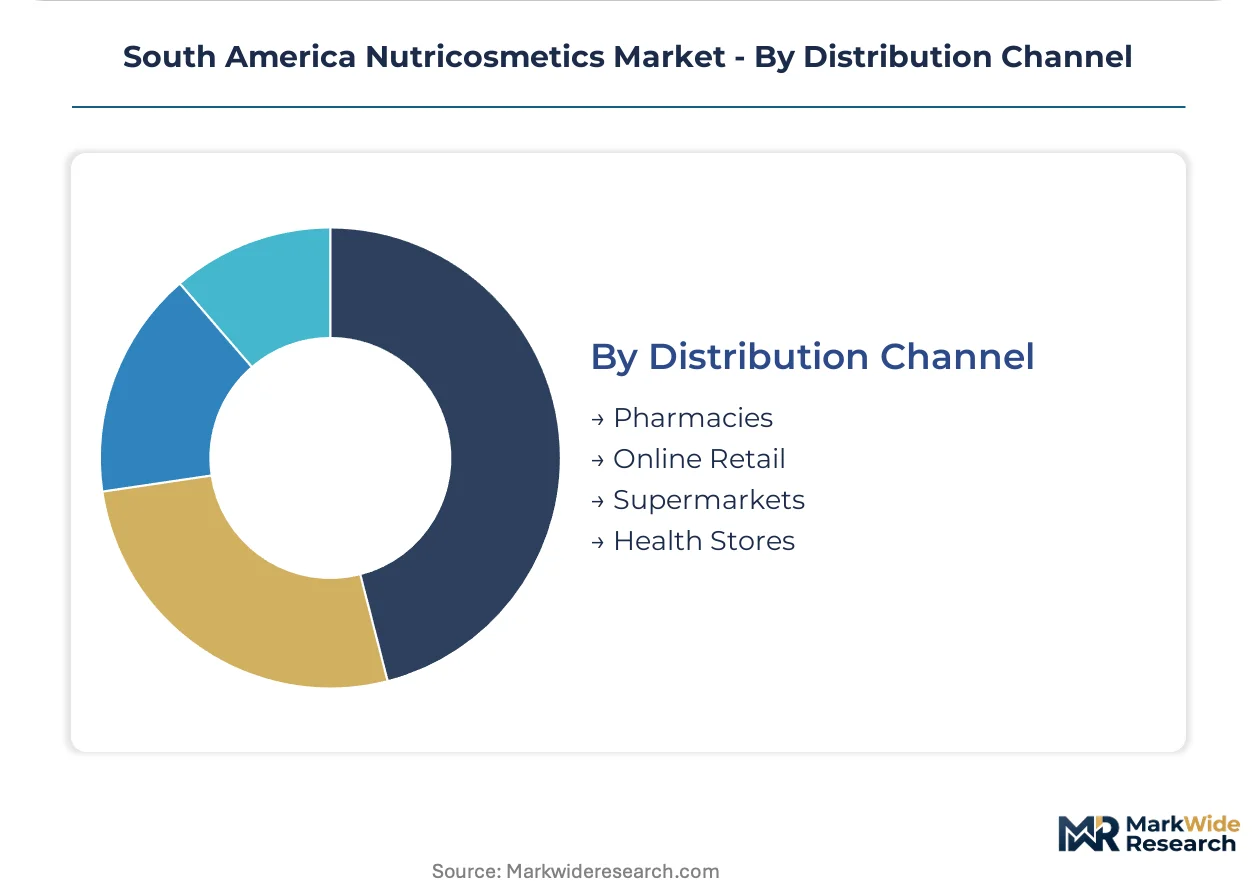
- Pharmacies:Pharmacist consultation enables premium price realization for clinically positioned collagen and antioxidant formulations. ANVISA's health-claim substantiation requirements reinforce this channel's credibility advantage.
- Online Retail:Subscription platforms and influencer-driven discovery erode pharmacy margins through auto-replenishment algorithms. São Paulo's digitally native consumer base concentrates here.
- Supermarkets:Mass-market vitamin and mineral positioning reaches budget-conscious segments with lower education requirements.
- Health Stores:Natural-product positioning for botanical antioxidants serves niche consumer segments in Brazil's affluent urban districts.
Pharmacies maintain the revenue concentration; online retail shows the steepest expansion trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collagen extraction and encapsulation capacity clusters in São Paulo state, with Brazilian manufacturers expanding micro-encapsulation facilities to serve pharmacy and digital channels across the continent.
Brazil
Millennial consumers aged 25-40 in São Paulo and Rio de Janeiro metropolitan corridors drive gummy format adoption through subscription platforms and influencer-curated discovery. ANVISA's tightened novel food ingredient rules extend validation timelines for new collagen sourcing variants. São Paulo state hosts expanded peptide encapsulation facilities stabilizing bioavailability for pharmacy distribution.
Argentina
Buenos Aires anchors demand for antioxidant polyphenol complexes targeting dermatology-influenced consumer segments with premium positioning. The national food regulator applies parallel but non-harmonized standards to Brazil's ANVISA framework, fragmenting compliance costs for cross-border brands. Pending Mercosur convergence talks could unify labeling standards and reduce duplicative documentation burdens.
Chile
Patagonian processors develop cosmetic-grade marine collagen hydrolysate capacity from fishery byproducts, offering supply chain resilience against bovine price volatility. The Ministry of Health governs novel ingredient approval with clinical-evidence thresholds similar to Brazilian requirements. Santiago's affluent urban districts concentrate health store distribution for natural-product positioning.
Colombia
Bogotá and Medellín urban centers replicate Brazilian community-based nutrition-club distribution models for supplement-beauty hybrid positioning. Direct-sales networks convert trial-to-repeat patterns through personalized regimen algorithms. Colombian regulatory frameworks for novel food ingredients remain less stringent than ANVISA, enabling faster product iteration for import-reliant entrants.
Peru
Lima's digitally native consumer base adopts subscription-based discovery models displacing traditional pharmacy counter sales among younger demographics. Social commerce integration outperforms conventional retail foot traffic in metropolitan corridors. Peruvian regulators apply developing frameworks for ingestible beauty claims, creating uncertainty for brands seeking systemic skin-health positioning.
South America Nutricosmetics Market Competitive Landscape
Direct-sales specialists and pharmaceutical-grade formulators split the market between community-based distribution credibility and clinical-validation authority. Brazilian players leverage domestic manufacturing scale against multinational nutrition brands importing finished formulations. Three archetypes dominate: beauty-retail hybrids with R&D anchoring, nutrition-club operators blurring supplement positioning, and pharmaceutical incumbents with established safety dossiers. Competitive moves concentrate on micro-encapsulation capacity expansion and cross-border regulatory harmonization partnerships.
Within the direct-sales tier, Natura & Co. and Herbalife Nutrition Ltd. exemplify community-based distribution models converting household penetration into repeat purchase loyalty. O Boticário occupies a position bridging beauty-retail heritage with bioactive peptide formulation science. These three anchors represent distinct strategic responses to ANVISA's clinical-substantiation requirements: captive R&D investment, nutrition-club channel control, and hybrid positioning between topical and ingestible beauty paradigms.
| Leading Market Players |
|---|
| Natura & Co. |
| O Boticário |
| Amway Corp. |
| Herbalife Nutrition Ltd. |
| Nestlé |
| Bayer AG |
| Integralmedica |
| Shiseido Company, Limited |
| Swisse |
| Others |
Value Network & Pricing Analysis
Bovine collagen concentration in Brazil's cattle-belt states feeds directly into margin distribution between São Paulo encapsulation facilities and pharmacy-channel brands. Raw material volatility from Asian gelatin processor demand pulls pricing power upstream, compressing formulator margins while subscription platforms capture downstream consumer surplus.
Pricing Analysis
ANVISA's health-claim substantiation requirements dictate the pricing tier structure across Brazilian nutricosmetics, separating clinically validated collagen peptides from unverified botanical extracts. Three-tier pricing structure across premium pharmacy-positioned, standard digital-subscription, and economy mass-market tiers reflects certification grade and pharmacist consultation bundling. Price erosion runs through the mass-market tier as supermarket vitamin-mineral positioning commoditizes basic formulations. Pharmacy-channel buyers show least price sensitivity due to consultation-derived trust, while digitally native millennials in São Paulo demonstrate highest elasticity to subscription discounting.
Supply Chain Analysis
São Paulo-based contract manufacturers including Integralmedica and regional peptide processors hold dominant encapsulation capacity for collagen and polyphenol stabilization. Brazil, Argentina, and Chile anchor geographic supply concentration, with Chilean Patagonian marine collagen hydrolysate diversifying bovine dependencies. Raw material inputs hinge on Brazilian cattle cycle conditions, açaí extract batch standardization, and imported gelatin precursor availability. Single-source vulnerability concentrates in bovine collagen supply during Asian export demand spikes. Distribution runs through pharmacy wholesale networks overlaid with direct-to-consumer subscription fulfillment centers in southeastern metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward digitally native millennials as subscription-platform consolidation concentrates demand aggregation. Pharmacy-channel fragmentation among independent operators weakens collective bargaining against branded formulators.
For Market Incumbents: Insulate pharmacy-channel premium positioning through captive micro-encapsulation capacity expansion in São Paulo state, defending against direct-to-consumer brands eroding consultation-derived price premiums. Deepen backward integration into Patagonian marine collagen sourcing to buffer bovine price cycle exposure. Prioritize ANVISA pre-submission dossier investment for novel antioxidant complexes to extend validation moats. For New Entrants and Emerging Players: Pursue Colombian and Peruvian nutrition-club white space where regulatory frameworks lag ANVISA stringency, enabling faster product iteration cycles. Target male fitness-adjacent collagen positioning in Brazilian metropolitan centers, a segment with minimal incumbent saturation. Deploy influencer-curated subscription boxes as the primary go-to-market vehicle to bypass pharmacy-channel credibility barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-sales networks possessing captive distributor relationships but lacking clinical-validation infrastructure. Long-term viability favors platforms integrating subscription technology with pharmacy-channel credibility across the analysis window. Acquisition targets should demonstrate cross-border Mercosur compliance capabilities. Monitor ANVISA regulatory convergence talks as the signal for cross-border scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Capacity Expansion | São Paulo facilities stabilize collagen bioavailability for pharmacy-channel premium positioning against conventional nutraceuticals. |
| Marine Collagen Supply Diversification | Patagonian hydrolysate sourcing reduces exposure to Brazilian cattle cycle volatility and Asian gelatin processor demand spikes. |
| Direct-to-Consumer Subscription Launch | Influencer-curated auto-replenishment platforms capture millennial trial-to-repeat conversion in São Paulo's digitally native base. |
| Regulatory Harmonization Partnership | Cross-border Mercosur compliance integration enables Brazilian manufacturers to scale into Argentina without duplicative validation costs. |
| Nutrition-Club Channel Replication | Community-based distribution models in Colombian and Peruvian urban centers blur supplement-beauty positioning for household penetration. |
Research Methodology
The analysis maps collagen peptide, antioxidant polyphenol, vitamin, and mineral sub-sectors, each validated through brand managers at Natura & Co. and O Boticário, pharmacy procurement leads in São Paulo and Rio de Janeiro, and ANVISA regulatory affairs specialists. Secondary sources include ANVISA novel food ingredient filings, Brazilian customs trade data for gelatin imports, and pharmacy-channel Nielsen retail audit data. Bottom-up demand modeling from consumer segmentation triangulates against top-down manufacturer capacity estimates.
Assumptions held fixed include ANVISA regulatory stringency levels and Mercosur trade framework continuity, while variables tested include bovine collagen input price trajectories and digital-channel adoption elasticity. The projection horizon spans product-type, form, end-user demographic, and distribution channel dimensions, with CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate pharmacy-channel foot traffic indices and social commerce engagement metrics from Brazilian metropolitan consumer panels.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or consumer discretionary spending indices would shift the trajectory of import-reliant premium positioning. Forecasts reflect documented assumptions around regulatory approval timelines and raw material supply continuity. Quarterly review of ANVISA novel ingredient submission queues and Asian gelatin export customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
US Nutraceuticals Market