
 Fire Sprinkler Systems Market | 2026-2036
Fire Sprinkler Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Sprinkler Systems Market Analytics
Data center construction is repositioning the commercial installation segment toward higher-density suppression architectures. Johnson Controls leverages its building automation integration to anchor large-scale hyperscale contracts. Minimax GmbH & Co. KG sustains engineering-intensive pre-action system dominance across European industrial facilities. Viking Group specializes in marine and offshore sprinkler variants where corrosion-resistant alloys command durable specification loyalty.
Fire sprinkler systems constitute pressurized networks of pipes, valves, and thermally activated discharge heads designed to suppress or control fire development through controlled water distribution at specified flow rates and coverage densities. Wet pipe configurations retain water-filled delivery lines for immediate discharge upon fusible element activation, serving as the default specification for climate-controlled commercial and residential structures. Dry pipe systems lead in unheated warehousing and cold-storage applications where freeze protection governs specification, while pre-action architectures capture premium margins in data centers and cultural heritage institutions demanding accidental-discharge immunity. Deluge systems occupy specialized industrial niches involving flammable liquid storage and chemical processing where rapid total-flooding response overrides water damage concerns.
National Fire Protection Association standards, European EN 12845 framework, and India's BIS fire safety codes collectively mandate minimum sprinkler coverage across expanding building categories and occupancy types. These regulatory layers directly shape product certification requirements, installer licensing thresholds, and inspection intervals that determine market access and recurring revenue streams. Stakeholders must monitor evolving green building integration mandates that tie suppression system efficiency to broader sustainability certification schemes.
Market Dynamics
Data center hyperscale construction is compressing specification cycles and forcing pre-action system dominance across commercial portfolios, while NFPA 13 and EN 12845 revisions simultaneously tighten performance thresholds and certification burdens.
Growth Catalysts
- India BIS mandate expansion:Urban fire safety requirements now penetrate tier-two industrial zones beyond Mumbai and Delhi corridors, creating installation volume in warehousing and manufacturing parks.
- Pre-action architecture demand:Data center operators specify accidental-discharge-immune systems to protect server infrastructure, displacing wet-pipe defaults in climate-controlled hyperscale facilities.
- Corrosion-resistant alloy specification:Marine and offshore platforms require specialized sprinkler variants that withstand salt-laden environments, locking in premium procurement for coastal installations.
Market Restraints
- Copper and brass input volatility:Sprinkler head manufacturing depends on non-ferrous metal supply chains subject to commodity price swings that compress fabricator margins.
- Certified installer scarcity:NFPA and EN licensing thresholds limit qualified contractor pools, creating bottlenecks in high-growth markets where inspection intervals are mandated.
- Dry pipe technical limitations:Unheated warehousing applications face delayed discharge constraints that restrict specification in rapid-response environments.
Strategic Opportunities
- European green building integration:CSRD and EU Green Deal tie suppression system efficiency to sustainability certification schemes, creating specification pull for low-flow, high-density architectures.
- Smart building convergence:IoT-enabled sprinkler networks integrating with building automation platforms open recurring revenue streams through predictive maintenance contracts.
- Heritage institution retrofit:Cultural properties in Western Europe demand invisible pre-action systems that preserve architectural integrity while meeting EN 12845 coverage mandates.
Industry Challenges
- NFPA 13D versus 13R code fragmentation:Residential sprinkler standards vary by occupancy type, forcing manufacturers to maintain redundant product lines and certification documentation.
- Legacy steel pipe integration:Retrofit projects face mechanical compatibility constraints when threading modern sprinkler heads into decades-old distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Sprinkler Systems Market |
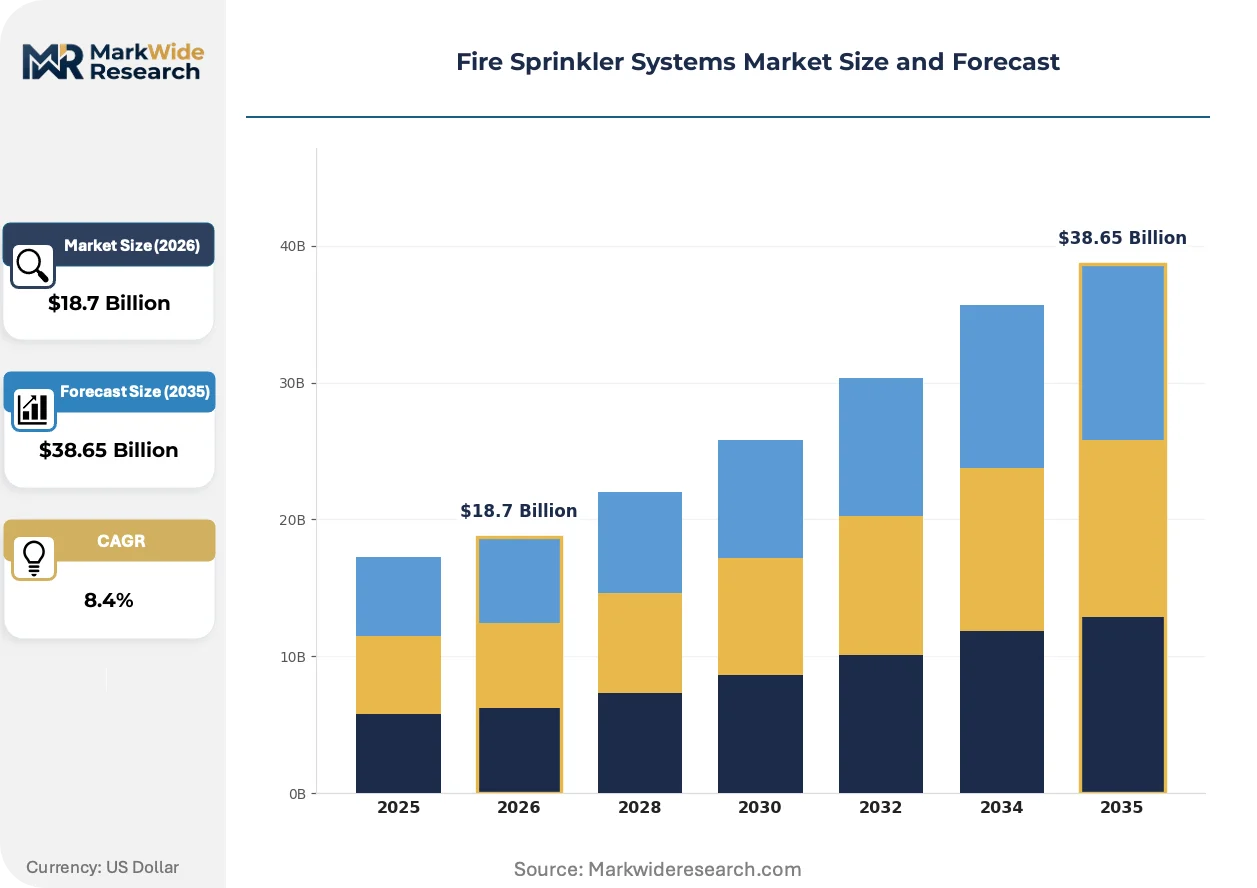
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Pre-Action, Deluge Installation Type: Residential, Commercial, Industrial, Institutional Control Method: Manual, Automatic, Hybrid, Pneumatic End User: Hospitality, Warehousing, Manufacturing, Education |
| Companies Covered | Victaulic Company, Minimax GmbH & Co. KG, Johnson Controls, Siemens AG, Hochiki Corporation, Reliable Automatic Sprinkler, Honeywell International, API Group, Viking Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Sprinkler Systems Market Evolving Landscape
Intelligent suppression architectures are displacing passive systems across high-value installations, while regulatory harmonization efforts compress regional specification variance and procurement digitization accelerates distributor consolidation.
Antifreeze-loop technology is rewriting cold-storage protection protocols by eliminating dry-pipe delays in sub-zero environments. Frozen food distribution centers in the upper Midwest United States and Nordic Europe are specifying propylene-glycol systems that maintain immediate discharge capability at negative temperatures. This chemistry is compressing dry-pipe dominance in refrigerated warehousing and forcing incumbent manufacturers to reformulate head designs.
REACH chemical restrictions are reshaping European sprinkler component supply chains by phasing out legacy solder alloys containing lead and cadmium. Manufacturers must recertify fusible elements under EN 12845 protocols using bismuth-tin substitutes that alter activation temperature precision. German industrial facilities face the tightest compliance deadlines, driving accelerated R&D cycles among regional component suppliers.
Specification bundling is consolidating procurement authority among mechanical-electrical-plumbing contractors who now control sprinkler selection within integrated building packages. Distributor relationships are shifting from product stocking to specification influence, with national MEP firms in the United States and United Kingdom centralizing vendor qualification across multi-site portfolios. Data center developers are the most aggressive adopters, leveraging volume concentration to demand extended warranty terms and dedicated engineering support.
Fire Sprinkler Systems Market Segmentation
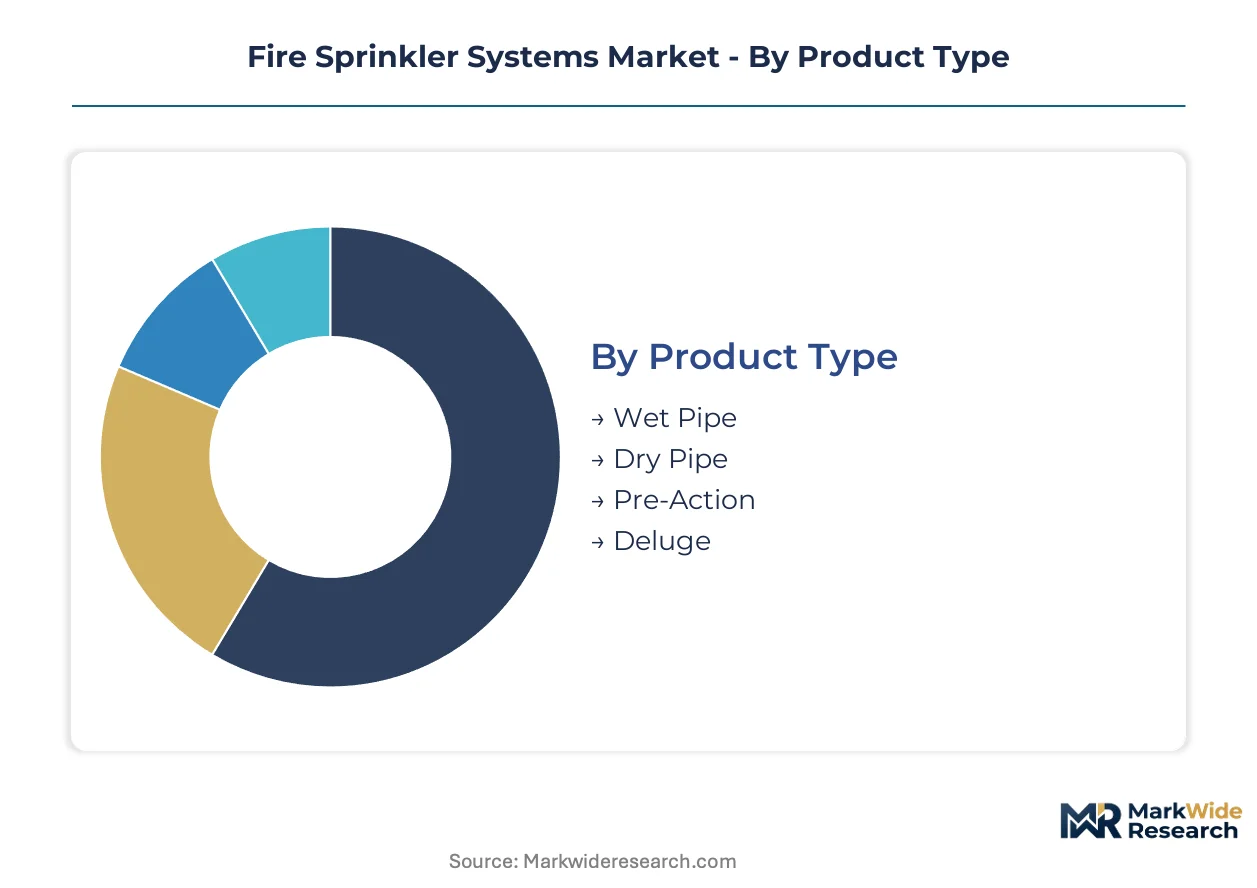
Fire sprinkler system segmentation reveals how specification logic varies across thermal environments, occupancy risk profiles, and discharge reliability requirements. Procurement patterns diverge sharply between climate-controlled commercial buildings and freeze-exposed industrial facilities, with each segment commanding distinct engineering standards and margin structures.
Product Type:
Upgrade cycles in fire suppression infrastructure follow building renovation timelines and code revision enforcement, with replacement demand accelerating where older architectures fail revised performance thresholds.
- Wet Pipe:Water-filled distribution lines deliver immediate discharge upon fusible element activation, making this the default specification for climate-controlled commercial and residential structures. Demand concentrates in United States multi-family housing developments where NFPA 13R mandates are tightening coverage requirements in new construction corridors.
- Pre-Action:Dual-interlock architectures require both detection system activation and sprinkler head thermal response before water enters pipes, eliminating accidental discharge risk. Data center operators across Northern Virginia and Frankfurt specify these systems to protect server infrastructure, displacing wet-pipe defaults despite higher installation costs.
- Dry Pipe:Pressurized air or nitrogen fills distribution lines until thermal activation releases the gas and admits water, serving unheated warehousing and cold-storage applications where freeze protection governs specification.
- Deluge:Open sprinkler heads and rapid total-flooding discharge characterize these systems, occupying specialized niches in flammable liquid storage and chemical processing facilities where water damage concerns yield to fire containment priorities.
Volume placements concentrate in Wet Pipe configurations; the faster expansion belongs to Pre-Action architectures.
Installation Type:
Cost tier differentiation separates specification complexity, with premium engineering support commanding higher margins in specialized institutional and industrial deployments compared to standardized residential rollouts.
- Commercial:Office complexes, retail centers, and hospitality properties specify systems balancing coverage density with aesthetic integration, driving demand for concealed head designs and building automation integration. Installation volumes cluster in Indian metro corridors where BIS enforcement is expanding beyond Mumbai and Delhi into tier-two industrial zones.
- Industrial:Manufacturing plants and heavy processing facilities require corrosion-resistant alloys and specialized discharge densities calibrated to commodity fire risks. European chemical processing clusters along Germany's Rhine corridor sustain premium specification cycles for deluge and pre-action variants.
- Residential:Single-family and multi-family dwellings increasingly face municipal sprinkler mandates in jurisdictions adopting NFPA 13D and 13R standards, though cost sensitivity limits specification to basic wet-pipe configurations.
- Institutional:Healthcare facilities, educational campuses, and government buildings demand redundant suppression layers and extended warranty terms, with procurement centralized through mechanical-electrical-plumbing contractor bundles.
Commercial installations generate the highest absolute volumes; industrial applications deliver the steepest margin expansion.
Control Method:
Application-specific reliability requirements determine whether passive thermal activation suffices or active detection integration becomes mandatory, with hybrid architectures gaining traction where single-mode systems prove inadequate.
- Automatic:Thermally activated heads operate without human intervention, serving as the baseline specification across residential and standard commercial portfolios where immediate response outweighs false-discharge concerns.
- Hybrid:Combined thermal and electronic detection layers reduce accidental activation risk in high-value environments, capturing specification in data centers and cultural heritage institutions.
- Manual:Human-activated suppression remains limited to specialized industrial niches where controlled discharge timing overrides automation benefits.
- Pneumatic:Air-pressure-based detection systems serve explosive atmospheres and electrically sensitive environments where electronic components pose ignition risks.
Automatic systems dominate placement volumes; hybrid configurations are climbing the fastest as asset protection requirements intensify.
End User:
Customer-type procurement patterns reveal how occupancy risk profiles and regulatory exposure shape specification sophistication, with hospitality and warehousing segments diverging sharply on aesthetic and functional priorities.
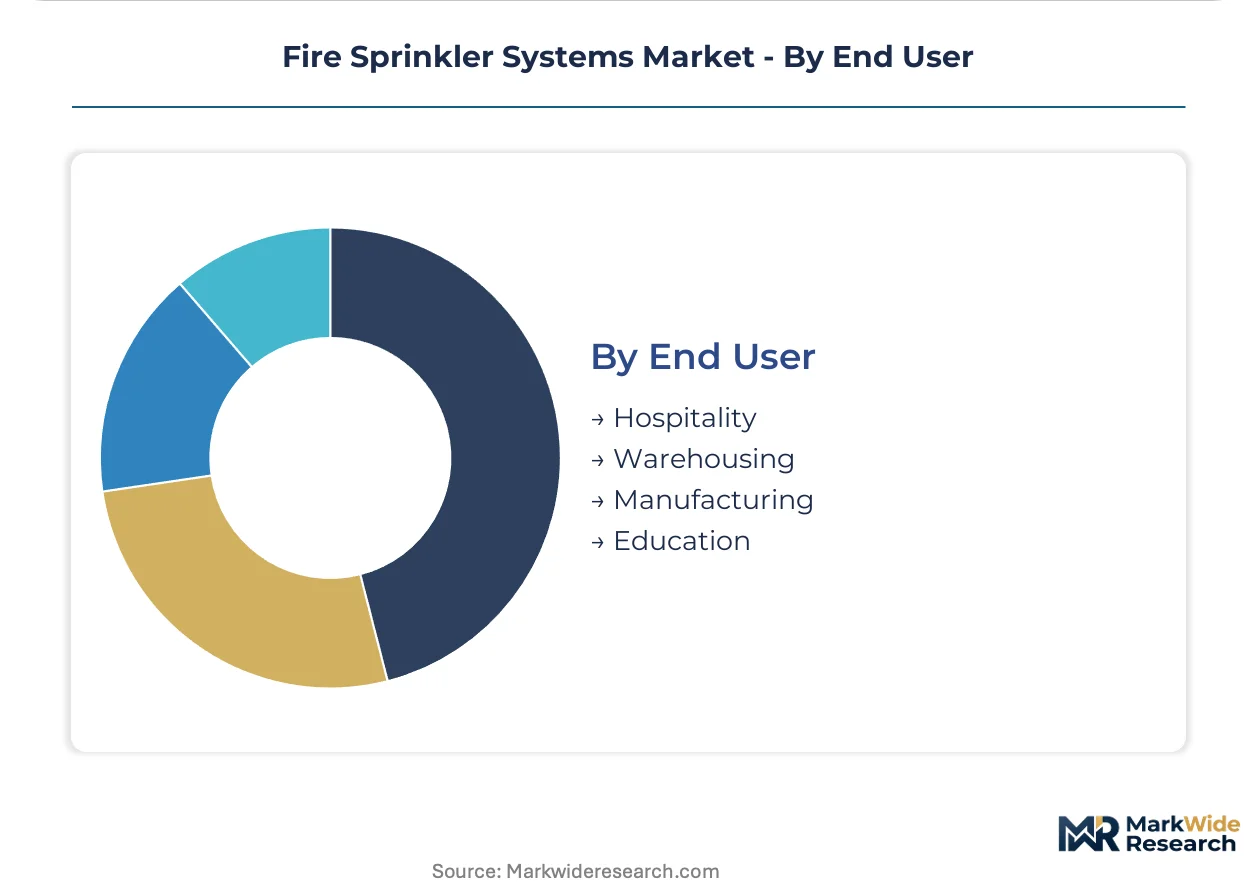
- Warehousing:Cold-storage and ambient distribution centers specify dry-pipe or antifreeze-loop systems to address freeze protection, with Indian logistics parks driving installation growth as e-commerce fulfillment networks expand into tier-two cities.
- Manufacturing:Process-intensive facilities require customized suppression architectures calibrated to specific commodity fire classes, sustaining engineering-intensive procurement relationships with specialized system integrators.
- Hospitality:Hotels and resorts prioritize concealed head designs and rapid aesthetic restoration capabilities, accepting premium pricing for finishes that preserve interior design integrity.
- Education:School and university campuses face municipal retrofit mandates in jurisdictions with aging infrastructure, generating replacement-cycle demand for systems compatible with legacy steel pipe networks.
Warehousing commands the largest project scale; manufacturing applications are gaining share fastest as process safety regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate fire sprinkler procurement as warehousing and data center investments accelerate under India's PLI scheme incentives. Tax-advantaged industrial corridors in these states anchor installation volume expansion through 2035.
United States
Hyperscale data center construction across Northern Virginia and Dallas-Fort Worth compresses specification cycles toward pre-action architectures. NFPA 13 code revisions tighten performance thresholds for commercial installations. Phoenix and Atlanta logistics corridors drive wet-pipe replacement demand as municipal retrofit mandates expand.
Germany
Chemical processing clusters along the Rhine corridor sustain premium engineering-intensive procurement for deluge and pre-action variants. REACH chemical restrictions force bismuth-tin alloy recertification of fusible elements under EN 12845 protocols. Bavarian automotive manufacturing parks specify corrosion-resistant sprinkler networks for paint-shop fire protection.
India
BIS fire safety mandates penetrate tier-two industrial zones beyond Mumbai and Delhi into Pune and Chennai manufacturing corridors. Urban fire safety requirements now cover warehousing and logistics parks under expanded commercial building codes. Hyderabad and Bengaluru data center clusters drive pre-action system specification for server infrastructure protection.
United Kingdom
Heritage institution retrofit demand concentrates in London and Western European cultural properties requiring invisible pre-action systems. EN 12845 coverage mandates accelerate specification for concealed head designs preserving architectural integrity. Manchester and Birmingham commercial developments integrate building automation-linked sprinkler networks.
China
GB standards enforcement tightens across Yangtze River Delta logistics hubs and Pearl River Delta manufacturing zones. Dual carbon goals tie suppression system efficiency to green building certification schemes in Shanghai and Shenzhen. Cold-storage expansion in northern provinces drives antifreeze-loop technology specification.
Fire Sprinkler Systems Market Competitive Landscape
Top-tier vendors anchor specification influence through building automation integration, while mid-tier fabricators compete on regional certification speed and installer network density. The vendor base stratifies across three functional tiers: systems integrators with MEP bundling power, component specialists commanding alloy and activation technology premiums, and regional installers competing on inspection compliance velocity. Two dominant competitive moves shape positioning: strategic partnerships with data center developers for multi-site volume contracts, and backward integration into corrosion-resistant alloy foundries to secure marine and offshore specification.
Within the systems integration tier, Johnson Controls and Siemens AG occupy positions defined by building automation convergence capabilities. Minimax GmbH & Co. KG exemplifies the European engineering-intensive archetype with pre-action system specialization. Viking Group represents the marine-offshore corrosion-resistant segment where specification loyalty locks around salt-environment performance. These three anchors illustrate how competitive positioning fragments across integration depth, regional code mastery, and application-specific metallurgy rather than scale alone.
| Leading Market Players |
|---|
| Victaulic Company |
| Minimax GmbH & Co. KG |
| Johnson Controls |
| Siemens AG |
| Hochiki Corporation |
| Reliable Automatic Sprinkler |
| Honeywell International |
| API Group |
| Viking Group |
| Others |
Value Network & Pricing Analysis
Backward integration into corrosion-resistant alloy foundries anchors supply security for marine and offshore specification while simultaneously locking in premium pricing power against commodity-grade competitors. This captive metallurgy capability separates tier-one systems integrators from fabricators exposed to copper and brass spot market volatility.
Pricing Analysis
Short lead-time premiums compress pricing spreads between spot inventory holders and engineered-to-order specialists serving data center developers. Three-tier pricing structure across pre-action, wet-pipe, and dry-pipe certification levels reflects installation complexity and after-sales engineering bundling. Pricing pressure stems from certified installer scarcity forcing subcontractor margin absorption. Residential developers exhibit highest price sensitivity while hyperscale data center operators prioritize discharge reliability over unit economics.
Supply Chain Analysis
Refurbishment flows for legacy steel pipe networks create reverse logistics complexity in education and heritage retrofit segments. Manufacturing concentrates in Germany, China, and India for fusible element fabrication and sprinkler head assembly. Raw material inputs draw from Chilean copper, Chinese brass billet, and Nordic stainless steel. Single-source vulnerability sits with bismuth-tin alloy suppliers facing REACH recertification deadlines. Distribution runs through mechanical-electrical-plumbing contractor bundles controlling multi-site specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where NFPA 13 and EN 12845 certification investments erect barrier-to-entry moats protecting incumbent market positions from commodity fabrication entrants.
For Market Incumbents: Cement specification influence through building automation integration partnerships with hyperscale data center developers pursuing multi-site volume contracts. Expand captive corrosion-resistant alloy production to defend marine and offshore premium positioning against Chinese fabricators exploiting raw material cost advantages. Prioritize installer network density in Indian tier-two industrial zones where BIS enforcement is accelerating faster than qualified contractor supply. For New Entrants and Emerging Players: Begin with antifreeze-loop technology specialization targeting cold-storage retrofit demand in upper Midwest United States and Nordic Europe where dry-pipe displacement creates white-space. Focus initial penetration on warehousing end-users in Indian logistics parks where e-commerce fulfillment expansion outpaces incumbent service capacity. Pursue specification bundling partnerships with regional mechanical-electrical-plumbing contractors seeking differentiated suppression offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by building automation conglomerates seeking fire suppression integration capabilities. Long-term viability favors engineering-intensive pre-action specialists over commodity wet-pipe fabricators facing margin compression. Monitor CSRD and EU Green Deal implementation velocity as the inflection signal for green building-integrated suppression specification pull.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Foundries | Captive corrosion-resistant metallurgy secures marine specification loyalty against spot-market competitors. |
| Building Automation Platform Integration | Johnson Controls and Siemens leverage MEP bundling power to anchor hyperscale data center contracts. |
| Antifreeze-Loop Technology Development | Propylene-glycol systems displace dry-pipe dominance in sub-zero warehousing across Nordic markets. |
| Installer Network Density Expansion | Certified contractor scarcity in Indian tier-two zones creates first-mover specification capture opportunity. |
| REACH-Compliant Fusible Element Recertification | Bismuth-tin alloy transition locks German suppliers into accelerated R&D investment cycles. |
Research Methodology
NFPA technical committee filings, EN standard revision drafts, and BIS regulatory gazettes formed the secondary backbone validating code-driven demand assumptions. Primary interviews with fire protection engineers, mechanical-electrical-plumbing procurement directors, data center facilities managers, and certified sprinkler contractors cross-checked specification trend direction. Customs data on copper alloy imports and construction permit databases supplied volume triangulation anchors. Bottom-up installation unit estimates reconciled against top-down building stock penetration models.
Bottom-up modeling of wet-pipe, pre-action, dry-pipe, and deluge system placements by control method and end-user vertical fed into aggregate value derivation across the analysis window. Segmentation dimensions spanned product architecture, installation type, activation mechanism, and regional regulatory cluster. CAGRs emerged from fitting logistic adoption curves to code enforcement timelines and construction pipeline data. Hyperscale data center capex trajectories and Indian PLI scheme warehousing incentives served as industry-specific demand drivers.
Copper price volatility, NFPA 13 revision implementation delays, and Indian installer certification bottlenecks are the dominant revision risks threatening volume assumptions. Forecasts embed construction cycle timing and regulatory enforcement intensity as core sensitivities. Practitioners should monitor base metal futures, code adoption jurisdiction maps, and tier-two Indian contractor licensing rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
North America Particle Board Market
Construction and Engineering
Cut-To-Length Line Systems Market
Construction and Engineering
Industrial Air Heaters Market
Construction and Engineering
Asia-Pacific Flanges Market
Construction and Engineering
Australia Conveyor Maintenance Market
Construction and Engineering
Hollow Concrete Block Market
Construction and Engineering
China Power Tools and Hand Tools Market
Construction and Engineering
UK Residential Construction Market
Construction and Engineering
Drilling Machine Market
Construction and Engineering
Drywall Tool Market
Construction and Engineering
Bathroom Remodeling Market
Construction and Engineering
Steel Bolts and Nuts Market
Construction and Engineering
Variable Refrigerant Flow (VRF) System Market
Construction and Engineering
Europe Metal Fabrication Equipment Market
Construction and Engineering
Pressure Pumping Services Market
Construction and Engineering
Spain Cement Market