
 Closed Cell Polyurethane Foam Market | 2026-2036
Closed Cell Polyurethane Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Closed Cell Polyurethane Foam Market Analysis
A capital-intensity divergence between integrated petrochemical producers and regional fabricators is bifurcating competitive dynamics across the value chain. BASF SE leverages its upstream polyol and isocyanate capabilities to sustain margin capture from raw material through finished foam systems. Huntsman International LLC anchors its position through specialized rigid foam formulations targeting appliance and construction insulation. Wisconsin Foam Products competes on custom fabrication speed and regional logistics for industrial gasketing and packaging applications.
Closed cell polyurethane foam consists of a thermoset polymer matrix with gas-filled cells that remain discrete and unconnected, typically achieving densities between 1.5 and 50 pounds per cubic foot depending on formulation chemistry and blowing agent selection. Its primary commercial purpose centers on thermal insulation, structural buoyancy, and moisture barrier protection across building envelopes, refrigerated transport, and marine flotation devices. Rigid foam dominates value contribution in construction and cold-chain applications where compressive strength and dimensional stability command specification premiums. Flexible foam occupies significant share in automotive seating and furniture cushioning where comfort index and fatigue resistance drive selection criteria. Specialty foam segments concentrate margin pools in aerospace gasketing and medical device packaging where certification burdens limit supplier entry.
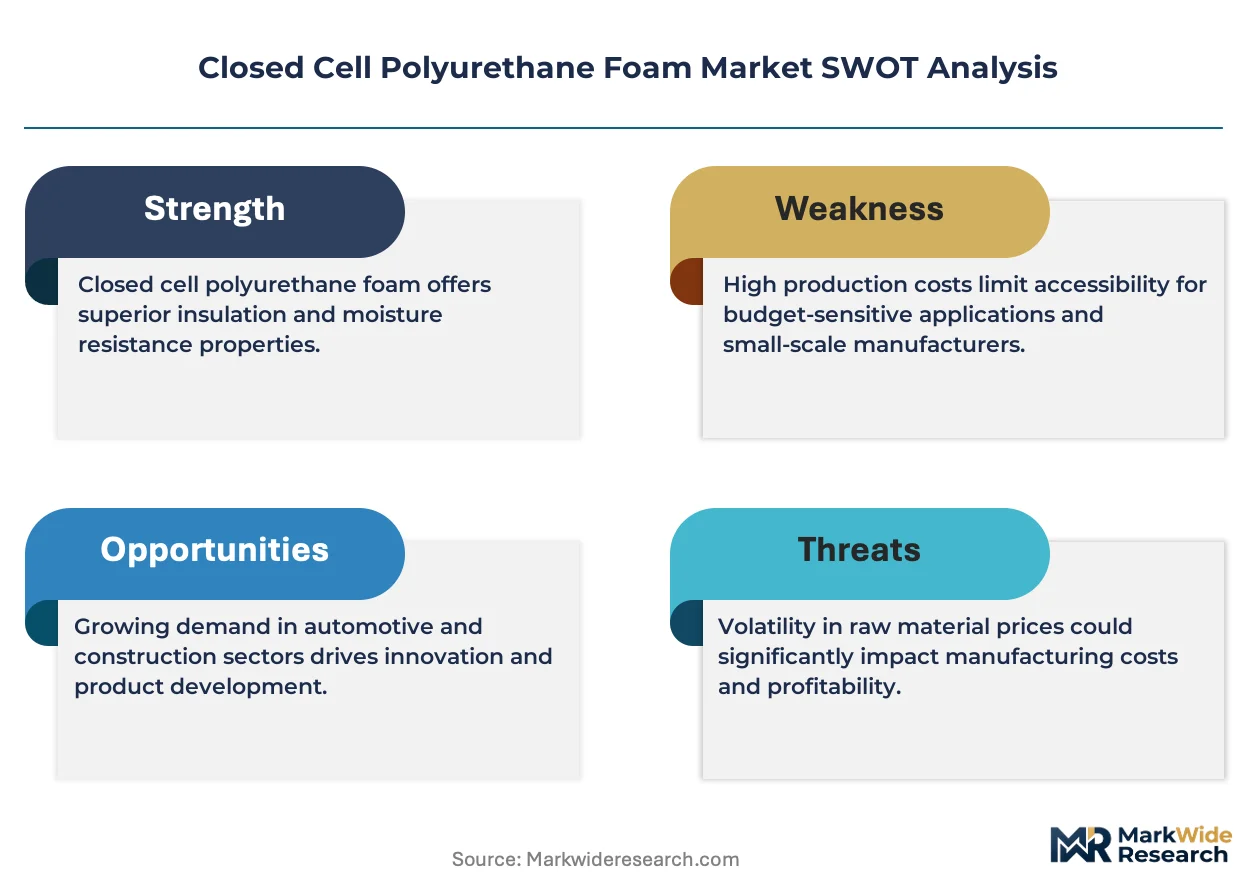
The US EPA regulates hydrofluorocarbon blowing agents under the AIM Act, driving transition toward lower-GWP alternatives across domestic manufacturing. REACH and the EU F-Gas Regulation impose parallel constraints on European producers, reshaping formulation chemistry and equipment capital requirements. California Title 24 and similar state-level energy codes extend these pressures through prescriptive insulation performance standards. Stakeholders must monitor blowing agent transition timelines and regional compliance certification to align product portfolios with divergent regulatory clocks.
Market Dynamics
The transition from hydrofluorocarbon to hydrofluoroolefin blowing agents is forcing simultaneous reformulation of polyurethane chemistry and capital retooling across manufacturing footprints, compressing margins for non-integrated producers while advantaging those with captive polyol supply.
Growth Catalysts
- Building envelope retrofit mandates:Germany's KfW funding programs and national renovation rate targets accelerate specification of high-R-value rigid foam in residential and commercial wall assemblies.
- Cold-chain infrastructure expansion:Refrigerated transport and warehouse construction across North America and Europe drives demand for moisture-resistant insulation with dimensional stability under thermal cycling.
- REACH and F-Gas Regulation compliance:European chemical frameworks are accelerating adoption of lower-GWP blowing agent formulations, creating specification premiums for certified foam systems.
Market Restraints
- Isocyanate supply concentration:MDI production capacity clusters in China, Germany, and the United States, exposing fabricators to feedstock volatility and logistics disruption.
- Technical performance trade-offs:Lower-GWP hydrofluoroolefin formulations often sacrifice lambda values versus legacy HFC-245fa systems, compressing thermal efficiency in thickness-constrained assemblies.
- Substitution by mineral wool:Stone wool and glass wool insulation capture share in fire-critical commercial applications where non-combustibility ratings override polyurethane's thermal superiority.
Strategic Opportunities
- Underpenetrated Indian construction:India's Bureau of Indian Standards energy code adoption and commercial real estate expansion create first-mover positioning for rigid foam in curtain wall and roofing systems.
- Marine flotation and buoyancy:Offshore wind farm installation vessels and aquaculture infrastructure demand closed-cell foam with saltwater resistance and long-term compressive creep resistance.
- California Title 24 extensions:Prescriptive R-value requirements and cool roof mandates in the state's energy code accelerate premium foam specification in multi-family residential envelopes.
Industry Challenges
- Blowing agent transition timeline compression:EPA AIM Act phase-down schedules and state-level HFC restrictions require simultaneous product recertification and equipment replacement.
- Formulation chemist scarcity:Specialized expertise in thermoset polymer kinetics and blowing agent solubility modeling concentrates among senior technical staff at integrated producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closed Cell Polyurethane Foam Market |
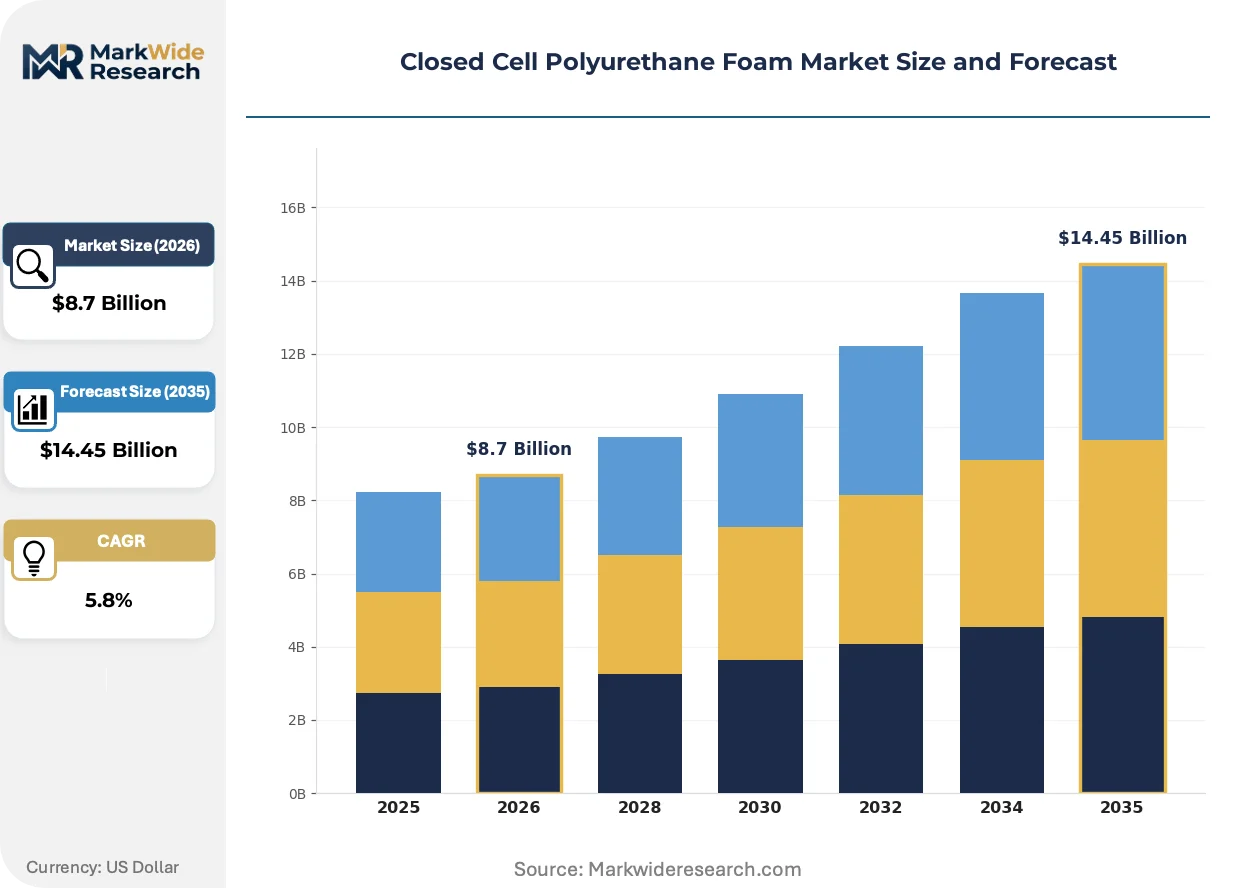
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Specialty Foam, High-Density Foam Application: Insulation, Seating, Packaging, Soundproofing End User: Construction, Automotive, Furniture, Aerospace Density: Low Density, Medium Density, High Density, Ultra High Density |
| Companies Covered | 3M, Armacell International S.A, BASF SE, Huntsman International LLC, Sekisui Chemical Co., Ltd, Wisconsin Foam Products, Ramfoam Ltd, Cellofoam North America Inc, Lapolla Industries, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closed Cell Polyurethane Foam Market Emerging Trajectories
Formulation chemistry and manufacturing process control are converging to address thermal performance, environmental compliance, and end-of-life recovery simultaneously. Three developments are restructuring competitive positioning.
Water-blown and hydrocarbon-blown rigid foam systems are bifurcating the construction insulation segment. Cold-storage warehouse developers and passive house builders are specifying these alternatives to meet near-zero-GWP targets. This technology transition is compressing margins for producers locked into transitional HFO blends while rewarding those with multi-blowing-agent platform flexibility.
The US EPA's AIM Act implementation and parallel EU F-Gas Regulation amendments are mandating stepped reductions in HFC consumption across foam blowing applications. Domestic manufacturers face 2025-2027 compliance deadlines requiring capital investment in alternative formulations and process controls. Appliance insulation and spray foam contractors in California and Northeast corridor states are experiencing earliest specification pressure due to state-level HFC prohibitions.
Building owners and general contractors are consolidating procurement around certified passive house and net-zero-ready envelope packages. This specification bundling displaces commodity foam purchasing through distributor channels. Germany and Austria exhibit the most advanced adoption, where energy performance contracting models tie contractor compensation to measured thermal bridging performance rather than installed product volume.
Closed Cell Polyurethane Foam Market Segmentation
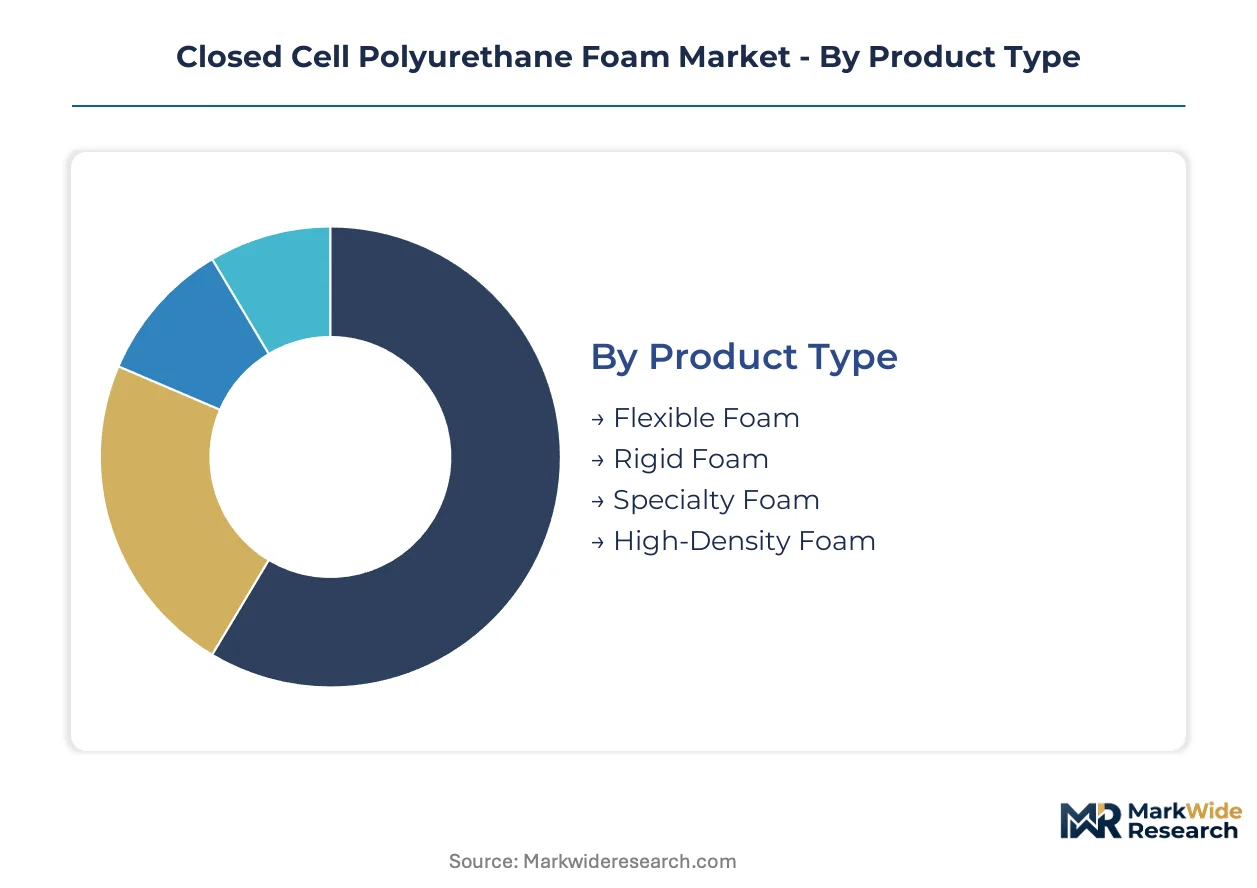
Segmentation in closed cell polyurethane foam reveals distinct margin structures and regulatory exposure profiles. Product chemistry and density specifications determine which segments face capital-intensive reformulation versus steady specification demand.
Product Type:
Flexible foam concentrates in domestic automotive and furniture manufacturing clusters across Germany, the United States, and Japan. Rigid foam serves export-led construction and cold-chain infrastructure with standardized thermal performance certifications.
- Rigid Foam:Thermoset polymer matrix with discrete gas-filled cells achieving densities between 1.5 and 50 pounds per cubic foot depending on blowing agent selection. Demand concentrates in German building envelope retrofits and North American refrigerated warehouse construction where compressive strength and dimensional stability command specification premiums. KfW funding programs and EPA AIM Act compliance deadlines accelerate specification of certified rigid foam systems.
- Flexible Foam:Open-cell or semi-closed-cell structures prioritizing comfort index and fatigue resistance over thermal performance. Automotive seating manufacturers in Stuttgart, Detroit, and Toyota City anchor procurement volumes; furniture cushioning demand clusters in domestic consumption markets with limited cross-border trade.
- Specialty Foam:Aerospace gasketing and medical device packaging segments where certification burdens limit supplier entry.
- High-Density Foam:Marine flotation and industrial gasketing applications requiring saltwater resistance and long-term compressive creep resistance.
Rigid foam holds the largest share; momentum sits with specialty foam as certification requirements tighten.
Application:
Cost tier differentiation separates specification-grade insulation from commodity cushioning and protective packaging.
- Insulation:Thermal barrier applications across building envelopes and refrigerated transport where lambda values and moisture resistance drive selection. Germany's national renovation rate targets and California Title 24 prescriptive R-value requirements accelerate demand for high-performance rigid foam in wall and roof assemblies.
- Packaging:Protective cushioning for electronics and medical devices where density consistency and static dissipation properties matter.
- Seating:Automotive and furniture comfort applications prioritizing indentation force deflection and dynamic fatigue performance.
- Soundproofing:Architectural acoustics and industrial noise control where absorption coefficients and fire ratings determine specification.
Insulation dominates value contribution; packaging expands most quickly as e-commerce fulfillment drives protective foam consumption.
End User:
Customer type determines procurement sophistication — construction and aerospace specify through certified envelope packages while furniture and automotive rely on tiered supplier relationships.
- Construction:Building envelope and cold-chain infrastructure where energy performance contracting models tie contractor compensation to measured thermal bridging performance. Germany and Austria exhibit the most advanced adoption of certified passive house and net-zero-ready envelope packages.
- Automotive:Seating, interior trim, and NVH applications where OEMs consolidate procurement around comfort index specifications and recyclability mandates.
- Furniture:Residential and commercial cushioning where domestic manufacturing clusters serve regional consumption markets.
- Aerospace:Gasketing, insulation, and structural components where FAA and EASA certification requirements limit qualified supplier pools.
Construction holds the largest share; aerospace shows the steepest expansion trajectory as offshore wind installation vessels drive marine flotation demand.
Density:
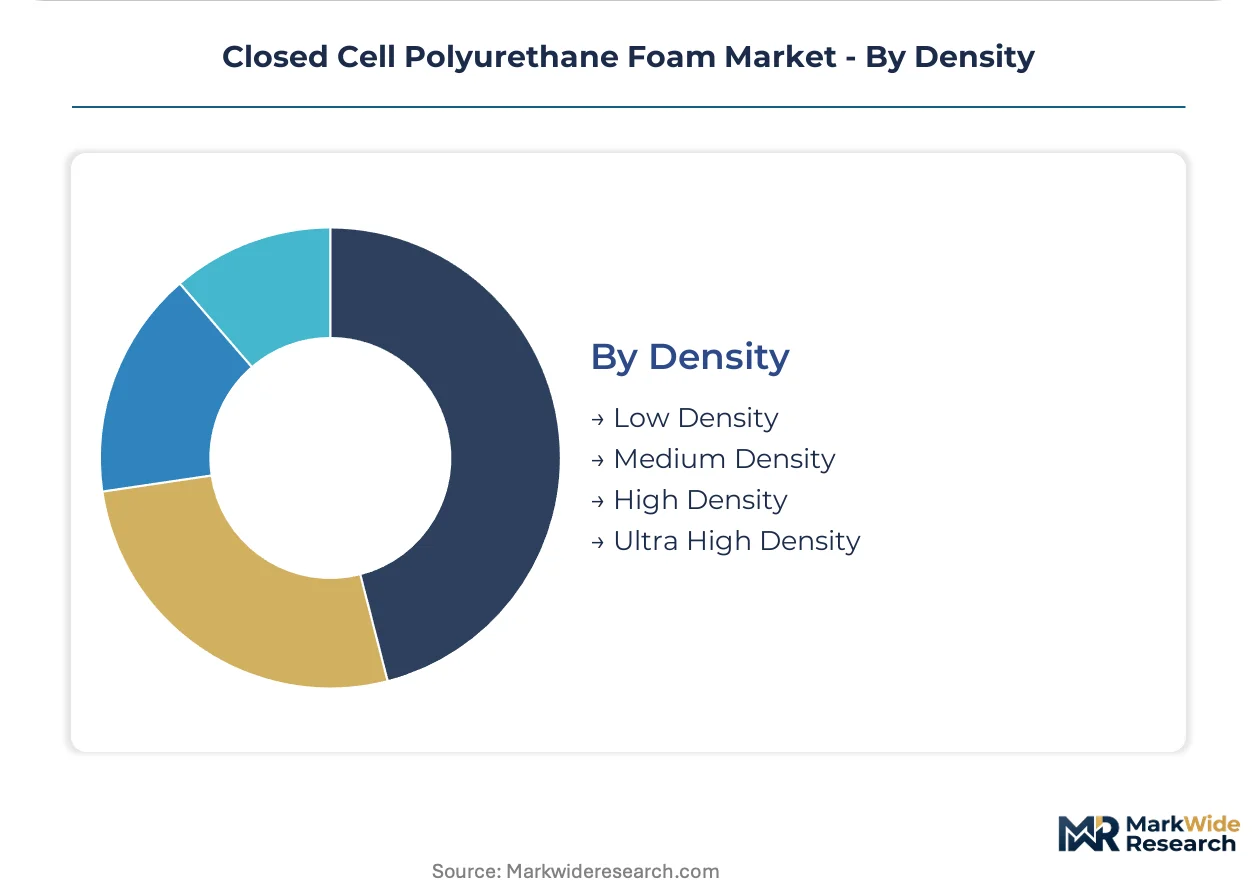
Volume concentration sits with medium-density formulations serving automotive and furniture applications; margin pools concentrate in ultra-high-density segments.
- Medium Density:Automotive seating and furniture cushioning where comfort index and fatigue resistance drive selection criteria. Production clusters in Germany, the United States, and Japan serve domestic OEM and furniture manufacturer demand.
- High Density:Industrial gasketing and protective packaging where compression set resistance and dimensional stability matter.
- Low Density:Spray foam insulation and lightweight packaging applications where cost per board foot dominates procurement decisions.
- Ultra High Density:Marine flotation, aerospace structural components, and medical device packaging where long-term compressive creep resistance and certification burdens limit supplier entry.
Medium density holds the largest share; ultra high density gains share fastest as offshore wind farm installation vessels and aquaculture infrastructure expand specification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in closed cell polyurethane foam track divergent regulatory clocks and construction cycles across major economies. Net exporters cluster where integrated petrochemical complexes feed downstream foam fabrication, while import dependence concentrates in markets lacking captive isocyanate capacity.
United States
Refrigerated warehouse construction across Texas and the Southeast drives rigid foam consumption for cold-chain infrastructure. The EPA's AIM Act mandates stepped HFC phase-downs through 2027, forcing simultaneous reformulation and equipment retooling. Houston and the Gulf Coast petrochemical corridor anchor MDI supply, insulating domestic fabricators from feedstock volatility.
Germany
KfW funding programs and national renovation rate targets accelerate specification of high-R-value rigid foam in residential retrofits. REACH and the EU F-Gas Regulation impose parallel constraints on blowing agent chemistry, reshaping formulation standards. The Rhine-Ruhr industrial cluster concentrates rigid foam production for export to neighboring European markets.
China
Commercial real estate expansion and cold-storage infrastructure buildout sustain import demand for specialty foam grades despite domestic MDI overcapacity. GB standards for building energy efficiency tighten specification requirements in tier-one cities. The Yangtze River Delta manufacturing belt hosts the highest concentration of flexible foam production for automotive seating.
India
Bureau of Indian Standards energy code adoption creates first-mover positioning for rigid foam in curtain wall and roofing systems. Commercial real estate expansion in Mumbai and Bangalore outpaces domestic foam fabrication capacity, sustaining import flows. Gujarat's chemical manufacturing corridor is attracting greenfield polyurethane system house investments.
Japan
Automotive OEM consolidation around electrification platforms reshapes demand for NVH and seating foam formulations. METI efficiency standards for commercial buildings accelerate high-performance insulation specification in Tokyo and Osaka redevelopment projects. The Nagoya industrial corridor maintains specialized flexible foam production for Toyota and Honda supply chains.
Closed Cell Polyurethane Foam Market Vendor Landscape
Concentration sits with integrated petrochemical producers commanding captive polyol and isocyanate supply. The vendor base separates into three archetypes: multinational chemical conglomerates with upstream integration, regional system houses competing on formulation speed, and custom fabricators serving niche industrial applications. Dominant competitive moves include backward integration into blowing agent distribution and portfolio diversification across rigid, flexible, and specialty foam grades.
Among integrated chemical producers, BASF SE and Huntsman International LLC exemplify the upstream-anchored archetype, while Wisconsin Foam Products occupies a position within the custom fabrication tier. Sekisui Chemical Co., Ltd represents the Asia-Pacific system house model. Each archetype faces distinct margin pressure from the HFC-to-HFO transition timeline.
| Leading Market Players |
|---|
| 3M |
| Armacell International S.A |
| BASF SE |
| Huntsman International LLC |
| Sekisui Chemical Co., Ltd |
| Wisconsin Foam Products |
| Ramfoam Ltd |
| Cellofoam North America Inc |
| Lapolla Industries, Inc |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day polyol inventory cycles at German system houses compress margin buffers when MDI spot volatility spikes, binding pricing power to feedstock security and captive isocyanate access across the value chain.
Pricing Analysis
The customization-premium spread separates configured-to-order rigid foam systems for passive house envelopes from standard slabstock for commodity insulation. Three-tier pricing structure across certified, transitional, and legacy blowing-agent grades anchors differentiation, with EPA AIM Act compliance tiers commanding premiums over HFC-based formulations. Cost compression in non-integrated fabrication tiers intensifies because captive polyol producers capture margin upstream. Cold-storage developers exhibit lowest price sensitivity; residential retrofit contractors face acute pressure from thickness-constrained assembly economics.
Supply Chain Analysis
Inbound logistics costs on Asia-Europe MDI trade lanes fluctuate with container availability at Shanghai and Rotterdam, exposing fabricators to freight volatility when Chinese petrochemical complexes schedule maintenance turnarounds. Supply concentrates in China, Germany, and the United States for isocyanate feedstock; polyol production clusters in the US Gulf Coast and Rhine-Ruhr corridor. Formulation chemistry draws from aromatic isocyanates, polyether polyols, and blowing agent blends. Single-source vulnerability concentrates in MDI capacity concentrated among three global producers. Distribution runs through regional system houses that blend and fabricate to specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The closed cell polyurethane foam market sits as a high-growth disruption justified by the EPA AIM Act and EU F-Gas Regulation forcing simultaneous reformulation across installed manufacturing capacity.
For Market Incumbents: Fortify captive isocyanate positions through backward integration into MDI supply or long-term offtake agreements with Chinese and German producers. Deepen certification investment in lower-GWP formulations ahead of state-level HFC prohibitions in California and the Northeast corridor. Mineral wool substitution in fire-critical commercial applications threatens rigid foam share; defend through enhanced fire-retardant formulation R&D. For New Entrants and Emerging Players: Lead with water-blown and hydrocarbon-blown rigid foam platforms targeting India's Bureau of Indian Standards energy code adoption in Mumbai and Bangalore commercial real estate. Marine flotation for offshore wind installation vessels offers penetrable white space with saltwater-resistance specifications. Pursue joint development agreements with European passive house envelope packagers to bypass distributor channel consolidation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because blowing-agent transition timelines create durable specification premiums for certified producers. Acquisition targets include regional system houses with multi-blowing-agent platform flexibility and established KfW or Title 24 certification pathways. Monitor EPA enforcement actions on HFC phase-down timelines as inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | Captive MDI access insulates margin capture from feedstock volatility at Ludwigshafen and Baytown complexes. |
| Multi-Blowing-Agent Platform Investment | Flexibility across HFO, hydrocarbon, and water-blown formulations aligns with divergent regulatory clocks in US and EU. |
| Passive House Certification Partnership | Energy performance contracting models in Germany and Austria displace commodity purchasing through bundled envelope packages. |
| Marine Flotation Specialty Capacity | Offshore wind farm installation vessels and aquaculture infrastructure demand saltwater-resistant ultra-high-density grades. |
| Indian Greenfield System House | Gujarat chemical corridor investments capture first-mover positioning under Bureau of Indian Standards energy code adoption. |
Methodological Framework
A standing panel of rigid foam plant managers, construction procurement leads at general contractors, cold-chain infrastructure developers, and technical R&D directors at system houses provided ongoing calibration across primary fieldwork. Secondary validation drew from US EPA AIM Act filings, EU F-Gas Regulation amendment tracking, customs data on MDI trade flows, and SEC disclosures from integrated chemical producers. Bottom-up volume modeling across product grades triangulated against top-down construction spending and cold-storage investment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by foam chemistry, density specification, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating energy code stringency indices and renovation rate targets. Forecast inputs included KfW funding program allocations, California Title 24 adoption timelines, and Indian commercial real estate pipeline data.
The analysis sits within stated boundaries; outcomes outside assumed regulatory enforcement schedules, construction cycle continuity, and blowing-agent transition cost curves would require recalibration. Forecasts reflect documented assumptions on MDI capacity expansion, REACH compliance cost pass-through, and mineral wool substitution elasticity. Raw material price volatility, trade policy shifts on Chinese chemical exports, or accelerated HFC phase-downs could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
High-Density Polyethylene (HDPE) Resins Market