
 Biometric Smart Cards Market | 2026-2036
Biometric Smart Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Smart Cards Market Insights
Market Context with Strategic Players
PSD2 is restructuring the competitive landscape for biometric card vendors by mandating strong customer authentication for electronic payments. IDEMIA leverages its integrated secure-element manufacturing to control supply chain costs for European issuers. Fingerprint Cards AB anchors the sensor module segment through dedicated foundry partnerships and reduced die-size architectures. Thales Group differentiates via dual-interface product lines that bridge legacy contact infrastructure with contactless biometric terminals.
Technical Definition and Structural Segments
Biometric smart cards embed fingerprint, iris, or facial-recognition sensors within ISO/IEC 7810-compliant card bodies, pairing live biometric capture with on-card secure-element matching to authenticate cardholder identity at the point of transaction without cloud dependency. Contactless product types are capturing premium positioning as transit operators and retail banks prioritize tap-and-go speed with biometric fallback, while dual-interface variants retain volume share among institutions with mixed terminal estates. Fingerprint recognition technology dominates engineering investment due to mature sensor miniaturization and established liveness-detection algorithms, whereas iris recognition occupies niche high-assurance applications in government credentialing programs where false-acceptance rates must fall below one in a million.
Regulatory Frame and Forward Outlook
EMA, ECHA, and the EU AI Act collectively shape biometric smart card deployment by governing data-protection standards, material restrictions for card substrates, and algorithmic transparency requirements for automated identification systems. The EU Green Deal further pressures manufacturers to eliminate halogenated flame retardants and shift toward recycled PVC or polylactic acid substrates. Stakeholders must monitor whether national data-protection authorities interpret biometric template storage as falling within GDPR's special-category processing, as this determination will dictate whether on-card matching architectures receive preferential regulatory treatment over cloud-dependent alternatives.
Market Dynamics
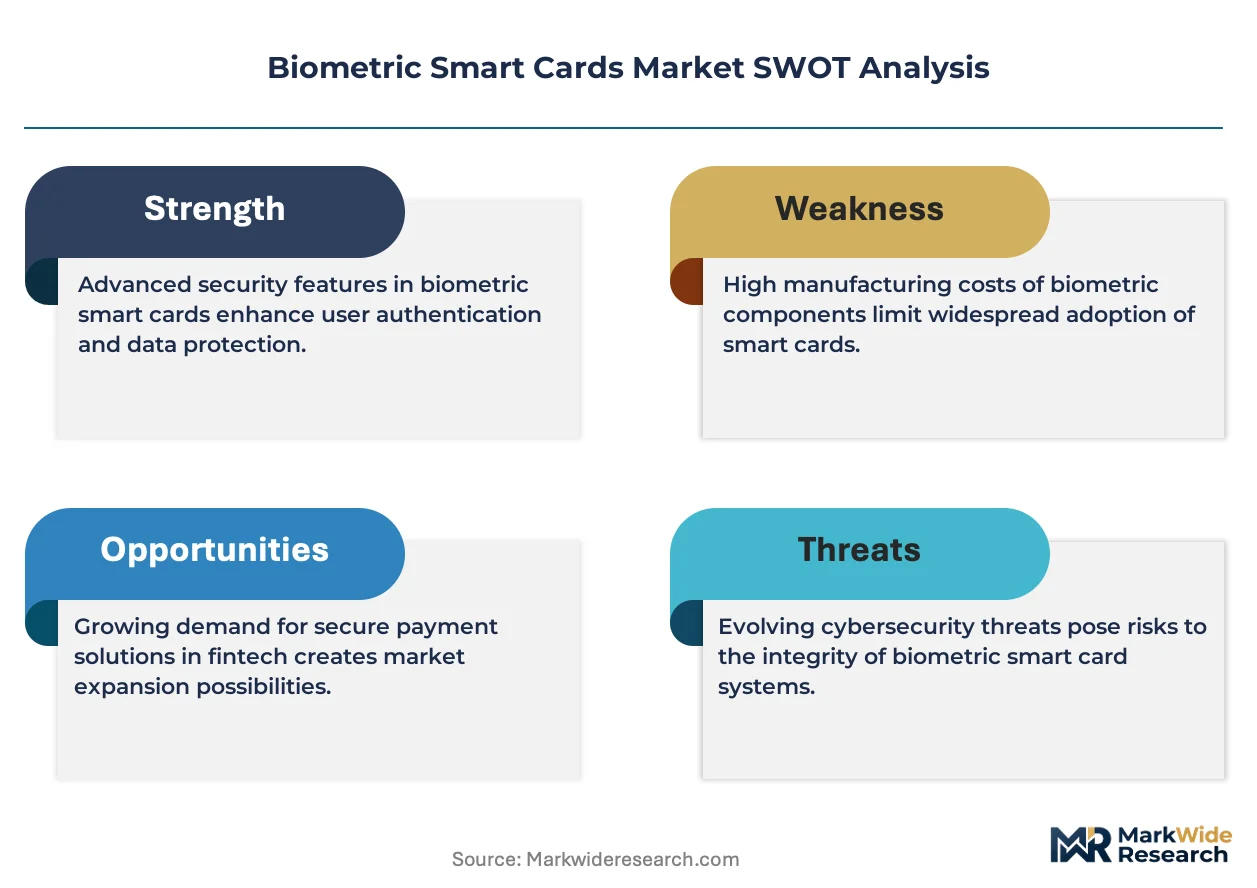
The EU AI Act's risk-classification framework for biometric systems is compressing vendor certification timelines while forcing architectural pivots toward on-card template storage to avoid cloud-dependent compliance burdens.
Growth Catalysts
- PSD2 Strong Customer Authentication:The EU directive mandates multi-factor verification for electronic payments above threshold limits, creating mandatory pull for fingerprint-enabled credentials among retail banks.
- Contactless Transit Infrastructure:Transport operators in France, Germany, and the United Kingdom are upgrading fare gates to accept biometric fallback, expanding addressable card volume beyond banking.
- Halogen-Free Substrate Mandates:The EU Green Deal's material restrictions are accelerating migration to recycled PVC and polylactic acid card bodies, favoring suppliers with certified green supply chains.
Market Restraints
- Secure-Element Supply Concentration:Advanced microcontroller fabrication for payment-grade elements clusters among a limited set of European and Asian foundries, creating input bottlenecks during demand surges.
- GDPR Special-Category Uncertainty:National data-protection authorities have not uniformly ruled whether on-card biometric templates trigger Article 9 processing requirements, chilling issuer rollout timelines.
- Terminal Estate Heterogeneity:Legacy contact-only infrastructure at smaller merchants blocks dual-interface card deployment, fragmenting addressable transaction volume.
Strategic Opportunities
- Government Credentialing Programs:High-assurance national ID schemes in France and Germany present volume anchors for iris-recognition cards with sub-one-in-a-million false-acceptance specifications.
- Healthcare Access Cards:Hospital systems are piloting biometric patient identification to eliminate duplicate records, opening a channel outside traditional payment networks.
- Sensor-Module Cost Compression:Reduced die-size architectures from dedicated foundry partnerships are narrowing the premium against standard EMV cards, enabling mass-market issuer trials.
Industry Challenges
- Biometric Algorithm Certification:EMA and national data-protection authorities maintain divergent testing protocols for liveness detection, forcing vendors to maintain multiple evaluation tracks.
- Legacy Core Banking Integration:Issuers must reconcile on-card authentication with decades-old authorization switches, requiring middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Smart Cards Market |
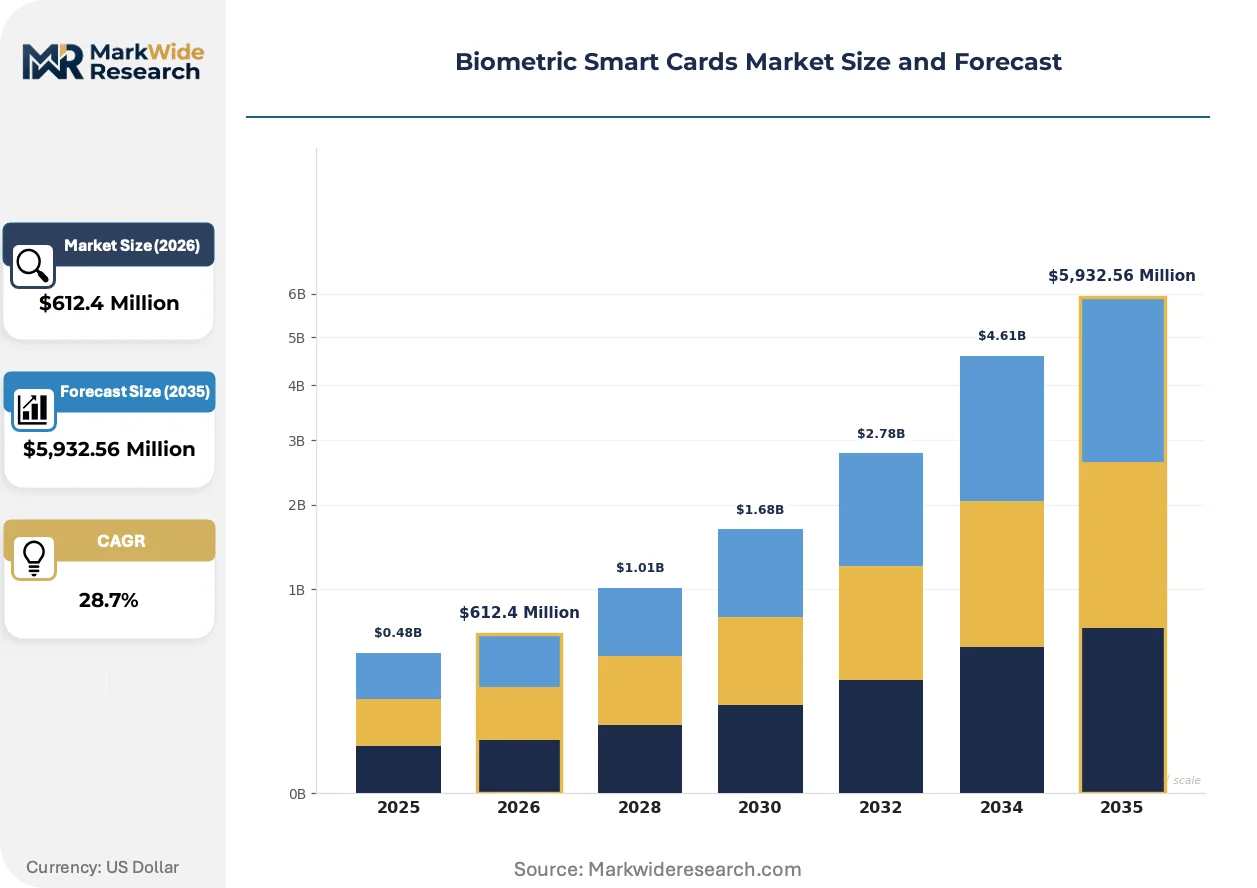
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $5,932.56 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact, Contactless, Dual-interface, Hybrid Technology: Fingerprint Recognition, Iris Recognition, Facial Recognition, Voice Recognition End User: Government, Banking, Retail, Healthcare Form Factor: Card, Key Fob, USB Device, Wearable |
| Companies Covered | IDEMIA, Thales Group, Fingerprint Cards AB, IDEX Biometrics, HID Global, NXP Semiconductors, CardLogix Corporation, Mastercard, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Smart Cards Market Trends and Innovations
Engineering investment is bifurcating between cost-optimized fingerprint modules for retail banking and high-assurance multimodal systems for government credentials, with substrate chemistry and power harvesting emerging as parallel innovation fronts.
Ultrathin flexible fingerprint sensors are rewriting the physical envelope of payment cards, enabling embedded modules that preserve ISO/IEC 7810 compliance without embossing distortion. Tier-one issuers in Germany and the United Kingdom are qualifying these sensors for 2026 portfolio refreshes. The technology is compressing the traditional trade-off between biometric security and card durability.
REACH substance restrictions are forcing substrate reformulation across European manufacturing, with ECHA's candidate list expansion targeting halogenated flame retardants used in legacy PVC card bodies. Manufacturers are accelerating polylactic acid and recycled PETG qualification to maintain CE marking access. Dual-interface card variants face the steepest retesting burden due to antenna substrate compatibility requirements.
Hospital procurement departments are unbundling biometric patient-identification cards from enterprise EMR contracts, creating direct purchasing relationships with specialized card vendors. French and German health networks are piloting this model to reduce duplicate-record rates. The shift is most visible in university hospital systems with independent IT governance structures.
Biometric Smart Cards Market Segmentation
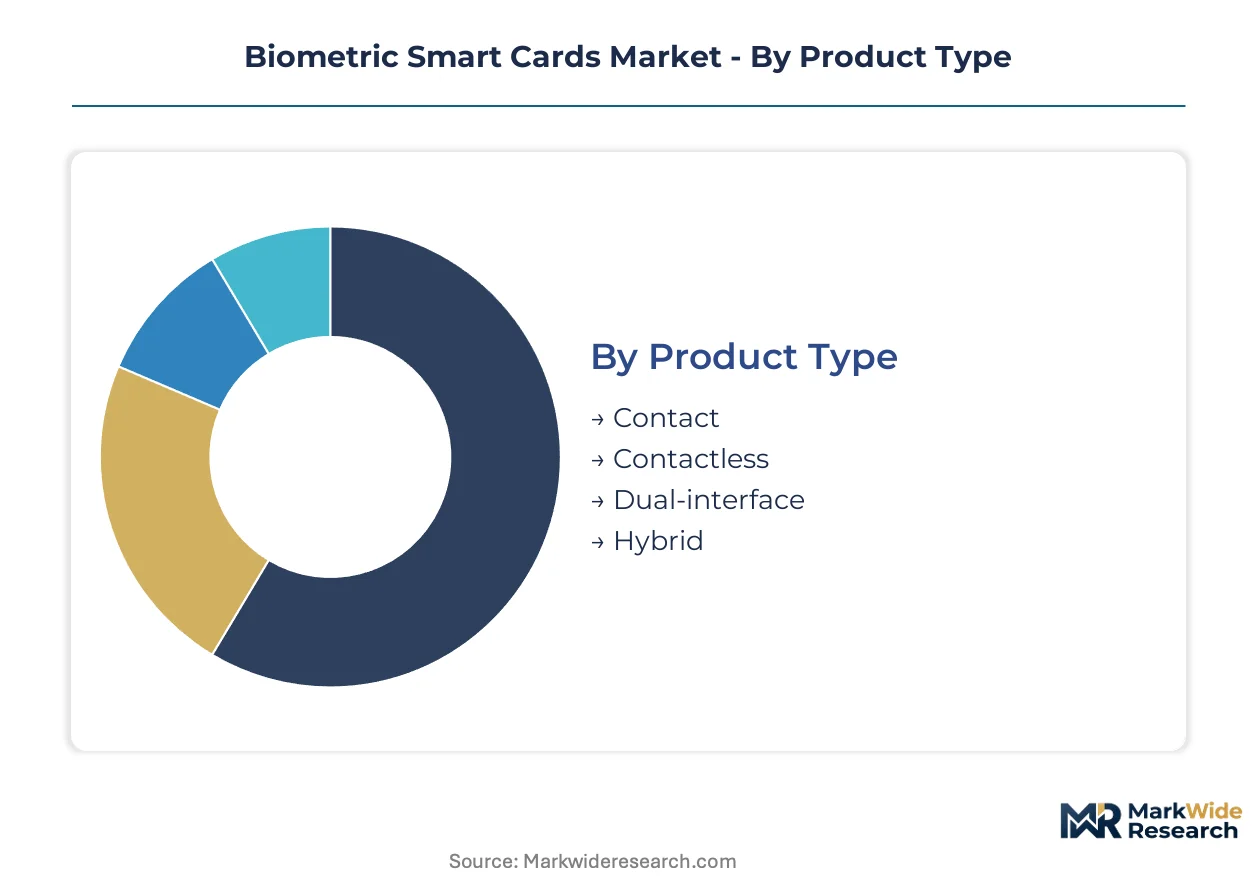
Biometric smart card segmentation reveals how payment infrastructure heterogeneity, authentication assurance requirements, and substrate material constraints fragment procurement decisions across European issuers. Each dimension carries distinct certification burdens and supply chain implications.
Product Type:
Issuers select product types based on terminal estate composition and transaction speed requirements, with legacy infrastructure protection driving dual-interface adoption while transit operators push pure contactless formats.
- Contact:Physical chip-and-sensor architectures requiring terminal insertion persist in markets with high fraud tolerance and low contactless penetration. German regional banks with aging ATM fleets maintain contact-only portfolios to avoid terminal replacement cycles.
- Contactless:Tap-and-go biometric cards with NFC-enabled sensors dominate French and UK transit-integrated banking products. Transport for London's fare gate certification requirements are accelerating EMV contactless biometric qualification timelines across European issuers.
- Dual-interface:Bridging legacy contact infrastructure with contactless capability, these variants capture volume among institutions with mixed merchant terminal estates. ECHA substrate compatibility testing creates retesting bottlenecks for antenna-embedded designs.
- Hybrid:Multi-protocol cards combining biometric authentication with magnetic stripe fallback serve transitional markets with bimodal terminal acceptance. UK card personalization bureaus are qualifying hybrid substrates for phased EMV migration programs.
Dual-interface cards lead volumes today; contactless variants are gaining share fastest.
Technology:
Technology selection trades sensor miniaturization maturity against false-acceptance rate specifications, with fingerprint modules achieving cost parity faster than multimodal alternatives.
- Fingerprint Recognition:Mature capacitive and ultrasonic sensor miniaturization enables sub-0.4mm module thickness without ISO/IEC 7810 embossing distortion. Dedicated foundry partnerships for reduced die-size architectures are narrowing cost premiums against standard EMV cards.
- Iris Recognition:Near-infrared imaging systems with sub-one-in-a-million false-acceptance rates occupy high-assurance government credentialing. France's national ID program specifications are anchoring iris module procurement volumes.
- Facial Recognition:Embedded camera modules with 3D depth sensing remain cost-prohibitive for payment card form factors. German automotive fleet card pilots represent the primary near-term demand channel.
- Voice Recognition:Microphone-integrated cards with speaker verification algorithms face power harvesting constraints in ISO-compliant envelopes. UK neobank pilot programs are testing voice-biometric fallback for telephone banking integration.
Fingerprint recognition leads volumes today; iris recognition climbs the fastest in government verticals.
End User:
End-user procurement patterns diverge sharply on certification stringency, with government tenders mandating Common Criteria EAL6+ while retail banks optimize for EMVCo compliance speed.
- Government:National credentialing programs demand multimodal biometric systems with algorithmic transparency documentation under EU AI Act risk-classification frameworks. German federal procurement specifications are setting de facto European standards for high-assurance card architectures.
- Banking:Retail issuers prioritize PSD2 strong customer authentication compliance with single-factor biometric fallback for contactless transactions. French banking consortium pilots are standardizing fingerprint-on-card specifications for 2026 portfolio refreshes.
- Retail:Merchant-issued loyalty and private-label payment cards are adopting biometric authentication to reduce chargeback liability. UK supermarket financial services divisions represent early trial volume.
- Healthcare:Hospital patient identification cards are unbundling from enterprise EMR contracts, creating direct procurement relationships with specialized vendors. French university hospital systems with independent IT governance are piloting biometric duplicate-record elimination.
Banking leads volumes today; healthcare is gaining share fastest.
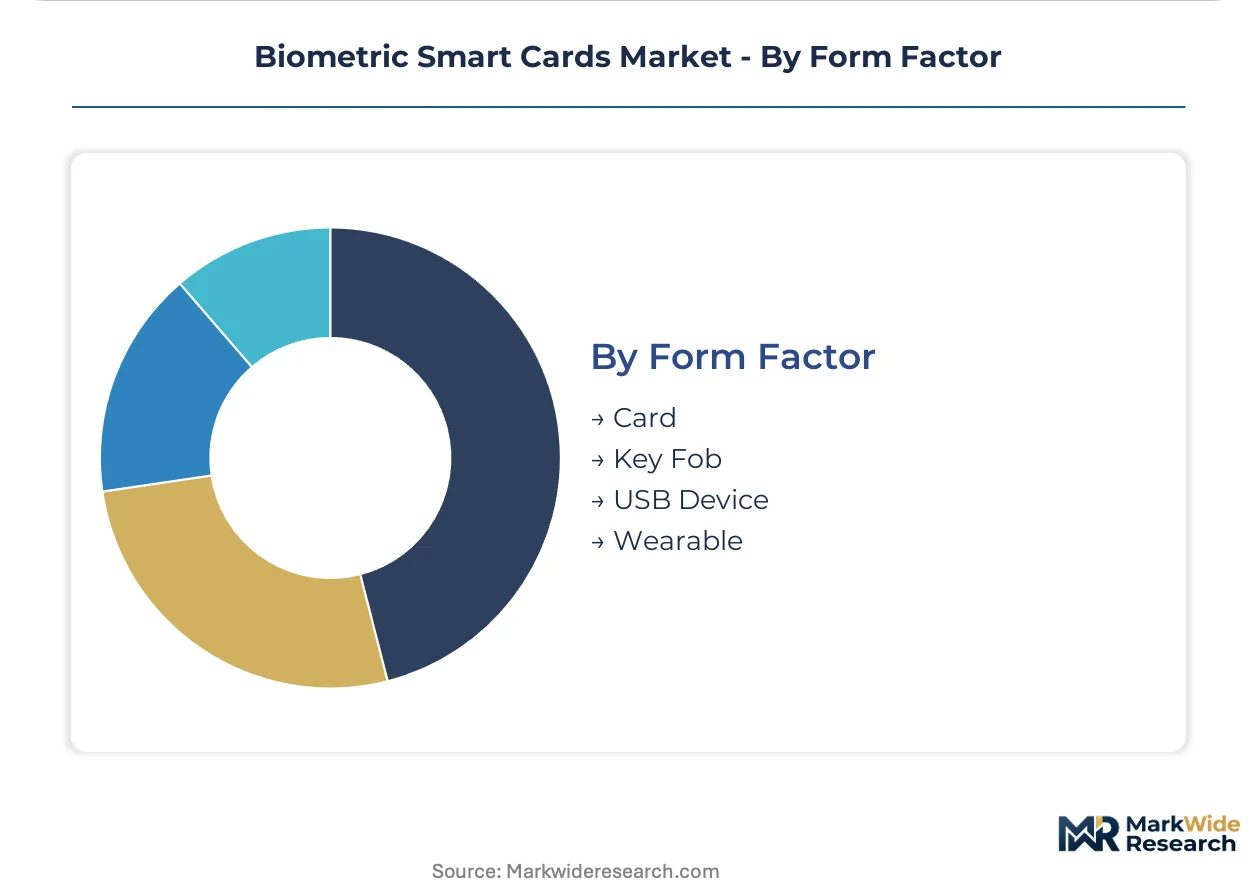
Form Factor:
Form factor selection reflects use-case mobility requirements and terminal interaction modes, with card dominance giving way to wearable formats in specific access-control applications.
- Card:ISO/IEC 7810-compliant form factors with embedded biometric sensors constitute the baseline product architecture. ECHA REACH substance restrictions are forcing substrate reformulation toward polylactic acid and recycled PVC alternatives.
- Key Fob:Compact biometric authenticators for physical access control and fleet fuel management operate outside payment network certification requirements. German corporate campus security upgrades are driving pilot deployments.
- USB Device:Desktop authentication tokens with biometric matching for remote banking and government portal access face declining relevance as smartphone-based alternatives mature.
- Wearable:Biometrically secured wristbands and rings for transit and event access are emerging in UK and French pilot programs where card carriage friction reduces transaction frequency.
Card form factors lead volumes today; wearables are expanding most quickly in transit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in semiconductor design and secure-element manufacturing anchor geographic concentration for biometric smart card production. Foundry partnerships cluster in jurisdictions with established payment-grade certification ecosystems. Regulatory divergence on biometric data processing creates deployment friction across national boundaries.
Germany
Federal procurement specifications for high-assurance national ID credentials drive multimodal biometric demand. The KBA and BSI coordinate testing protocols for liveness detection algorithms. Bavaria's secure-element design houses anchor sensor-module integration for government credentialing programs.
France
Banking consortium pilots for 2026 portfolio refreshes concentrate fingerprint-on-card procurement. ANSM and CNIL interpretations of GDPR Article 9 shape on-card template storage architectures. Île-de-France personalization bureaus qualify ultrathin flexible sensors for transit-integrated banking products.
United Kingdom
Transport for London's fare gate certification accelerates EMV contactless biometric qualification timelines. The Financial Conduct Authority enforces PSD2 strong customer authentication thresholds. London neobanks pilot voice-biometric fallback cards for telephone banking integration.
United States
HIPAA compliance requirements drive hospital procurement of biometric patient identification cards outside payment networks. The FDA maintains parallel evaluation tracks for healthcare access credentialing. California university hospital systems with independent IT governance unbundle card contracts from enterprise EMR vendors.
China
MIIT standards for dual-interface card substrates accelerate domestic qualification of polylactic acid alternatives. SAMR enforcement of GB standards for payment security creates certification bottlenecks for foreign sensor vendors. Yangtze River Delta foundries concentrate microcontroller fabrication for Asian card issuers.
Biometric Smart Cards Market Competitive Landscape
The competitive structure tilts toward integrated secure-element manufacturers with captive foundry access. Tier-one vendors control supply chain costs through backward integration into sensor module production. Three archetypes dominate: European secure-element specialists, Nordic sensor-module pure-plays, and diversified aerospace-defense conglomerates with payment credentialing divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves as vendors position for 2026-2027 portfolio refresh cycles.
Within the integrated manufacturing tier, IDEMIA exemplifies the European secure-element specialist archetype through its control of foundry-to-card personalization workflows. Fingerprint Cards AB and IDEX Biometrics occupy the sensor-module pure-play segment, with the former anchoring Nordic engineering concentration in reduced die-size architectures. Thales Group represents the diversified conglomerate model, leveraging aerospace and defense credentialing expertise across dual-interface product lines.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| Fingerprint Cards AB |
| IDEX Biometrics |
| HID Global |
| NXP Semiconductors |
| CardLogix Corporation |
| Mastercard |
| STMicroelectronics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up secure-element specialists anchor European manufacturing capacity, tightening pricing discipline through captive foundry access while sensor-module pure-plays compete on die-size cost compression. This ownership pattern concentrates supply-side leverage among integrated manufacturers who bundle certification services with component procurement.
Pricing Analysis
Bundled certification-and-component packages dominate procurement for retail banking issuers, while unbundled sensor-module sourcing serves government tenders with bespoke Common Criteria requirements. Price differentiation rests on EMVCo compliance speed versus EAL6+ certification depth, with French and German banking consortiums showing lowest sensitivity due to PSD2-mandated upgrade budgets. Cost compression in fingerprint modules is intensifying because dedicated foundry partnerships are narrowing die-size premiums against standard EMV cards.
Supply Chain Analysis
Single-source vulnerability sits with advanced microcontroller fabrication clustering in Taiwan, South Korea, and Germany for payment-grade secure elements. The industry draws from silicon wafers, halogen-free PVC substrates, and near-infrared optical components as critical inputs. Tariff exposure on Chinese sensor-module assemblies threatens cost structures for European personalization bureaus. Distribution runs through certified personalization centers in France, Germany, and the United Kingdom that handle both substrate qualification and biometric template enrollment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as hospital procurement departments unbundle biometric patient-identification cards from enterprise EMR contracts, shifting demand toward premium specifications with independent IT governance.
For Market Incumbents: Deploy backward integration into sensor-module production to defend margins against Nordic pure-plays with reduced die-size architectures. Capture channel control through exclusive partnerships with French and German personalization bureaus facing ECHA substrate retesting bottlenecks.
For New Entrants and Emerging Players: Capture healthcare access credentials as the most penetrable vertical outside payment-network certification requirements. Target French university hospital systems with independent procurement authority and pilot-ready EMR integration needs.
For Investors and Strategic Acquirers: Diversified aerospace-defense conglomerates with payment credentialing divisions are the most active acquirer in this space, seeking sensor-module capabilities to complete vertical stacks. Over a five-to-ten-year horizon, targets with certified green supply chains for polylactic acid substrates offer defensive positioning. Watch for national data-protection authority rulings on GDPR Article 9 template storage as the inflection signal for on-card versus cloud-dependent architecture preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Foundry Partnership | Captive microcontroller supply from Taiwan and Germany insulates against demand surge bottlenecks. |
| ECHA Green Substrate Certification | Polylactic acid qualification maintains CE marking access under REACH substance restrictions. |
| Dual-Interface Terminal Certification | EMVCo contactless qualification unlocks Transport for London fare gate integration. |
| Healthcare EMR Unbundling | Direct hospital procurement relationships bypass enterprise software vendor gatekeeping. |
| EU AI Act Algorithm Transparency | Documentation protocols for liveness detection satisfy French ANSM and German BSI requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with secure-element procurement directors, biometric algorithm engineers, hospital IT governance officers, and ECHA compliance consultants with secondary validation. Sources included EMVCo certification databases, ECHA candidate list updates, BSI technical guidelines, and payment processor terminal deployment disclosures. Bottom-up sensor-module shipment tallies and top-down banking card issuance forecasts were triangulated against transit operator procurement records.
Segment-weighting applied product type, technology modality, end-user vertical, and form factor dimensions across the modeling period. CAGRs were derived from installed terminal base penetration curves and issuer refresh cycle timing. Forecast inputs incorporated PSD2 strong customer authentication compliance deadlines and EU Green Deal material restriction phase-ins without year-specific anchoring.
Regulatory reinterpretation of GDPR Article 9, secure-element foundry capacity allocation shifts, and transit operator certification timeline delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about biometric template storage architecture preferences and substrate qualification completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Global Human Identification Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Spain Mobile Biometrics Market
Biometrics & Identity Management
United States Biometrics Market