
 Automated Fingerprint Identification Systems (AFIS) Market | 2026-2036
Automated Fingerprint Identification Systems (AFIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Fingerprint Identification Systems (AFIS) Market Outlook
Asian semiconductor foundries is recalibrating sensor output for biometric modules as government procurement cycles intensify. NEC Corporation leverages its legacy in pattern-matching algorithms to anchor large-scale national deployments. IDEMIA sustains manufacturing scale across multiple continental markets through integrated credential production. Fujitsu competes in the high-resolution sensor tier with proprietary capacitive scanning architectures.
Automated Fingerprint Identification Systems deploy optical, capacitive, or ultrasonic sensors to capture ridge patterns, then apply minutiae extraction algorithms to match latent or live-scan prints against enrolled databases within sub-second response windows. The systems serve primarily to verify identity in criminal justice workflows, border management, and civil registry modernization. Software Solutions and Biometric Algorithms command disproportionate margin pools as recurring licensing revenue outpaces hardware depreciation cycles. Law Enforcement applications retain the largest installed base, though Financial Services represents the fastest structural expansion as Know-Your-Customer mandates proliferate. Cloud-Based deployment is displacing legacy On-Premises infrastructure among mid-sized security firms seeking elastic compute for peak verification loads.
FBI certification standards in the United States, BIS biometric device registration in India, and ETSI technical norms across European procurement frameworks collectively elevate entry barriers for non-compliant vendors. GDPR data-retention limits in Europe and India's Digital Personal Data Protection Act constrain how fingerprint templates traverse jurisdictional boundaries. Stakeholders must monitor whether emerging encryption standards for template protection become mandatory preconditions for government contract eligibility.
Market Dynamics
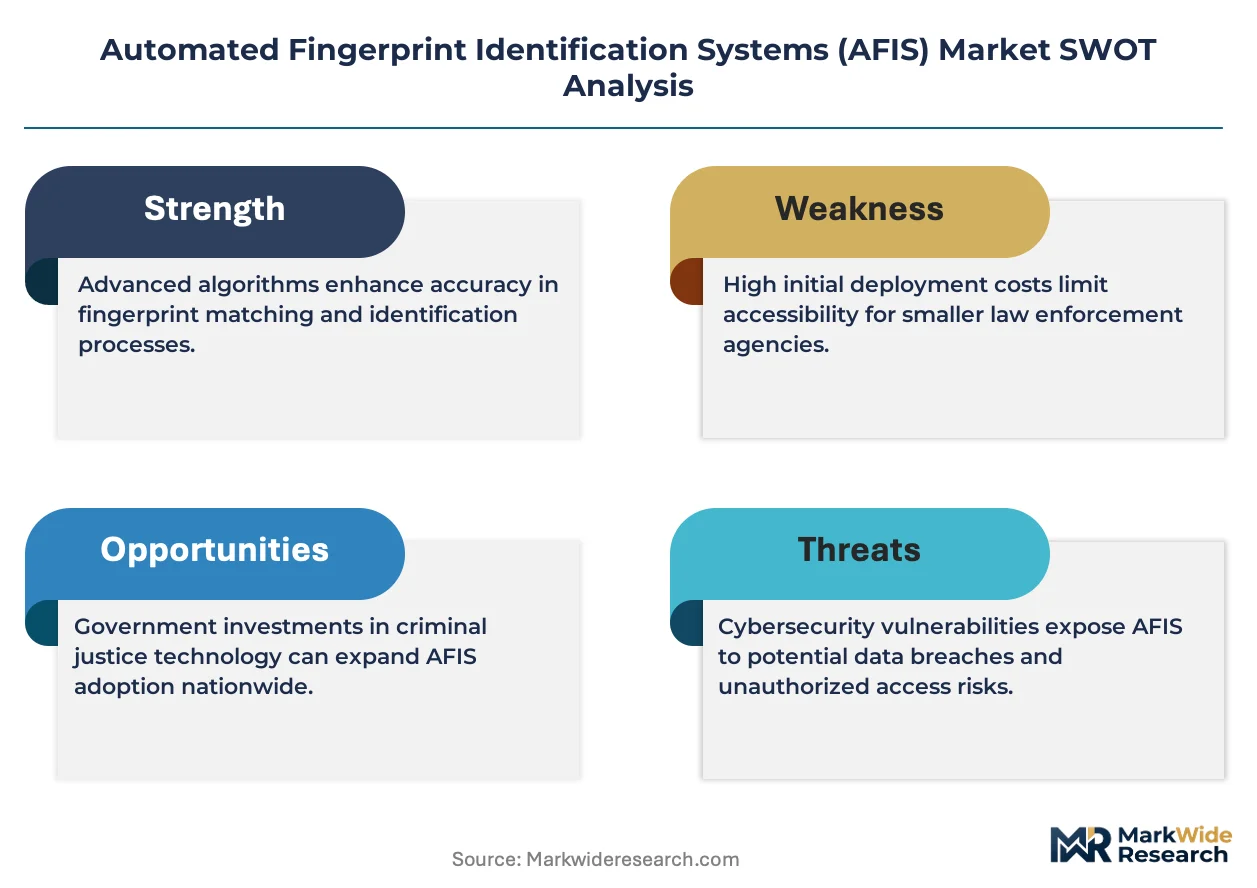
Cloud-native AFIS architectures are compressing deployment timelines for mid-sized security operators while fragmenting vendor concentration that legacy on-premises systems once protected.
Growth Catalysts
- India's Digital Personal Data Protection Act:Civil identification mandates are accelerating biometric enrollment across state-level welfare programs, expanding hardware procurement cycles for enrollment stations.
- Financial Services KYC compliance:Banks and non-banking financial companies are embedding live-scan terminals into customer onboarding workflows to satisfy central bank verification requirements.
- Ultrasonic sensor maturation:Sub-surface fingerprint capture is penetrating high-assurance border control checkpoints where latent print recovery rates determine operational throughput.
Market Restraints
- Specialized semiconductor foundry concentration:Biometric sensor ASIC fabrication depends on a narrow base of advanced-node suppliers concentrated in East Asian manufacturing clusters.
- GDPR template retention limits:European data protection authorities constrain cross-border fingerprint database synchronization, complicating multinational law enforcement information sharing protocols.
- Facial recognition substitution:Contactless biometric modalities are capturing budget allocations in public transit and retail access control where hygiene concerns persist.
Strategic Opportunities
- Brazil's national ID modernization:The civil registry sector offers deployment scale for vendors capable of meeting ANVISA-equivalent biometric device certification timelines.
- Mobile-first enrollment platforms:Smartphone-integrated fingerprint modules are opening last-mile identity verification in rural banking correspondent networks.
- Edge-AI inference convergence:On-device template matching is reducing latency for field-based law enforcement queries where connectivity is intermittent.
Industry Challenges
- FBI certification timeline compression:Hardware vendors face extended validation cycles for Appendix F compliance as test criteria tighten for sub-500 PPI resolution thresholds.
- Legacy system API fragmentation:Municipal police departments struggle to integrate cloud-based AFIS queries with decades-old state criminal history repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Fingerprint Identification Systems (AFIS) Market |
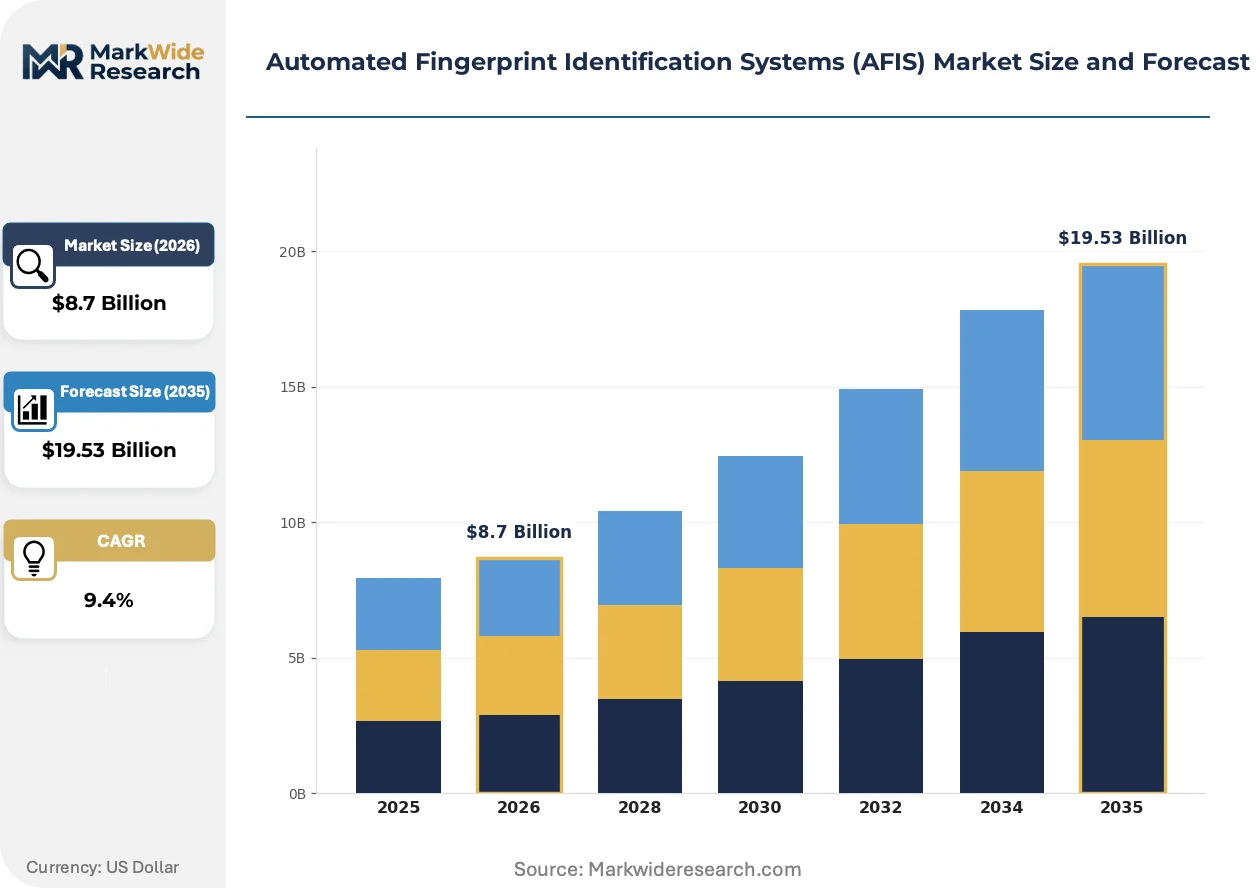
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Scanners, Software Solutions, Biometric Algorithms, Data Management Systems Application: Law Enforcement, Civil Identification, Access Control, Financial Services End User: Government Agencies, Private Enterprises, Research Institutions, Security Firms Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Fujitsu, DERMALOG Identification Systems GmbH, NEC Corporation, Suprema Inc., Aware, Inc., IDEMIA, HID Global Corporation, Papillon Systems, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Fingerprint Identification Systems (AFIS) Market Strategic Shifts
Template protection protocols and edge-compute distribution are redistributing technical capability across the AFIS value chain, compressing the historical advantage of centralized database operators.
Ultrasonic sensing is decentralizing high-resolution enrollment from dedicated forensic laboratories to distributed field locations. Border management agencies in Australia and the United Arab Emirates are deploying portable units for remote visa processing. This capability diffusion is eroding the premium pricing power that centralized live-scan manufacturers previously commanded in high-assurance segments.
India's BIS biometric device registration framework is tightening quality benchmarks for capacitive and optical sensor modules entering government procurement channels. The certification mandate is filtering out uncertified hardware vendors from national ID program tenders. Domestic system integrators are responding by deepening partnerships with foundries capable of guaranteeing compliance documentation.
Subscription-based software licensing is supplanting perpetual license sales among mid-sized private security firms. Managed service providers are absorbing upfront infrastructure costs in exchange for per-transaction verification fees. This preference shift is most visible in North American commercial access control markets where capital expenditure constraints dominate buyer decision criteria.
Automated Fingerprint Identification Systems (AFIS) Market Segmentation
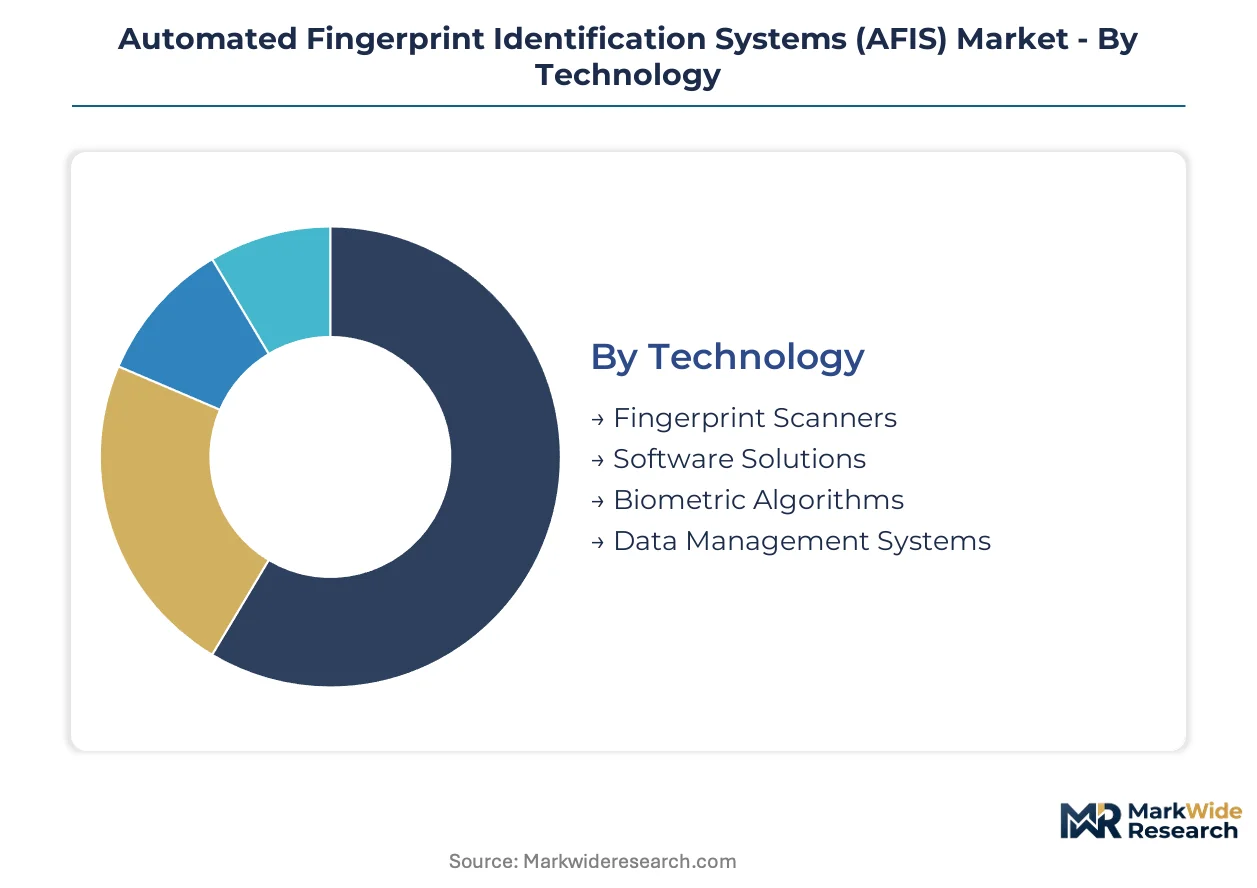
Technology choices in AFIS procurement hinge on legacy infrastructure age and compliance refresh cycles. Organizations weighing sensor replacement against full-stack modernization drive divergent spending patterns across hardware and software categories.
Technology:
Upgrade timelines stretch from 5-year sensor refresh cycles to 15-year enterprise platform overhauls, creating asynchronous replacement demand across component layers.
- Fingerprint Scanners:Optical, capacitive, and ultrasonic sensor modules capture ridge patterns at resolutions spanning 500 to 1000+ PPI. India's BIS biometric device registration is filtering uncertified hardware from national ID tenders, compressing supplier pools for government procurement.
- Software Solutions:Matching engines and system middleware command recurring licensing revenue that outpaces hardware depreciation. Financial services KYC mandates are accelerating live-scan terminal deployments in banking correspondent networks.
- Biometric Algorithms:Minutiae extraction and template matching codebases differentiate vendor performance in sub-second identification. NIST evaluations provide procurement benchmarks for federal buyers.
- Data Management Systems:Database architectures handling million-record galleries with failover redundancy. Municipal police departments prioritize API compatibility with state criminal history repositories.
Software Solutions sits at the top of the volume ranking, with Biometric Algorithms climbing the fastest.
Application:
End-use concentration reflects divergent certification requirements and procurement authority structures across public and private sectors.
- Law Enforcement:Criminal justice workflows demand FBI Appendix F certified sensors for tenprint and latent print matching. Forensic laboratories maintain the largest installed base of centralized AFIS infrastructure.
- Civil Identification:National ID programs and voter registry modernization drive enrollment station procurement at population scale. India's state-level welfare programs are expanding biometric coverage into rural districts.
- Access Control:Commercial and government facility entry systems integrate live-scan terminals with physical security infrastructure. Hygiene-sensitive deployments are evaluating contactless alternatives.
- Financial Services:Know-Your-Customer compliance embeds fingerprint verification into customer onboarding workflows. Central bank mandates in emerging markets are accelerating terminal deployment.
Law Enforcement retains the deepest installed base, though Financial Services is expanding most quickly.
End User:
Budget authority and compliance obligations segment buyer behavior from sovereign procurement to commercial security operations.
- Government Agencies:National ID authorities, border management, and law enforcement command multi-year procurement cycles with stringent certification requirements. Tender specifications prioritize vendor track records in large-scale deployments.
- Private Enterprises:Banks, telecom operators, and commercial security firms seek elastic verification capacity without capital-intensive infrastructure. Subscription licensing is displacing perpetual software sales in this segment.
- Research Institutions:Academic and government laboratories evaluate emerging sensor modalities and algorithmic approaches. NIST test participation provides performance benchmarking for vendor selection.
- Security Firms:Mid-sized operators manage access control and identity verification services for commercial clients. Cloud-native architectures reduce upfront infrastructure investment.
Government Agencies dominate procurement value, with Private Enterprises gaining share fastest.
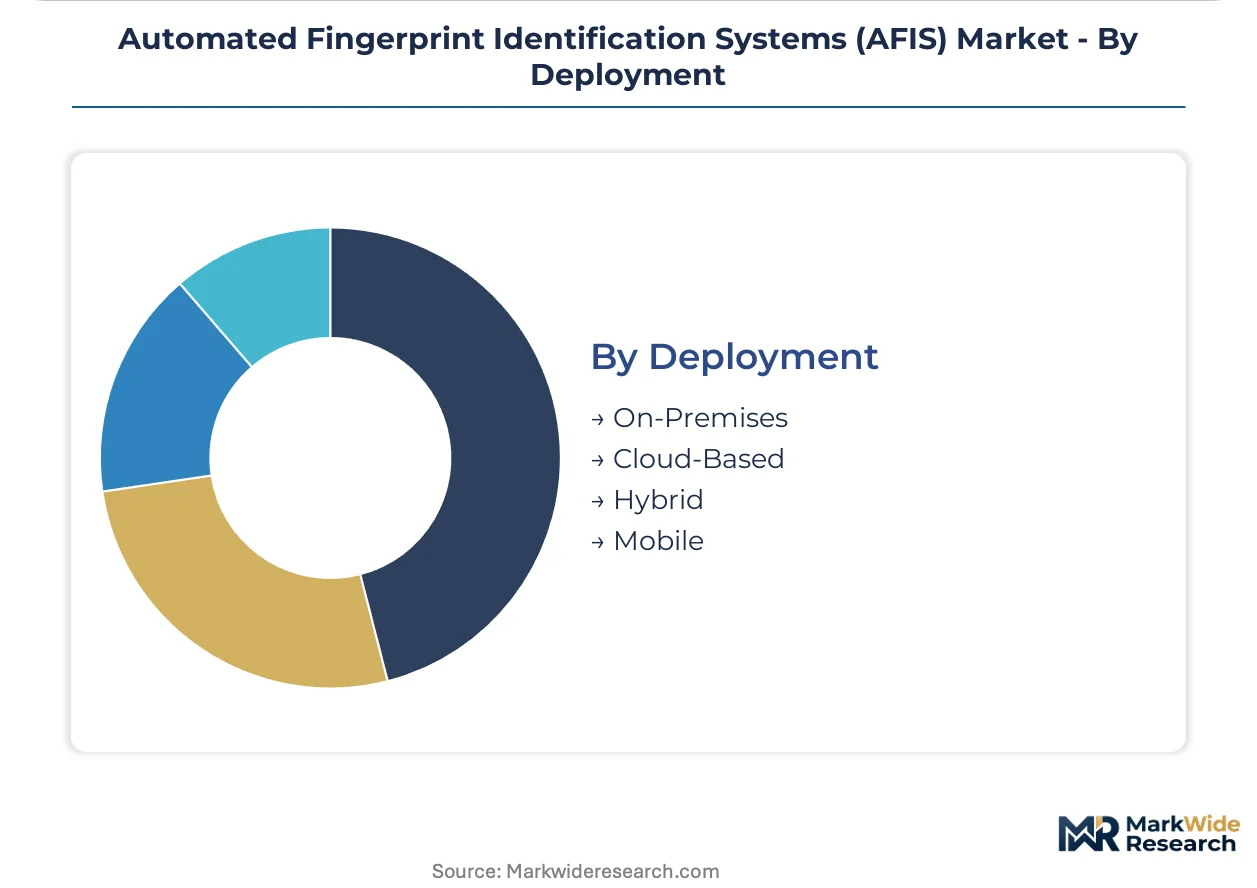
Deployment:
Infrastructure architecture choices reflect connectivity constraints, data sovereignty requirements, and operational mobility needs.
- On-Premises:Dedicated hardware installations in secure facilities with full data custody. Legacy state criminal history repositories maintain this architecture for chain-of-custody requirements.
- Cloud-Based:Elastic compute resources for peak verification loads without fixed infrastructure investment. Mid-sized security firms in North America are migrating to this model.
- Hybrid:Edge enrollment with centralized matching for latency-sensitive applications. Border control agencies deploy this architecture for remote visa processing.
- Mobile:Smartphone-integrated or portable terminal solutions for field-based identity verification. Rural banking networks in India leverage this modality for last-mile enrollment.
On-Premises retains the largest footprint, with Cloud-Based deployment showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric hardware production gravitates toward jurisdictions with streamlined certification pathways, creating compliance arbitrage between established testing regimes and emerging standard-setting bodies. Vendors are relocating sensor module assembly to capture cost advantages in regulatory environments with faster approval timelines.
United States
FBI Appendix F certification requirements drive procurement specifications for law enforcement agencies upgrading latent print matching infrastructure. The Department of Homeland Security mandates biometric interoperability standards for border management systems. California-based system integrators are consolidating enrollment station deployments for state-level criminal justice modernization programs.
India
The Digital Personal Data Protection Act accelerates state-level welfare program enrollment, expanding demand for BIS-certified capacitive sensor modules. BIS biometric device registration filters uncertified hardware from national ID tenders. Domestic system integrators in Bengaluru and Hyderabad are deepening foundry partnerships to guarantee compliance documentation for government procurement.
Germany
GDPR template retention limits constrain cross-border fingerprint database synchronization for multinational law enforcement coordination. The KBA-equivalent transport regulator influences biometric access control specifications for critical infrastructure facilities. Bavarian industrial security firms are migrating mid-sized deployments to cloud-native verification architectures.
Japan
METI standards for biometric device interoperability shape enterprise access control procurement in financial services and manufacturing sectors. The national digital ID program drives enrollment station demand for civil identification modernization. Tokyo-based pattern-matching specialists are licensing algorithmic cores to Southeast Asian system integrators.
Brazil
ANVISA-equivalent biometric device certification timelines determine vendor eligibility for national ID modernization tenders. The civil registry sector offers deployment scale for compliant enrollment infrastructure. São Paulo-based security distributors are building technical service networks to support field deployment of portable fingerprint terminals.
Automated Fingerprint Identification Systems (AFIS) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue edge-AI inference and mobile-first enrollment platforms. The vendor base stratifies across three capability layers: integrated credential producers with manufacturing scale, algorithm specialists with NIST benchmarking track records, and hardware fabricators with foundry partnerships for sensor module production. Dominant competitive moves include strategic partnerships with semiconductor foundries for BIS-compliant sensor supply and geographic expansion through managed service licensing to absorb upfront infrastructure costs.
Within the integrated credential tier, IDEMIA and NEC Corporation exemplify vendors sustaining manufacturing scale across multiple continental markets. DERMALOG Identification Systems GmbH anchors the specialized hardware segment with German engineering heritage. Fujitsu occupies a position in the high-resolution sensor tier with proprietary architectures. These archetypes represent distinct competitive positioning strategies rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Fujitsu |
| DERMALOG Identification Systems GmbH |
| NEC Corporation |
| Suprema Inc. |
| Aware, Inc. |
| IDEMIA |
| HID Global Corporation |
| Papillon Systems |
| Thales |
| Others |
Value Chain & Pricing Dynamics
BIS biometric device registration mandates in India are compressing supplier pools for government tenders, forcing hardware vendors to absorb certification costs or cede procurement access to compliant competitors. This qualification-driven supply consolidation elevates pricing power for certified foundry partnerships while squeezing margins for uncertified module assemblers.
Pricing Analysis
Distributor margin compression in the enrollment station tier reflects elongated sales cycles for FBI Appendix F certified hardware. Three-tier pricing structure across FBI-certified, BIS-registered, and uncertified sensor tiers separates law enforcement procurement from commercial access control budgets. Pricing pressure stems from cloud-native software vendors absorbing upfront infrastructure costs through per-transaction SaaS models. Municipal police departments exhibit highest price sensitivity due to fixed capital budgets, while national ID authorities prioritize certification compliance over unit cost.
Supply Chain Analysis
Certification gating through FBI Appendix F and BIS biometric device registration filters sensor module supply to a narrow base of compliant foundries concentrated in Taiwan, South Korea, and Japan. Advanced-node ASIC fabrication draws from specialized semiconductor capacity, capacitive sensor substrates, and precision optical components. Single-source vulnerability in biometric sensor ASIC production exposes procurement timelines to foundry allocation decisions. Distribution runs through domestic system integrators in India and Germany who manage compliance documentation for government tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AFIS market has entered a late-cycle quality phase where procurement specifications favor certified hardware over cost-optimized alternatives. India's Digital Personal Data Protection Act and comparable civil identification mandates across emerging economies are elevating premium-tier demand for compliant enrollment infrastructure.
For Market Incumbents: Deepen foundry partnerships guaranteeing BIS and FBI certification documentation to defend procurement access against emerging cloud-native competitors. Anchor manufacturing scale across multiple continental markets to absorb per-transaction pricing pressure from SaaS entrants. Prioritize API compatibility investments bridging legacy state criminal history repositories with cloud-based query architectures. For New Entrants and Emerging Players: Launch via mobile-first enrollment platforms targeting rural banking correspondent networks in India and Brazil where last-mile identity verification gaps persist. Capture share in mid-sized private security firms seeking elastic verification capacity without capital-intensive infrastructure. Pursue edge-AI inference partnerships with field-based law enforcement agencies facing intermittent connectivity constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm specialists possessing NIST benchmarking track records and licensing revenue models insulated from hardware depreciation cycles. Long-term viability favors vendors controlling both template protection protocols and edge-compute distribution architectures. Monitor whether emerging encryption standards for biometric template protection become mandatory preconditions for government contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Deepening | BIS-compliant sensor supply secures access to India's national ID program tenders. |
| Cloud-Native Platform Launch | Subscription licensing absorbs upfront costs for North American commercial security firms. |
| Edge-AI Inference Integration | On-device template matching reduces latency for field-based law enforcement queries. |
| API Compatibility Investment | Legacy system integration addresses municipal police department modernization barriers. |
| Mobile-First Enrollment Expansion | Smartphone-integrated modules penetrate rural banking networks in emerging markets. |
Study Parameters
Bottom-up law enforcement and civil identification modeling reconciled against top-down biometric hardware production tracking forms the analytical core of this study. Primary interviews with AFIS procurement officers at national ID authorities, system integrators in Bengaluru and Hyderabad, forensic laboratory directors, and cloud-native software vendors combined with secondary validation against FBI certification databases, BIS registered device listings, NIST algorithm evaluation results, and customs records for sensor module trade flows. Triangulation across these sources ensures demand-side enrollment projections align with supply-side foundry capacity.
Historical trendline analysis of sensor refresh cycles and enterprise platform replacement timelines informed projection modeling across the analysis window. Segmentation dimensions include technology tier, application workflow, end-user budget authority, and deployment architecture. CAGRs derived from regression analysis of procurement cycle intensities and compliance refresh mandates. Industry-specific forecast inputs incorporate India's state-level welfare program rollout schedules and FBI Appendix F certification pipeline backlogs.
Several conditions sit outside the modeled scope, including unannounced regulatory encryption mandates for template protection and breakthrough advances in contactless biometric substitution. Forecasts reflect assumptions regarding continued government procurement preference for certified hardware and stable foundry allocation for biometric sensor ASICs. A model refresh is warranted upon material change in FBI or BIS certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Hand Geometry Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Global Behavioral Biometrics Market