
 Reformer Unit Market | 2026-2036
Reformer Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Reformer Unit Market Analytics
The EU Green Deal is repositioning the cost-of-entry calculus for European reformer deployments, forcing refinery operators to account for embedded carbon in hydrogen supply chains. Honeywell International leverages its catalyst and control systems portfolio to sustain technology leadership in steam methane reforming retrofits. Linde plc anchors large-scale hydrogen production through its proprietary autothermal reformer designs. KBR Inc. competes on modular reformer delivery, reducing field construction timelines for remote gas-to-liquids projects.
A reformer unit is a pressurized reaction vessel that converts hydrocarbon feedstocks—typically natural gas, naphtha, or refinery off-gas—into synthesis gas or hydrogen through catalytic or thermal processes at temperatures exceeding 800°C, with nickel-based catalysts dominating steam methane reforming. Its primary industrial purpose is to generate hydrogen for ammonia synthesis, refinery hydrotreating, and emerging fuel cell applications. Steam methane reformers occupy the dominant share of installed capacity due to decades of operational maturity and lowest levelized hydrogen cost, while membrane technology segments are attracting capital as operators seek to simplify downstream purification and reduce energy intensity. Catalytic reformers retain stable demand from oil refineries processing heavier crude slates, though margin pools are shifting toward hybrid systems that integrate carbon capture.
EPA emissions standards for refinery hydrogen plants and the EU F-Gas Regulation on fluorinated greenhouse gases are tightening product specifications and compelling equipment upgrades across North American and European installations. India's CEA grid interconnection rules and the country's PLI scheme for electrolyzer and reformer manufacturing are reshaping procurement patterns for domestic hydrogen projects. Stakeholders must monitor how carbon border adjustment mechanisms in Europe and evolving green hydrogen certification standards alter the competitive economics of steam methane versus electrolysis-based supply.
Market Dynamics
Carbon border adjustment mechanisms are forcing hydrogen producers to recalibrate feedstock choices and capture technology investments, compressing the economic viability window for unabated steam methane reforming against electrolysis alternatives.
Growth Catalysts
- EU Green Deal carbon border adjustments:Refinery operators in Rotterdam and Antwerp are accelerating low-carbon hydrogen retrofits to avoid import tariffs on embedded emissions in fuel exports.
- Ammonia synthesis capacity expansion:Fertilizer producers in India and the Middle East are commissioning new reformer trains to serve both domestic agriculture and emerging marine fuel bunkering demand.
- Membrane purification integration:Operators are retrofitting pressure swing adsorption units with polymeric membrane systems to reduce energy intensity in hydrogen separation.
Market Restraints
- Nickel catalyst supply concentration:Russian and Indonesian nickel processing dominance creates raw material vulnerability for steam methane reformer operators dependent on alumina-supported catalysts.
- Natural gas price volatility:European feedstock cost spikes following pipeline supply disruptions have compressed operating margins for merchant hydrogen producers.
- Electrolysis cost compression:Alkaline and PEM electrolyzer capital cost reductions are narrowing the levelized cost gap against reforming for green hydrogen certification.
Strategic Opportunities
- India PLI scheme for green hydrogen:Domestic manufacturing incentives are attracting reformer and electrolyzer assembly investments across Gujarat and Maharashtra industrial corridors.
- Autothermal reforming with carbon capture:Integration of oxygen-blown reformers with amine or solid sorbent capture systems is opening blue hydrogen export pathways to Japan and South Korea.
- Modular skid-mounted units:Compact reformer designs are enabling distributed hydrogen production at remote gas-to-liquids and methanol sites lacking pipeline infrastructure.
Industry Challenges
- High-temperature materials engineering shortage:Qualified welders and metallurgists capable of servicing reformer tube alloys at 900°C operating conditions are concentrated among a shrinking contractor base.
- Legacy control system integration:Digital twin and advanced process control retrofits face compatibility friction with decades-old distributed control systems in established refinery hydrogen plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reformer Unit Market |
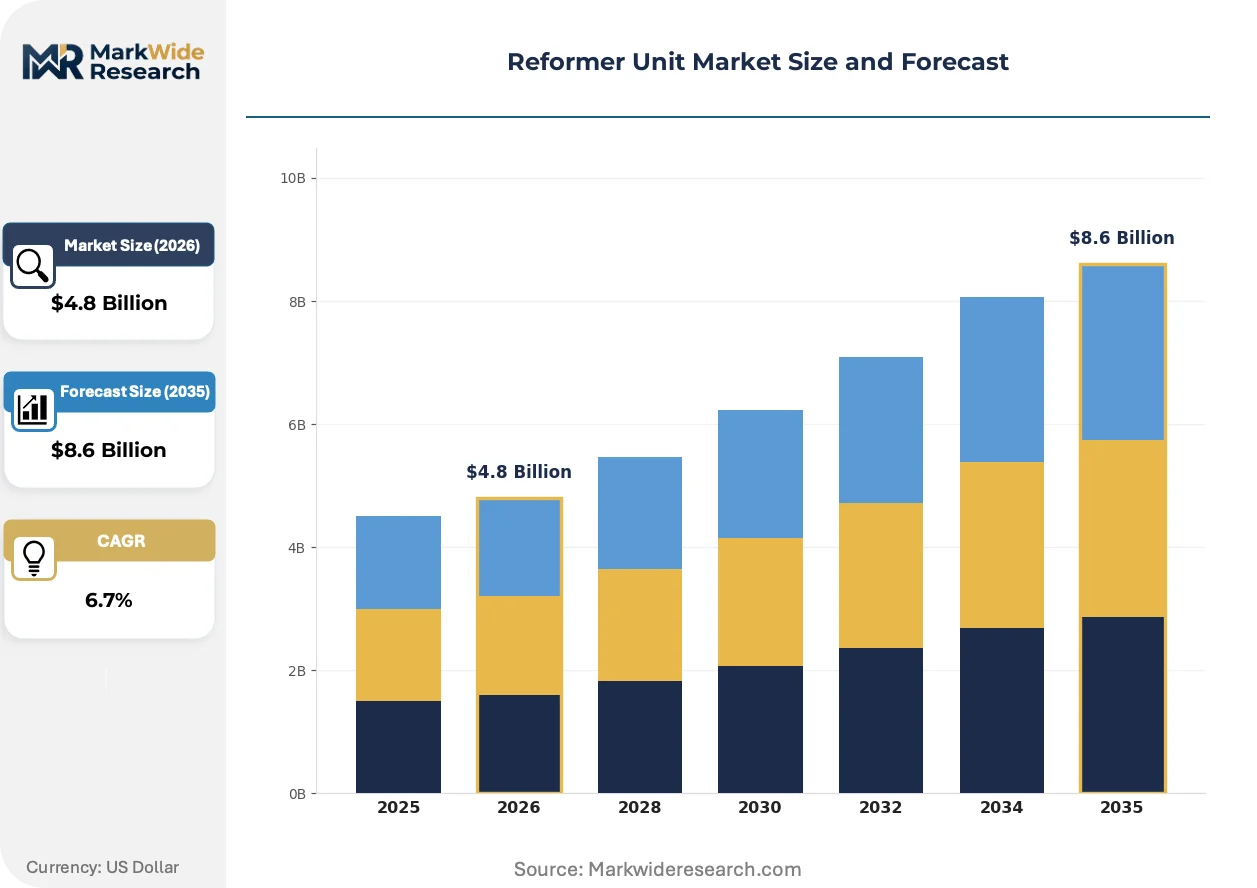
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Methane Reformers, Auto Thermal Reformers, Partial Oxidation Reformers, Catalytic Reformers End User: Chemical Manufacturers, Oil Refineries, Hydrogen Producers, Power Plants Technology: Fixed Bed, Fluidized Bed, Membrane Technology, Hybrid Systems Application: Hydrogen Production, Ammonia Synthesis, Syngas Production, Fuel Cells |
| Companies Covered | Honeywell International, Wood plc, BP plc, Larsen and Toubro Limited, Siemens AG, KBR Inc., Linde plc, Chiyoda Corporation, McDermott International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reformer Unit Market Evolving Landscape
Reformer technology trajectories are bifurcating between efficiency maximization for incumbent fossil hydrogen and carbon intensity minimization for certification-compliant supply, with equipment vendors recalibrating R&D portfolios accordingly.
Solid oxide electrolysis is expanding into hybrid configurations with steam methane reformers, enabling efficient heat integration and reducing external natural gas demand for hydrogen production. Chemical producers in the Netherlands and Germany are piloting these coupled systems to achieve partial load flexibility while maintaining output. This convergence is expanding into new project financing structures that blend green bond proceeds with traditional project debt.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration cycles for hydrogen liquefaction, compelling equipment suppliers to adopt ammonia or magnetic bearing alternatives for pre-cooling duty. Reformer-integrated hydrogen liquefaction projects in France and Germany face compliance timelines accelerating capital replacement cycles. Affected developers are sourcing non-fluorinated cold box designs from Japanese and Korean cryogenic engineering specialists.
Refinery operators are consolidating hydrogen procurement through long-term offtake agreements with merchant producers, displacing captive on-site reforming capacity. This contractual shift concentrates volume risk with independent hydrogen suppliers while freeing refinery capital for renewable fuel conversion investments. The pattern is most pronounced in the US Gulf Coast and Rotterdam-Antwerp corridor where pipeline networks enable competitive sourcing.
Reformer Unit Market Segmentation
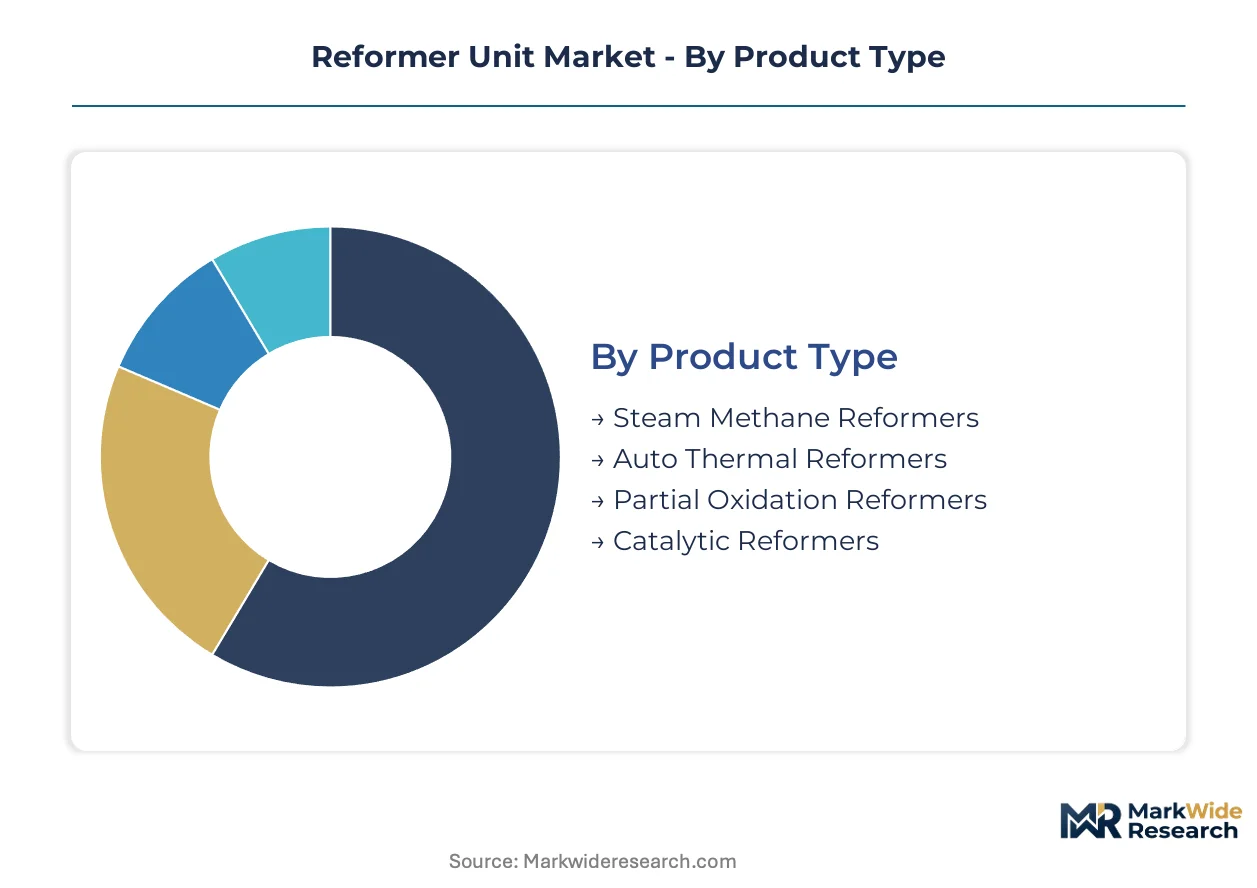
Reformer unit procurement varies sharply by hydrogen purity requirements, carbon intensity targets, and integration complexity with existing process infrastructure. Equipment specifications diverge across ammonia synthesis, refinery hydrotreating, and emerging fuel cell feedstock applications, creating distinct margin pools for vendors.
Product Type:
Standardized reactor vessel designs dominate high-volume ammonia and methanol corridors, while bespoke configurations prevail in remote gas-to-liquids projects and carbon capture retrofits.
- Steam Methane Reformers:Nickel-catalyzed tubular reactors operating above 800°C constitute the installed base majority. Demand concentrates in India and the Middle East where fertilizer producers scale capacity for domestic agriculture and marine fuel bunkering.
- Auto Thermal Reformers:Oxygen-blown partial oxidation combined with steam reforming enables lower carbon intensity through efficient heat integration. Japanese and South Korean importers favor autothermal designs with amine capture for certified blue hydrogen supply chains.
- Partial Oxidation Reformers:Heavy hydrocarbon feedstocks including refinery residue and coal gasification drive deployment in regions with stranded carbon resources.
- Catalytic Reformers:Platinum-rhenium catalyst systems process naphtha for high-octane gasoline blending and aromatics extraction in complex refineries.
Most installed capacity flows through steam methane reformers. Expansion is steepest in autothermal reformers with integrated carbon capture.
End User:
Procurement scale and technical sophistication separate merchant hydrogen suppliers from captive refinery operators, with chemical manufacturers occupying intermediate volume tiers.
- Chemical Manufacturers:Methanol and synthetic fuel producers require syngas ratios tunable to downstream catalytic requirements. Indian chemical corridors in Gujarat and Maharashtra are absorbing modular reformer trains under PLI scheme incentives.
- Oil Refineries:Hydrotreating and hydrocracking hydrogen demand drives continuous operation at 90%+ capacity factors. Rotterdam and Antwerp refiners are outsourcing hydrogen procurement to merchant producers to avoid carbon border adjustment exposure.
- Hydrogen Producers:Dedicated merchant suppliers consolidate volume risk across multiple offtakers, concentrating in the US Gulf Coast and Netherlands pipeline networks.
- Power Plants:Gas turbine co-firing and fuel cell integration represent emerging demand with stringent purity specifications.
Refinery operators currently command the largest procurement volumes. Merchant hydrogen producers are gaining share fastest as outsourcing accelerates.
Technology:
Fixed bed maturity contrasts with membrane simplification and hybrid flexibility, with technology choice hinging on purification downstream and turndown ratio requirements.
- Fixed Bed:Conventional packed catalyst tubes deliver proven reliability for baseload hydrogen production. Established refineries in North America and Europe retain fixed bed systems despite retrofit complexity with legacy distributed control architectures.
- Fluidized Bed:Enhanced heat transfer and catalyst circulation suit heavy feedstock processing and rapid response to load swings.
- Membrane Technology:Palladium or polymeric membrane integration eliminates separate pressure swing adsorption units, reducing energy intensity for smaller-scale distributed production.
- Hybrid Systems:Solid oxide electrolysis coupled with steam methane reforming enables partial electrification and carbon intensity reduction for EU Green Deal compliance.
Fixed bed configurations retain the dominant installed footprint. Hybrid systems are climbing the fastest as operators seek certification-compliant supply pathways.
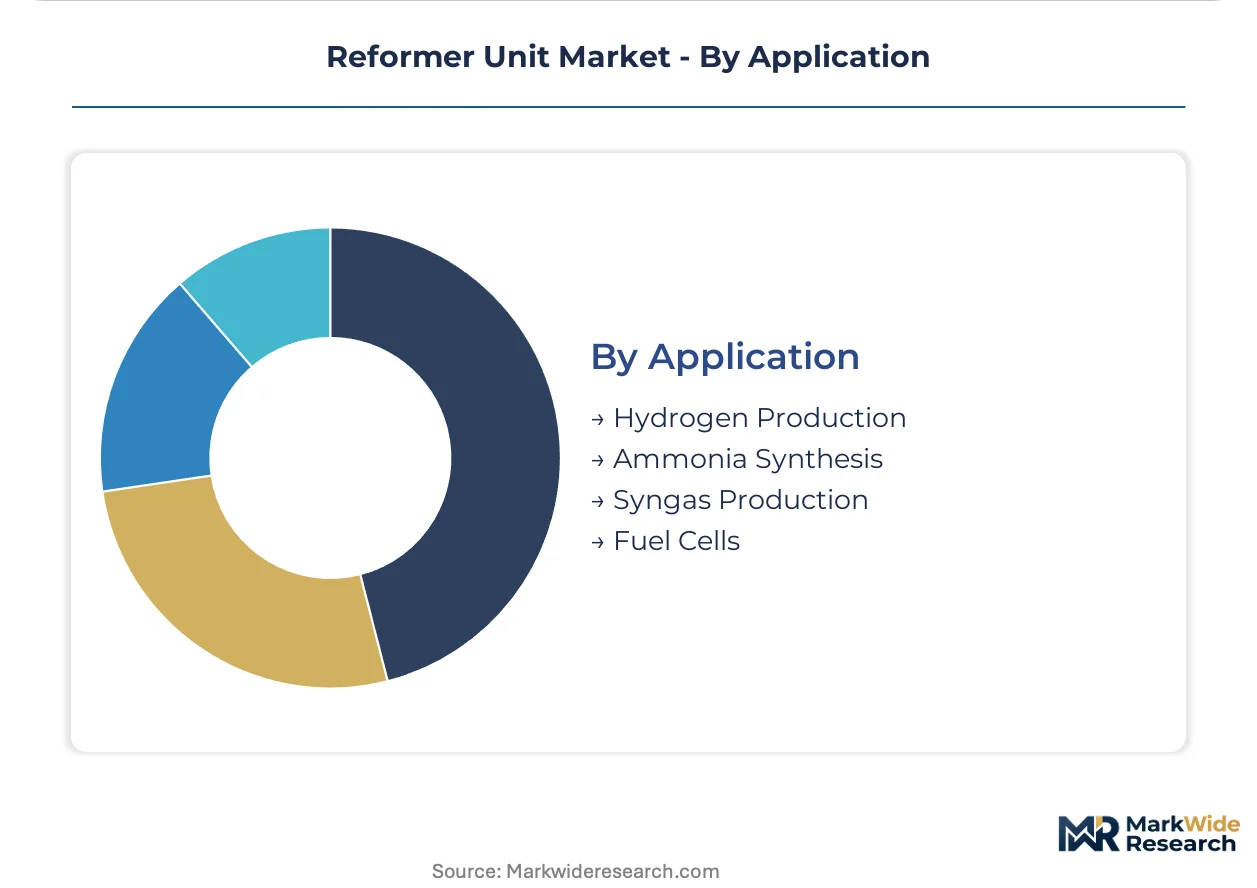
Application:
Hydrogen purity grades and delivery pressure specifications fragment demand across industrial gas, chemical synthesis, and energy transition end uses.
- Hydrogen Production:Refinery hydrotreating and merchant industrial gas supply constitute volume anchors. US Gulf Coast pipeline hubs concentrate reformer deployments serving multiple downstream offtakers.
- Ammonia Synthesis:Stoichiometric 3:1 hydrogen-nitrogen ratio requirements demand reformer-syngas optimization. Indian fertilizer producers under PLI incentives are commissioning capacity for domestic urea and export-oriented marine fuel.
- Syngas Production:Methanol, Fischer-Tropsch, and oxo-alcohol synthesis require adjustable H2:CO ratios through reformer configuration and downstream water-gas shift.
- Fuel Cells:Proton exchange membrane and solid oxide fuel cells impose 99.97%+ purity requirements with CO and sulfur contaminants below 0.2 ppm, driving advanced purification integration.
Hydrogen production for industrial applications retains the largest capacity share. Fuel cell feedstock preparation is expanding most quickly as transportation and stationary power applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians and high-temperature metallurgists cluster around Rotterdam, Houston, and Gujarat, anchoring reformer fabrication and maintenance capacity in corridors where hydrogen demand concentrates.
United States
Merchant hydrogen suppliers along the Gulf Coast pipeline network are consolidating offtake agreements with refiners seeking to outsource production risk. EPA emissions standards for refinery hydrogen plants compel equipment upgrades across Texas and Louisiana installations. The Houston Ship Channel corridor hosts dense reformer maintenance contractor activity serving ammonia and methanol producers.
Germany
Chemical producers in the Rhine-Ruhr industrial belt pilot solid oxide electrolysis coupled with steam methane reforming for partial load flexibility. The EU F-Gas Regulation accelerates capital replacement cycles for hydrogen liquefaction cold boxes. Ludwigshafen and Duisburg clusters absorb modular autothermal reformer trains with integrated carbon capture systems.
India
Fertilizer producers scale ammonia synthesis capacity under the PLI scheme for green hydrogen manufacturing incentives. CEA grid interconnection rules reshape procurement patterns for domestic hydrogen projects. Gujarat and Maharashtra industrial corridors commission reformer deployments serving both urea production and emerging marine fuel bunkering demand.
Japan
Importers favor autothermal reformer designs with amine capture for certified blue hydrogen supply chains to power sector offtakers. METI policy frameworks support technology validation for overseas hydrogen export projects. The Kansai industrial zone concentrates engineering procurement for Middle East and Australian supply partnerships.
Saudi Arabia
Stranded gas monetization drives autothermal reformer deployment for ammonia and synthetic fuel export corridors. National industrial diversification programs channel investment toward hydrogen-based chemical manufacturing. The Eastern Province hosts concentrated EPC activity linking reformer fabrication to Red Sea shipping logistics.
Reformer Unit Market Competitive Landscape
The competitive structure tilts toward integrated industrial gas and engineering conglomerates with captive catalyst and control system portfolios. Technology licensing arrangements and modular delivery capabilities separate premium-tier participants from regional fabrication specialists. Two strategic archetypes dominate: full-service hydrogen solution providers combining reformer design with downstream purification, and specialized EPC contractors focused on remote site modularization. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators seek to secure nickel catalyst supply chains and carbon capture integration expertise.
Among diversified technology conglomerates, Honeywell International and Siemens AG occupy positions exemplifying control system and catalyst integration archetypes. Linde plc anchors the industrial gas supplier tier with proprietary autothermal reformer designs. KBR Inc. sits within the modular delivery specialist category, representing engineering firms that compress field construction timelines for gas-to-liquids projects lacking established infrastructure.
| Leading Market Players |
|---|
| Honeywell International |
| Wood plc |
| BP plc |
| Larsen and Toubro Limited |
| Siemens AG |
| KBR Inc. |
| Linde plc |
| Chiyoda Corporation |
| McDermott International |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel prices cascade through reformer catalyst supply chains into three-tier pricing structures across premium, standard, and economy levels. Alumina-supported nickel catalyst procurement costs compress margins for steam methane reformer operators while carbon-capture-integrated autothermal systems command certification premiums from Japanese and South Korean offtakers.
Pricing Analysis
Bundled engineering-procurement-construction contracts dominate large-scale ammonia and refinery projects while unbundled equipment-only sales serve modular distributed installations. Premium-mid-economy pricing differentiation tracks carbon intensity certification tiers and after-sales service bundling rather than hardware specifications alone. Pricing pressure stems from electrolysis capital cost compression narrowing the levelized hydrogen cost gap against unabated reforming. Merchant hydrogen producers exhibit highest price sensitivity due to thin margins on pipeline-delivered volumes, while captive refinery operators prioritize reliability over unit economics.
Supply Chain Analysis
Direct-to-refinery channels handle integrated project demand while specialized EPC contractors serve remote gas-to-liquids sites lacking established infrastructure. Nickel catalyst manufacturing concentrates in Russia and Indonesia, with reformer vessel fabrication anchored in India, South Korea, and Germany. High-temperature alloy tube production draws from Japanese and European metallurgical specialists. Single-source vulnerability in nickel sulfate processing creates supply chain risk for steam methane reformer operators dependent on consistent catalyst replenishment cycles. Distribution runs through industrial gas majors with captive engineering capabilities and regional fabrication specialists focused on modular skid delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon border adjustment mechanism compounds demand for low-carbon hydrogen pathways, repositioning reformer procurement economics toward capture-integrated systems and certification-compliant supply chains.
For Market Incumbents: Anchor technology leadership through backward integration into nickel catalyst manufacturing and solid oxide electrolysis hybrid system development. Defend installed base against electrolysis substitution by embedding carbon capture into autothermal reformer retrofits for Rotterdam and Antwerp refinery clusters. Prioritize control system upgrade pathways that bridge legacy distributed control architectures with digital twin implementations. For New Entrants and Emerging Players: Capture white-space opportunity in modular skid-mounted reformer delivery for remote gas-to-liquids projects across Saudi Arabia's Eastern Province and India's Gujarat industrial corridor. Target distributed hydrogen production at marine fuel bunkering hubs where pipeline infrastructure remains absent. Pursue joint development agreements with Japanese cryogenic engineering specialists for F-Gas-compliant hydrogen liquefaction integration. For Investors and Strategic Acquirers: Asymmetric upside sits with engineering procurement contractors possessing modular fabrication capabilities and carbon capture integration expertise. Long-term viability favors participants with captive catalyst portfolios and established maintenance contractor networks servicing high-temperature alloy systems. Watch nickel supply chain restructuring and EU green hydrogen certification standard finalization as inflection indicators for technology mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Amine and solid sorbent systems enable blue hydrogen export certification for Japanese power sector offtakers. |
| Modular Skid Delivery | Compact reformer designs compress field construction timelines for remote sites lacking pipeline infrastructure. |
| Catalyst Supply Security | Backward integration into nickel processing mitigates raw material vulnerability from Russian and Indonesian concentration. |
| Hybrid System Development | Solid oxide electrolysis coupling with steam methane reforming achieves partial electrification for EU compliance. |
| Digital Twin Implementation | Advanced process control retrofits bridge legacy distributed control systems with modern optimization platforms. |
Research Methodology
Bottom-up hydrogen end-use modeling reconciled against top-down reformer manufacturing capacity tracking forms the analytical core of this study. Primary interviews with plant managers at ammonia synthesis facilities, procurement leads at merchant hydrogen suppliers, EPC contractors, and aftermarket service heads inform demand-side assumptions. Secondary validation draws from EPA emissions filings, EU ETS registry data, Indian CEA grid interconnection records, and customs trade statistics for nickel catalyst and high-temperature alloy imports. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map feedstock cost trajectories, carbon intensity certification thresholds, and technology substitution elasticities across the projection horizon. Segmentation dimensions include reformer type, end-user industry, technology configuration, and regional regulatory framework. CAGRs derive from capacity expansion announcements, policy incentive trajectories, and levelized cost convergence dynamics between reforming and electrolysis pathways. Forecast inputs incorporate natural gas price volatility scenarios and nickel supply disruption risk assessments.
Policy incentive withdrawal, nickel supply chain fragmentation, and electrolysis cost compression beyond modeled trajectories are the dominant revision risks to installed capacity forecasts. Technology substitution rates and carbon border adjustment enforcement timelines carry asymmetric uncertainty. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
US Commercial Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Hydrogen Boilers Market
Boilers
Gas Fired Boilers Market
Boilers
Superheater Market
Boilers
Watertube Boilers Market
Boilers
Europe Combined Heat and Power Market
Boilers
Europe Power Plant Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
North America Commercial Boiler Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Global Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Electric Boiler Market